
 Organic Cereals Market | 2026-2036
Organic Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Cereals Market Outlook
EU Green Deal compliance is realigning the cost-of-entry calculus for organic cereal manufacturers seeking European market access. General Mills leverages its North American supply chain scale to compete across multiple product formats. Nature's Path anchors its positioning through certified organic sourcing and transparent grain provenance. Kellogg Company sustains R&D intensity in reformulation to meet evolving EU pesticide residue thresholds.
Organic cereals are breakfast grain products manufactured from certified organic ingredients, typically containing whole grains with minimal processing and no synthetic pesticides or genetically modified organisms, serving commercial and retail channels requiring verified clean-label nutrition. Oats and granola command the largest volume positions due to their versatility in hot and cold applications, while muesli captures premium margin pools through imported European formulations. Supermarkets dominate distribution channel volume, though online retail is extending fastest as direct-to-consumer subscription models reshape household replenishment patterns.
USDA Organic certification governs American market access, while EU Organic Regulation 2018/848 shapes European product standards, and India's FSSAI enforces import labeling for cross-border trade. These frameworks create divergent compliance burdens that favor manufacturers with multi-jurisdiction certification capabilities. Stakeholders must monitor evolving maximum residue limits and carbon footprint disclosure rules that will determine which suppliers retain shelf placement in regulated channels.
Market Dynamics
EU Organic Regulation 2018/848 compliance costs are compressing manufacturer margins while simultaneously locking out uncertified competitors from European retail channels.
Growth Catalysts
- EU Green Deal Farm to Fork:Mandatory pesticide reduction targets are redirecting conventional grain acreage toward certified organic cultivation across member states.
- German household consumption:Rising breakfast muesli purchases in metropolitan clusters demonstrate sustained willingness to pay organic premiums.
- Whole grain processing:Cold-press milling technology preserves nutrient density and extends shelf stability without synthetic preservatives.
Market Restraints
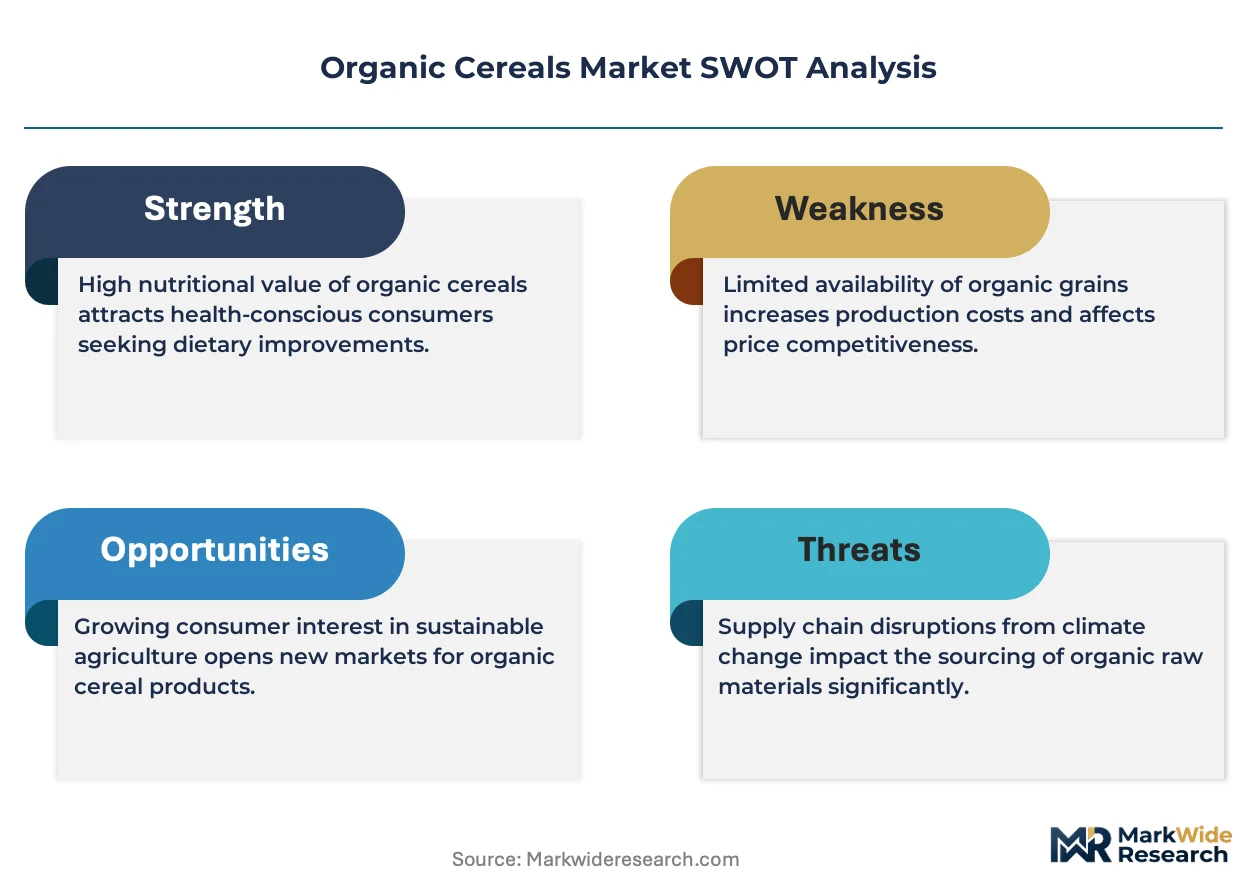
- Organic input cost volatility:Non-GMO seed premiums and natural fertilizer prices fluctuate with weather-driven commodity cycles.
- Certification timeline friction:Three-year land conversion requirements under USDA Organic and EU 2018/848 delay supply expansion.
- Conventional cereal substitution:Private-label standard granola captures price-sensitive households during inflationary periods.
Strategic Opportunities
- French organic muesli gap:Underdeveloped domestic production creates import substitution potential for certified European suppliers.
- Direct-to-consumer subscription:Replenishment automation bypasses supermarket slotting fees and builds recurring revenue.
- Carbon footprint disclosure:Early adoption of CSRD-aligned Scope 3 reporting differentiates shelf positioning ahead of mandated deadlines.
Industry Challenges
- Multi-jurisdiction certification complexity:Simultaneous USDA Organic, EU 2018/848, and FSSAI compliance requires dedicated regulatory staff.
- Legacy ERP integration:Grain provenance tracking systems must interface with existing inventory management without disrupting fulfillment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Cereals Market |
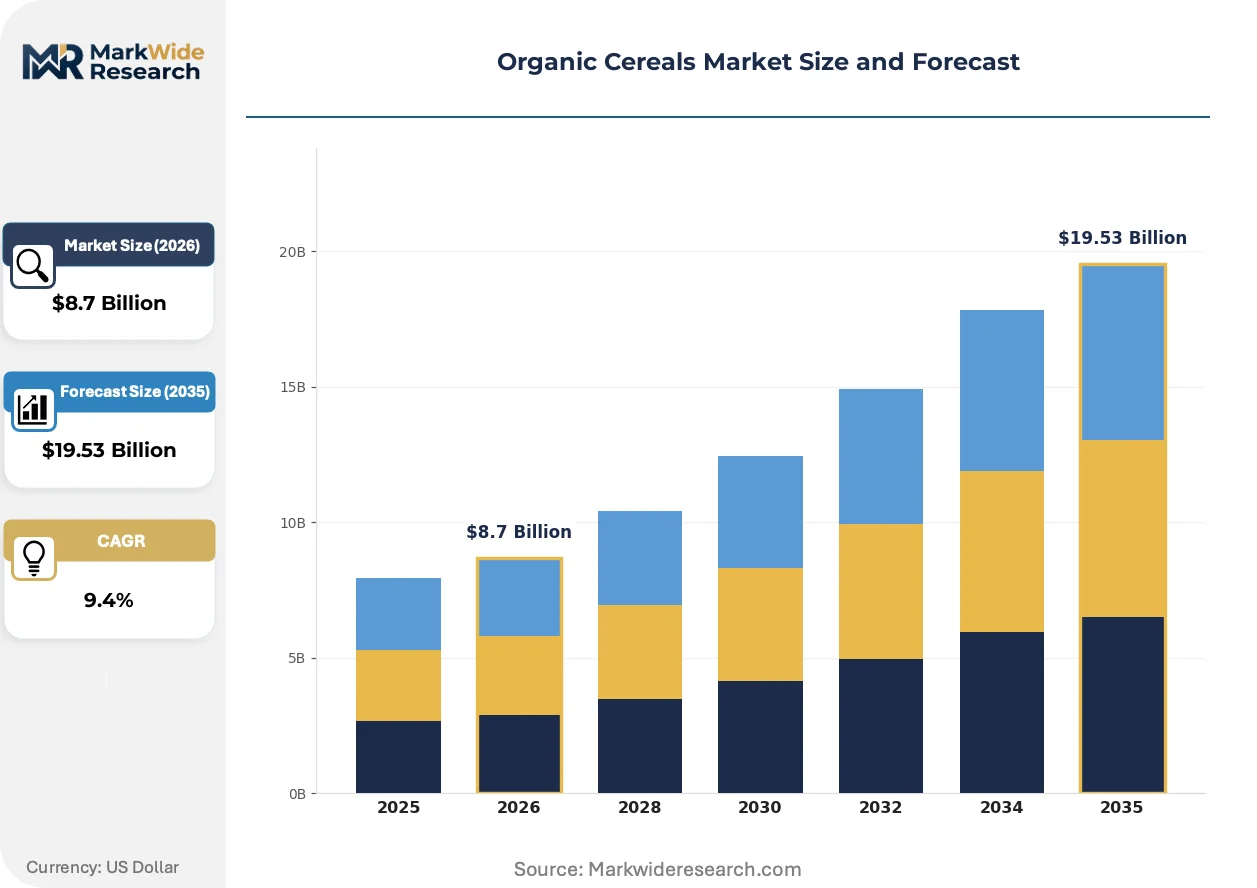
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oats, Corn Flakes, Granola, Muesli End User: Households, Restaurants, Cafes, Schools Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Farmers' Markets Packaging Type: Bags, Boxes, Pouches, Jars |
| Companies Covered | General Mills, Kellogg Company, Nature's Path, Quaker Oats, Bob's Red Mill, Annie's, Cascadian Farm, Hain Celestial, Kroger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Cereals Market Strategic Shifts
Clean-label verification technology and regenerative sourcing claims are restructuring how organic cereals demonstrate value beyond certification logos.
Sprouted grain processing is absorbing conventional heat-treated oats as the preferred base for premium granola formulations. Small-batch manufacturers in Denmark and the Netherlands have adopted enzymatic sprouting to reduce phytic acid content. This shift is absorbing shelf space from legacy toasted products in Scandinavian retail.
EU F-Gas Regulation phase-down is pressuring cold-chain logistics providers serving organic cereal distribution. Refrigerated transport operators must retrofit fleets with lower-global-warming-potential refrigerants by 2030. Breakfast cereal exporters to Germany and France face elevated freight costs as compliance deadlines tighten.
Subscription-based household replenishment is compressing traditional supermarket purchasing cycles for organic breakfast products. Direct-to-consumer platforms in urban UK and German markets now capture recurring orders previously routed through Tesco and Rewe. This behavioral pivot concentrates customer data with brand owners rather than retail intermediaries.
Organic Cereals Market Segmentation
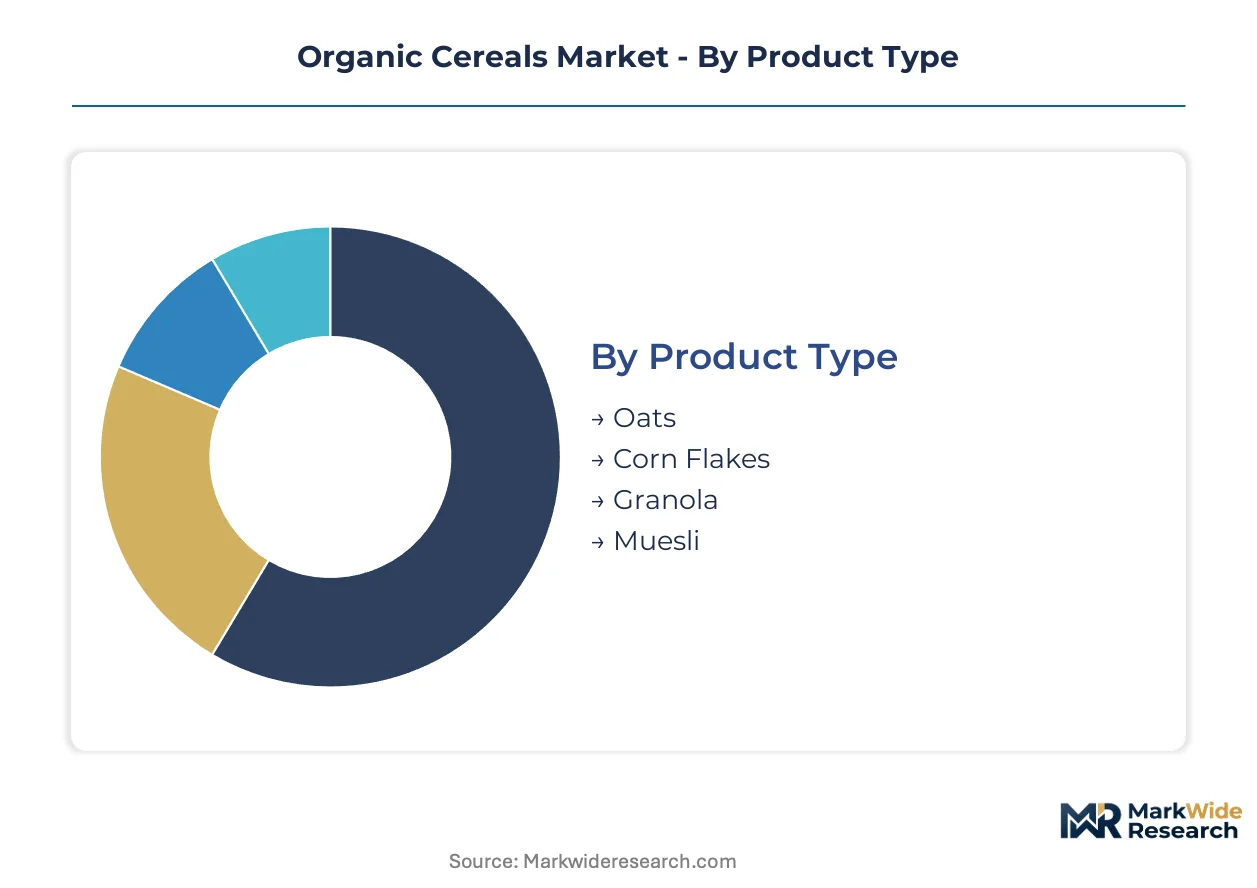
Organic cereals fragment across four structural dimensions that determine capital deployment and margin capture. Product type dictates processing equipment intensity, while distribution channel shapes working capital cycles and customer acquisition costs. End user and packaging specifications further stratify production requirements and shelf positioning economics.
Product Type:
Oat milling and granola production demand the heaviest upfront capital, with roasting lines and cold-press equipment requiring dedicated facility footprints.
- Oats:Rolled and steel-cut varieties serve hot breakfast applications with minimal ingredient layering. German and French households drive volume through muesli base demand, though conventional oat substitution pressures organic premiums during commodity spikes.
- Granola:Baked clusters combine rolled grains with binders and dried fruits, requiring controlled-temperature ovens and coating drums. Cold-press technology adoption in Scandinavian markets preserves nutrient density without synthetic preservatives, supporting premium positioning.
- Corn Flakes:Extrusion cooking and flaking mills demand continuous processing lines with high energy inputs. EU Green Deal energy efficiency standards are reshaping equipment procurement timelines for new capacity.
- Muesli:Unbaked blends of flakes, seeds, and dried fruits minimize processing but require sophisticated ingredient sourcing and mixing precision. French import dependency creates margin capture opportunities for certified European suppliers with domestic production.
Oats and granola together absorb the bulk of installed capacity; muesli is expanding most quickly through premium imported formulations.
End User:
Channel concentration varies sharply by order frequency and certification documentation requirements, with institutional buyers demanding batch-level traceability.
- Households:Supermarket and direct-to-consumer purchases dominate volume, with subscription models in UK and German urban markets compressing replenishment cycles. EU Organic Regulation 2018/848 label recognition drives repeat purchase behavior in metropolitan clusters.
- Restaurants:Foodservice procurement prioritizes bulk formats and consistent supply security, with granola topping applications in breakfast and dessert menus. Cold-chain logistics requirements under EU F-Gas Regulation phase-down are elevating freight cost structures.
- Cafes:Specialty coffee chains specify single-origin grain provenance for menu differentiation, requiring supplier audit capabilities and transparent sourcing documentation.
- Schools:Public procurement frameworks in Germany and France mandate organic certification for breakfast program eligibility, creating dedicated volume pools with rigid compliance specifications.
Households anchor current demand volumes; restaurants are climbing the fastest as foodservice organic penetration deepens.
Distribution Channel:
Slotting fees and inventory carrying costs create divergent margin structures across channel types, with digital native brands bypassing traditional retail economics.
- Supermarkets:Rewe, Tesco, and Carrefour control primary volume placement through category management agreements and promotional calendar coordination. Three-year land conversion timelines under USDA Organic and EU 2018/848 constrain supplier expansion to meet retail growth targets.
- Online Retail:Direct-to-consumer platforms capture recurring revenue with subscription automation, concentrating customer data with brand owners rather than retail intermediaries. Replenishment algorithms optimize inventory turns without supermarket slotting fee burdens.
- Health Food Stores:Independent retailers prioritize SKUs with multiple certification logos, rewarding manufacturers with multi-jurisdiction compliance capabilities.
- Farmers' Markets:Local production claims and minimal packaging resonate with urban consumers seeking shortened supply chains, though scale limitations constrain national brand participation.
Supermarkets retain the steepest volume concentration; online retail is gaining share fastest through subscription model adoption.
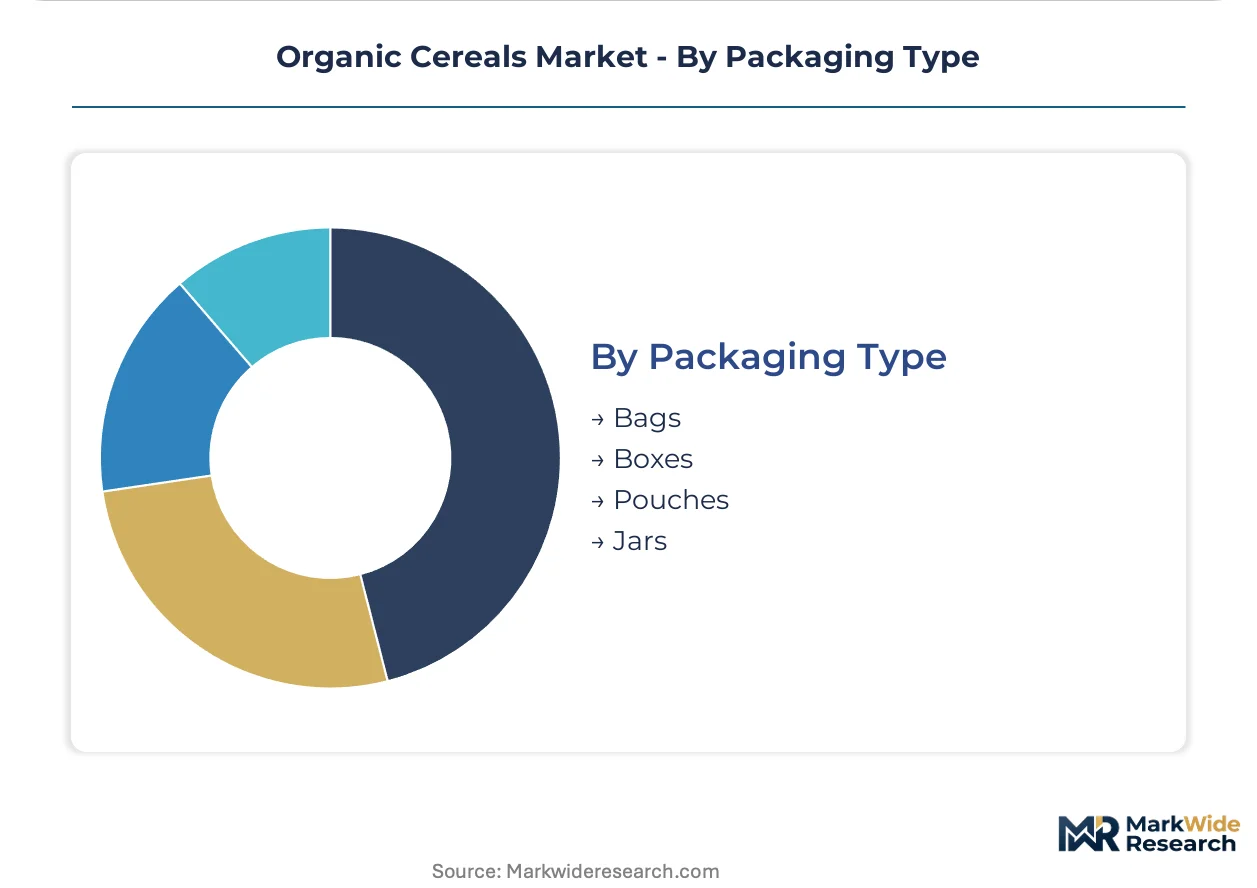
Packaging Type:
Material specifications and shelf stability requirements determine packaging line investment and regulatory compliance burden.
- Bags:Flexible formats minimize material cost and shipping cube, with resealable closures extending shelf life for high-frequency household consumption. India's FSSAI import labeling requirements add compliance complexity for cross-border bagged product shipments.
- Boxes:Structural rigidity protects flake integrity through distribution, with retail-ready secondary packaging reducing shelf-stocking labor. CSRD-aligned carbon footprint disclosure rules are pressuring corrugated sourcing transparency.
- Pouches:Stand-up formats with spouts serve single-serve and on-the-go consumption occasions, requiring form-fill-seal equipment with nitrogen flush capabilities.
- Jars:Glass containers support premium positioning and reuse cycles, though weight and fragility elevate freight costs and breakage risk in direct-to-consumer shipping.
Bags and boxes together command dominant format share; pouches are expanding most quickly through convenience-oriented product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal Farm to Fork incentives concentrate organic cereal investment in designated agricultural transition zones across member states. Certified grain processing clusters are emerging near Rotterdam, Hamburg, and Marseille to exploit preferential zoning and streamlined customs clearance.
Germany
Metropolitan households in Berlin and Munich sustain double-digit organic breakfast category growth through subscription replenishment models. EU Organic Regulation 2018/848 enforcement by the Federal Office for Consumer Protection and Food Safety tightens residue testing protocols for imported grain. The Baden-Württemberg organic milling cluster near Stuttgart is expanding cold-press capacity to serve French and Swiss cross-border demand.
France
Paris and Lyon urban consumers demonstrate sustained willingness to pay premiums for imported Scandinavian muesli formulations. ANSM and DGCCRF coordinate pesticide maximum residue limit enforcement under EU 2018/848 transposition. The Hauts-de-France grain belt near Lille is attracting Dutch and Belgian capital for organic oat conversion to reduce import dependency.
United States
West Coast and Northeast households anchor North American organic granola consumption through direct-to-consumer channels. USDA Organic certification administered by accredited state agencies governs interstate commerce and EU export eligibility. The Willamette Valley in Oregon concentrates sprouted grain processing infrastructure serving Pacific Rim export markets.
United Kingdom
London and Southeast England urban clusters drive fastest online retail adoption for subscription-based organic breakfast replenishment. Post-Brexit UK Organic Regulation maintains equivalence with EU 2018/848 through retained law provisions. The East Anglia grain region is converting conventional acreage to meet retailer organic sourcing commitments under supermarket sustainability frameworks.
India
Maharashtra and Karnataka urban middle-class households are expanding organic breakfast product trials through e-commerce platforms. FSSAI import labeling requirements and BIS organic standards create dual compliance layers for cross-border cereal trade. The Pune-Nashik agricultural corridor is developing domestic organic oat cultivation to substitute Australian and European imports.
Organic Cereals Market Competitive Environment
North American producers anchor one tier; European specialists hold premium positioning through provenance differentiation. The vendor base concentrates around three structural archetypes: multinational packaged food conglomerates with cross-category scale, family-owned organic pure-plays with certified supply chains, and private-label manufacturers serving retailer brands. Strategic moves center on backward integration into organic grain sourcing and direct-to-consumer channel development to bypass retail slotting fees.
Within the scale-driven tier, General Mills and Kellogg Company represent multinational packaged food conglomerates with cross-category manufacturing infrastructure and multi-jurisdiction certification capabilities. Nature's Path occupies a position exemplifying the family-owned organic pure-play archetype, anchoring competitive differentiation through transparent grain provenance and single-category focus. These three companies collectively illustrate how scale advantages and sourcing credibility define positioning in regulated European and North American retail channels.
| Leading Market Players |
|---|
| General Mills |
| Kellogg Company |
| Nature's Path |
| Quaker Oats |
| Bob's Red Mill |
| Annie's |
| Cascadian Farm |
| Hain Celestial |
| Kroger |
| Others |
Value Chain & Pricing Dynamics
Supermarket category managers at Rewe, Tesco, and Carrefour concentrate procurement volumes through long-term supply agreements, anchoring organic cereal pricing in contract-based structures rather than spot markets. This buyer concentration shifts pricing power toward retailers with slotting fee leverage, compressing manufacturer margins while rewarding multi-jurisdiction certification capabilities that secure shelf placement.
Pricing Analysis
Short lead-time premiums for certified organic grain deliveries command price escalation of 15-20% above standard contract rates, while spot inventory liquidation discounts emerge during harvest surplus windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and grain provenance documentation, with EU Organic Regulation 2018/848 compliance serving as the primary price differentiation driver. Pricing pressure stems from private-label conventional granola substitution capturing inflation-sensitive households. Foodservice procurement teams demonstrate highest price sensitivity due to bulk volume negotiations, while direct-to-consumer subscription buyers accept premium positioning for replenishment convenience.
Supply Chain Analysis
Certified organic grain supply rests on Canadian prairie oat cultivation, German Baden-Württemberg milling clusters, and Australian organic acreage expansion programs. Non-GMO seed stock, natural fertilizer inputs, and cold-press processing equipment constitute critical dependencies with limited supplier bases. Single-source vulnerability concentrates in Scandinavian sprouted grain technology providers serving premium formulation demand. Distribution runs through Rotterdam and Hamburg port clusters for European market access, with refrigerated logistics operators facing EU F-Gas Regulation retrofit deadlines that elevate freight cost structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance cost escalation is consolidating organic cereal manufacturing, forcing sub-scale operators without multi-jurisdiction certification capabilities toward exit or acquisition.
For Market Incumbents: Lock in backward integration into organic grain sourcing through long-term land conversion partnerships in Canadian prairies and German agricultural transition zones. Secure EU 2018/848 certification renewal ahead of residue testing protocol tightening by the Federal Office for Consumer Protection and Food Safety. Cold-chain logistics cost inflation under F-Gas Regulation phase-down threatens foodservice margin pools; direct-to-consumer channel development bypasses supermarket slotting fee extraction while capturing recurring revenue automation. For New Entrants and Emerging Players: The price-point gap between imported Scandinavian muesli premiums and domestic French production creates white-space capture potential for certified European suppliers with Hauts-de-France oat conversion capacity. Target underdeveloped French organic muesli domestic production through cold-press milling technology deployment. Subscription-based replenishment algorithms in UK and German urban markets offer the most penetrable go-to-market angle, concentrating customer data with brand owners rather than retail intermediaries. For Investors and Strategic Acquirers: The window for entry favors family-owned organic pure-plays with transparent grain provenance and established EU 2018/848 certification infrastructure. Long-term viability hinges on 5-10 year organic land conversion pipeline security and carbon footprint disclosure capability ahead of CSRD-mandated deadlines. Watch for Federal Office for Consumer Protection and Food Safety residue testing protocol enforcement intensity as inflection indicator for import-dependent supplier viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Grain Sourcing | Long-term land conversion partnerships in Canadian prairies and German transition zones secure supply pipeline. |
| Direct-to-Consumer Subscription Launch | Replenishment automation in UK and German urban markets bypasses supermarket slotting fee structures. |
| Multi-Jurisdiction Certification Investment | Simultaneous USDA Organic, EU 2018/848, and FSSAI compliance unlocks cross-border retail channel access. |
| Cold-Press Milling Capacity Expansion | Baden-Württemberg cluster growth serves French and Swiss cross-border premium muesli demand. |
| Carbon Footprint Disclosure Program | Early CSRD-aligned Scope 3 reporting differentiates shelf positioning ahead of regulatory mandates. |
Study Parameters
Independent corroboration across supply chain directors at organic grain processors, category buyers at Rewe and Tesco, regulatory affairs leads at certification bodies, and cold-chain logistics operators underwrites the qualitative findings. Primary interviews with plant managers at Baden-Württemberg milling clusters, procurement leads at granola manufacturers, and distribution channel partners at Rotterdam port facilities combined with secondary validation from EU Organic Regulation 2018/848 transposition documents, USDA Organic certification databases, and FSSAI import labeling guidelines. Bottom-up volume modeling and top-down value triangulation anchored the market sizing framework.
Rate-of-change decomposition across the analysis window isolated volume growth drivers from price elasticity effects in subscription versus supermarket channels. Segmentation dimensions modeled include product type, end user, distribution channel, and packaging format, with organic certification tier and grain provenance documentation serving as industry-specific stratifiers. CAGRs were derived from rolling average growth rate convergence across the projection horizon. Forecast inputs incorporated EU Green Deal Farm to Fork pesticide reduction target implementation timelines and F-Gas Regulation logistics cost pass-through assumptions.
Underlying measurement precision varies by segment; direct-to-consumer subscription volume carries tighter precision than farmers' market local production claims. Forecasts reflect documented assumptions regarding land conversion timeline adherence and certification audit pass rates. Organic input cost volatility, regulatory enforcement intensity variation, and conventional cereal substitution elasticity constitute primary revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
North America Maize Market
Grains
Organic Rice Flour Market
Grains
Global Rice Market
Grains
North America Oats Market
Grains
United States Maize Market
Grains
Ghana Grain Market
Grains
Gluten Feed Market
Grains
Soybean Market
Grains
Durum Wheat Flour Market
Grains
Black Gram Market
Grains
Corn Silage Market
Grains
Rye Market
Grains
Whole-Wheat Flour Market
Grains
North America Wheat Protein Market
Grains
Uganda Grains Market
Grains
Soy Grits Market