
 Global Grain and Seed Cleaning Equipment Market | 2026-2036
Global Grain and Seed Cleaning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Grain and Seed Cleaning Equipment Market Analysis
Seed certification grade specifications are unwinding legacy equipment replacement cycles across commercial seed operations. Bühler AG leverages its optical sorting R&D pipeline to anchor premium positioning in European seed houses. AGCO Corporation sustains broad geographic coverage through its dealer network serving grain handling facilities. Cimbria specializes in gravity table engineering for high-value vegetable seed producers.
Grain and seed cleaning equipment comprises mechanical and optical systems designed to remove foreign matter, damaged kernels, and varietal impurities based on physical properties such as density, size, shape, and color reflectance. Air screen cleaners handle bulk commodity throughput using integrated aspiration and sieving stages, while optical sorters employ near-infrared cameras and ejectors for defect removal at line speeds exceeding ten tons per hour. Mechanical cleaning equipment occupies the largest installed base due to lower capital requirements and simpler maintenance protocols. Optical sorting is expanding fastest among seed producers seeking varietal purity rates above 99.9% for certified multiplication programs.
The EU's REACH framework and F-Gas Regulation constrain solvent-based seed treatment systems and refrigerant choices in cooling applications, redirecting capital toward aqueous treatment and ambient optical technologies. The USDA's Federal Seed Act and state-level certification standards in Iowa and California mandate minimum germination rates and varietal purity, creating compliance-driven demand for precision cleaning infrastructure. Brazil's MAPA seed certification requirements and China's GB standards for grain processing equipment add parallel compliance layers. Stakeholders must weigh capital allocation between mechanical reliability and optical precision as regulatory thresholds tighten and seed trait complexity multiplies.
Market Dynamics
Seed certification thresholds above 99.9% varietal purity are compressing equipment replacement cycles across commercial multiplication programs, forcing capital allocation toward optical precision systems and away from legacy mechanical infrastructure.
Growth Catalysts
- Brazil MAPA Certification:Soybean seed multiplication programs mandate third-party inspection standards that disqualify gravity-table-only operations, driving systematic upgrades to combined optical-mechanical lines.
- EU F-Gas Regulation:Refrigerant phase-down schedules in cooling applications redirect investment toward ambient-temperature optical sorting platforms that eliminate compressor-dependent conditioning stages.
- Near-Infrared Spectroscopy:Real-time chemical composition detection enables simultaneous protein, moisture, and defect removal, collapsing multiple processing stages into single-pass configurations.
Market Restraints
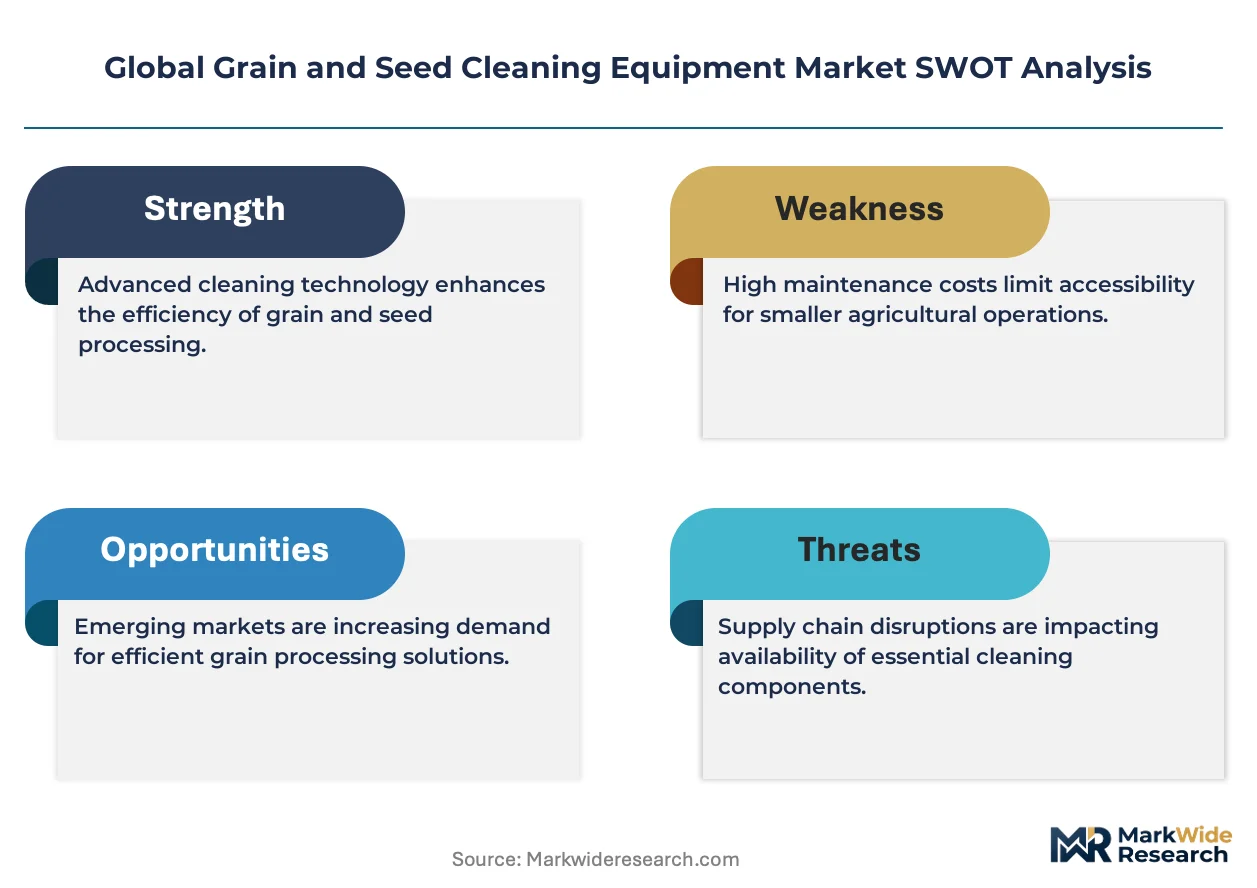
- Capital Intensity:Optical sorter installations require three to four times the upfront expenditure of mechanical air-screen systems, freezing out smaller seed cooperatives and independent grain elevators.
- Component Supply Concentration:High-resolution CMOS sensors and precision ejector valves concentrate among East Asian semiconductor fabricators, exposing equipment manufacturers to lead-time volatility.
- Technical Limitation:Current optical systems struggle with size-matched contaminants sharing spectral signatures with target seeds, leaving density-based separation indispensable for certain varietal classes.
Strategic Opportunities
- India Seed Sector Formalization:Hybrid rice and vegetable seed expansion under the national seed mission creates first-mover positioning for integrated cleaning-treatment-packaging lines.
- Convergence of AI Sorting with Blockchain Traceability:Real-time purity verification tied to immutable batch records commands premium positioning in identity-preserved grain supply chains.
- Outcome-Based Service Contracts:Equipment-as-a-service models shift revenue from capital sales to throughput guarantees, aligning vendor incentives with operational uptime and certification pass rates.
Industry Challenges
- Multidisciplinary Talent Scarcity:Integration of machine vision, pneumatics, and seed biology requires hybrid engineering profiles that agricultural equipment manufacturers struggle to recruit.
- Legacy System Interoperability:Brownfield grain elevators operate decades-old mechanical infrastructure with incompatible control architectures, complicating phased optical upgrades.
- Certification Timeline Compression:Accelerated seed multiplication schedules leave minimal windows for equipment commissioning and regulatory validation before planting deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Grain and Seed Cleaning Equipment Market |
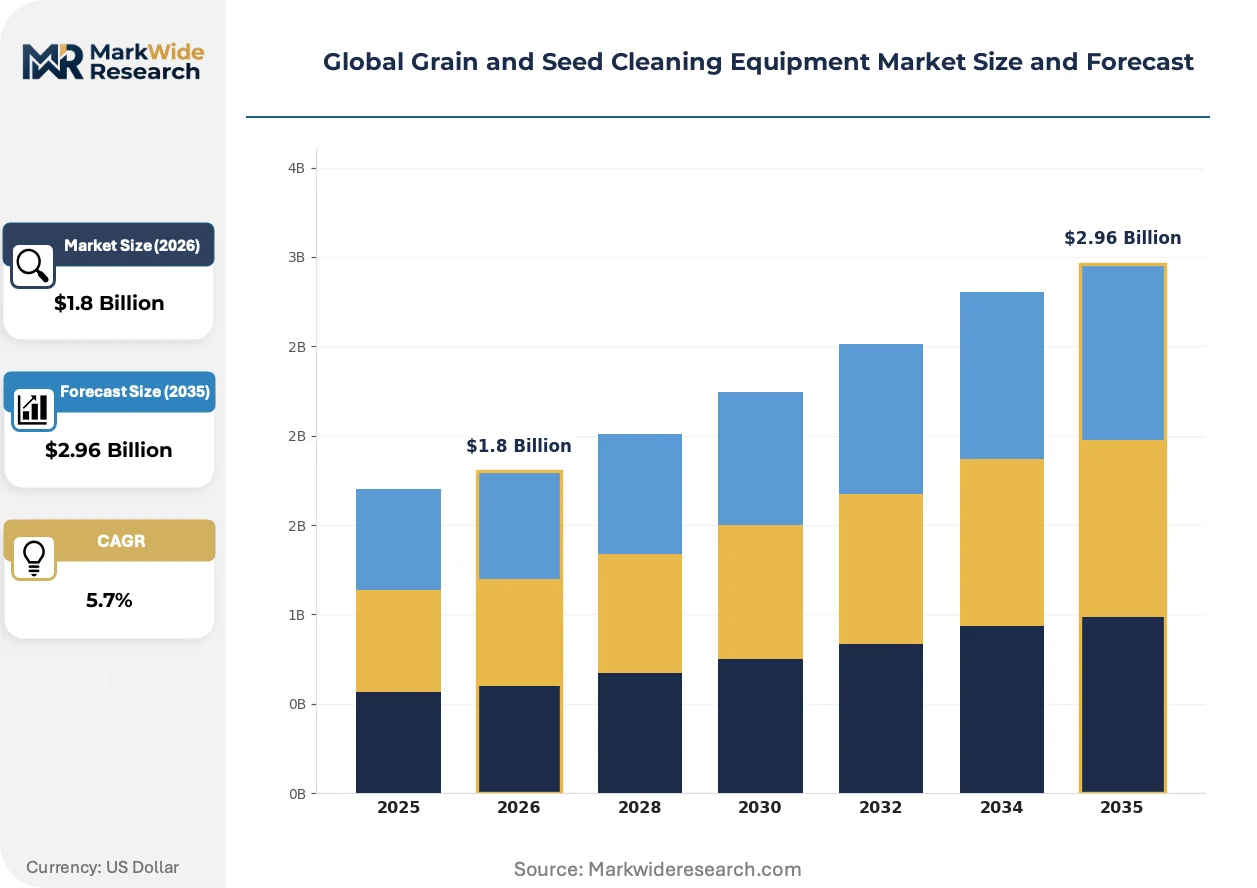
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Air Screen Cleaners, Gravity Tables, Seed Treaters, Aspirators Technology: Mechanical Cleaning, Electrostatic Separation, Optical Sorting, Chemical Treatment End User: Agricultural Cooperatives, Seed Producers, Grain Handling Facilities, Organic Farmers Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | Bühler AG, AGCO Corporation, Cimbria, PETKUS Technologie GmbH, Westrup A/S, Satake Corporation, Akyurek Technology, AGI, A.T. Ferrell Company Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Grain and Seed Cleaning Equipment Market Emerging Trajectories
Digital sensing architectures are supplanting mechanical density separation as the primary purity enforcement layer, while regulatory chemical restrictions and buyer consolidation reshape equipment specification priorities.
Hyperspectral imaging is decomposing the traditional separation workflow by capturing hundreds of wavelength bands beyond visible spectrum, enabling chemical-specific discrimination that density tables cannot achieve. Large-scale corn and soybean seed houses in Iowa and Illinois are retrofitting existing lines with modular hyperspectral heads to meet Federal Seed Act documentation requirements. This capability compression is collapsing the distinction between commodity cleaning and laboratory-grade varietal verification.
REACH compliance deadlines for solvent-based seed treatments are forcing aqueous formulation transitions that alter residue detection thresholds and cleaning validation protocols. Equipment manufacturers must redesign aspiration stages to handle higher-moisture seed surfaces without clogging or kernel damage. European seed processing facilities face the tightest compliance windows, with Germany and France leading capital deployment toward closed-loop water-recovery systems.
Certification-driven procurement now dominates equipment specification in commercial seed operations, with buyers prioritizing documented traceability over throughput metrics. Third-party audit requirements from certification bodies are displacing informal vendor relationships with formal performance guarantees and validation documentation packages. This preference shift concentrates demand among equipment suppliers with established regulatory filing support capabilities, particularly visible in California's specialty vegetable seed corridor.
Global Grain and Seed Cleaning Equipment Market Segmentation
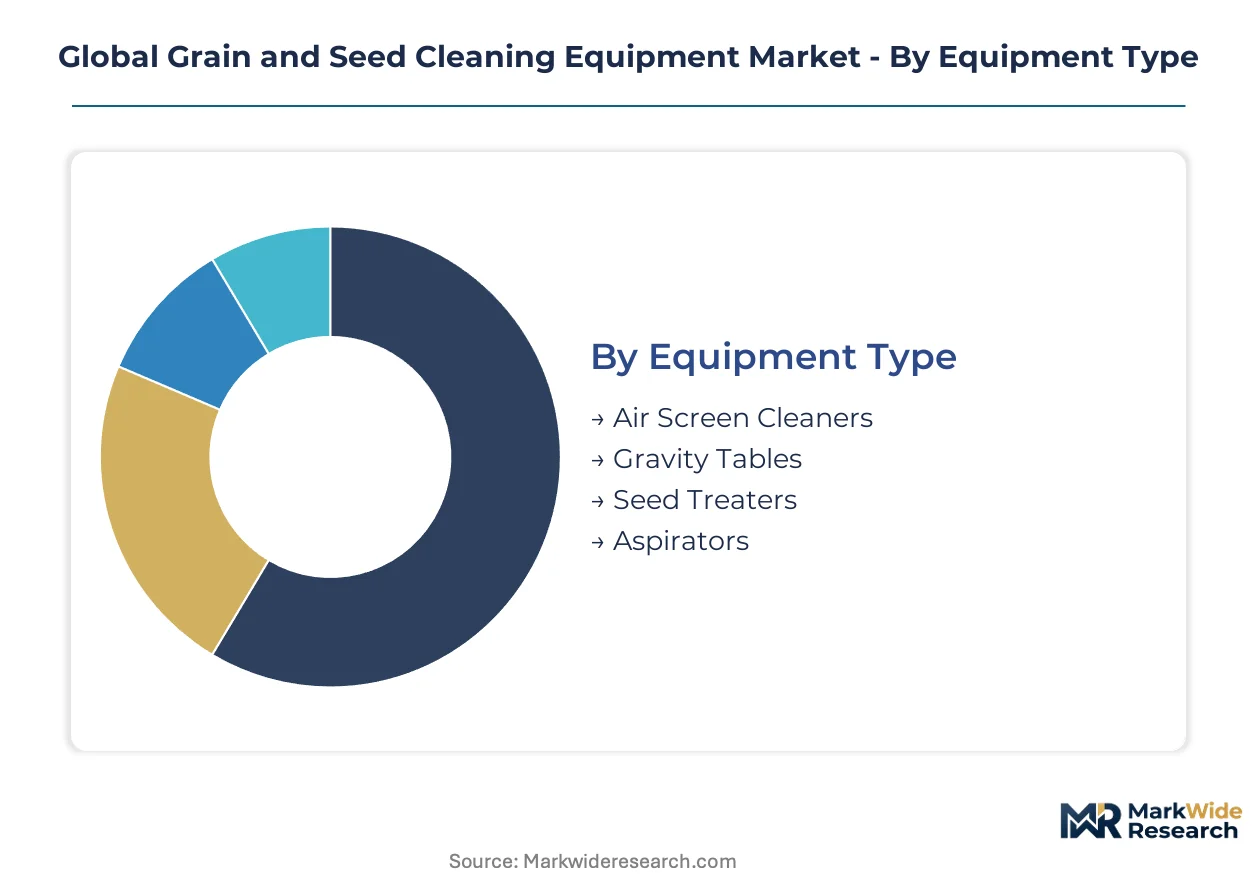
Segmentation in grain and seed cleaning equipment reveals divergent capital allocation patterns across mechanical legacy systems and precision optical platforms. Equipment buyers prioritize either throughput volume or certification-grade purity thresholds depending on their position in the seed multiplication chain.
Equipment Type:
Optical sorters and hyperspectral units exert the strongest substitution pressure on legacy gravity-based infrastructure as certification standards tighten.
- Air Screen Cleaners:Integrated aspiration and sieving stages handle bulk commodity throughput at line speeds exceeding ten tons per hour. Grain handling facilities in Brazil and the US Midwest deploy these systems for soybean and corn intake where varietal purity requirements remain below certified seed thresholds.
- Gravity Tables:Density-based separation using tilted decks and air fluidization remains indispensable for size-matched contaminants that optical systems cannot spectrally discriminate. Vegetable seed producers in California's Imperial Valley and the Netherlands retain gravity tables for high-value brassica and lettuce varieties where kernel damage from pneumatic ejection poses unacceptable germination risk.
- Seed Treaters:Aqueous formulation equipment replaces solvent-based systems under REACH and F-Gas Regulation deadlines in European seed houses.
- Aspirators:Standalone aspiration modules handle pre-cleaning stages before precision finishing in integrated optical-mechanical lines.
Air screen cleaners retain volume leadership; optical sorting platforms hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive precision systems from maintenance-favorable mechanical alternatives across seed producer budgets.
- Mechanical Cleaning:Air-screen and gravity-based systems dominate installed base economics with lower capital requirements and simpler maintenance protocols. Agricultural cooperatives in India's Punjab and Haryana states favor mechanical infrastructure for wheat and rice processing where certification premiums do not justify optical investment.
- Optical Sorting:Near-infrared cameras and precision ejectors achieve varietal purity rates above 99.9% demanded by Federal Seed Act documentation and Brazil MAPA certification. Iowa and Illinois corn seed houses retrofit existing lines with modular hyperspectral heads to collapse multiple processing stages into single-pass configurations.
- Electrostatic Separation:Niche deployment for weed seed and insect fragment removal in organic grain channels.
- Chemical Treatment:Declining share under aqueous formulation mandates from EU and US EPA regulatory pressure.
Mechanical cleaning commands the largest installed base; optical sorting climbs fastest among certified multiplication programs.
End User:
Customer type determines specification priority between throughput metrics and documented traceability for third-party audit compliance.
- Seed Producers:Commercial multiplication programs mandate combined optical-mechanical lines to meet certification body inspection standards. Third-party audit requirements from AOSCA and OECD seed schemes displace informal vendor relationships with formal performance guarantees.
- Grain Handling Facilities:Brownfield elevators operate decades-old mechanical infrastructure with incompatible control architectures complicating phased optical upgrades. US Gulf Coast export terminals prioritize throughput over purity documentation for commodity grain streams.
- Agricultural Cooperatives:Capital constraints freeze investment at mechanical air-screen stages despite rising certification premiums in hybrid seed markets.
- Organic Farmers:Niche demand for electrostatic and density-based separation avoiding chemical treatment residues.
Seed producers drive specification innovation; grain handling facilities anchor replacement part revenues.
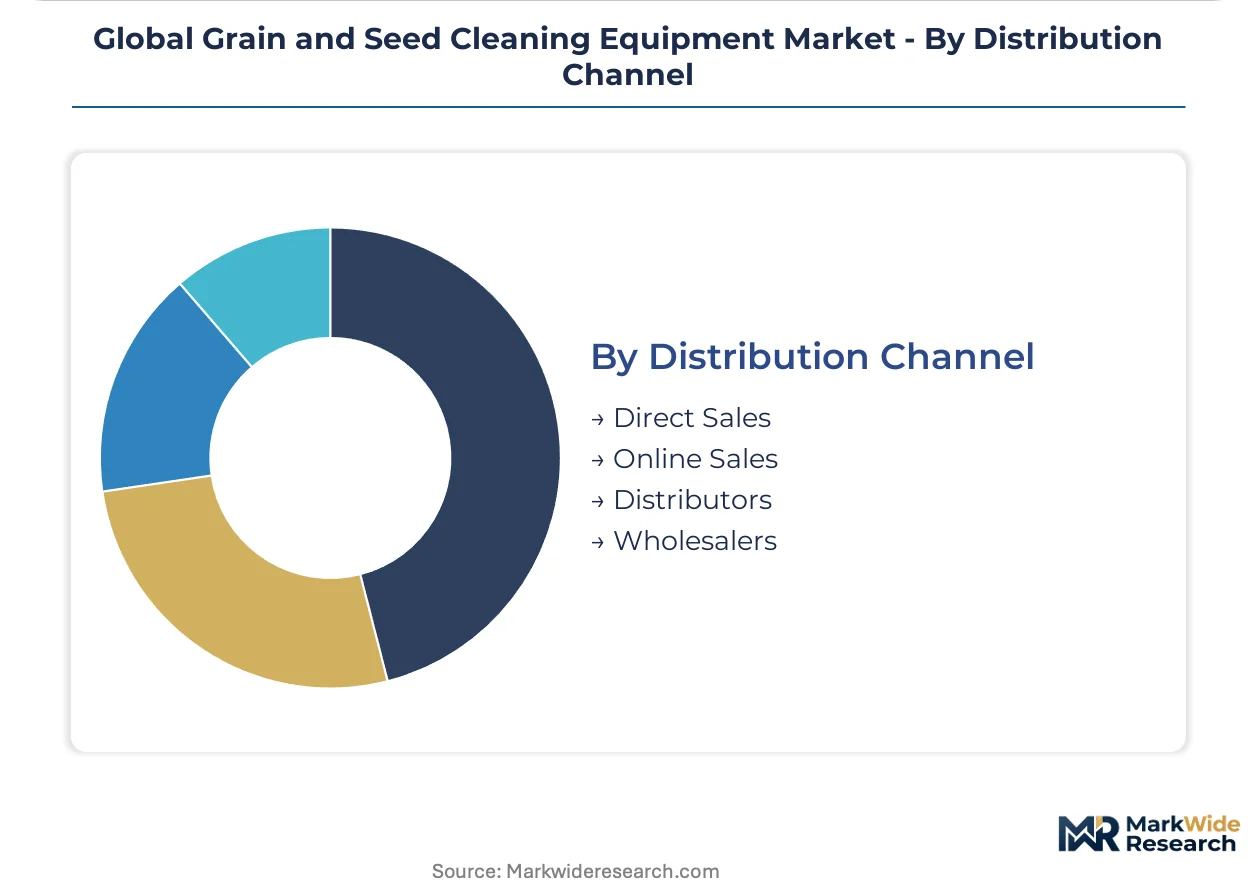
Distribution Channel:
Supply concentration among precision component fabricators shapes channel strategy for optical system vendors versus mechanical equipment suppliers.
- Direct Sales:Equipment manufacturers deploy application engineering teams for integrated line design and regulatory validation documentation. Bühler AG and Cimbria maintain direct relationships with European seed houses for closed-loop water-recovery system commissioning.
- Distributors:Dealer networks sustain geographic coverage for mechanical spare parts and retrofit services. AGCO Corporation leverages agricultural equipment dealer infrastructure across Brazil's Mato Grosso and Rio Grande do Sul soybean corridors.
- Online Sales:Limited to consumables and standard replacement components rather than capital equipment.
- Wholesalers:Bulk procurement channels for commodity air-screen cleaner sieves and aspiration ducting in developing markets.
Direct sales capture premium optical system revenues; distributors defend mechanical aftermarket share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in grain and seed cleaning equipment tilt toward net-import status in emerging seed formalization markets while established manufacturing bases in Germany and Switzerland supply precision optical systems worldwide. Brazil and India absorb the highest inbound equipment volumes as domestic seed certification programs accelerate. North American and European facilities predominantly refresh existing installed bases rather than expand greenfield capacity.
United States
Iowa and Illinois corn seed houses drive retrofit demand for modular hyperspectral sorting heads to meet Federal Seed Act documentation requirements. The USDA enforces minimum germination rates and varietal purity thresholds that disqualify legacy gravity-table-only operations from certified multiplication programs. Processing clusters in the Midwest Corn Belt concentrate replacement investment in combined optical-mechanical lines during narrow pre-planting commissioning windows.
Brazil
MAPA seed certification mandates for soybean multiplication programs force systematic upgrades from mechanical air-screen systems to integrated optical sorting platforms. The national agricultural ministry's third-party inspection standards compress equipment replacement cycles across Mato Grosso and Rio Grande do Sul production corridors. Dealer networks in the Cerrado and Pampas regions prioritize throughput guarantees and validation documentation packages over capital cost minimization.
Germany
REACH compliance deadlines and F-Gas Regulation refrigerant phase-downs redirect capital toward ambient-temperature optical sorting and closed-loop water-recovery systems. ECHA chemical restrictions constrain solvent-based seed treatment equipment, favoring aqueous formulation transitions that alter aspiration stage design. Equipment engineering concentrates in Baden-Württemberg and Bavaria, supplying European seed houses with regulatory filing support capabilities.
India
The national seed mission's hybrid rice and vegetable seed expansion creates first-mover positioning for integrated cleaning-treatment-packaging lines in Punjab and Haryana. BIS equipment standards and state-level seed certification formalization displace informal mechanical processing at agricultural cooperatives. Processing infrastructure clusters in Gujarat and Maharashtra attract direct sales engagement from optical system vendors seeking volume scale in formalizing markets.
China
GB standards for grain processing equipment and domestic seed sector modernization drive import substitution in optical sorter manufacturing. MIIT industrial policy supports precision agriculture equipment localization, compressing market access for foreign component suppliers. Yangtze River Delta fabrication clusters concentrate CMOS sensor integration and precision ejector valve assembly for regional equipment supply.
Global Grain and Seed Cleaning Equipment Market Vendor Landscape
Concentration sits with diversified agricultural machinery conglomerates and precision sorting specialists rather than fragmented mechanical equipment fabricators. Three archetypes dominate: integrated optical-mechanical line designers, gravity table engineering specialists, and broad-line agricultural equipment manufacturers with dealer-network distribution. Competitive maneuvering centers on regulatory validation documentation capabilities and outcome-based service contract structuring rather than capital equipment price competition alone.
Among European precision equipment specialists, Bühler AG and Cimbria exemplify the integrated line designer archetype, while AGCO Corporation represents the diversified agricultural machinery conglomerate with extensive dealer infrastructure. PETKUS Technologie GmbH occupies a position within the German engineering specialist tier. These named entities anchor industry-level patterns of geographic coverage strategy, direct sales versus distribution channel preference, and certification-grade versus commodity-throughput market segmentation without claims about specific product portfolios or strategic initiatives.
| Leading Market Players |
|---|
| Bühler AG |
| AGCO Corporation |
| Cimbria |
| PETKUS Technologie GmbH |
| Westrup A/S |
| Satake Corporation |
| Akyurek Technology |
| AGI |
| A.T. Ferrell Company Inc |
| Others |
Supply Flow & Price Mechanics
Near-infrared camera modules replacing legacy mechanical density sensors simultaneously concentrate component sourcing in East Asian fabrication hubs and compress pricing economics for mid-tier optical-mechanical hybrid systems. This substitution dynamic redirects margin pools toward precision ejector valve suppliers while forcing European and North American integrators to absorb semiconductor lead-time volatility through inventory pre-positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the grain and seed cleaning equipment market. Price differentiation rests on certification-grade documentation packages and aftermarket service bundling rather than base hardware specifications alone. Cost compression in the standard tier is intensifying because Brazilian and Indian seed cooperatives demand performance guarantees without optical precision premiums. Agricultural cooperatives in India's Punjab and Haryana states exhibit the highest price sensitivity, while commercial seed houses in Iowa and Germany prioritize documented traceability over capital cost minimization.
Supply Chain Analysis
Inventory pre-positioning for CMOS sensors and precision ejector valves now extends to six-month coverage given lead-time volatility from Taiwan, South Korea, and Japan. Component sourcing draws from East Asian semiconductor fabricators for imaging arrays and German engineering specialists for pneumatic control systems. Single-source vulnerability concentrates in high-resolution sensor supply, exposing equipment manufacturers to tariff exposure and logistics chokepoint risk. Distribution runs through direct sales channels for integrated optical-mechanical lines and dealer networks for mechanical spare parts and retrofit services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grain and seed cleaning equipment market functions as a defensive-moat industry where regulatory entrenchment creates durable competitive positioning. Certification body validation documentation and third-party audit relationships generate switching costs that freeze out unqualified suppliers.
For Market Incumbents: Shield market position by deepening backward integration into precision ejector valve manufacturing to offset East Asian component concentration risk. Anchor certification investment in Brazil MAPA and USDA Federal Seed Act documentation capabilities to exploit emerging entrant gaps in regulatory filing support. Prioritize outcome-based service contract structuring that ties revenue to throughput guarantees and certification pass rates, displacing capital-sales-only competitors.
For New Entrants and Emerging Players: Anchor in India's hybrid rice and vegetable seed formalization corridor where BIS standards displacement creates first-mover positioning for integrated cleaning-treatment-packaging lines. Target agricultural cooperatives in Punjab and Haryana with mechanical-to-optical upgrade pathways that bypass full capital replacement. Pursue equipment-as-a-service go-to-market models that align vendor incentives with operational uptime rather than competing on upfront capital cost.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with precision optical sorting specialists that have achieved regulatory validation entrenchment in EU REACH and F-Gas compliance frameworks. Long-term viability over a multi-year horizon favors equipment manufacturers with documented traceability capabilities and blockchain-ready batch verification infrastructure. Watch for inflection when seed certification thresholds tighten beyond 99.95% varietal purity, forcing systematic gravity-table displacement and accelerating optical sorter replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captive supply of ejector valves insulates margin from East Asian semiconductor lead-time volatility. |
| Certification Documentation Investment | USDA Federal Seed Act and Brazil MAPA filing capabilities freeze out unqualified competitors. |
| Outcome-Based Service Contracts | Throughput guarantee revenue models align vendor incentives with seed house certification pass rates. |
| Hyperspectral Imaging Module Launch | Real-time chemical composition detection collapses multiple processing stages into single-pass configurations. |
| Closed-Loop Water-Recovery Systems | EU REACH aqueous formulation mandates require redesigned aspiration stages for higher-moisture seed surfaces. |
Methodological Framework
A spread of perspectives from seed processing plant managers, agricultural cooperative procurement leads, optical system application engineers, and aftermarket service heads converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation from USDA Federal Seed Act filings, Brazil MAPA certification databases, EU ECHA REACH compliance records, and customs trade data for equipment import flows. Bottom-up equipment shipment tracking and top-down seed sector investment flow analysis triangulated on market sizing across the projection horizon.
Segmentation dimensions modeled include equipment type, cleaning technology, end-user archetype, and distribution channel, with additional granularity on certification-grade versus commodity-throughput specification tiers. CAGRs derived from regression analysis of historical replacement cycle compression and forward projection of regulatory threshold tightening. Forecast inputs incorporated seed multiplication program expansion rates in Brazil and India, plus EU F-Gas Regulation refrigerant phase-down schedules affecting cooling-dependent mechanical systems.
Material uncertainties — regulatory timeline acceleration, semiconductor supply disruption, seed trait complexity multiplication — sit outside the modeled envelope. Forecasts reflect assumptions about certification standard stability and component supply normalization. Revision becomes warranted when seed certification varietal purity thresholds cross 99.95% or when CMOS sensor lead times extend beyond pre-positioned inventory coverage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Poultry Processing Equipment Market
Agricultural Processing Equipment
Sugarcane Harvesters Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Meat Cutting Machine Market
Agricultural Processing Equipment
Rice Processing Machine Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Color Sorter Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Feed Screw Barrel Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Tobacco Drying Machines Market
Agricultural Processing Equipment
Cashew Processing Machine Market