
 Saudi Arabia Fertilizer Market | 2026-2036
Saudi Arabia Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Fertilizer Market Analytics
Saudi Vision 2030 sustainability targets is broadening the addressable market for precision agriculture inputs. SABIC Agri-Nutrients Company leverages its integrated methane-to-urea infrastructure to sustain cost leadership across the Gulf. Ma'aden Phosphate Company anchors domestic phosphoric acid supply through its Waad Al-Shamal complex. Qatar Fertiliser Company (QAFCO) competes via cross-border granular urea shipments into Dammam and Jeddah ports.
Fertilizers are chemically formulated soil amendments supplying primary macronutrients—nitrogen, phosphorus, and potassium—in specified N-P-K ratios to optimize plant metabolic function and crop yield. Urea dominates Saudi product type volumes due to its high nitrogen density and compatibility with local wheat and date palm cultivation, while granular form leads over liquid alternatives because of storage stability in arid climates and compatibility with mechanized broadcast spreading. Potassium nitrate occupies a premium niche in horticulture and greenhouse operations where chloride sensitivity limits standard potassium chloride application.
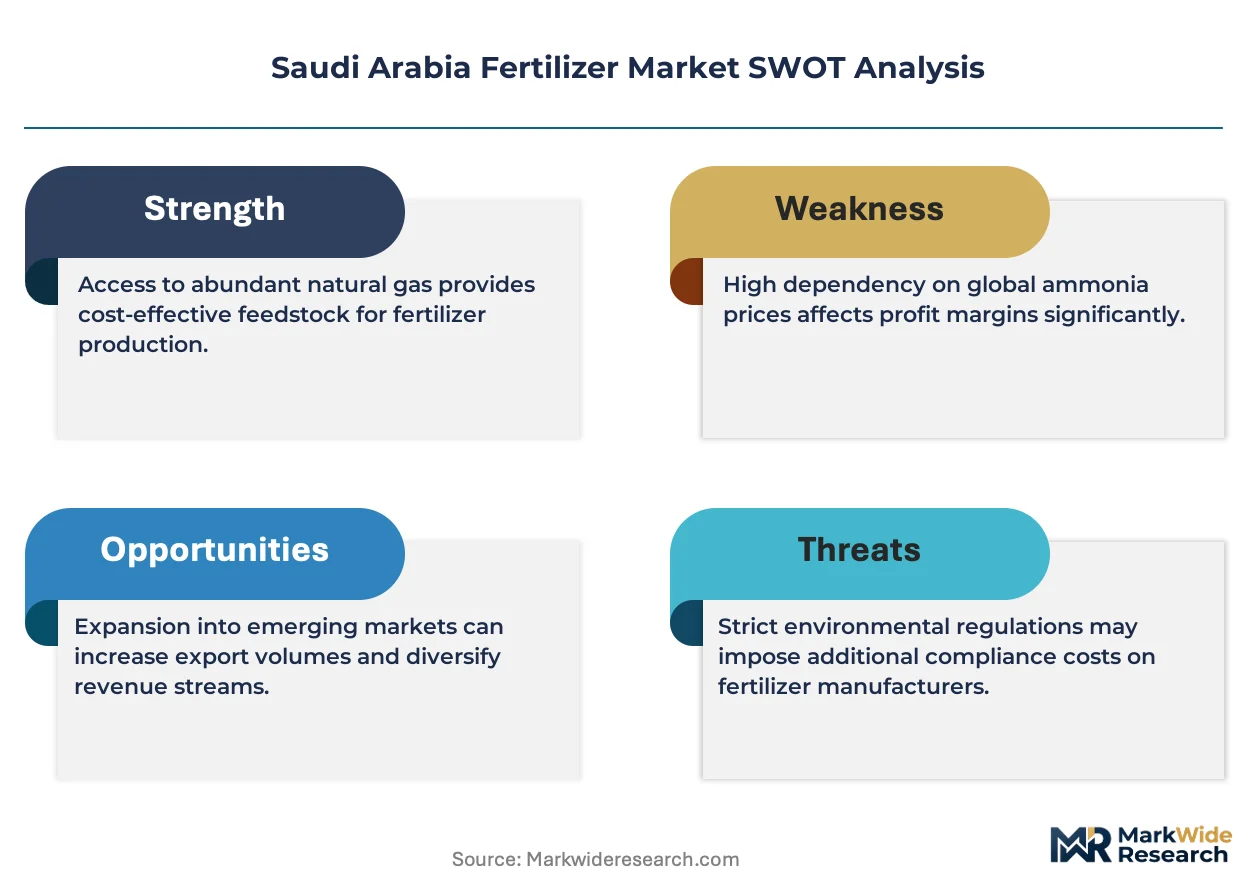
SFDA, MOHAP, and SASO collectively govern fertilizer registration, labeling, and contaminant limits under converging national food security and environmental frameworks. Import permits now require third-party laboratory certification for heavy metal content, directly elevating compliance costs for non-integrated traders. Stakeholders must monitor feedstock pricing volatility at Jubail industrial clusters and assess backward integration into ammonia production as a margin defense mechanism.
Market Dynamics
Feedstock integration around Jubail Industrial City is compressing procurement cycles for nitrogen-based fertilizers while SFDA residue thresholds force reformulation investments across the supply base.
Growth Catalysts
- Saudi Vision 2030 sustainability mandates:Precision agriculture targets expand demand for controlled-release and water-efficient fertilizer formulations in wheat and date palm cultivation.
- Petrochemical feedstock concentration:Methane-to-ammonia infrastructure at Jubail Industrial City anchors cost-competitive urea production for domestic and regional offtake.
- Qassim wheat belt expansion:Mechanized farming in central Saudi Arabia absorbs rising volumes of granular nitrogen products optimized for broadcast application.
Market Restraints
- Natural gas price volatility:Ammonia synthesis depends on methane feedstock pricing at Jubail clusters, compressing margins during upstream energy spikes.
- Import documentation burdens:SFDA and SASO heavy metal certification requirements elevate compliance costs for non-integrated traders sourcing from external suppliers.
- Water scarcity constraints:Fertigation system deployment faces technical limitations in regions lacking treated wastewater infrastructure for nutrient dissolution.
Strategic Opportunities
- Eastern Province demand concentration:Industrial city clusters around Dammam and Jubail offer captive offtake for ammonia-integrated producers with logistics advantages.
- Controlled-release technology convergence:Polymer-coated urea combined with soil moisture sensors enables premium pricing in greenhouse and horticulture segments.
- SFDA residue threshold tightening:Stricter contaminant limits create competitive separation for domestic producers with integrated laboratory certification capabilities.
Industry Challenges
- Specialized agronomist scarcity:Precision fertilizer application requires field technicians trained in soil chemistry and variable-rate spreading calibration.
- Integrated compliance timelines:Dual SFDA and SASO registration processes extend product launch cycles for reformulated blends targeting residue thresholds.
- Legacy storage infrastructure:Existing bulk handling facilities in arid interior regions require humidity control upgrades to preserve granular product integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Fertilizer Market |
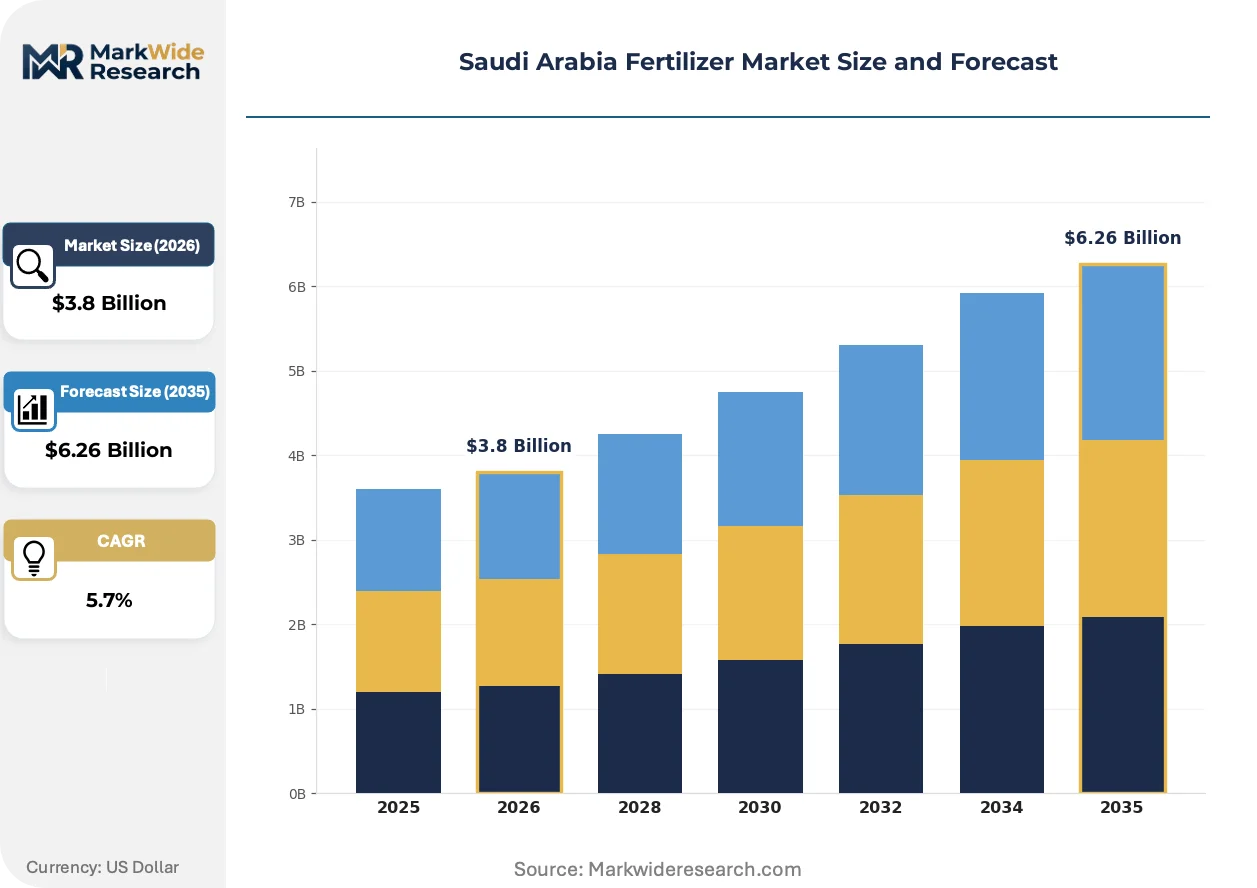
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, DAP, Potassium Nitrate Form: Granular, Powder, Liquid, Pellets End User: Agriculture, Horticulture, Landscaping, Turf Management Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Wholesale |
| Companies Covered | OCP Group, Saudi United Fertilizer Company (Al-Asmida), SABIC Agri-Nutrients Company, Saf Sulphur Company, Jas Global Industries, Ma'aden Phosphate Company, Al-Tayseer Chemical Industry, Qatar Fertiliser Company (QAFCO), Gulf Petrochemical Industries Company (GPIC), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Fertilizer Market Evolving Landscape
Digital soil mapping and variable-rate application systems are restructuring how nutrients reach Saudi wheat and date palm operations, compressing traditional broadcast methods.
Polymer-coated controlled-release fertilizers are decentralizing nutrient management authority from centralized procurement offices to field-level agronomists. Large-scale wheat operations in Qassim are adopting these formulations to synchronize nitrogen release with crop growth stages. This shift reduces leaching losses in sandy soils and enables split-application schedules without multiple field passes.
SFDA residue threshold enforcement is compressing import windows for non-certified suppliers while elevating domestic laboratory infrastructure investments. Heavy metal testing mandates now require third-party verification before port clearance at Dammam and Jeddah. Fertilizer traders with captive analytical capabilities are capturing share from documentation-dependent competitors facing extended clearance timelines.
Direct procurement from integrated producers is displacing layered distributor networks in the Eastern Province. Large agricultural cooperatives around Al-Ahsa and Al-Qatif are negotiating volume contracts with Jubail-based ammonia-urea complexes, bypassing traditional wholesale channels. This channel consolidation concentrates pricing power with feedstock-integrated manufacturers while compressing margins for independent trading operations.
Saudi Arabia Fertilizer Market Segmentation
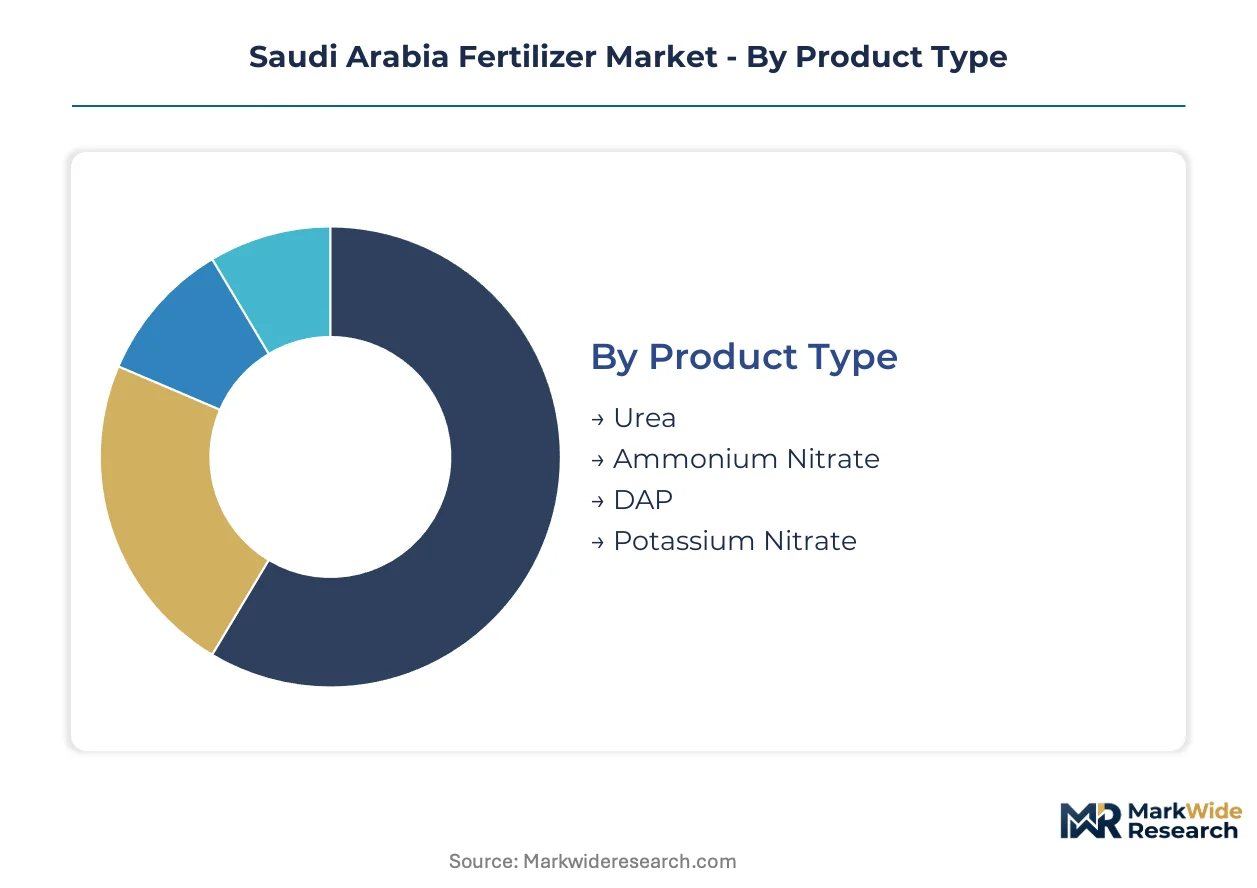
Segmentation in the Saudi fertilizer market reveals how feedstock integration, crop specialization, and regulatory compliance reshape procurement patterns. Buyers select formulations based on soil chemistry, irrigation infrastructure, and SFDA certification requirements rather than price alone.
Product Type:
Buyers differentiate primarily by nitrogen density requirements and chloride sensitivity of target crops.
- Urea:Contains 46% nitrogen by weight, the highest concentration among solid fertilizers. Qassim wheat operations absorb the largest volumes due to compatibility with broadcast spreading equipment and arid-zone storage stability. Methane-to-urea integration at Jubail Industrial City anchors domestic supply security.
- Ammonium Nitrate:Delivers 34% nitrogen with faster soil mobility than urea. Date palm cultivation in Al-Ahsa and Al-Qatif favors this formulation for split-application schedules during fruit development stages.
- DAP:Diammonium phosphate supplies nitrogen and phosphorus in 18-46-0 N-P-K ratio. Field crop operators in central Saudi Arabia deploy DAP for phosphorus-deficient sandy soils.
- Potassium Nitrate:Premium chloride-free potassium source for greenhouse tomatoes and cucumbers. Horticulture segments in Riyadh and Jeddah pay price premiums for residue-compliant grades.
Urea leads volumes today; potassium nitrate is gaining share fastest.
Form:
Storage infrastructure and application equipment determine form selection across interior and coastal farming zones.
- Granular:Spherical particles 2-4mm diameter resist caking in low-humidity environments. Mechanized wheat farms in Qassim specify granular for pneumatic spreader compatibility and minimal dust generation.
- Liquid:Pre-dissolved nutrient solutions enable fertigation through drip systems. Treated wastewater infrastructure in the Eastern Province supports liquid adoption for high-value vegetable production.
- Powder:Fine-ground formulations dissolve rapidly for foliar spray applications. Specialty crop consultants specify powder for micronutrient blends targeting greenhouse operations.
- Pellets:Compressed formulations with controlled-release coatings. Polymer-coated pellets command premiums in turf management contracts for Riyadh municipal landscaping.
Granular dominates procurement today; liquid is expanding most quickly.
End User:
Scale and technical sophistication separate commercial agricultural operations from maintenance-oriented buyers.
- Agriculture:Large-scale wheat and date palm producers purchasing bulk volumes. Cooperative buying groups in Al-Ahsa negotiate direct contracts with Jubail-based manufacturers, bypassing distributor margins.
- Horticulture:Greenhouse and open-field vegetable operations requiring precision nutrient management. Riyadh and Jeddah peri-urban zones concentrate demand for chloride-free potassium formulations.
- Landscaping:Municipal and private estate maintenance contractors. Seasonal procurement patterns align with planting calendars rather than continuous cultivation cycles.
- Turf Management:Golf courses, sports facilities, and luxury residential compounds. Neom and Red Sea Project developments specify slow-release formulations for water-efficient establishment phases.
Agriculture absorbs the largest tonnage; horticulture shows the steepest expansion trajectory.
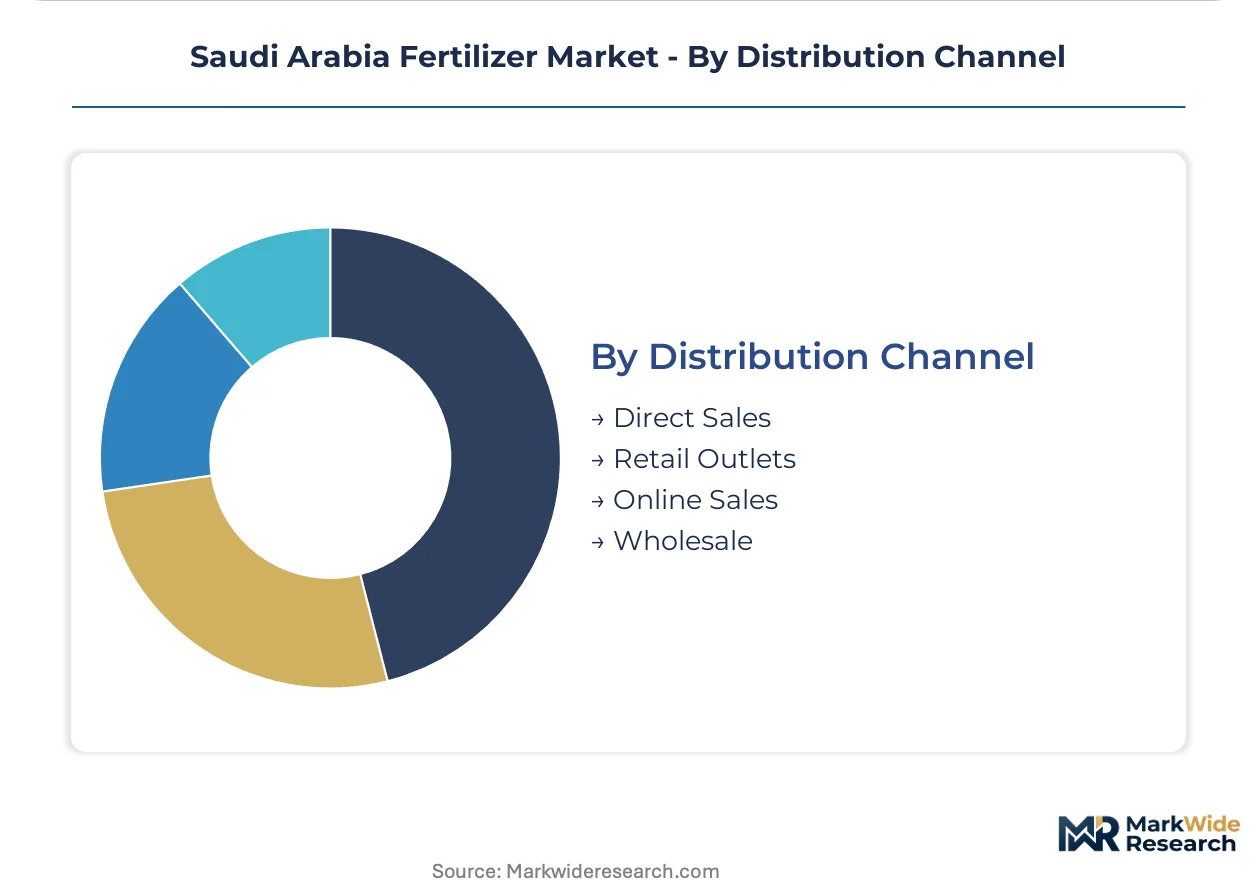
Distribution Channel:
Integration depth and volume scale determine whether buyers access feedstock-integrated supply or layered wholesale networks.
- Direct Sales:Volume contracts between agricultural cooperatives and ammonia-integrated producers. Eastern Province cooperatives with storage infrastructure capture 10-15% price advantages over retail-dependent competitors.
- Wholesale:Regional distributors serving interior provinces lacking direct producer access. Inventory holding in Qassim and Asir requires climate-controlled warehousing investments.
- Retail Outlets:Local agrochemical shops serving smallholder farmers. Package sizing and credit terms outweigh price sensitivity for this buyer tier.
- Online Sales:Digital platforms emerging for specialty formulations and laboratory-certified imports. SFDA documentation transparency enables remote verification before purchase commitment.
Direct sales command the largest value flows; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomist and soil chemistry specialists concentrate around Riyadh and the Eastern Province, anchoring technical advisory capacity for precision fertilizer deployment across Saudi Arabia's agricultural zones.
Eastern Province
Jubail Industrial City hosts methane-to-ammonia complexes supplying feedstock for urea synthesis. SFDA residue certification laboratories cluster in Dammam, accelerating import clearance for certified suppliers. Large agricultural cooperatives in Al-Ahsa negotiate direct procurement contracts with ammonia-integrated producers, bypassing traditional wholesale channels.
Qassim Region
Mechanized wheat cultivation absorbs granular nitrogen formulations optimized for broadcast spreading equipment. The region's sandy soils drive demand for controlled-release coatings that reduce leaching losses. Bulk storage facilities in Buraidah require humidity control upgrades to preserve product integrity during extended holding periods.
Riyadh Province
Peri-urban greenhouse operations concentrate demand for chloride-free potassium nitrate in tomato and cucumber production. The Saudi Vision 2030 sustainability framework mandates precision agriculture targets that expand addressable markets for polymer-coated formulations. Municipal landscaping contracts specify slow-release pellets for water-efficient turf establishment.
Western Region
Jeddah port serves as the primary entry point for imported specialty fertilizers requiring SFDA heavy metal documentation. Date palm cultivation in Medina and Tabuk favors ammonium nitrate for split-application schedules during fruit development. Retail agrochemical distribution networks serve smallholder farmers with package sizing prioritized over bulk pricing.
NEOM Northwest
Red Sea Project developments specify premium slow-release formulations for establishment-phase landscaping in arid coastal conditions. Treated seawater infrastructure enables fertigation system deployment for high-value ornamental plantings. Direct procurement relationships with integrated producers are displacing layered distributor networks for large-scale contracts.
Saudi Arabia Fertilizer Market Competitive Landscape
Capital-heavy producers compete with asset-light traders across Saudi Arabia's fertilizer supply base. The market structure concentrates around feedstock-integrated ammonia-urea complexes and import-dependent specialty distributors. Three archetypes dominate: petrochemical-integrated manufacturers with captive methane supply, regional traders with SFDA certification capabilities, and cross-border exporters leveraging granular urea shipments. Competitive moves center on backward integration into ammonia production and laboratory infrastructure investments for residue compliance.
Among domestic integrated producers, SABIC Agri-Nutrients Company and Ma'aden Phosphate Company exemplify the capital-intensive archetype with captive feedstock positions. Qatar Fertiliser Company represents the cross-border exporter archetype serving Dammam and Jeddah port offtake. These anchors illustrate how feedstock access and certification capabilities separate sustainable competitive positions from documentation-dependent trading operations facing margin compression.
| Leading Market Players |
|---|
| OCP Group |
| Saudi United Fertilizer Company (Al-Asmida) |
| SABIC Agri-Nutrients Company |
| Saf Sulphur Company |
| Jas Global Industries |
| Ma'aden Phosphate Company |
| Al-Tayseer Chemical Industry |
| Qatar Fertiliser Company (QAFCO) |
| Gulf Petrochemical Industries Company (GPIC) |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers with captive methane feedstock anchor supply-side concentration while exerting disciplined pricing power over import-dependent traders facing SFDA certification cost burdens.
Pricing Analysis
Bundled laboratory certification and logistics services command premiums over unbundled commodity urea transactions. Pricing stratifies across premium, standard, and economy tiers based on SFDA residue compliance grade and volume scale. Pricing pressure stems from natural gas volatility at Jubail clusters compressing ammonia synthesis margins. Large agricultural cooperatives in Al-Ahsa exhibit lowest price sensitivity due to direct procurement contracts, while smallholder farmers at retail outlets face highest sensitivity to package-size economics.
Supply Chain Analysis
Empty container repositioning and bulk handling equipment refurbishment flows from Dammam port back to Jubail Industrial City sustain fertilizer logistics efficiency. Supply concentrates in Saudi Arabia, Qatar, and Morocco for ammonia-urea complexes and phosphate rock processing. Raw material dependencies center on natural gas feedstock, sulfuric acid for phosphoric acid production, and polymer coating chemicals for controlled-release formulations. Tariff exposure on European specialty coating imports presents structural risk. Distribution runs through direct sales contracts for volume buyers and wholesale networks for interior provinces lacking storage infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA residue threshold tightening functions as a regulatory compounder, elevating domestic laboratory infrastructure investments while compressing import windows for non-certified suppliers.
For Market Incumbents: Anticipate margin compression from QAFCO cross-border granular urea shipments by securing backward integration into ammonia production at Jubail clusters. Invest in captive heavy metal testing laboratories to capture share from documentation-dependent traders facing extended Dammam port clearance timelines. Channel control through direct cooperative contracts in Al-Ahsa and Al-Qatif defends pricing power against distributor bypass threats.
For New Entrants and Emerging Players: Capture white-space opportunity in polymer-coated controlled-release formulations for Qassim wheat belt precision agriculture applications. Target peri-urban greenhouse operations in Riyadh with chloride-free potassium nitrate certified for SFDA horticulture residue limits. Pursue go-to-market partnerships with agricultural cooperatives possessing existing storage infrastructure rather than building independent wholesale networks.
For Investors and Strategic Acquirers: Petrochemical conglomerates seeking downstream agri-nutrient exposure represent the most active acquirer in this space. Long-term viability hinges on feedstock-integrated positions with methane-to-ammonia infrastructure and SFDA certification capabilities. Monitor Jubail Industrial City capacity expansion announcements as inflection indicators for supply-side pricing discipline.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Production | Captive methane-to-ammonia infrastructure at Jubail clusters defends margins against feedstock volatility. |
| SFDA Laboratory Certification Investment | In-house heavy metal testing accelerates port clearance and separates compliant suppliers from documentation-dependent traders. |
| Controlled-Release Technology Partnership | Polymer coating capabilities enable premium positioning in Qassim wheat precision agriculture segments. |
| Direct Cooperative Procurement Contracts | Volume agreements with Al-Ahsa agricultural cooperatives bypass wholesale margins and concentrate pricing power. |
| Treated Wastewater Fertigation Infrastructure | Eastern Province liquid fertilizer deployment expands through irrigation system integration with municipal water recycling. |
Research Methodology
Bottom-up agricultural end-use modeling reconciled against top-down petrochemical feedstock tracking forms the analytical core of this study. Primary interviews with SABIC Agri-Nutrients procurement directors, Ma'aden Phosphate plant managers, Al-Ahsa cooperative buying group leaders, and SFDA regulatory affairs specialists combined with secondary validation. Secondary sources include SASO technical regulations, SFDA fertilizer registration databases, Jubail Industrial City production disclosures, and customs import documentation at Dammam and Jeddah ports. Triangulation across stakeholder inputs and documentary sources ensures segment-level consistency.
Input-output matrices map ammonia and urea production capacities against wheat, date palm, and greenhouse cultivation acreage across Saudi sub-regions. Segmentation dimensions include product type, physical form, end-user scale, and distribution channel depth. CAGRs derive from production capacity trajectories at Jubail clusters and cultivation expansion patterns in Qassim and Al-Ahsa. Forecast inputs incorporate SFDA regulatory implementation timelines and Saudi Vision 2030 precision agriculture targets.
Natural gas price volatility, SFDA enforcement intensity variations, and treated wastewater infrastructure deployment delays are the dominant revision risks. Forecasts reflect capacity and demand assumptions subject to these triggers. Practitioners should monitor Jubail feedstock pricing, Dammam port clearance duration statistics, and municipal water recycling project announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
United States Organic Fertilizers Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Soil Conditioners Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
Single Superphosphate (SSP) Market