
 Grain Silos and Storage System Market | 2026-2036
Grain Silos and Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Silos and Storage System Market Insights
The divergence between premium and commodity tiers is hardening as large-scale automated steel silo systems with integrated climate control command fundamentally different procurement cycles than basic corrugated bins. Sukup Manufacturing Co. leverages its Iowa-based fabrication footprint to anchor supply for North American agricultural producers seeking high-capacity galvanized structures. SCAFCO Grain Systems Co. competes through specialized hopper-bottom designs that reduce unload times for commercial grain traders. Symaga differentiates by dominating European project engineering for port-side concrete silo complexes.
Grain silos and storage systems are engineered structures designed to preserve cereal crop quality through controlled aeration, moisture management, and pest exclusion, typically fabricated from galvanized steel with 4-8mm wall thickness or reinforced concrete for capacities exceeding 50,000 tonnes. Their primary purpose is to extend grain marketability windows by maintaining stable internal conditions that prevent spoilage, fungal growth, and insect infestation during seasonal price fluctuations. Steel silos occupy the dominant share of new installations due to faster on-site assembly and lower foundation requirements compared to poured concrete alternatives. Automated solutions with remote temperature sensing and aeration fan control represent the fastest-expanding technology segment as food processors and co-operatives seek labor reduction and real-time quality assurance.
The USDA's Grain Inspection, Packers and Stockyards Administration enforces structural and sanitary standards that shape domestic silo design specifications and market access for equipment suppliers. In Europe, the EU Green Deal and F-Gas Regulation drive retrofit demand for low-energy aeration and heat-recovery systems in existing storage infrastructure. China's GB standards for grain storage safety, administered by SAMR, mandate specific ventilation rates and fire suppression protocols that filter which foreign manufacturers qualify for state procurement tenders. Stakeholders must monitor how carbon accounting requirements and energy efficiency benchmarks increasingly penetrate agricultural infrastructure procurement criteria across multiple jurisdictions.
Market Dynamics
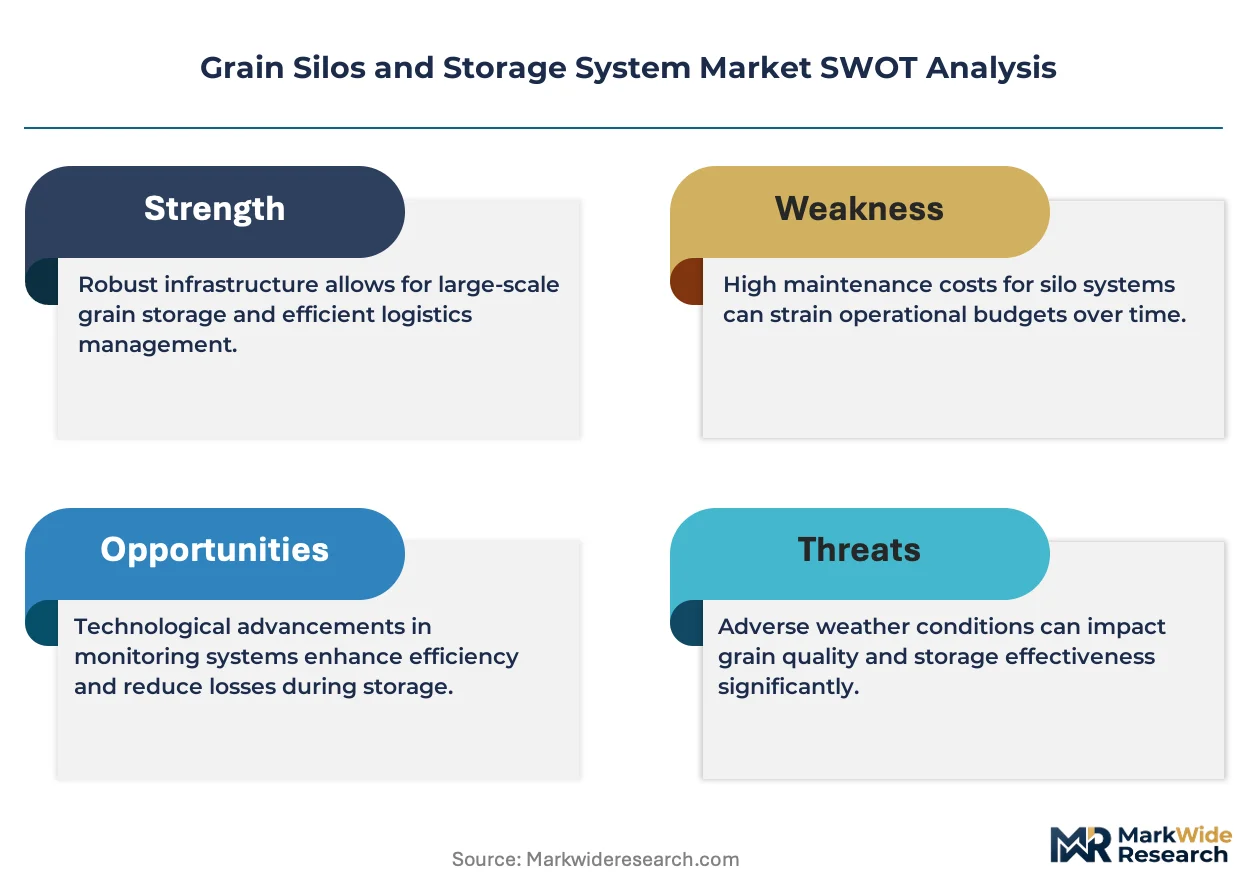
Automated climate monitoring systems are compressing traditional aeration cycles as grain handlers prioritize real-time spoilage prevention over scheduled ventilation protocols. This technological inflection is redrawing capital allocation patterns across storage infrastructure investments.
Growth Catalysts
- USDA GIPSA structural standards:Federal sanitary and engineering mandates compel facility upgrades, creating replacement demand for compliant steel silo systems and integrated monitoring hardware.
- On-farm storage expansion:Agricultural producers in Iowa, Mato Grosso, and Heilongjiang are adding capacity to bypass elevator delivery windows and capture price arbitrage during harvest compression.
- Remote sensing integration:Wireless temperature and humidity probes linked to aeration controls reduce labor inspection rounds while maintaining GB-standard ventilation compliance in Chinese state grain reserves.
Market Restraints
- Galvanized steel price volatility:Zinc coating inputs fluctuate with mining supply disruptions, squeezing fabrication margins for hopper-bottom and flat-bottom silo manufacturers.
- Foundation engineering concentration:Specialized geotechnical contractors for high-capacity concrete silo complexes cluster in Western Europe, limiting project velocity in emerging storage markets.
- F-Gas Regulation retrofit friction:EU-mandated heat recovery and low-energy aeration upgrades impose capital burdens on aging port-side facilities without guaranteed throughput recovery.
Strategic Opportunities
- Sub-Saharan storage deficit:Post-harvest loss rates exceeding 20% in Nigeria and Kenya create openings for modular steel silo deployments with mobile aeration units.
- EU Green Deal carbon accounting:Energy efficiency benchmarks for agricultural infrastructure unlock financing for solar-integrated aeration and thermal storage systems in cooperative facilities.
- Blockchain-enabled provenance tracking:Converging IoT sensors with distributed ledger verification allows exporters to command premiums from European and Japanese food processors demanding supply chain transparency.
Industry Challenges
- Certified welding technician scarcity:Field assembly of sealed galvanized structures requires specialized corrosion-resistant joining skills that agricultural equipment labor pools rarely possess.
- Legacy aeration integration:Retrofitting automated fan control onto 1970s-era concrete silos demands custom PLC programming that extends commissioning timelines and strains maintenance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Silos and Storage System Market |
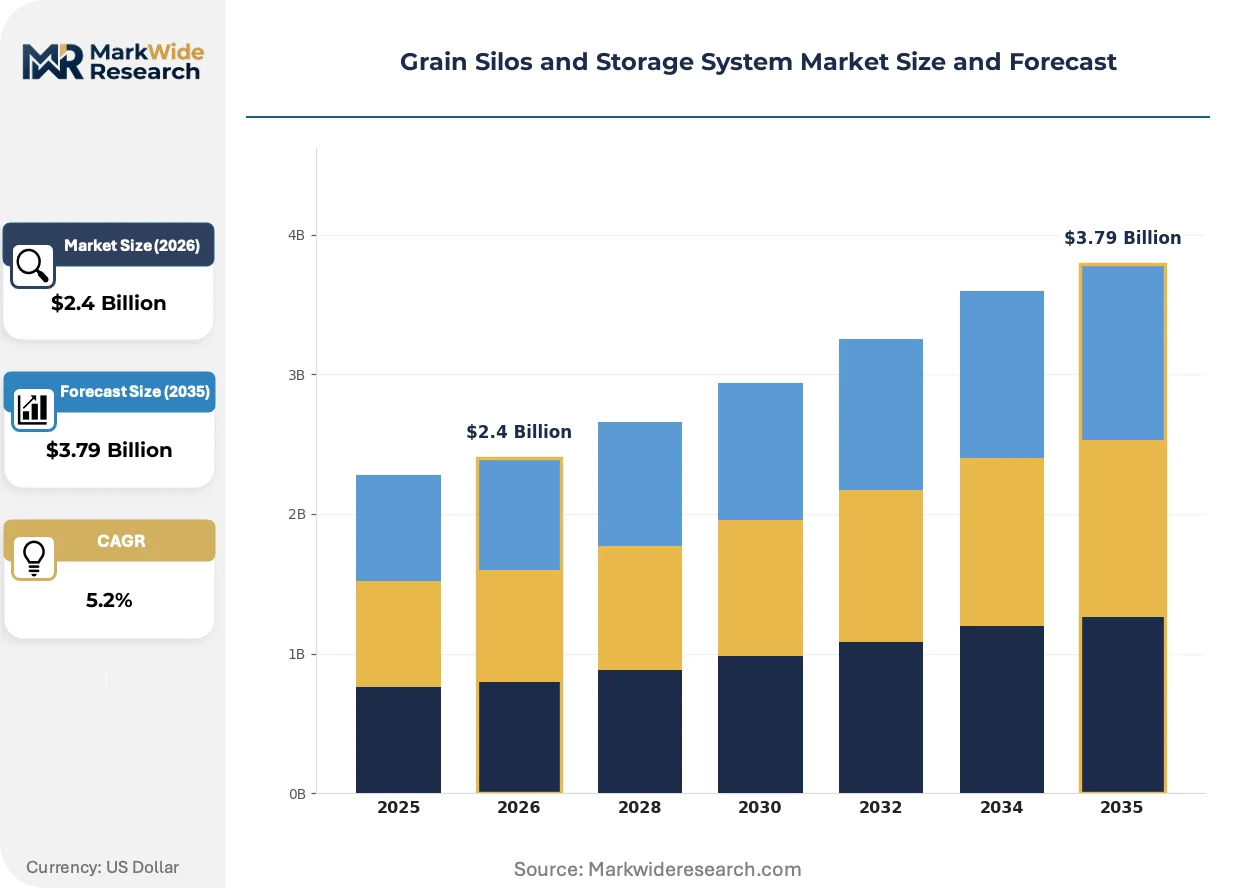
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Silos, Concrete Silos, Bins, Bags End User: Agricultural Producers, Food Processors, Grain Traders, Co-operatives Capacity: Small Scale, Medium Scale, Large Scale, Bulk Storage Technology: Traditional Storage, Automated Solutions, Temperature Control, Humidity Monitoring |
| Companies Covered | SCAFCO Grain Systems Co., Prado Silos, Ag Growth International Inc., Cimbria A/S, Symaga, Sukup Manufacturing Co., Brock Grain Systems, Superior Grain Equipment, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Silos and Storage System Market Trends and Innovations
Digital infrastructure is penetrating grain storage faster than mechanization did in prior decades, compressing the gap between harvest conditioning and market readiness. This convergence of sensing, control, and data architecture is redefining what constitutes a complete storage system.
Integrated aeration and temperature management platforms are unifying previously separate mechanical and electronic subsystems into single-dashboard operations. Large grain cooperatives in the US Corn Belt and Brazilian Center-West are deploying these systems at greenfield sites within 18-month construction windows. The technology is unifying capital expenditure categories that buyers once sourced from distinct vendors, consolidating procurement relationships around full-stack suppliers.
The EU F-Gas Regulation is phasing down hydrofluorocarbon-based cooling in favor of natural refrigerants and heat recovery aeration designs. This transition forces engineering retrofits at major port storage complexes in Rotterdam and Hamburg. European project engineers are responding with concrete silo designs that embed geothermal preconditioning loops, trading higher upfront construction costs for operational compliance.
Service unbundling is separating hardware procurement from ongoing monitoring subscriptions as grain traders seek operational expenditure flexibility. Commercial elevators in Argentina and Australia are piloting temperature-monitoring-as-a-service models that transfer sensor maintenance risk to technology vendors. This shift is most visible among multinational grain merchants managing distributed storage networks across multiple regulatory jurisdictions.
Grain Silos and Storage System Market Segmentation
Grain silo procurement patterns diverge sharply across buyer sophistication, with integrated agribusinesses demanding full-stack automated systems while smaller operators prioritize modular steel capacity. Understanding these segment boundaries reveals where technology premiums command pricing power versus where commodity fabrication dominates.
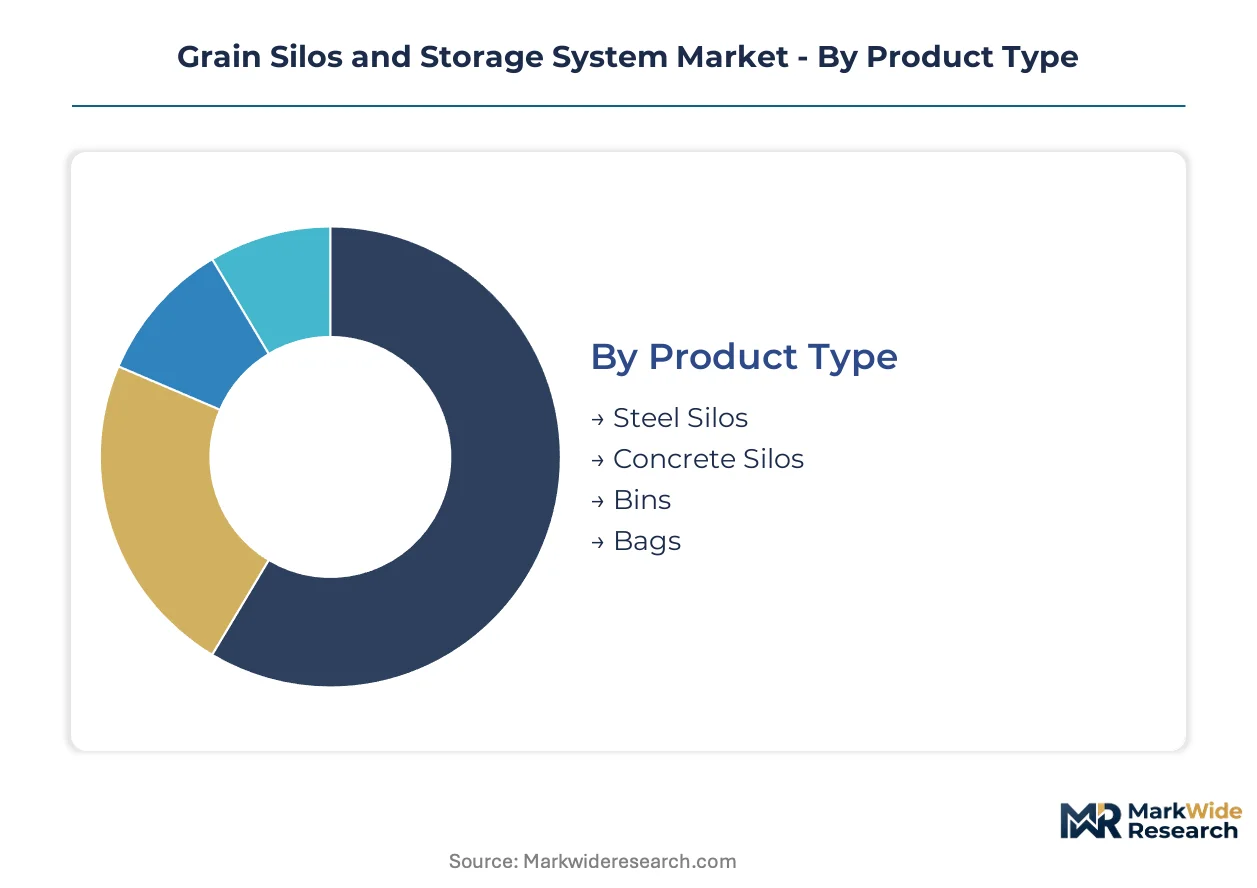
Product Type:
Customization intensity spans from engineered-to-order concrete complexes to catalog-configured steel bins, with fabrication location and foundation requirements driving total installed cost variation.
- Steel Silos:Galvanized corrugated structures with 4-8mm wall thickness enable rapid field assembly using bolted panel construction. Demand concentrates among North American agricultural producers in Iowa and Illinois seeking 10,000-50,000 tonne on-farm capacity with minimal concrete foundation work. Faster installation cycles and lower geotechnical requirements displace concrete alternatives in greenfield grain belt expansions.
- Concrete Silos:Reinforced cylindrical structures exceeding 50,000 tonnes capacity require specialized slip-form construction and deep foundation piling. Port-side complexes in Rotterdam and Hamburg deploy these for long-duration storage of export-bound cereals where structural longevity outweighs capital intensity. EU F-Gas Regulation retrofit mandates accelerate thermal storage integration into new concrete designs.
- Bins:Smaller-diameter hopper-bottom units under 5,000 tonnes serve food processors requiring frequent turnover and rapid discharge. Brazilian soybean processors in Mato Grosso favor these for just-in-time supply to crushing facilities.
- Bags:Polyethylene hermetic storage for emergency harvest overflow or temporary field-side conditioning. Nigerian and Kenyan grain cooperatives adopt these where capital constraints preclude permanent structures.
Most installed capacity flows through Steel Silos. Expansion is steepest in Concrete Silos.
End User:
Customer scale determines whether procurement favors operational expenditure flexibility or capital-intensive ownership models.
- Agricultural Producers:Farm-level operators in the US Corn Belt and Brazilian Center-West adding 20,000-100,000 tonne capacity to bypass commercial elevator delivery windows. Price arbitrage capture during harvest compression justifies automation investment despite higher upfront cost.
- Grain Traders:Multinational merchants operating distributed port and inland elevator networks. Argentine and Australian facilities pilot temperature-monitoring-as-a-service to transfer sensor maintenance risk onto technology vendors.
- Food Processors:Milling and brewing operations requiring certified sanitary storage with lot traceability. Japanese and European buyers command blockchain-enabled provenance verification for supply chain transparency.
- Co-operatives:Member-owned storage networks pooling capital for shared infrastructure. EU Green Deal carbon accounting unlocks financing for solar-integrated aeration in French and German cooperative facilities.
Volume concentrates with Agricultural Producers. Technology upgrade rates are highest among Grain Traders.
Capacity:
Scale thresholds align with distinct construction methodologies and automation integration depth.
- Small Scale:Sub-1,000 tonne units serving specialty grain segregation or seed multiplication programs. Organic wheat producers in Saskatchewan deploy these for identity-preserved crop isolation.
- Medium Scale:1,000-10,000 tonne configurations dominating on-farm expansion in Heilongjiang province. Chinese state grain reserve procurement favors this tier for distributed storage network resilience.
- Large Scale:10,000-50,000 tonne systems with integrated aeration and temperature sensing. US cooperative facilities in Minnesota and Indiana standardize on this capacity band for harvest compression management.
- Bulk Storage:Exceeding 50,000 tonnes at major export terminals and strategic reserve facilities. Foundation engineering scarcity in Western Europe limits project velocity for new concrete complexes in this tier.
Medium Scale captures the majority of annual installations. Bulk Storage commands the highest project values per site.
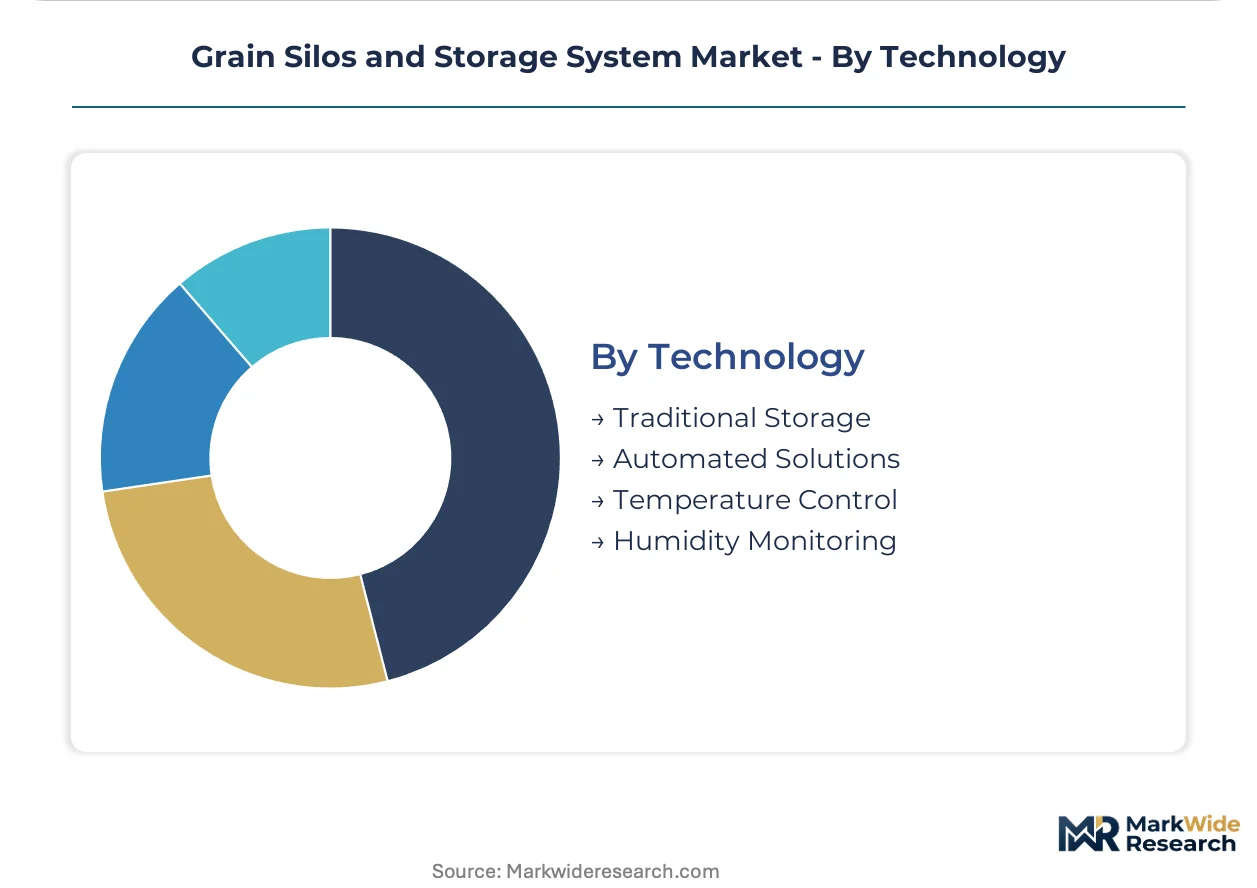
Technology:
Digital penetration depth separates legacy mechanical systems from unified control platforms.
- Traditional Storage:Scheduled aeration and manual temperature inspection protocols. Aging concrete silos from the 1970s in Eastern Europe retain this profile where retrofit capital is constrained.
- Automated Solutions:Unified dashboard control merging aeration fans, temperature probes, and moisture sensors into single-platform operations. Large cooperatives in the US Corn Belt deploy these within 18-month construction windows.
- Temperature Control:Wireless probe networks enabling real-time spoilage prevention rather than scheduled ventilation cycles. Chinese state grain reserves deploy these to maintain GB-standard ventilation compliance with reduced labor inspection rounds.
- Humidity Monitoring:Capacitance and resistive sensors tracking grain moisture equilibrium to trigger targeted aeration. Australian wheat exporters integrate these with quality certification systems for Asian market access.
Traditional Storage retains the largest installed base. Automated Solutions are climbing the fastest as procurement consolidates around full-stack suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication labor pools in Iowa and Mato Grosso anchor the largest regional production clusters for galvanized steel silo systems. These workforce concentrations shape where capital investment flows and which regulatory standards dominate procurement specifications.
United States
Corn Belt agricultural producers in Iowa and Illinois are expanding on-farm storage capacity to capture harvest-time price arbitrage. USDA GIPSA structural and sanitary standards compel facility upgrades, creating replacement demand for compliant steel systems. Sukup Manufacturing Co. leverages its Iowa-based fabrication footprint to anchor supply for North American producers seeking high-capacity galvanized structures.
Brazil
Soybean processors in Mato Grosso favor hopper-bottom bins for just-in-time supply to crushing facilities. ANVISA and Ministry of Agriculture sanitary protocols filter equipment imports. The Center-West region concentrates greenfield storage investments as producers bypass congested port delivery windows during harvest compression.
China
State grain reserve procurement in Heilongjiang province favors medium-scale distributed storage for network resilience. SAMR-administered GB standards mandate specific ventilation rates and fire suppression protocols that filter foreign manufacturer qualification for state tenders. Remote temperature sensing deployments reduce labor inspection rounds while maintaining compliance.
Germany
EU F-Gas Regulation retrofit mandates accelerate thermal storage integration into new concrete silo designs at Rotterdam and Hamburg port complexes. The country's national agricultural regulator enforces energy efficiency benchmarks that unlock financing for solar-integrated aeration in cooperative facilities. Western European project engineering clusters concentrate specialized geotechnical contracting for high-capacity foundations.
Australia
Wheat exporters integrate humidity monitoring with quality certification systems for Asian market access. The country's national agricultural regulator oversees sanitary storage standards for export-bound cereals. Temperature-monitoring-as-a-service pilots among commercial elevators transfer sensor maintenance risk to technology vendors.
Grain Silos and Storage System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across fabrication and systems integration boundaries. The vendor base spans integrated steel fabricators with captive galvanizing lines, specialized concrete engineering houses, and technology vendors unbundling monitoring hardware from installation services. Three archetypes dominate: full-stack automated system suppliers, commodity steel bin fabricators, and project-engineered concrete specialists. Consolidation pressure runs through strategic partnerships linking sensor vendors with established fabricators, plus capacity expansion into Sub-Saharan markets where post-harvest losses exceed 20 percent.
Among North American fabricators, Sukup Manufacturing Co. and Brock Grain Systems exemplify the integrated steel production archetype with domestic fabrication footprints. SCAFCO Grain Systems Co. occupies a position within the specialized design tier, its company name signaling hopper-bottom engineering concentration. Symaga represents the European project-engineering archetype, anchoring concrete silo complex delivery for port-side storage infrastructure.
| Leading Market Players |
|---|
| SCAFCO Grain Systems Co. |
| Prado Silos |
| Ag Growth International Inc. |
| Cimbria A/S |
| Symaga |
| Sukup Manufacturing Co. |
| Brock Grain Systems |
| Superior Grain Equipment |
| AGCO Corporation |
| Others |
Pricing and Supply Chain Analysis
Automated temperature-monitoring platform adoption is compressing traditional aeration economics while concentrating procurement power among full-stack system suppliers. This technology transition simultaneously elevates upfront capital requirements for grain handlers and reduces long-term operational expenditure flexibility, reshaping how buyers evaluate total cost of ownership across galvanized steel and concrete storage alternatives.
Pricing Analysis
Service unbundling from hardware procurement is fragmenting traditional project-based contracting into subscription-tiered monitoring arrangements. Three-tier pricing structure across premium automated systems, standard semi-automated configurations, and economy manual-aeration tiers separates buyers by operational sophistication and capital availability. Cost compression in economy steel silo segments is intensifying because zinc-coated galvanized steel input volatility squeezes fabrication margins. Agricultural producers in the US Corn Belt exhibit highest price sensitivity due to seasonal cash flow constraints, while multinational grain traders demonstrate lowest sensitivity given operational expenditure flexibility priorities.
Supply Chain Analysis
Single-source vulnerability sits with specialized geotechnical contractors for high-capacity concrete foundation engineering clustered in Western Europe. Fabrication capacity concentrates in the United States, Brazil, and China where galvanized steel panel production and field assembly labor pools anchor regional supply networks. Raw material dependencies rest on zinc mining supply chains, hot-rolled steel coil availability, and corrosion-resistant welding consumables. Tariff exposure on Chinese steel inputs presents structural risk for North American fabricators dependent on imported substrate materials. Distribution runs through direct OEM sales to large agricultural producers and co-operatives, with project-engineered concrete complexes sold through specialized construction management firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in automated system integration and aftermarket monitoring services as buyers shift from capital-intensive ownership toward operational expenditure flexibility. Premium-tier displacement of commodity steel bins by full-stack climate-controlled platforms justifies this reorientation.
For Market Incumbents: Lock in sensor-technology partnerships to anchor full-stack procurement relationships before unbundled service models fragment customer loyalty. Sukup Manufacturing Co. and Brock Grain Systems should deepen captive galvanizing capacity to defend against zinc price volatility eroding fabrication margins. Incumbent steel fabricators face emerging threat from technology vendors unbundling monitoring hardware from installation services. For New Entrants and Emerging Players: Sub-Saharan agricultural co-operatives in Nigeria and Kenya represent the most penetrable buyer archetype given post-harvest loss rates exceeding 20 percent and absent permanent storage infrastructure. Modular steel silo deployments with mobile aeration units address capital-constrained demand. Blockchain-enabled provenance verification systems command premium positioning with Japanese and European food processors demanding supply chain transparency. For Investors and Strategic Acquirers: Valuations sit cheapest among commodity steel bin fabricators lacking automation integration capabilities relative to full-stack system suppliers. Long-term viability favors technology-forward vendors with recurring revenue streams from monitoring subscriptions. Acquisition target archetype: mid-cap European concrete engineering houses with established port-side project credentials and EU Green Deal retrofit exposure. Watch for inflection when Chinese state grain reserve procurement shifts from medium-scale distributed storage toward bulk terminal automation.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Platform Integration | Unifies aeration, temperature, and humidity control into single-dashboard operations for US cooperatives. |
| Backward Integration into Galvanizing | Captive zinc-coating capacity insulates fabrication margins from mining supply disruption volatility. |
| EU Green Deal Retrofit Positioning | Thermal storage and solar-integrated aeration unlock financing for cooperative facility upgrades. |
| Sub-Saharan Modular Deployment | Mobile steel silo units with aeration-as-a-service address 20 percent post-harvest loss rates. |
| Blockchain Provenance Verification | IoT sensor convergence with distributed ledger commands premiums from Japanese food processors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct segment-level demand estimates. Primary discussions with grain elevator operators, agricultural cooperative managers, food processor procurement directors, and steel fabrication plant engineers informed capacity expansion timelines and technology adoption thresholds. Secondary validation drew from USDA GIPSA facility inspection records, EU F-Gas Regulation implementation reports, Chinese SAMR grain reserve procurement disclosures, and customs trade data on galvanized steel panel exports. Bottom-up project pipeline tracking and top-down agricultural production forecasts were triangulated to anchor volume assumptions.
Segment-weighting approaches distributed total market value across product type, end user, capacity tier, and technology penetration dimensions. Steel silo, concrete silo, bin, and bag categories were modeled separately with distinct installation cost curves and replacement cycles. Agricultural producer, grain trader, food processor, and co-operative end-use segments carried differentiated automation upgrade propensities. CAGRs were derived from rolling three-year capacity addition trends and technology substitution elasticities. Forecast inputs incorporated zinc price volatility scenarios, EU F-Gas retrofit compliance deadlines, and Chinese state grain reserve distributed storage network expansion targets.
Underlying measurement precision varies by segment; automated solutions and bulk storage carry tighter precision than traditional storage and small-scale installations due to concentrated vendor reporting. Forecasts reflect documented assumptions on technology adoption curves and regulatory implementation timelines. Commodity price volatility, geotechnical contractor availability constraints, and trade policy shifts on steel inputs present specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Green Banana Flour Market
Grains
Canada Pulses Market
Grains
00 Flour Market
Grains
Bangladesh Rice Market
Grains
Mexico Rice Market
Grains
South America Wheat Market
Grains
Red Rice Market
Grains
South America Rice Market
Grains
Grain and Cereal Crop Market
Grains
Dried Spent Grain Market
Grains
Ghana Grain Market
Grains
GMO Corn Market
Grains
Argentina Maize Market
Grains
Mesquite Flour Market
Grains
Asia-Pacific Wheat Market
Grains
Grain-Based Flours Market