
 Global Cassava Flour Market | 2026-2036
Global Cassava Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cassava Flour Market Analysis
ISO 22000 certification is rotating as the primary gate for commercial-scale supply contracts in the cassava flour trade. Ingredion Incorporated leverages its integrated starch processing infrastructure to sustain bulk supply agreements across multiple continents. Cargill Incorporated anchors its position through backward integration into Nigerian and Thai raw material zones. Thai Wah Public Company Limited dominates Southeast Asian export channels with specialized tapioca-derived product lines.
Cassava flour consists of dried, powdered starch extracted from Manihot esculenta tubers, typically containing 80-85% carbohydrate content with minimal protein and fat, produced through washing, grating, pressing, drying, and milling sequences for use as a wheat alternative in gluten-free food manufacturing. The organic cassava flour segment commands premium positioning in European and North American retail channels where clean-label claims drive shelf placement. Gluten-free cassava flour occupies the highest volume tier within baking and snack applications as celiac-safe formulations expand across commercial foodservice. Instant cassava flour competes primarily in African and Latin American household markets where preparation convenience determines repeat purchase behavior.
FDA gluten-free labeling rules and the EU's REACH framework govern cross-border starch trade, while Nigeria's NAFDAC and Standards Organisation of Nigeria set domestic fortification and safety benchmarks that determine which processors qualify for public procurement programs. Stakeholders must monitor evolving mycotoxin thresholds and sustainability audit requirements as these standards increasingly determine market access rather than price alone.
Market Dynamics
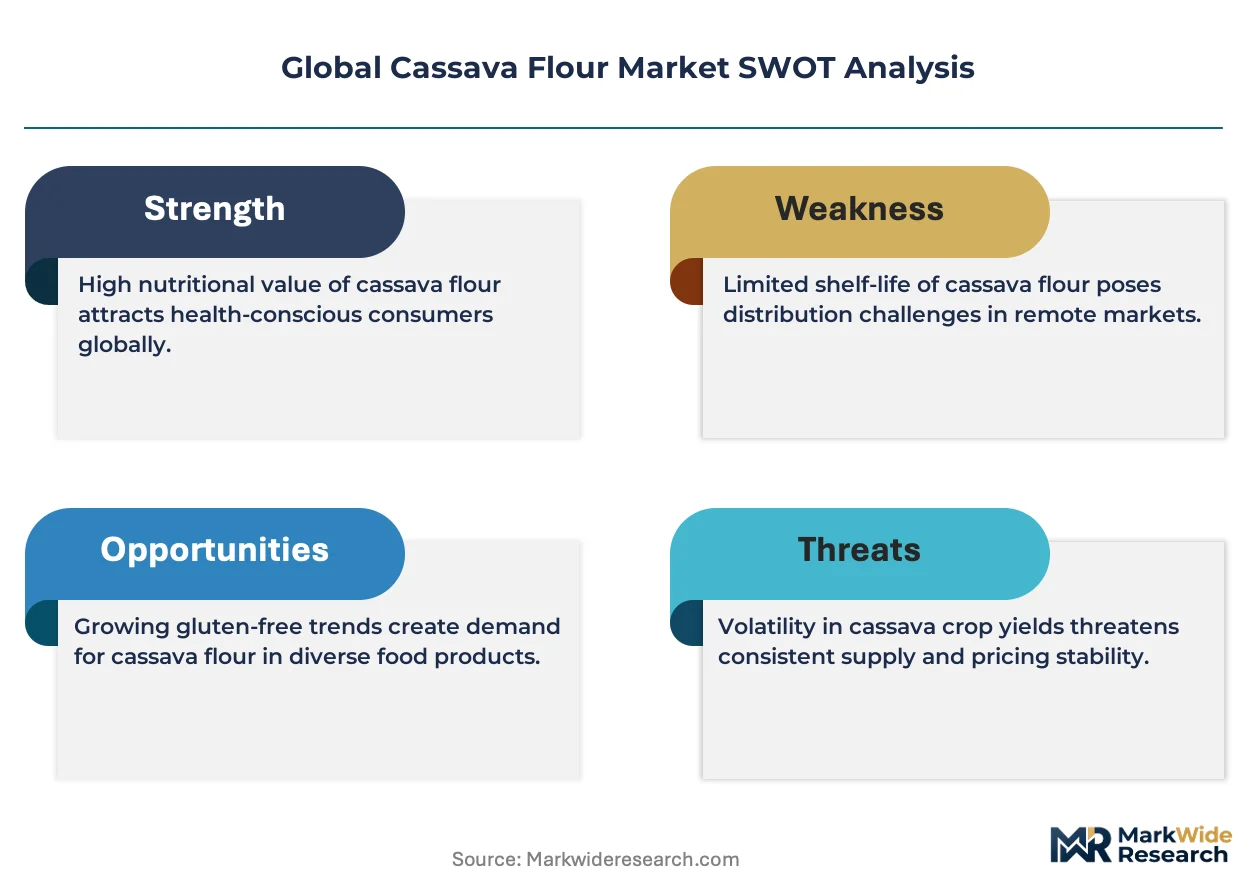
ISO 22000 certification is hardening into a non-negotiable commercial gate across bulk procurement channels, separating contract-eligible processors from spot-market suppliers in the cassava flour trade.
Growth Catalysts
- EU Green Deal compliance:REACH-aligned sustainability audits are accelerating demand for traceable, low-carbon starch derivatives in European food manufacturing.
- Gluten-free bakery expansion:Celiac-safe formulation requirements across North American commercial bakeries are pulling certified cassava flour into wheat-alternative recipes.
- Nigerian food security programs:Domestic processing capacity investments under national fortification mandates are expanding institutional offtake for locally milled flour.
Market Restraints
- Raw material concentration:Nigerian and Thai root supply zones dominate global feedstock, creating weather-linked volume volatility.
- Input cost sensitivity:Natural gas prices directly compress margins for mechanical drying operations, the dominant processing method.
- Regulatory fragmentation:Divergent mycotoxin thresholds between FDA, EFSA, and NAFDAC force parallel compliance investments for exporters.
Strategic Opportunities
- Clean-label retail channels:Organic certification unlocks premium shelf placement in European and North American grocery segments.
- Instant flour convenience positioning:Pre-gelatinized formats address time-constrained households across Brazilian and Colombian urban markets.
- Bioplastics feedstock pivot:Thermoplastic starch applications are opening industrial offtake channels beyond food-grade specifications.
Industry Challenges
- Certification timeline compression:ISO 22000 audit backlogs are delaying contract eligibility for mid-scale African processors.
- Specialized equipment scarcity:Flash dryer fabrication capacity constraints are extending capex deployment cycles for capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cassava Flour Market |
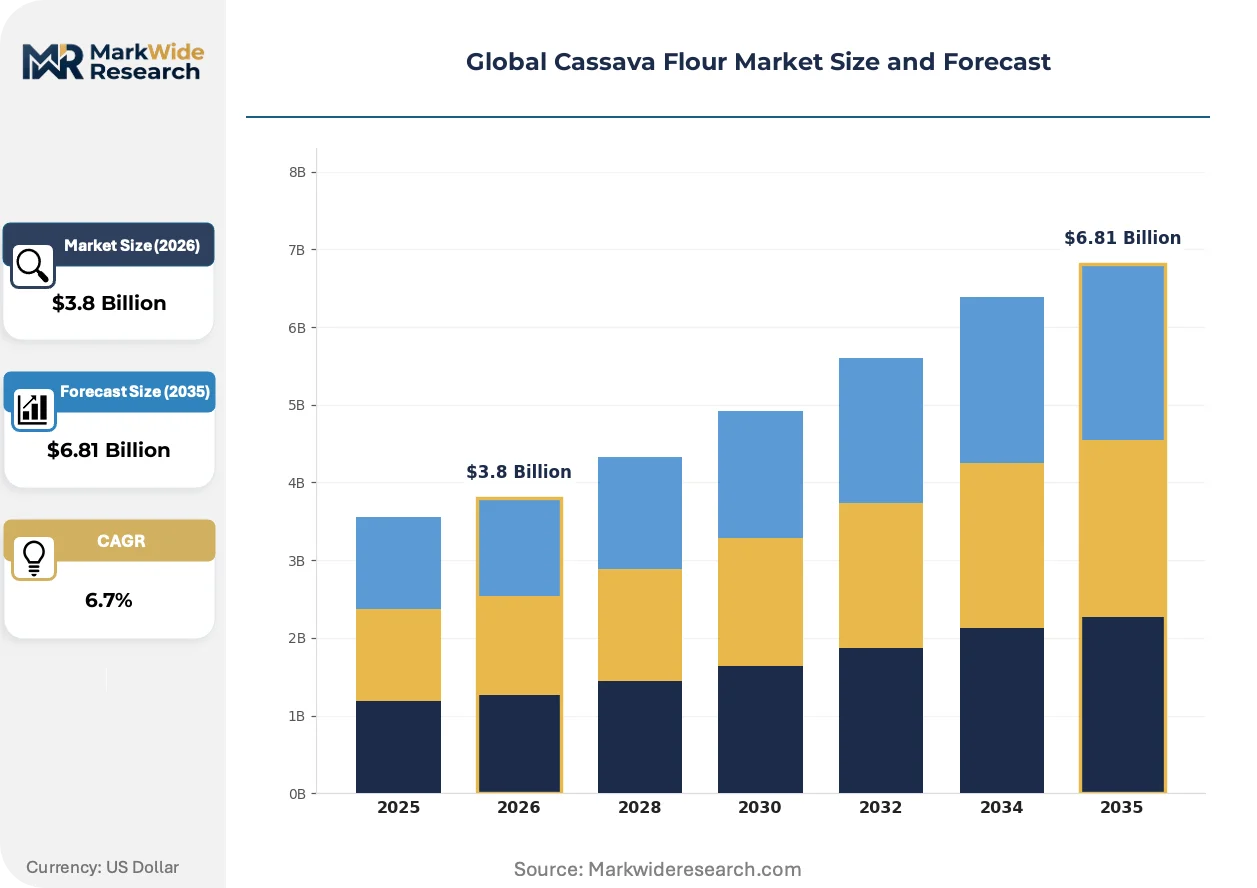
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Cassava Flour, Gluten-Free Cassava Flour, Instant Cassava Flour, Frozen Cassava Flour End Use: Baking, Snacks, Pasta, Sauces Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Packaging Type: Bags, Boxes, Sachets, Tubs |
| Companies Covered | Ingredion Incorporated, Cargill Incorporated, Archer Daniels Midland Company, Thai Wah Public Company Limited, Otto's Naturals, DADTCO Rivers Cassava Processing Company, Psaltry International, Roquette Frères, Emsland Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cassava Flour Market Emerging Trajectories
Processing technology divergence and certification-driven buyer sorting are restructuring competitive access in cassava flour supply chains.
Flash drying systems are fragmenting the traditional sun-drying and belt-drying landscape in Southeast Asian processing clusters. Large-scale Thai exporters are retrofitting facilities to capture energy efficiency gains and reduce aflatoxin risk. This capital-intensive shift is fragmenting the supplier base into ISO-certified industrial processors and informal sun-drying operations serving domestic spot markets.
REACH substance restriction updates are tightening import specifications for starch derivatives entering EU food and industrial applications. ECHA evaluations of processing aid residues are forcing Nigerian exporters to validate supply chain chemical inventories. European importers are consolidating procurement around vertically integrated processors with documented hazard controls.
Clean-label preference sorting is compressing purchase decisions toward certified organic SKUs in premium retail channels. North American gluten-free brands are requiring third-party allergen testing beyond baseline regulatory compliance. This behavioral shift is concentrating shelf access among processors with captive organic root supply and in-house laboratory capabilities.
Global Cassava Flour Market Segmentation
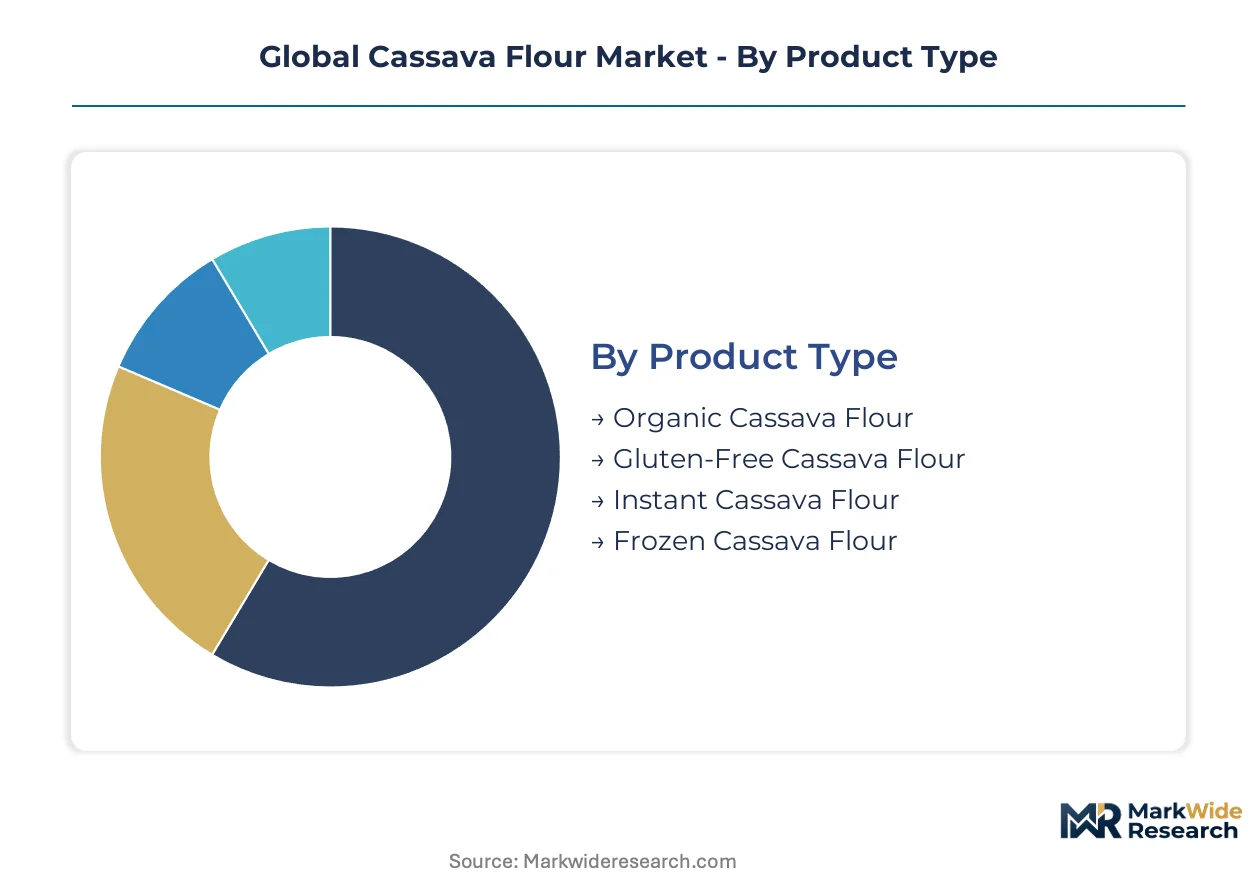
Cassava flour market segmentation reveals how certification tiers, convenience formats, and channel access determine contract eligibility and margin capture across food manufacturing and retail channels.
Product Type:
Premium margin pools concentrate in certified organic and allergen-controlled specifications that unlock shelf placement in European and North American retail.
- Organic Cassava Flour:Milled from root crops cultivated without synthetic pesticides or fertilizers, carrying USDA Organic or EU Organic certification. Clean-label positioning in German and French retail chains commands price premiums three to four times above conventional grades.
- Gluten-Free Cassava Flour:Processed in dedicated facilities with validated allergen controls to meet FDA gluten-free labeling rules and EFSA thresholds. Celiac-safe formulations are accelerating procurement by commercial bakeries across the United States and United Kingdom.
- Instant Cassava Flour:Pre-gelatinized through controlled heat-moisture treatment for cold-water reconstitution. Nigerian and Brazilian household markets favor this format for reduced preparation time.
- Frozen Cassava Flour:Blast-frozen at point of milling to preserve enzymatic stability and extend shelf life. Industrial foodservice operations in Southeast Asian processing clusters utilize this for consistent viscosity in starch applications.
Gluten-free cassava flour holds installed capacity. Organic cassava flour is rotating up the share rankings.
End Use:
Application-driven demand splits between reformulation mandates in commercial baking and convenience positioning in household consumption.
- Baking:Wheat-alternative formulations for bread, pastry, and cake production requiring specific amylose-amylopectin ratios for structural integrity. North American gluten-free bakery expansion is pulling certified flour into industrial mixing operations.
- Snacks:Extruded and sheeted applications including crackers, chips, and puffed products where cassava's neutral flavor profile permits seasoning adhesion. Clean-label snack brands in the United States and Canada are specifying non-GMO verified supply.
- Pasta:Gluten-free noodle and dumpling formulations requiring high gelatinization temperatures for al dente texture. Italian and Brazilian manufacturers are validating cassava-wheat blend ratios for export markets.
- Sauces:Viscosity modification and freeze-thaw stability in gravies, soups, and ready-meal applications. Thai and Vietnamese food processors favor tapioca-derived starches for transparent finished appearance.
Baking commands the largest volume commitment. Snacks are climbing the fastest as extrusion technology spreads.
Distribution Channel:
Channel selection determines certification requirements, with institutional procurement demanding ISO 22000 validation that spot-market suppliers cannot satisfy.
- Supermarkets:Mass retail placement requiring pallet-scale supply consistency and promotional fund participation. European grocery consolidation is favoring processors with pan-national distribution infrastructure.
- Online Retail:Direct-to-consumer fulfillment through Amazon, Thrive Market, and specialty gluten-free portals. Subscription models in the United States are concentrating repeat purchase around single-origin and fair-trade claims.
- Specialty Stores:Health food and ethnic grocery channels with educated staff and sampling programs. Nigerian diaspora communities in the United Kingdom and United States drive demand for specific regional grind specifications.
- Wholesale:Bulk supply to food manufacturers, bakeries, and institutional kitchens with tanker or tote delivery requirements. REACH-aligned sustainability audits are restricting European wholesale procurement to traceable supply chains.
Wholesale channels hold installed capacity. Online retail is gaining share fastest as direct-to-consumer brands bypass traditional distribution.
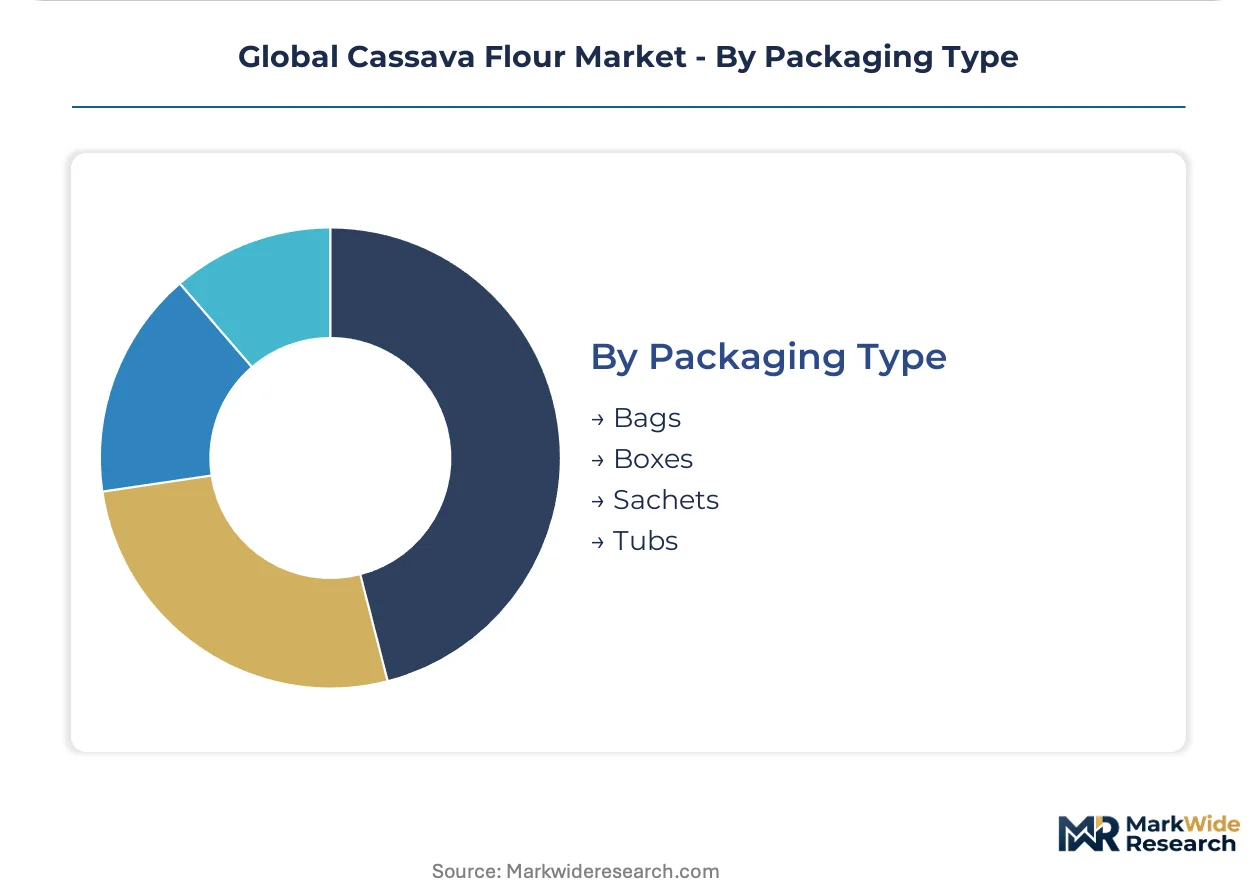
Packaging Type:
Packaging configuration aligns with use-case scale, from household portion control to industrial bulk handling.
- Bags:Multi-wall paper or woven polypropylene formats from 500g to 25kg for retail and small commercial use. Shelf-ready bag designs with window features are rotating into premium organic SKUs.
- Boxes:Corrugated containers with inner liners for palletized shipment to food manufacturers. Automated filling lines in Thai processing facilities favor box formats for line speed optimization.
- Sachets:Single-serve foil or metallized film pouches for instant flour and travel formats. Nigerian and Colombian urban markets are adopting sachet packaging for affordability and portion control.
- Tubs:Rigid plastic containers with resealable lids for high-humidity environments and repeated access. Brazilian retail channels favor tub formats for kitchen storage convenience.
Bags hold installed capacity. Sachets are rotating up the share rankings as emerging-market urbanization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal compliance requirements and Nigeria's national fortification mandates are redirecting procurement flows toward certified supply chains in key producing and consuming countries.
Nigeria
Domestic food security programs and institutional procurement are expanding processing capacity in the Niger Delta and Southwest zones. NAFDAC fortification mandates determine eligibility for public sector offtake contracts. Lagos-Ibadan corridor processors are upgrading mechanical drying infrastructure to meet ISO 22000 audit standards.
Thailand
Specialized tapioca export channels serve Southeast Asian food manufacturing and European industrial starch buyers. REACH-aligned sustainability documentation is becoming mandatory for EU-bound shipments. Chonburi and Nakhon Ratchasima processing clusters are retrofitting flash drying systems to reduce energy intensity.
United States
FDA gluten-free labeling rules are pulling certified cassava flour into commercial bakery reformulation. Celiac-safe product expansion across retail and foodservice channels is accelerating. Texas and California distribution hubs are consolidating procurement around third-party allergen-tested supply.
Germany
Clean-label retail positioning and organic certification premiums are concentrating demand in specialized grocery channels. EFSA mycotoxin thresholds and ECHA substance restrictions govern import specifications. Hamburg and Rotterdam-adjacent processors are validating supply chain chemical inventories for REACH compliance.
Brazil
Urban household convenience demand is driving instant flour adoption in São Paulo and Rio de Janeiro metropolitan markets. ANVISA food safety standards regulate domestic manufacturing and import flows. Paraná and Minas Gerais root supply zones are expanding pre-gelatinized production capacity for regional distribution.
Global Cassava Flour Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage zones. The supplier base separates into ISO-certified industrial processors serving institutional contracts and informal operators supplying domestic spot markets. Three archetypes dominate: integrated starch conglomerates with captive raw material supply, regional export specialists with dedicated tapioca product lines, and mid-scale African processors scaling toward contract eligibility. Competitive moves center on backward integration into Nigerian and Thai root zones and flash dryer capacity expansion to capture energy efficiency gains.
Within the integrated conglomerate tier, Ingredion Incorporated and Cargill Incorporated exemplify scale-driven positioning through upstream control over multi-continent raw material sourcing. Thai Wah Public Company Limited occupies a specialist position representing Southeast Asian export channel concentration. These three anchors illustrate how certification infrastructure and geographic footprint determine contract access across wholesale procurement channels.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Thai Wah Public Company Limited |
| Otto's Naturals |
| DADTCO Rivers Cassava Processing Company |
| Psaltry International |
| Roquette Frères |
| Emsland Group |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with Nigerian and Thai processors lock in both supply access and price visibility for European and North American buyers, insulating procurement teams from spot-market volatility while exposing them to natural gas cost pass-through clauses in mechanical drying operations.
Pricing Analysis
Certification level creates the primary spread between contract tiers, with ISO 22000-validated supply commanding substantial premiums over uncertified spot material. Three-tier pricing structure across premium organic, certified gluten-free, and conventional grades reflects input cost differentials and audit overhead. Pricing pressure stems from flash dryer energy intensity and mycotoxin remediation costs. Small-scale African processors exhibit highest price sensitivity, while integrated conglomerates absorb cost fluctuations through captive root supply.
Supply Chain Analysis
Nigeria and Thailand anchor global root supply, with Brazilian and Indonesian zones feeding regional demand. Processing draws from cassava tubers, natural gas for drying, and specialized flash dryer fabrication capacity concentrated in East Asian engineering clusters. Single-source vulnerability runs through Thai Wah and Ingredion export channels. Distribution runs through Rotterdam and Hamburg-adjacent consolidation hubs for EU REACH-compliant shipments, with Lagos-Ibadan corridor serving West African institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cassava flour market sits at a platform-economics inflection where REACH-aligned sustainability documentation interoperability is consolidating procurement around vertically integrated processors with validated chemical inventories.
For Market Incumbents: Fortify backward integration into Niger Delta and Southwest Nigerian root zones to secure feedstock against weather-linked volatility. Expand flash dryer capacity in Chonburi and Nakhon Ratchasima clusters to capture energy efficiency gains and reduce aflatoxin risk exposure. Prioritize ISO 22000 audit infrastructure to maintain contract eligibility as certification timelines compress. For New Entrants and Emerging Players: Differentiate on instant flour convenience positioning in São Paulo and Rio de Janeiro metropolitan markets where ANVISA compliance barriers are lower than EU REACH thresholds. Target Colombian and Brazilian urban households with sachet-format pre-gelatinized products. Pursue direct-to-consumer subscription models through specialty gluten-free portals to bypass wholesale channel consolidation. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale African processors scaling toward ISO 22000 contract eligibility under Nigeria's NAFDAC fortification mandates. Long-term viability hinges on sustainability audit infrastructure and captive organic root supply. Monitor ECHA processing aid residue evaluations as the inflection signal for supply chain chemical inventory validation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Flash Dryer Capacity Expansion | Reduces energy intensity and aflatoxin risk in Thai processing clusters. |
| Backward Integration into Nigerian Root Zones | Secures feedstock supply for Ingredion and Cargill multi-continent operations. |
| ISO 22000 Certification Investment | Unlocks European wholesale procurement contracts requiring validated hazard controls. |
| REACH-Aligned Sustainability Documentation | Enables EU market access as ECHA tightens processing aid residue thresholds. |
| Instant Flour Format Development | Captures convenience-driven demand in Brazilian and Colombian urban households. |
Methodological Framework
A spread of perspectives from plant managers at Thai and Nigerian processing facilities, procurement leads at North American commercial bakeries, regulatory affairs specialists navigating REACH and FDA frameworks, and distribution channel partners in European consolidation hubs converged on the working assumptions. Primary fieldwork combined with secondary validation from customs and trade data, SEC 10-K filings of listed starch processors, NAFDAC and Standards Organisation of Nigeria regulatory bulletins, and ECHA substance restriction updates. Bottom-up capacity and production estimates triangulated against top-down demand modeling across end-use segments.
Segmentation dimensions modeled include certification tier, product format, end-use application, and distribution channel across the analysis window. CAGRs derived from production capacity buildout trajectories, import flow analysis, and institutional procurement program scaling. Forecast inputs incorporated natural gas price sensitivity for mechanical drying operations and mycotoxin threshold evolution across FDA, EFSA, and NAFDAC jurisdictions.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal compliance enforcement or Nigerian food security program funding continuity would require recalibration. Forecasts reflect assumptions regarding flash dryer fabrication capacity availability and REACH substance restriction implementation timelines. Recalibration cycles align with material shifts in ECHA processing aid evaluations and NAFDAC fortification mandate revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Grain Analysis Market
Grains
Grain Silos Market
Grains
Tunisia Grain Market
Grains
Corn Flour Market
Grains
United States Gluten-Free Oats Market
Grains
South America Rice Market
Grains
South Africa Grain Market
Grains
Europe Maize Market
Grains
Corn Market
Grains
North America Wheat Protein Market
Grains
China Maize Market
Grains
United States Rice Market
Grains
Mexico Rice Market
Grains
Dried Spent Grain Market
Grains
Basmati Rice Market
Grains
Italy Rice Market