
 Africa Wheat Flour Market | 2026-2036
Africa Wheat Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Wheat Flour Market Outlook
Miller training capacity across East and West Africa is collapsing, constraining output quality at mid-scale facilities and widening the performance gap between artisanal and industrial operations. Bakhresa Group leverages integrated supply chains from grain import through retail distribution to sustain margin control across Tanzania and neighboring markets. Olam Agri anchors its position through port-advantaged milling infrastructure in Senegal and Nigeria, while Dangote Flour Mills competes on manufacturing scale in Lagos and northern Nigerian corridors.
Africa wheat flour denotes milled endosperm from Triticum aestivum, typically refined to 72-76% extraction rates for bread-making applications and fortified with iron, folic acid, and B vitamins under national food safety protocols. All-purpose flour dominates household procurement through informal retail channels, while bread flour captures expanding bakery sector volumes in Lagos, Cairo, and Nairobi. Wholesale distribution channels control the largest value flow to industrial bakeries and food processors, though supermarket penetration in South African and Moroccan cities is shifting packaging requirements toward branded consumer units.
Nigeria's National Agency for Food and Drug Administration and Control mandates micronutrient fortification compliance, while South Africa's Department of Health enforces wheat flour enrichment standards through port-of-entry inspections and domestic mill audits. Egypt's General Organization for Export and Import Control regulates wheat import quality and subsidized flour distribution to public bakeries. Stakeholders must monitor divergence between national fortification regimes and the fragmented enforcement capacity that creates uneven competitive obligations across milling operations.
Market Dynamics
National food fortification mandates are forcing widespread capital reinvestment across African milling operations as governments tighten micronutrient compliance protocols and inspection regimes.
Growth Catalysts
- NAFDAC fortification mandates:Nigeria's enforcement of iron, folic acid, and B vitamin standards in wheat flour creates guaranteed demand for compliant milling capacity and premix inputs.
- Artisanal bakery scaling:Urban bakeries in Lagos, Nairobi, and Cairo are expanding production lines and standardizing flour specifications to serve supermarket retail channels.
- Port-advantaged infrastructure:Milling facilities co-located with grain import terminals in Dakar, Lagos, and Mombasa capture logistics cost advantages over inland competitors.
Market Restraints
- Hard currency wheat procurement:Egyptian, Nigerian, and Kenyan millers face foreign exchange scarcity when securing Black Sea and North American grain shipments.
- Concentrated import dependency:Over 85 percent of African wheat supply originates from Russia, Ukraine, and EU exporters, exposing buyers to geopolitical supply shocks.
- Maize and cassava substitution:Price-sensitive consumers in East and West African markets pivot toward locally produced starch alternatives when wheat flour costs spike.
Strategic Opportunities
- Ethiopia milling capacity gaps:Africa's second-most populous nation maintains underdeveloped industrial flour production relative to its consumption base.
- Supermarket channel expansion:Branded consumer packaging formats are penetrating South African, Moroccan, and Egyptian urban retail beyond traditional wholesale sacks.
- Regional trade harmonization:AfCFTA tariff reductions on processed food cross-border movement enable integrated production networks across East African Community member states.
Industry Challenges
- Miller technician scarcity:Training programs across Tanzania, Uganda, and Ghana cannot supply sufficient qualified operators for mid-scale facility expansion.
- Laboratory certification backlogs:Premix validation and end-product testing queues at national food safety authorities delay product release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Wheat Flour Market |
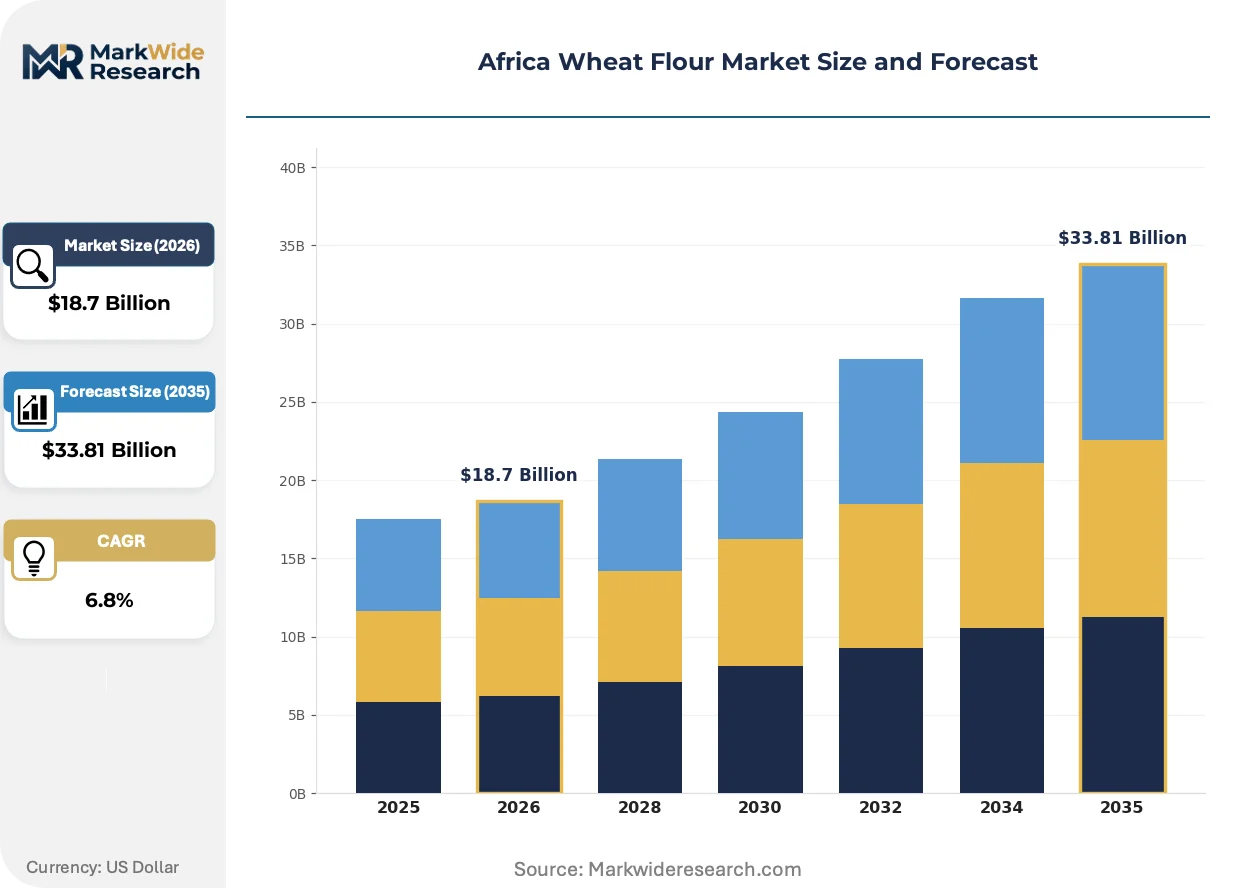
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Purpose Flour, Whole Wheat Flour, Bread Flour, Cake Flour End User: Households, Bakeries, Restaurants, Food Processing Distribution Channel: Supermarkets, Online Retail, Wholesale, Convenience Stores Packaging Type: Bags, Boxes, Bulk, Sachets |
| Companies Covered | Grands Moulins de Mauritanie, Gideon Milling, Bakhresa Group, Supreme Flour, Rotana Flour Mills, SOMDIAA SA, Olam Agri, Dangote Flour Mills, Honeywell Flour Mills, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Wheat Flour Market Strategic Shifts
Digital quality monitoring and automated blending systems are penetrating African milling floors as operators seek to reduce fortification variance and labor dependency.
Near-infrared spectroscopy for real-time protein and moisture analysis is fragmenting quality control workflows across Nigerian and Egyptian industrial mills. Mid-scale facilities in Nairobi and Dar es Salaam are adopting portable NIR units to bypass centralized laboratory bottlenecks. This instrumentation compression is fragmenting the traditional divide between artisanal visual inspection and capital-intensive laboratory verification.
South Africa's Department of Health has tightened wheat flour enrichment audit protocols through unannounced mill inspections and port-of-entry documentation checks. Non-compliant shipments now face detention and re-export requirements at Durban and Cape Town terminals. Industrial bakeries supplying supermarket chains are responding by demanding batch-level fortification certificates from milling suppliers.
Urban households in Lagos, Cairo, and Johannesburg are rotating toward pre-packaged bread and convenience flour formats away from bulk loose purchases at open-air markets. Supermarket penetration in Moroccan and Kenyan cities is accelerating branded unit sales with printed expiration dates and nutritional labeling. This channel migration is most visible among middle-income consumers in Accra, Dakar, and Tunis metropolitan zones.
Africa Wheat Flour Market Segmentation
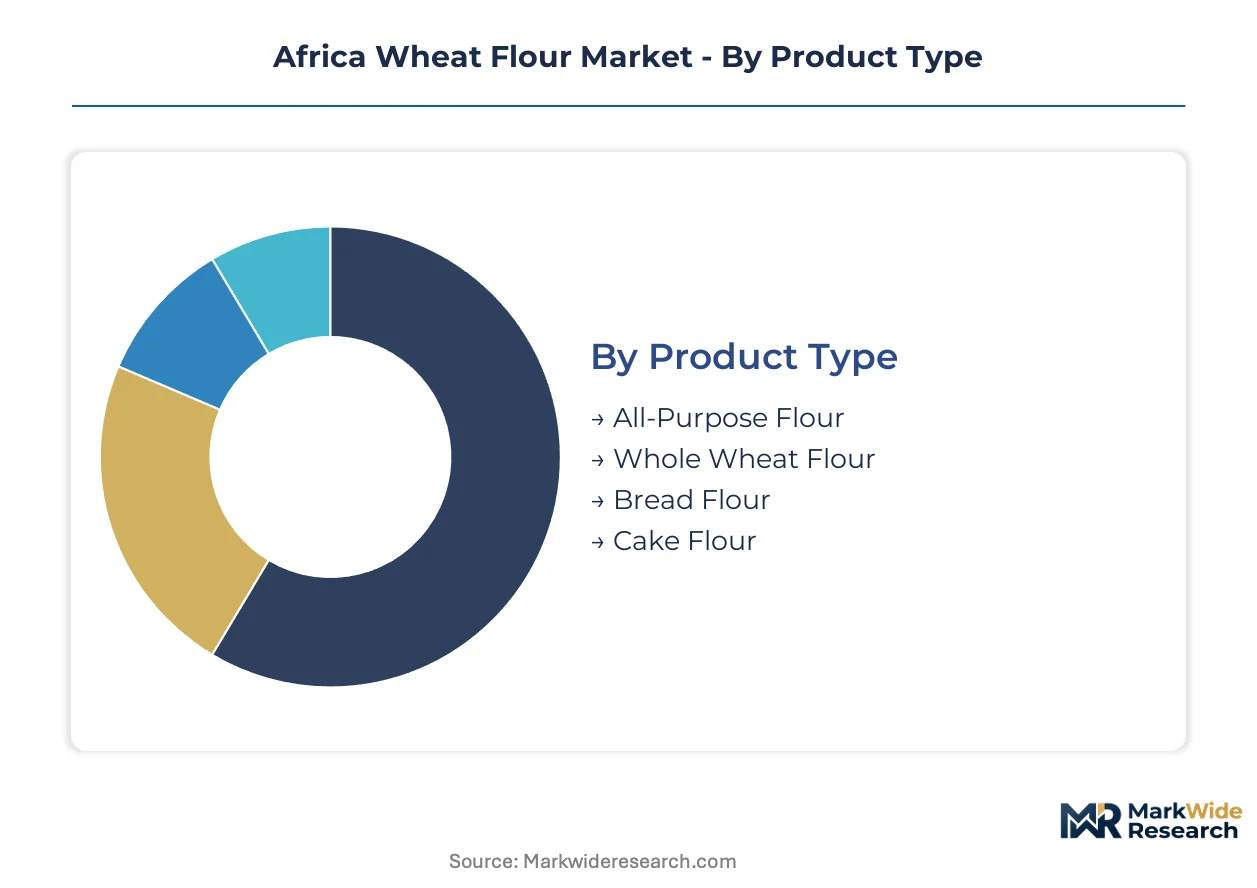
Segmentation reveals how substitution pressures and channel evolution are fragmenting demand across Africa's wheat flour landscape. Product specifications, end-use requirements, and packaging formats now determine competitive viability in ways that cut across traditional geographic boundaries.
Product Type:
Maize and cassava substitution threats concentrate most intensely on refined flour categories where price sensitivity dominates household purchasing decisions.
- All-Purpose Flour:Milled to 72-76% extraction rates with moderate protein content suitable for multiple applications. Demand concentrates in Lagos, Nairobi, and Cairo informal retail channels where households prioritize cost flexibility over specialized performance. Price spikes trigger immediate pivot toward locally available starch alternatives.
- Bread Flour:Higher protein formulations (11-14%) optimized for gluten development in commercial yeast breads. Artisanal bakeries across urban Nigeria and Kenya are standardizing procurement specifications to meet supermarket chain quality requirements. Fortification compliance mandates from NAFDAC and South Africa's Department of Health create technical barriers for non-compliant suppliers.
- Whole Wheat Flour:Retains bran and germ fractions with extraction rates exceeding 85%, delivering fiber and micronutrient density. Health-conscious middle-income consumers in Johannesburg, Casablanca, and Accra metropolitan zones.
- Cake Flour:Low-protein (8-10%), finely milled endosperm with chlorinated or heat-treated starch for tender crumb structure. Specialty baking segments and premium household occasions.
All-purpose flour anchors the volume base while bread flour gains share at the steepest rate.
End User:
Channel migration from open-air markets to formal retail is restructuring procurement relationships across customer categories.
- Households:The largest consumption base purchasing through informal retail, open-air markets, and emerging supermarket channels. Lagos, Cairo, and Kinshasa households demonstrate accelerating rotation toward pre-packaged formats with printed expiration dates and nutritional labeling as supermarket penetration deepens.
- Bakeries:Artisanal and industrial operations requiring consistent protein specifications and batch-level fortification certificates. Nigerian and South African supermarket chains now mandate supplier documentation proving iron, folic acid, and B vitamin compliance.
- Restaurants:Food service operators sourcing through wholesale distributors for chapati, pasta, and pastry applications. Urban hospitality clusters in Nairobi, Dakar, and Tunis.
- Food Processing:Manufacturers of noodles, biscuits, and prepared meals requiring customized flour blends with specified ash content and falling number parameters. Industrial zones in Egypt, Morocco, and South Africa.
Households retain the dominant volume position while bakeries are expanding most quickly as formal retail penetration accelerates.
Distribution Channel:
Logistics cost structures and payment terms differentiate channel viability across urban and peri-urban catchments.
- Supermarkets:Formal retail with branded unit packaging, barcode scanning, and cold-chain adjacent storage. South African chains Shoprite and Pick n Pay, plus Moroccan Marjane and Kenyan Naivas, are expanding private-label flour portfolios.
- Wholesale:Sack-format distribution to industrial bakeries, restaurants, and food processors controlling the largest value flow. Port-advantaged milling infrastructure in Dakar, Lagos, and Mombasa captures cost advantages over inland competitors through this channel.
- Convenience Stores:Small-format urban retail stocking 1-2kg bags for immediate household replenishment. Dense neighborhood networks in Cairo, Lagos, and Johannesburg townships.
- Online Retail:Emerging direct-to-home delivery platforms aggregating orders for scheduled distribution. Limited penetration concentrated in South African and Moroccan metropolitan zones with established e-commerce logistics.
Wholesale channels dominate current value flows while supermarkets are climbing the fastest as urban formalization proceeds.
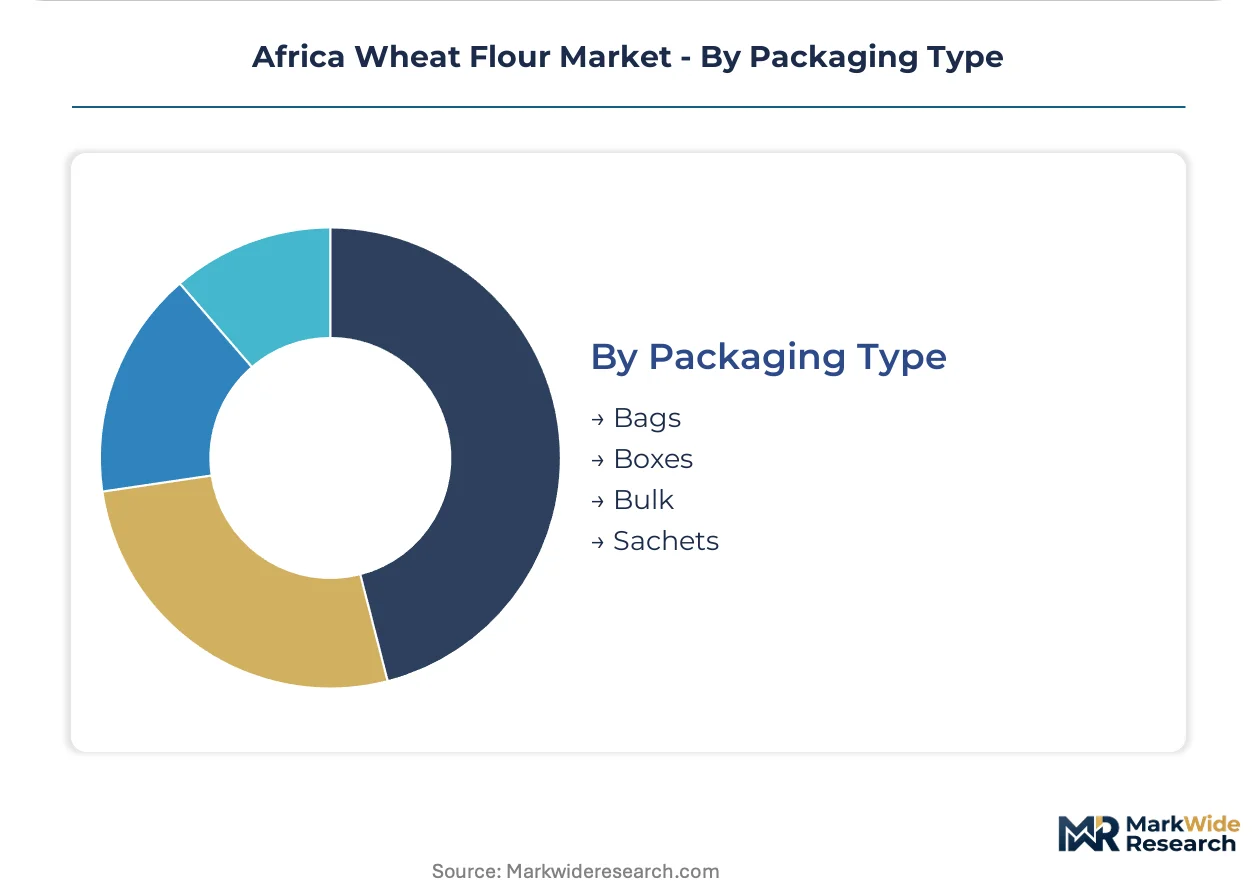
Packaging Type:
Packaging investment requirements now separate capitalized millers from informal competitors as fortification and traceability mandates tighten.
- Bags:Woven polypropylene or paper sacks of 25-50kg for wholesale and industrial bakery procurement. Standard format across Nigerian and Egyptian milling operations with printed batch codes for traceability compliance.
- Sachets:Small-format sealed pouches of 1-5kg targeting household trial and single-use occasions. Rapid adoption in Kenyan and Ghanaian urban supermarkets where refrigeration constraints favor frequent small purchases.
- Boxes:Cardboard containers for premium positioning and gift-oriented sales. Limited deployment in Moroccan and South African specialty retail.
- Bulk:Unpackaged loose flour dispensed at open-air markets and informal mills. Shrinking share as national food safety authorities enforce packaged product standards.
Bags retain the volume anchor position while sachets are gaining share fastest through supermarket channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egyptian millers command pricing power through subsidized wheat procurement programs that Nigerian and Kenyan operators cannot replicate, creating a structural cost advantage at Mediterranean ports versus Atlantic and Indian Ocean supply chains.
Nigeria
Lagos and Kano industrial corridors drive bread flour consumption as artisanal bakeries scale to serve Shoprite and SPAR supermarket chains. NAFDAC fortification mandates enforce iron, folic acid, and B vitamin standards through mill audits and product detention protocols. Dangote Flour Mills anchors manufacturing scale across Lagos and northern Nigerian corridors, capturing wholesale channel dominance.
Egypt
Cairo and Alexandria public bakery networks consume subsidized flour volumes exceeding any African peer market. The General Organization for Export and Import Control regulates wheat import quality and subsidized distribution channels through port-of-entry inspections. Port-advantaged milling infrastructure at Alexandria and Damietta terminals captures Black Sea grain logistics efficiencies.
South Africa
Johannesburg and Cape Town metropolitan zones accelerate branded consumer packaging rotation toward supermarket retail. The Department of Health enforces wheat flour enrichment standards through unannounced mill inspections and port documentation checks at Durban and Cape Town terminals. Shoprite and Pick n Pay private-label flour portfolios expand shelf-space allocation in formal retail channels.
Kenya
Nairobi and Mombasa urban bakeries standardize procurement specifications to meet Naivas and Quick Mart chain quality requirements. National food fortification mandates reshape milling standards through premix compliance protocols. Mombasa port-advantaged milling infrastructure captures logistics cost advantages over inland Ugandan and Tanzanian competitors.
Ethiopia
Addis Ababa and surrounding highland population centers exhibit underdeveloped industrial flour production relative to consumption base scale. The Ethiopian Food and Drug Authority implements emerging food safety protocols with fragmented laboratory certification capacity. Mid-scale facility expansion across Oromia and Amhara regions faces miller technician training program shortfalls.
Africa Wheat Flour Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Africa's wheat flour landscape. Integrated supply chain operators capture margin control through grain import-to-retail coordination, while port-advantaged specialists dominate logistics-sensitive wholesale channels. Three archetypes define competitive positioning: multinational agribusiness conglomerates with integrated trading and milling operations, regional family-owned groups with backward integration into grain procurement, and national-scale industrial millers competing on manufacturing throughput. Capacity expansion and strategic port infrastructure co-location represent the dominant competitive moves, with players securing terminal-adjacent milling assets to reduce landed cost structures.
Among integrated African milling groups, Bakhresa Group exemplifies supply chain integration from grain import through retail distribution, while Olam Agri occupies a position anchored through port-advantaged milling infrastructure. Dangote Flour Mills represents the scale-driven national industrial archetype competing on manufacturing throughput in Nigerian metropolitan corridors.
| Leading Market Players |
|---|
| Grands Moulins de Mauritanie |
| Gideon Milling |
| Bakhresa Group |
| Supreme Flour |
| Rotana Flour Mills |
| SOMDIAA SA |
| Olam Agri |
| Dangote Flour Mills |
| Honeywell Flour Mills |
| Others |
Value Chain & Pricing Dynamics
NAFDAC fortification mandates in Nigeria gate both supply qualification and price differentiation simultaneously, as compliant mills command premium positioning while non-compliant operators face detention and re-export penalties. This regulatory architecture compresses margins for informal processors while rewarding capitalized facilities with batch-level certification capabilities.
Pricing Analysis
Egyptian millers maintain 15-20% cost advantages over Nigerian counterparts due to subsidized wheat procurement programs. Three-tier pricing structure across premium, standard, and economy levels reflects fortification compliance status, protein specification, and packaging format. Cost compression in the economy tier is intensifying because maize and cassava substitution accelerates during wheat price spikes. Household purchasers in informal Lagos and Kinshasa channels exhibit highest price sensitivity, while industrial bakeries supplying Shoprite and Naivas chains prioritize specification consistency over unit cost.
Supply Chain Analysis
Russia, Ukraine, and EU member states anchor over 85% of African wheat supply, with Black Sea port disruptions immediately transmitting to Mombasa and Lagos landed costs. Egyptian, Nigerian, and Kenyan millers draw from North American and Argentine alternative origins when geopolitical shocks constrain traditional flows. Single-source vulnerability concentrates in Russian grain dominance, with limited near-term diversification pathways. Distribution runs through port-advantaged milling clusters at Dakar, Lagos, Mombasa, and Alexandria terminals, feeding wholesale sack-format channels to industrial bakeries and informal retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against cassava and maize flour alternatives that capture price-sensitive household volumes during wheat cost spikes. Incumbents must fortify supply chain control while entrants exploit service-layer gaps in Ethiopia and supermarket-channel packaging.
For Market Incumbents: Compound port-advantaged infrastructure investments at Mombasa, Lagos, and Dakar terminals to sustain logistics cost leadership against inland competitors. Deepen backward integration into grain procurement through long-term Black Sea offtake agreements, insulating margin structures from currency volatility. Defensive capacity expansion should prioritize Ethiopia, where industrial milling capacity lags population scale. For New Entrants and Emerging Players: Miller technician training services represent an under-served layer where incumbents under-invest, creating white-space for specialized facility staffing solutions across Tanzania, Uganda, and Ghana. Target Ethiopia's Oromia and Amhara regions for mid-scale facility deployment, leveraging fragmented laboratory certification capacity to capture regulatory compliance premiums. Go-to-market execution should anchor through supermarket private-label partnerships in Nairobi and Accra, bypassing wholesale channel dominance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fortification-compliant milling capacity, favoring scaled operators with premix validation infrastructure. Long-term viability hinges on acquisition targets with terminal-adjacent assets and existing NAFDAC or South African Department of Health audit compliance. Watch AfCFTA tariff implementation velocity as the signal indicating cross-border production network feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Port-Adjacent Capacity Expansion | Secures logistics cost advantages at Mombasa and Lagos terminals against inland competitors. |
| Backward Integration into Grain Procurement | Captures margin control through Black Sea and North American long-term supply agreements. |
| Fortification Compliance Certification | Enables NAFDAC and South African Department of Health audit passage for supermarket channel access. |
| Miller Technician Training Programs | Addresses Tanzania and Uganda facility staffing constraints constraining mid-scale output quality. |
| Supermarket Private-Label Partnerships | Penetrates Shoprite, Naivas, and Marjane branded packaging requirements in urban retail. |
Study Parameters
Cross-validation between primary interviews with milling operations directors, grain procurement managers, and food safety authority inspectors anchors the qualitative findings. Secondary validation draws from customs and trade flow databases, national food fortification program documentation, and supermarket retail audit data. Bottom-up facility capacity assessments triangulate against top-down consumption estimates derived from population dietary surveys and bakery sector scaling indicators.
Sensitivity analysis frames the analytical approach across the projection horizon, modeling volume and value outputs through product type, end-use application, distribution channel, and regional regulatory cluster dimensions. CAGRs derive from segmented growth rate blending with macroeconomic drivers including urbanization velocity, foreign exchange availability, and fortification mandate enforcement intensity. Wheat import dependency ratios and substitution elasticity parameters inform scenario-weighted projections.
Underlying assumptions cover sustained NAFDAC and Egyptian General Organization for Export and Import Control enforcement trajectories, with deviation risk concentrated in geopolitical supply shocks and currency volatility spikes. Forecasts reflect these conditions with acknowledgment that maize substitution acceleration or laboratory certification backlogs could materially revise trajectory. Recalibration cycles align with material shifts in AfCFTA implementation, Black Sea trade flows, and national fortification audit protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Grain Silos and Storage System Market
Grains
Corn Silage Market
Grains
South Africa Maize Market
Grains
Asia Pacific Maize Market
Grains
Italy Rice Market
Grains
Global Cassava Flour Market
Grains
Barley Market
Grains
Global Quinoa Market
Grains
South Africa Grain Market
Grains
United States Maize Market
Grains
Brown Rice Market
Grains
Precooked Flour Market
Grains
Global Oats Market
Grains
Global Flour Market
Grains
Millets Market
Grains
Oat Bran Market