
 Heritage Grain Market | 2026-2036
Heritage Grain Market Size, Share, and Industry Trends Forecast 2026-2036
Heritage Grain Market Foresight
Buyer concentration in the Heritage Grain Market is shifting as regional artisan bakeries consolidate procurement through cooperative purchasing agreements while direct-to-restaurant channels fragment across farm-to-table networks. Anson Mills anchors its position through controlled propagation of antebellum grain varieties across coastal Carolina. Bob's Red Mill Natural Foods, Inc. leverages vertically integrated milling infrastructure to sustain supply consistency for retail and foodservice accounts. King Arthur Baking Company differentiates through certified organic heritage wheat sourcing and education-driven consumer engagement.
Heritage grains comprise landrace cereal cultivars predating the Green Revolution, typically exhibiting lower gluten indices, higher bran retention, and distinctive amino acid profiles preserved through open-pollinated reproduction. Their commercial purpose centers on flavor differentiation, nutritional density, and biodiversity conservation in food systems. Wheat dominates product type volumes due to established milling infrastructure and baker familiarity, while rye experiences accelerated demand from craft distilling and Nordic-style baking trends. Health food as an end use captures expanding margin pools as functional nutrition claims drive premium positioning, whereas animal feed remains a volume-stable baseline with thinner returns.
The USDA administers organic certification standards that govern heritage grain labeling, while FDA food safety regulations shape processing facility compliance and interstate commerce protocols. State departments of agriculture in Montana, North Dakota, and Kansas operate seed purity programs that protect heritage variety integrity and prevent varietal contamination. Stakeholders must monitor evolving definitions of "heritage" and "heirloom" as classification ambiguity creates both market access risks and premium capture opportunities across distribution channels.
Market Dynamics
Artisan bakery consolidation through cooperative purchasing agreements is compressing price discovery windows while fragmenting direct-to-restaurant procurement across farm-to-table networks, fundamentally altering how heritage grain volumes flow from field to mill.
Growth Catalysts
- USDA Organic certification expansion:The USDA Organic seal creates premium price capture for heritage wheat and rye, driving farmer conversion to certified acreage in the Pacific Northwest.
- Craft distilling demand surge:Heritage rye procurement volumes accelerate as American craft distillers seek flavor differentiation for bourbon and whiskey production.
- Portland-Seattle processing hub concentration:Heritage grain cooperatives cluster around these Pacific Northwest cities, reducing logistics costs for regional artisan bakers.
Market Restraints
- Landrace yield volatility:Open-pollinated heritage wheat varieties produce 30-50% lower bushel-per-acre yields than modern hybrids, constraining supply scalability.
- Montana seed purity program compliance:State-level varietal contamination prevention rules impose testing costs and isolation distances that limit small-farm participation.
- Gluten index limitations:Lower gluten content in heritage wheat restricts application in industrial bread manufacturing optimized for high-volume production.
Strategic Opportunities
- Functional nutrition positioning:Distinctive amino acid profiles in heritage grains enable health food manufacturers to command premium shelf space with biodiversity conservation claims.
- Nordic-style baking trend diffusion:Dense rye bread formats popularized by Scandinavian culinary influence create new formulation demand in North American artisan bakeries.
- State grain identity preservation laws:Kansas and North Dakota seed integrity frameworks offer regulatory tailwinds for heritage variety commercialization through certified sourcing programs.
Industry Challenges
- Miller skill scarcity:Heritage grain processing requires stone milling expertise and varietal-specific tempering knowledge that conventional mill operators lack.
- Certification timeline compression:USDA Organic transition periods and state seed purity verification create 24-36 month gaps between planting decisions and market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heritage Grain Market |
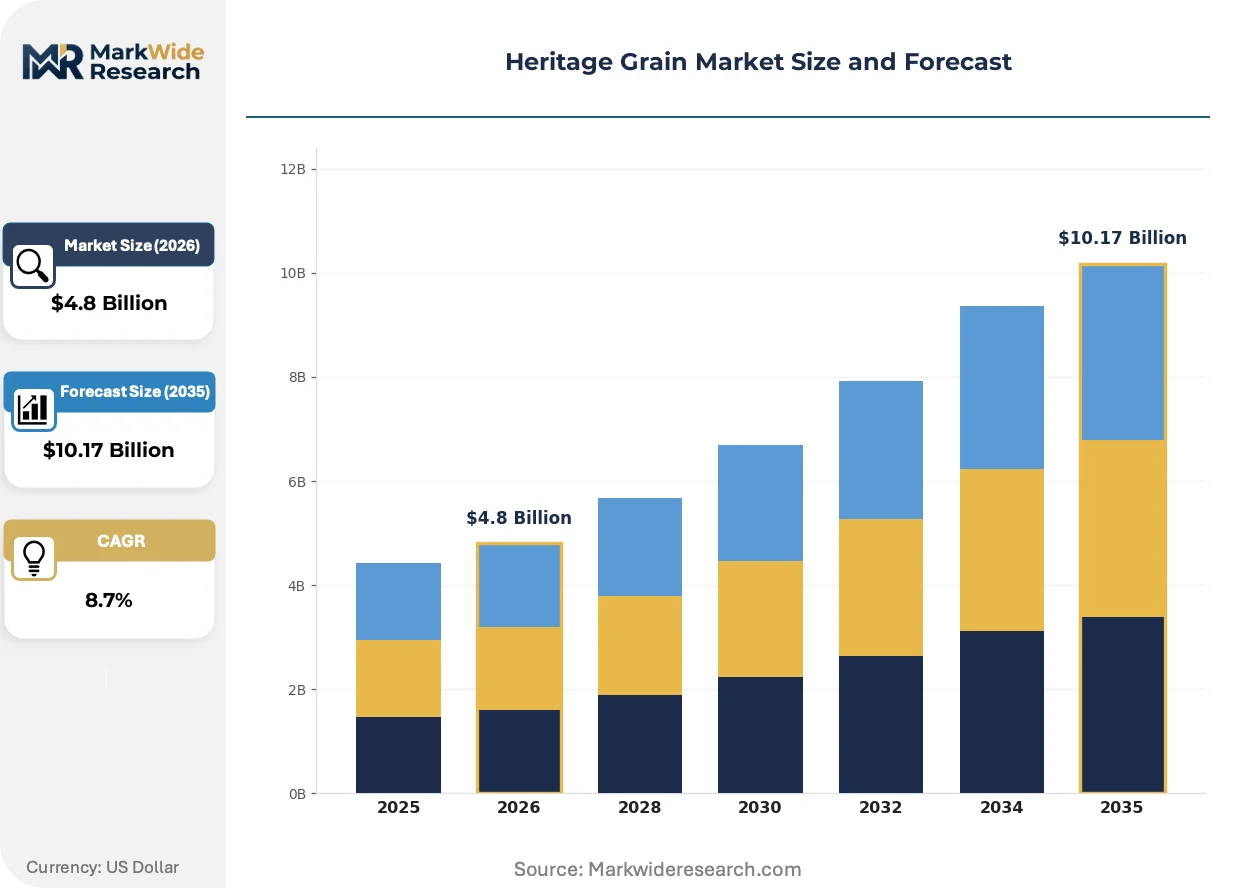
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat, Barley, Rye, Oats End Use: Baking, Brewing, Animal Feed, Health Food Distribution Channel: Retail, Wholesale, Online, Direct Sales Origin: Heritage Farms, Organic Sources, Traditional Varieties, Others |
| Companies Covered | King Arthur Baking Company, Anson Mills, Bob’s Red Mill Natural Foods, Inc., Hayden Flour Mills, To Your Health Sprouted Flour Co., Arrowhead Mills, Inc., Grain Millers, Inc., Bluebird Grain Farms, Shiloh Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heritage Grain Market Shifts & Advancements
Three intersecting forces are reconfiguring heritage grain value chains: distributed processing technology, evolving organic certification scope, and procurement model fragmentation between cooperative and direct channels.
Small-scale mobile milling units are modularizing heritage grain processing infrastructure. Regional cooperatives in Oregon and Washington deploy trailer-mounted stone mills to farm gate locations, eliminating consolidation transport costs. This distributed model is modularizing the traditional centralized mill economics that previously disadvantaged low-volume heritage producers.
REACH chemical registration requirements in Europe are tightening pesticide residue thresholds for imported grain. The European Chemicals Agency framework now classifies certain conventional fungicides as Substances of Very High Concern, blocking grain lots from entry. North American heritage grain exporters to EU markets are accelerating organic transition to bypass these restrictions.
Direct-to-restaurant sourcing contracts are displacing distributor-mediated procurement for heritage wheat and rye. Farm-to-table networks in California and New York establish fixed-price seasonal agreements that bypass commodity pricing volatility. This channel shift concentrates margin capture with coastal urban restaurant clusters while reducing price transparency for remaining distributor-dependent buyers.
Heritage Grain Market Segmentation
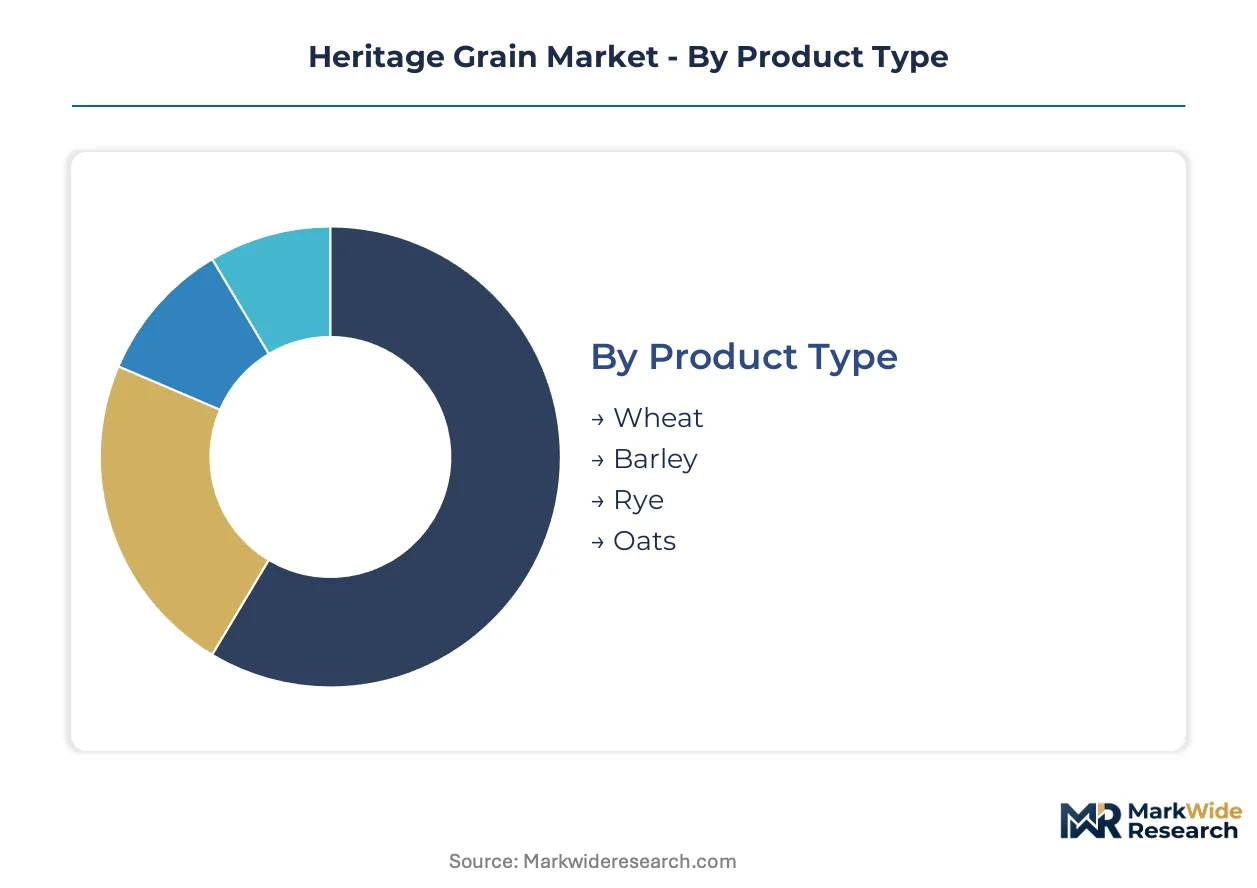
Heritage grain procurement patterns diverge sharply across product types and end-use applications, with milling infrastructure constraints and certification requirements fragmenting supply routes. Understanding these segment boundaries clarifies where margin pools concentrate and which channels offer scalable entry points for new suppliers.
Product Type:
Upgrade cycles in milling equipment and bakery formulation knowledge determine which landrace cereals gain commercial traction, with infrastructure investment lagging behind varietal rediscovery.
- Wheat:Landrace wheat cultivars predating the Green Revolution exhibit lower gluten indices and higher bran retention than modern hybrids. Demand concentrates in Pacific Northwest artisan bakeries where stone milling infrastructure supports varietal-specific tempering requirements; supply scalability remains constrained by 30-50% yield penalties versus commercial hybrids.
- Rye:Open-pollinated rye varieties deliver distinctive amino acid profiles and fermentable sugars prized in craft distilling applications. Procurement volumes from American craft distillers are climbing fastest as bourbon and whiskey producers seek flavor differentiation; Nordic-style baking trends in coastal urban markets amplify bakery demand.
- Barley:Heritage malting barley supplies craft brewing operations seeking terroir-specific flavor signatures for farmhouse ale styles.
- Oats:Landrace oat varieties serve health food manufacturers targeting beta-glucan content claims and biodiversity conservation narratives.
Volume placements concentrate in wheat; the faster expansion belongs to rye.
End Use:
Cost tier differentiation separates commodity-scale applications from premium-positioned segments, with certification requirements widening the gap between baseline feed uses and certified organic food channels.
- Baking:Artisan bakeries drive procurement through cooperative purchasing agreements that compress price discovery windows while securing consistent supply. Portland and Seattle processing hubs anchor regional demand; gluten index limitations restrict penetration into industrial bread manufacturing optimized for high-volume production.
- Brewing:Craft distillers and farmhouse ale producers seek heritage grains for fermentable sugar profiles and terroir differentiation. Direct-to-producer contracts are displacing distributor-mediated procurement in California and New York; fixed-price seasonal agreements bypass commodity pricing volatility.
- Animal Feed:Volume-stable baseline demand with thinner margins, serving as an outlet for lots failing food-grade certification standards.
- Health Food:Functional nutrition claims enable premium shelf space capture through distinctive amino acid profiles and biodiversity conservation positioning.
Margin capture concentrates in health food; brewing applications are expanding most quickly.
Distribution Channel:
Customer type fragmentation between consolidated cooperative buyers and dispersed farm-to-table networks reshapes how heritage grain volumes flow from field to mill.
- Retail:Bob's Red Mill Natural Foods and King Arthur Baking Company sustain supply consistency through vertically integrated milling infrastructure. Certified organic heritage wheat sourcing with education-driven consumer engagement commands premium positioning; shelf space competition intensifies as mainstream brands introduce heritage-labeled lines.
- Direct Sales:Farm-to-table networks establish fixed-price seasonal agreements that concentrate margin capture with coastal urban restaurant clusters. California and New York restaurant procurement bypasses distributor price transparency; Anson Mills anchors this channel through controlled propagation of antebellum grain varieties.
- Wholesale:Consolidated procurement through regional cooperatives reduces logistics costs for Pacific Northwest artisan bakeries.
- Online:Specialty food manufacturers and home bakers access small-lot heritage grains through direct-to-consumer platforms.
Procurement volume concentrates in wholesale; direct sales channels are gaining share fastest.
Origin:
Supply concentration around certification-validated sourcing programs determines market access, with state-level seed purity frameworks creating regulatory moats for verified heritage varieties.
- Heritage Farms:Designated landrace preservation operations maintain open-pollinated reproduction through isolation distances and varietal contamination prevention protocols. Montana, North Dakota, and Kansas seed purity programs protect integrity; testing costs and isolation requirements limit small-farm participation.
- Organic Sources:USDA Organic certification creates premium price capture and drives farmer conversion to certified acreage in the Pacific Northwest. 24-36 month transition gaps between planting decisions and market access compress farmer cash flow; ECHA REACH requirements accelerate organic transition for EU-bound exports.
- Traditional Varieties:Generational seed-saving networks supply regionally adapted cultivars with established local milling relationships.
- Others:Research institution germplasm collections and seed bank distributions support varietal rediscovery and commercial propagation.
Certified volume concentrates in organic sources; heritage farms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan bakery procurement concentrates in the United States, where cooperative purchasing agreements and craft distilling demand anchor volume flows. Regulatory frameworks governing organic certification and seed purity vary significantly across producing regions.
United States
Cooperative purchasing agreements among Pacific Northwest artisan bakeries compress price discovery windows while securing consistent supply. USDA Organic certification requirements and state-level grain identity preservation laws in Montana, North Dakota, and Kansas shape market access protocols. Portland and Seattle processing hubs anchor regional demand clusters where heritage grain cooperatives reduce logistics costs.
Canada
Craft brewing operations in Ontario and Quebec seek heritage malting barley for farmhouse ale styles with terroir-specific flavor signatures. Health Canada and the Canadian Food Inspection Agency administer organic certification equivalency agreements with USDA standards. Prairie Provinces heritage grain networks supply regional artisan bakeries through direct-to-restaurant contracts.
Germany
Nordic-style baking trends drive dense rye bread demand among coastal urban consumers seeking Scandinavian culinary formats. ECHA REACH chemical registration requirements tighten pesticide residue thresholds for imported grain, blocking conventional fungicide-treated lots. Bavaria and North Rhine-Westphalia anchor processing infrastructure for heritage variety distribution.
France
Artisan bakers in Île-de-France and Auvergne-Rhône-Alpes pursue landrace wheat for flavor differentiation in traditional baguette formulations. ANSM and DGCCRF oversee food safety compliance while EU organic regulations govern certification scope. Regional milling cooperatives in Provence-Alpes-Côte d'Azur specialize in stone-ground heritage grain processing.
United Kingdom
London and Southeast England restaurant clusters establish fixed-price seasonal agreements that bypass commodity pricing volatility through farm-to-table networks. Food Standards Agency regulations align with EU organic standards post-Brexit through retained law mechanisms. Midlands and North England heritage grain preservation societies maintain generational seed-saving networks for regionally adapted cultivars.
Heritage Grain Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cooperative sourcing and mobile milling infrastructure to capture margin from fragmented procurement channels. Market structure tilts toward vertical integration among retail-facing millers and geographic specialization among regional cooperatives. Three archetypes dominate: heritage variety propagators, vertically integrated millers, and cooperative procurement aggregators. Competitive moves concentrate on backward integration into controlled propagation and strategic partnerships with artisan bakery networks.
Within the heritage variety propagator archetype, Anson Mills anchors position through controlled propagation of antebellum grain varieties. Among vertically integrated millers, Bob's Red Mill Natural Foods, Inc. exemplifies supply consistency through captive milling infrastructure. King Arthur Baking Company occupies a position in the education-driven engagement tier, differentiating through certified organic heritage wheat sourcing and consumer-facing content programs.
| Leading Market Players |
|---|
| King Arthur Baking Company |
| Anson Mills |
| Bob's Red Mill Natural Foods, Inc. |
| Hayden Flour Mills |
| To Your Health Sprouted Flour Co. |
| Arrowhead Mills, Inc. |
| Grain Millers, Inc. |
| Bluebird Grain Farms |
| Shiloh Farms |
| Others |
Supply & Pricing Matrix
Artisan bakery cooperative purchasing agreements in the Pacific Northwest are compressing price discovery windows and forcing suppliers to choose between volume commitments at thinner margins or fragmented direct-to-restaurant channels with higher per-unit returns but greater logistics complexity.
Pricing Analysis
Volume placements in animal feed capture baseline returns with minimal premium, while certified organic heritage wheat and rye destined for health food and craft distilling applications command substantial markups. Price differentiation rests on USDA Organic certification status and varietal purity verification under state seed integrity programs. Pricing pressure stems from landrace yield penalties that elevate per-bushel production costs relative to commercial hybrids. Industrial bread manufacturers exhibit highest price sensitivity due to gluten index limitations that prevent heritage wheat substitution, whereas craft distillers and Nordic-style bakeries absorb premiums for flavor differentiation.
Supply Chain Analysis
Dual-sourcing requirements from Portland and Seattle processing hubs mandate that artisan bakeries qualify multiple heritage grain cooperatives to mitigate varietal contamination risks and ensure consistent stone-milled supply. Geographic concentration centers on the United States, with Pacific Northwest clusters and Carolina coastal propagation operations anchoring North American supply. Raw material dependencies include open-pollinated seed stock, isolation-distance acreage, and skilled stone mill operators. Supply chain risk manifests through Montana seed purity program compliance costs that exclude small-farm participation. Distribution runs through cooperative wholesale channels for volume accounts and direct farm-to-table contracts for coastal urban restaurant clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from cooperative purchasing agreements and certification timeline compression is forcing sub-scale heritage grain propagators and single-channel millers toward exit or acquisition, concentrating margin capture with vertically integrated operators possessing captive sourcing and multi-channel distribution.
For Market Incumbents: Lock in varietal integrity through controlled propagation programs that secure antebellum landrace genetics against contamination risks from neighboring commercial hybrid operations. Expand stone milling capacity within Pacific Northwest processing hubs to capture cooperative procurement volumes before mobile milling units fragment the infrastructure advantage. Certification investment in simultaneous USDA Organic and state seed purity compliance creates regulatory moats against emerging entrants lacking 24-36 month transition capital. For New Entrants and Emerging Players: USDA Organic certification expansion in the Pacific Northwest opens a window for certified acreage conversion targeting craft distilling procurement with heritage rye supply gaps. White-space targets include mobile milling services for farm-gate processing that eliminates consolidation transport costs for isolated heritage farms, and direct-to-restaurant contracts in California and New York that bypass established distributor relationships. Kansas and North Dakota grain identity preservation laws offer the most penetrable regulatory pathway for certified sourcing program entry. For Investors and Strategic Acquirers: The window for entry favors vertically integrated millers with captive heritage variety propagation and established artisan bakery network relationships, positioned to capture margin from cooperative procurement consolidation. Acquisition targets should exhibit controlled germplasm collections, Pacific Northwest or Carolina coastal processing infrastructure, and existing USDA Organic certification. The signal to watch is craft distilling procurement volume acceleration as bourbon and whiskey producers expand heritage rye sourcing commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled Propagation Program | Anson Mills demonstrates how antebellum variety preservation secures supply exclusivity against varietal contamination. |
| Mobile Milling Infrastructure | Trailer-mounted stone mills in Oregon and Washington eliminate transport costs that previously disadvantaged low-volume producers. |
| Dual Certification Investment | Simultaneous USDA Organic and state seed purity compliance creates regulatory barriers against undercapitalized entrants. |
| Direct-to-Restaurant Contracts | Fixed-price seasonal agreements in California and New York bypass commodity volatility while concentrating urban margin capture. |
| Cooperative Procurement Aggregation | Regional heritage grain cooperatives around Portland and Seattle reduce logistics costs and compress price discovery for artisan bakeries. |
Research Methodology
Document review covered USDA organic certification databases, state seed purity program filings in Montana and North Dakota, and ECHA REACH chemical registration frameworks, complemented by interviews with heritage grain cooperative managers, stone mill operators, artisan bakery procurement leads, and craft distilling supply chain directors. Secondary validation drew from FDA food safety compliance records, state department of agriculture varietal integrity reports, and Pacific Northwest logistics cost studies. Bottom-up volume modeling triangulated against top-down market sizing across product type and end-use segments.
Cross-referencing historical procurement patterns with expert panel input on cooperative purchasing trends and craft distilling demand trajectories shaped the analytical framework across the analysis window. Segmentation dimensions modeled include landrace cereal type, end-use application, distribution channel structure, and origin certification status. CAGRs were derived from trend extrapolation calibrated against documented conversion rates to certified organic acreage and mobile milling deployment timelines.
The model assumes a particular technology adoption path for distributed stone milling infrastructure; alternative pathways for automated tempering systems or hybrid varietal development would alter the outlook for supply scalability and price compression. Forecasts reflect assumptions regarding cooperative consolidation velocity, craft distilling procurement expansion, and ECHA REACH enforcement stringency for EU-bound exports. A model refresh is warranted upon material change in USDA Organic certification timelines or state-level seed purity program scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Grain Roller Market
Grains
Global Maize Market
Grains
Organic Wheat Flour Market
Grains
Organic Rice Market
Grains
Spain Rice Market
Grains
Green Pea Grits Market
Grains
Barley Market
Grains
Bangladesh Rice Market
Grains
Organic Rice Flour Market
Grains
Global Quinoa Market
Grains
00 Flour Market
Grains
Egypt Rice Market
Grains
North America Pulses Market
Grains
Rolled Oats Market
Grains
China Rice Market
Grains
Low Fat Rice Market