
 Cambodia Agricultural Machinery Market | 2026-2036
Cambodia Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Cambodia Agricultural Machinery Market Outlook
The dealer network for farm equipment is narrowing across Cambodia's northwestern provinces. Kubota Corporation leverages its long-standing Phnom Penh distribution hub to control spare parts availability. Mahindra and Mahindra Ltd. anchors its position through affordable tractor financing tailored to smallholder cooperatives. Deere & Company competes by specializing in high-horsepower harvesters for large-scale rice contractors.
Cambodia agricultural machinery encompasses powered and non-powered equipment engineered for soil tillage, planting, irrigation, crop maintenance, and harvest operations, typically featuring diesel engines rated between 15 and 75 horsepower and steel-framed implements designed for paddy field conditions. Tractors dominate unit sales as the foundational platform for tillage and transport, while harvesters command premium pricing due to seasonal labor scarcity during peak rice collection. Precision agriculture technology remains nascent but attracts government pilot funding, whereas traditional equipment still sustains volume among subsistence farmers in remote provinces.
Cambodia's Ministry of Agriculture, Forestry and Fisheries and the country's national standards body shape import compliance through emissions testing and safety certification requirements for all mechanized farm equipment. The General Department of Customs and Excise enforces tariff classifications that favor ASEAN-origin machinery under regional trade agreements. Stakeholders must monitor whether draft regulations on agricultural diesel subsidies survive legislative review, as this policy signal will determine fleet replacement timing for Cambodia's contractor segment.
Market Dynamics
Cambodia's Ministry of Agriculture, Forestry and Fisheries has tightened diesel engine emissions protocols, forcing distributors to purge older inventory and redirect procurement toward cleaner-certified equipment. This regulatory compression is accelerating fleet turnover among commercial rice contractors in the Tonle Sap lowlands and Mekong Delta corridor.
Growth Catalysts
- Labor scarcity during peak harvest windows:Rice farming cooperatives in Battambang and Siem Reap provinces are mechanizing planting and harvesting operations to compensate for seasonal workforce gaps. This structural shortage sustains demand for automated transplanting and combine harvesting systems.
- ASEAN trade agreement tariff preferences:The General Department of Customs and Excise enforces favorable tariff classifications for machinery originating within the regional bloc, lowering landed costs for Thai and Vietnamese equipment entering Cambodian distribution channels.
- Subsidized credit lines for cooperative formation:Agricultural development banks are extending preferential financing to smallholder groups pooling resources for shared tractor and harvester fleets, expanding addressable demand beyond individual farm capital constraints.
Market Restraints
- Import compliance cost escalation:Safety certification and emissions testing requirements administered by the national standards body add procedural delays and third-party verification expenses to every equipment shipment.
- Spare parts supply concentration:Critical engine components and hydraulic assemblies flow through a narrow channel of Phnom Penh-based distributors, creating vulnerability to stockout risk during peak agricultural seasons.
- Manual cultivation persistence:Subsistence farmers in remote northeastern provinces continue relying on animal traction and hand tools, capping penetration rates for mechanized equipment in peripheral geographies.
Strategic Opportunities
- Precision agriculture pilot funding:Government grants for GPS-guided tillage and variable-rate input application are creating early-adopter revenue pools among large-scale contractors seeking yield optimization.
- Equipment-as-a-service models:Leasing structures with bundled maintenance are penetrating smallholder cooperatives previously excluded by upfront capital barriers, shifting transaction economics from asset ownership to operational expenditure.
- Cross-border service corridors:Thai and Vietnamese technical service networks are extending mobile repair capabilities into Cambodia's northwestern provinces, addressing historical after-sales coverage gaps.
Industry Challenges
- Certification timeline compression:Tighter import inspection windows are forcing distributors to pre-position inventory before planting seasons, straining working capital and warehouse capacity.
- Technical operator training deficits:Harvester and precision equipment deployment outpaces qualified mechanic availability, forcing contractors to rely on manufacturer fly-in support with associated downtime costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cambodia Agricultural Machinery Market |
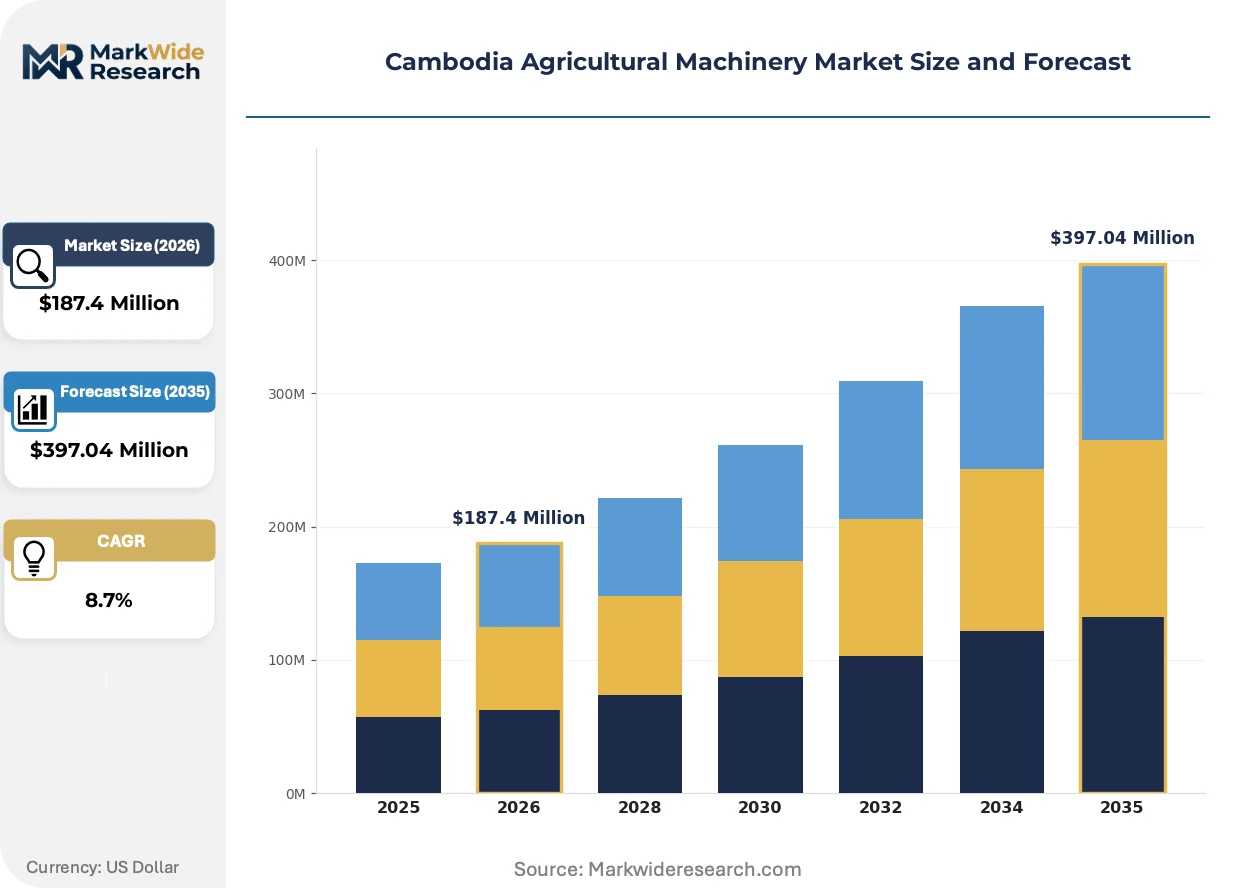
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Plows, Harvesters, tillers Application: Irrigation, Soil Preparation, Crop Maintenance, Pest Control End User: Farmers, Cooperatives, Agricultural Contractors, Government Agencies Technology: Traditional, Semi-Automated, Fully Automated, Precision Agriculture |
| Companies Covered | Mahindra and Mahindra Ltd., AGCO Corporation, Kubota Corporation, CLAAS KGaA mbH, Escorts Limited, Deere & Company, Tractors and Farm Equipment Limited, Iseki & Co. Ltd., Yanmar Holdings Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cambodia Agricultural Machinery Market Strategic Shifts
Mechanization patterns across Cambodia's rice belt are converging around three distinct vectors: regulatory-driven engine technology turnover, digital precision adoption subsidized by pilot programs, and contractual restructuring of equipment access. These forces collectively reshape how capital flows into productive agricultural assets.
GPS-enabled auto-steering tillage systems are collapsing the operational boundary between large-scale commercial contractors and technically sophisticated cooperatives. Battambang province rice farming groups are adopting these guidance platforms at accelerating rates, compressing the historical capability gap that separated estate-level precision from smallholder mechanization. This technology diffusion is enabling cooperative fleets to match contractor-grade field efficiency at reduced labor input.
Draft regulations on agricultural diesel subsidies are advancing through legislative review channels, with Cambodia's Ministry of Agriculture, Forestry and Fisheries signaling potential restructuring of fuel support programs. The industrial consequence is inventory pre-positioning by distributors ahead of policy clarity, creating temporary supply gluts in Phnom Penh storage facilities. Large-scale rice contractors in the Mekong Delta corridor are most exposed to this uncertainty, delaying fleet replacement commitments until subsidy terms crystallize.
Service unbundling is fragmenting traditional dealer-customer relationships across northwestern provinces. Independent mobile mechanics and third-party parts resellers are displacing authorized service networks for routine maintenance, particularly among aging tractor fleets operating beyond warranty periods. This behavioral shift is most visible in Siem Reap province, where cooperative members prioritize repair speed and cost over manufacturer certification.
Cambodia Agricultural Machinery Market Segmentation
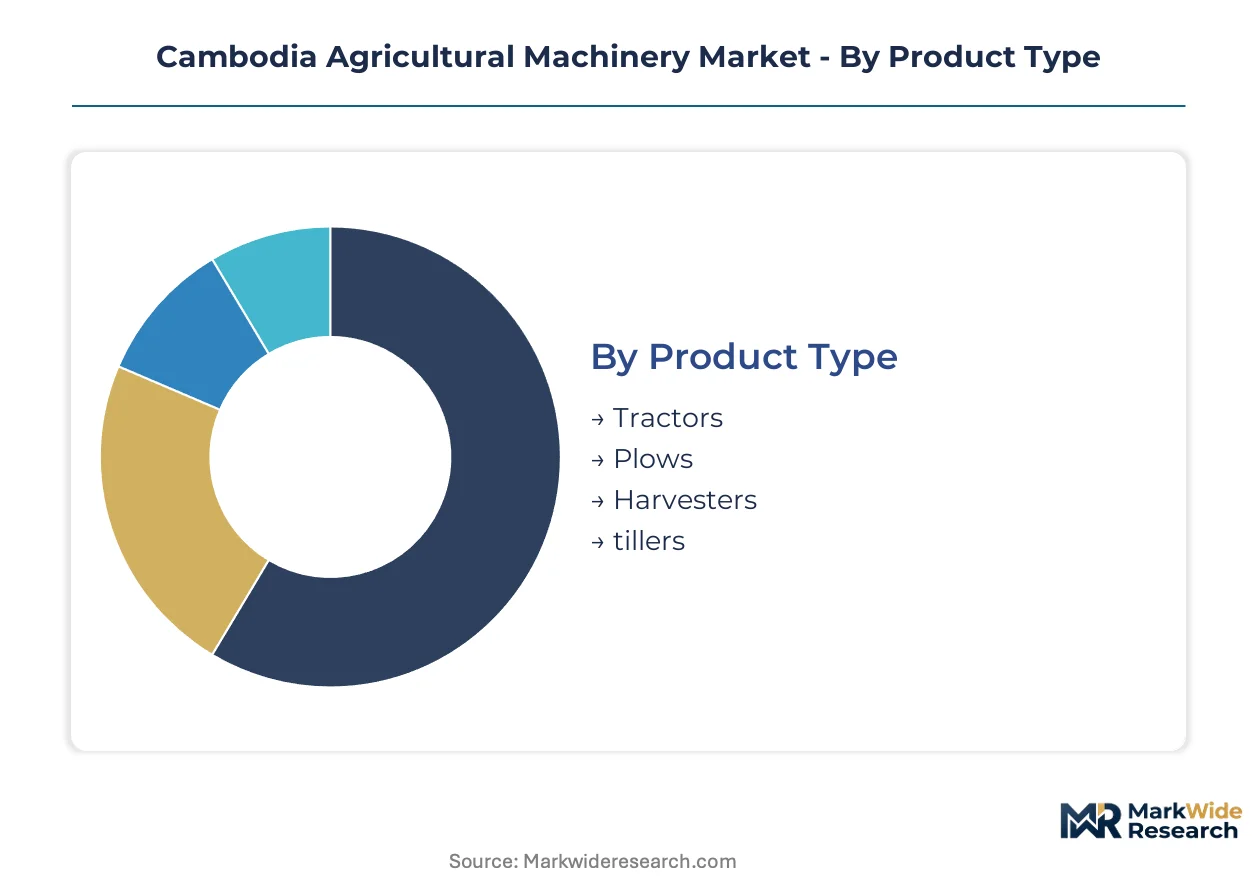
Equipment segmentation in Cambodia reveals distinct procurement patterns across the Tonle Sap lowlands and Mekong Delta corridor. Commercial rice contractors, smallholder cooperatives, and government extension services each prioritize different performance specifications and financing structures.
Product Type:
The use-case spectrum spans foundational soil tillage through specialized harvest operations, with equipment selection driven by field size, crop rotation intensity, and seasonal labor availability.
- Tractors:Diesel-powered platforms rated 15-75 horsepower serve as the primary tillage and transport foundation across Battambang and Siem Reap provinces. Rice farming cooperatives are expanding shared tractor fleets to reduce per-hectare mechanization costs while maintaining planting schedule compliance.
- Harvesters:Combine systems command premium positioning due to acute seasonal labor scarcity during peak rice collection windows. Large-scale contractors in the Mekong Delta corridor prioritize high-horsepower models with grain handling capacity matched to contract acreage obligations.
- Plows:Steel-framed implements engineered for paddy field conditions attach to tractor three-point hitch systems for primary and secondary tillage operations.
- Tillers:Compact walk-behind units address smallholder plots below five hectares where full tractor deployment proves economically inefficient.
The dominant share belongs to tractors, while harvesters are closing the gap fastest as labor substitution economics intensify.
Application:
Cost tier differentiation separates capital-intensive infrastructure from seasonal operational equipment, with irrigation systems representing the highest per-hectare investment category.
- Irrigation:Pump sets and canal distribution networks require substantial upfront capital and regulatory coordination with Cambodia's Ministry of Agriculture, Forestry and Fisheries. Water access security determines land valuation in drought-prone provinces, concentrating demand among commercial contractors with multi-year lease commitments.
- Soil Preparation:Tillage operations consume the majority of annual tractor operating hours across the northwestern rice belt. Secondary tillage demand peaks during narrow pre-planting windows, forcing equipment sharing arrangements among adjacent smallholders.
- Crop Maintenance:Cultivators and inter-row equipment address weed competition during vegetative growth stages.
- Pest Control:Mounted and trailed sprayers apply agrochemical inputs with increasing regulatory scrutiny on application precision and buffer zone compliance.
Irrigation commands the steepest price points, while soil preparation equipment moves the highest unit volumes annually.
End User:
Customer type segmentation governs financing structure, service expectations, and equipment specification complexity across distribution channels.
- Farmers:Individual smallholders below five hectares rely on animal traction and hand tools in remote northeastern provinces, limiting mechanization penetration. Subsistence operations prioritize repair accessibility over manufacturer certification, driving independent mechanic network expansion.
- Cooperatives:Pooled-resource groups in Battambang and Siem Reap provinces access subsidized credit lines for shared tractor and harvester fleets. Equipment-as-a-service leasing structures with bundled maintenance are penetrating this segment, shifting transaction economics from asset ownership to operational expenditure.
- Agricultural Contractors:Commercial operators manage seasonal labor gaps through automated transplanting and combine harvesting systems across the Tonle Sap lowlands.
- Government Agencies:Extension services and demonstration farms pilot precision agriculture technology with grant funding support.
Cooperatives are expanding their equipment base most aggressively, while contractors maintain the highest asset utilization rates.
Technology:
Maturity stage segmentation tracks the progression from established mechanical systems through digitally-enabled precision platforms.
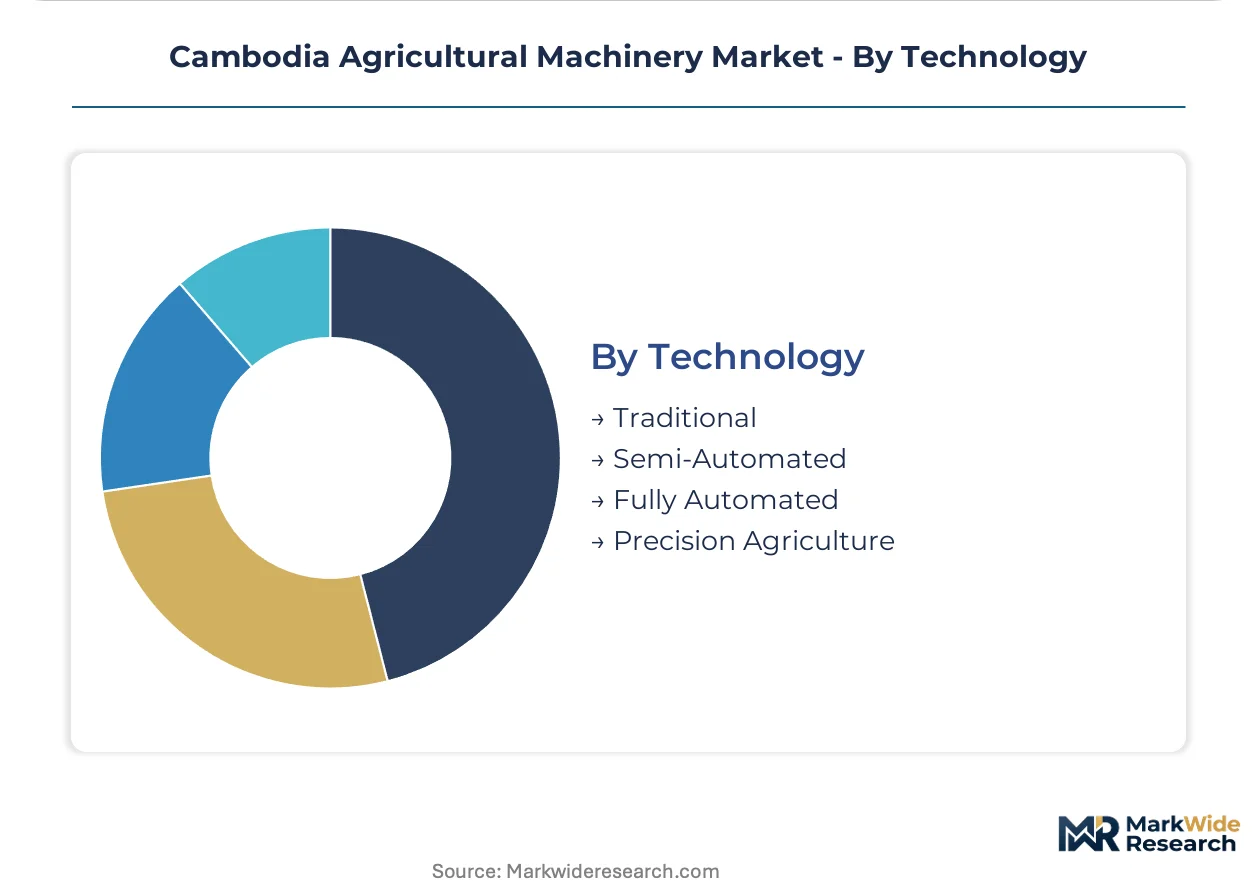
- Traditional:Conventional diesel-mechanical equipment without electronic control systems sustains volume among subsistence farmers in peripheral geographies. Manual cultivation persistence in remote northeastern provinces caps replacement demand for this tier.
- Semi-Automated:Hydraulically-assisted implements and power-shift transmissions reduce operator fatigue during extended field operations. Siem Reap cooperatives are adopting these platforms at accelerating rates as technical operator training programs expand.
- Fully Automated:Autosteer and continuous variable transmission systems remain concentrated among large-scale contractors with dedicated technical staff.
- Precision Agriculture:GPS-guided tillage and variable-rate input application attract government pilot funding for yield optimization trials.
Traditional equipment retains the broadest installed base, though semi-automated systems are gaining share fastest among technically-capable cooperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cambodia's Ministry of Agriculture, Forestry and Fisheries anchors regulatory oversight across the northwestern rice belt, shaping equipment import protocols and diesel subsidy frameworks that determine fleet replacement timing for commercial contractors.
Battambang Province
Rice farming cooperatives in Battambang are mechanizing planting and harvesting operations to address acute seasonal labor scarcity. The Ministry of Agriculture, Forestry and Fisheries channels subsidized credit lines toward pooled-resource groups forming shared tractor fleets. Battambang's commercial rice contractors now deploy GPS-enabled auto-steering tillage systems previously limited to large-scale estate operations.
Siem Reap Province
Smallholder cooperatives in Siem Reap access preferential financing for semi-automated equipment with hydraulically-assisted implements. Cambodia's national standards body enforces emissions testing requirements that accelerate turnover of older diesel inventory. Independent mobile mechanics in Siem Reap are displacing authorized service networks for routine maintenance among aging tractor fleets.
Tonle Sap Lowlands
Commercial rice contractors across the Tonle Sap lowlands prioritize high-horsepower harvesters with grain handling capacity matched to contract acreage obligations. The General Department of Customs and Excise applies favorable tariff classifications for ASEAN-origin machinery, lowering landed costs for Thai and Vietnamese equipment. Large-scale operators in this corridor face inventory pre-positioning pressures ahead of anticipated diesel subsidy restructuring.
Mekong Delta Corridor
Agricultural contractors in the Mekong Delta corridor manage seasonal workforce gaps through automated transplanting and combine harvesting systems. Draft regulations on agricultural diesel subsidies are advancing through legislative review, creating policy uncertainty that delays fleet replacement commitments. Phnom Penh-based distributors are pre-positioning cleaner-certified equipment in storage facilities to meet compressed import inspection windows.
Remote Northeastern Provinces
Subsistence farmers in Cambodia's remote northeastern provinces continue relying on animal traction and hand tools, capping mechanization penetration rates. Manual cultivation persistence in these peripheral geographies sustains demand for traditional non-powered implements. The Ministry of Agriculture, Forestry and Fisheries extends limited extension services to these areas, with precision agriculture pilot funding concentrated in more accessible commercial zones.
Cambodia Agricultural Machinery Market Competitive Environment
Japanese and Indian equipment manufacturers split the Cambodian market between premium-tier precision platforms and affordability-optimized tractor lines. The competitive structure concentrates around three strategic archetypes: diversified agricultural conglomerates with full-line portfolios, specialized compact equipment fabricators, and regional distributors with integrated financing capabilities. Market participants are pursuing strategic partnerships with local cooperative networks and expanding service infrastructure to address after-sales coverage gaps in northwestern provinces.
Among Japanese manufacturers, Kubota Corporation and Yanmar Holdings Co., Ltd. exemplify the diversified conglomerate archetype with established Phnom Penh distribution infrastructure. Mahindra and Mahindra Ltd. represents the affordability-focused tractor specialist, occupying a position tailored to smallholder cooperative financing requirements. These three companies anchor the competitive landscape through distinct positioning vectors: premium precision technology, compact utility platforms, and accessible credit-linked equipment access.
| Leading Market Players |
|---|
| Mahindra and Mahindra Ltd. |
| AGCO Corporation |
| Kubota Corporation |
| CLAAS KGaA mbH |
| Escorts Limited |
| Deere & Company |
| Tractors and Farm Equipment Limited |
| Iseki & Co. Ltd. |
| Yanmar Holdings Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Thai and Vietnamese manufacturing clusters anchor upstream production for Cambodia's agricultural machinery imports, concentrating margin capture in Phnom Penh-based distribution hubs that control spare parts availability and financing terms for Battambang and Siem Reap cooperatives.
Pricing Analysis
Price spreads of 15-25% separate ASEAN-origin equipment from third-country alternatives across the Tonle Sap lowlands. Three-tier pricing structure across premium, standard, and economy levels reflects engine certification grade and after-sales bundling intensity. Cost compression in the economy tier is intensifying because manual cultivation persistence in remote provinces caps replacement demand. Smallholder cooperatives exhibit acute price sensitivity, while large-scale contractors prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from Thai and Vietnamese assemblers to Phnom Penh distributors define working capital dynamics across the procurement cycle. Manufacturing concentrates in Thailand, Vietnam, and Japan, with diesel engines and hydraulic assemblies representing critical component dependencies. Single-source vulnerability runs through the narrow channel of Ministry-certified import inspectors. Distribution runs through cooperative-linked dealers in northwestern provinces and contractor-direct relationships in the Mekong Delta corridor.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cambodia's agricultural machinery market rewards regulatory entrenchment as a structural moat. Distributors with pre-established Ministry of Agriculture, Forestry and Fisheries certification relationships face switching costs that deter new competitor entry.
For Market Incumbents: Pre-empt emerging equipment-as-a-service competitors by embedding maintenance contracts into cooperative financing structures. Capture backward integration into parts warehousing in Battambang province to reduce stockout vulnerability during peak harvest windows. Certification investment in cleaner-engine inventory ahead of diesel subsidy restructuring will consolidate positioning among policy-exposed contractors.
For New Entrants and Emerging Players: Establish a beachhead in Siem Reap's independent mobile mechanic networks, where authorized service displacement creates white-space for third-party parts resellers. Remote northeastern provinces offer the most penetrable geography given persistent manual cultivation and limited extension service coverage. A leasing-first go-to-market angle with bundled operator training addresses capital constraints among smallholder cooperatives.
For Investors and Strategic Acquirers: Capital is best deployed toward distributors with integrated financing capabilities and established cooperative relationships. Long-term viability hinges on regulatory compliance infrastructure rather than volume scale alone. Watch for diesel subsidy legislation crystallization as the signal determining fleet replacement timing and inventory valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Expansion | Shifts cooperative economics from asset ownership to operational expenditure with bundled maintenance. |
| Cross-Border Service Corridor Development | Thai and Vietnamese technical networks address after-sales coverage gaps in northwestern provinces. |
| Precision Agriculture Pilot Engagement | Government grant access positions contractors for GPS-guided tillage yield optimization trials. |
| Cleaner-Engine Inventory Pre-Positioning | Compressed import inspection windows require Phnom Penh warehouse capacity expansion. |
| Independent Mechanic Network Partnership | Siem Reap cooperative repair preferences favor speed and cost over manufacturer certification. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with equipment distributors, cooperative managers, and Ministry of Agriculture, Forestry and Fisheries officials, alongside secondary validation through customs records, ASEAN trade agreement documentation, and agricultural development bank lending disclosures. Bottom-up triangulation across tractor and harvester unit flows converged with top-down expenditure estimates from commercial contractor acreage obligations.
Forecast inputs span equipment type segmentation, end-user financing structure, and technology adoption tier across the projection horizon. The analytical framework models product type, application intensity, customer scale, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and cooperative formation credit expansion. Diesel subsidy policy trajectory and labor scarcity severity represent primary forecast sensitivity variables.
Sensitivities concentrate around regulatory timeline compression for import compliance and subsidy restructuring legislative outcomes. Forecasts reflect assumptions regarding cooperative credit access continuity and cross-border service network extension. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
France Agricultural Machinery Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
North America Agricultural Sprayers Market
Agricultural Machinery
Agricultural Drum Mowers Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Agricultural Unit Heaters Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Automated Turf Harvester Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market