
 North America PET Bottle Market | 2026-2036
North America PET Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
North America PET Bottle Market Intelligence
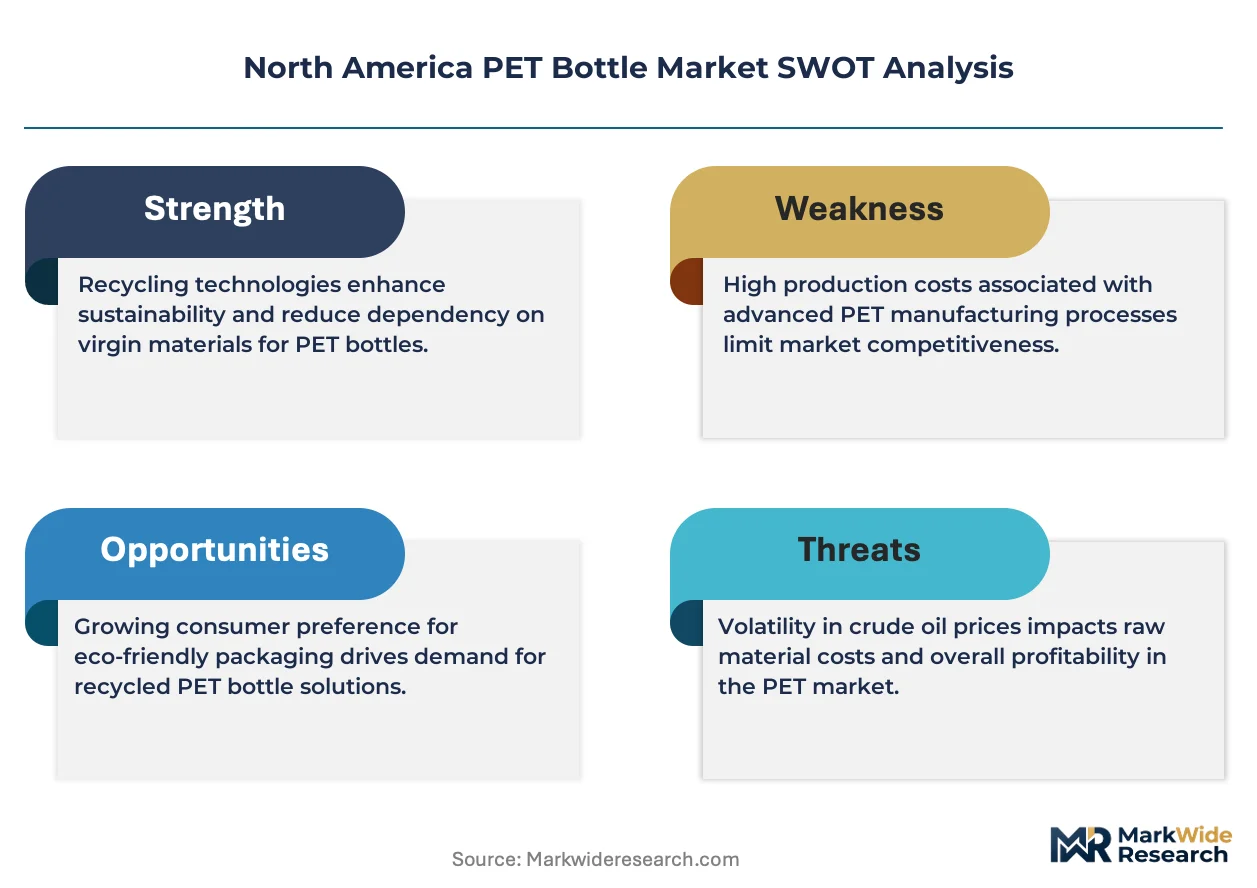
Multi-source resin procurement is realigning how converters manage virgin and recycled PET feedstock. Graham Packaging Company LP leverages its captive blow-molding network to sustain supply continuity across dairy and juice accounts. Amcor plc anchors North American volume through integrated preform-to-bottle operations in the Midwest and Southeast. Berry Global Inc. competes on scale, operating multiple facilities optimized for lightweighting and high-speed filling compatibility.
Polyethylene terephthalate bottles are thermoplastic containers formed through injection-stretch blow molding of PET resin, valued for barrier properties against oxygen and carbon dioxide loss, with typical wall thickness ranging from 0.25 to 0.50 millimeters depending on carbonation pressure requirements. The beverage end-user segment dominates volume, though personal care applications in shampoos and body washes represent a faster-growing margin pool as brands switch from HDPE. Recyclable product types occupy the structural center, while biodegradable alternatives remain nascent due to limited industrial composting infrastructure and higher unit economics.
FDA food-contact notifications govern resin purity and additive migration limits for PET bottles, while EPA recycled content mandates under emerging state frameworks are pressuring converters to document post-consumer feedstock percentages. The FDA also coordinates with OSHA on plant safety standards for blow-molding operations involving high-pressure compressed air. Stakeholders must monitor how California, Oregon, and Washington state-level extended producer responsibility laws diverge from federal baselines, as compliance fragmentation will determine regional manufacturing investment priorities.
Market Dynamics
rPET integration mandates from California, Oregon, and Washington are forcing converters to reengineer resin procurement and blow-molding workflows across the US Southeast manufacturing corridor.
Growth Catalysts
- State EPR frameworks:Extended producer responsibility laws in California and Oregon mandate minimum post-consumer recycled content thresholds, creating guaranteed offtake for rPET processors.
- Beverage brand commitments:Carbonated soft drink and bottled water lines are converting virgin PET lines to recycled feedstock to meet corporate sustainability targets ahead of regulatory deadlines.
- Resin production clustering:Gulf Coast petrochemical complexes and inland recycling hubs in the US Southeast concentrate virgin and recycled PET supply within 500 miles of major bottling operations.
Market Restraints
- rPET cost volatility:Post-consumer bale prices fluctuate with collection infrastructure investment cycles, squeezing converter margins against stable virgin resin benchmarks.
- FDA food-contact purity requirements:Migration limit testing for contaminants in recycled feedstock adds certification lag and rejects batches that fail decontamination verification.
- Industrial composting absence:Biodegradable PET alternatives lack regional processing infrastructure, trapping brands in conventional recyclable formats despite consumer preference signals.
Strategic Opportunities
- Mexico nearshoring expansion:Bottling operations in Baja California and Monterrey offer tariff-advantaged export platforms to US Southwest distribution networks.
- Personal care conversion:Shampoo and body wash brands are switching from HDPE to PET for clarity and shelf appeal, opening premium margin pools outside beverage commoditization.
- Lightweighting technology convergence:Advanced preform design software combined with high-speed blow-molding controls enables sub-10 gram bottle weights without carbonation loss.
Industry Challenges
- Blow-molding technician scarcity:High-pressure compressed air system operation requires specialized OSHA safety certification that regional community colleges have not scaled to meet demand.
- Multi-source resin qualification:Blending virgin and recycled feedstock streams demands real-time viscosity monitoring and rapid die adjustment that legacy equipment cannot execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America PET Bottle Market |
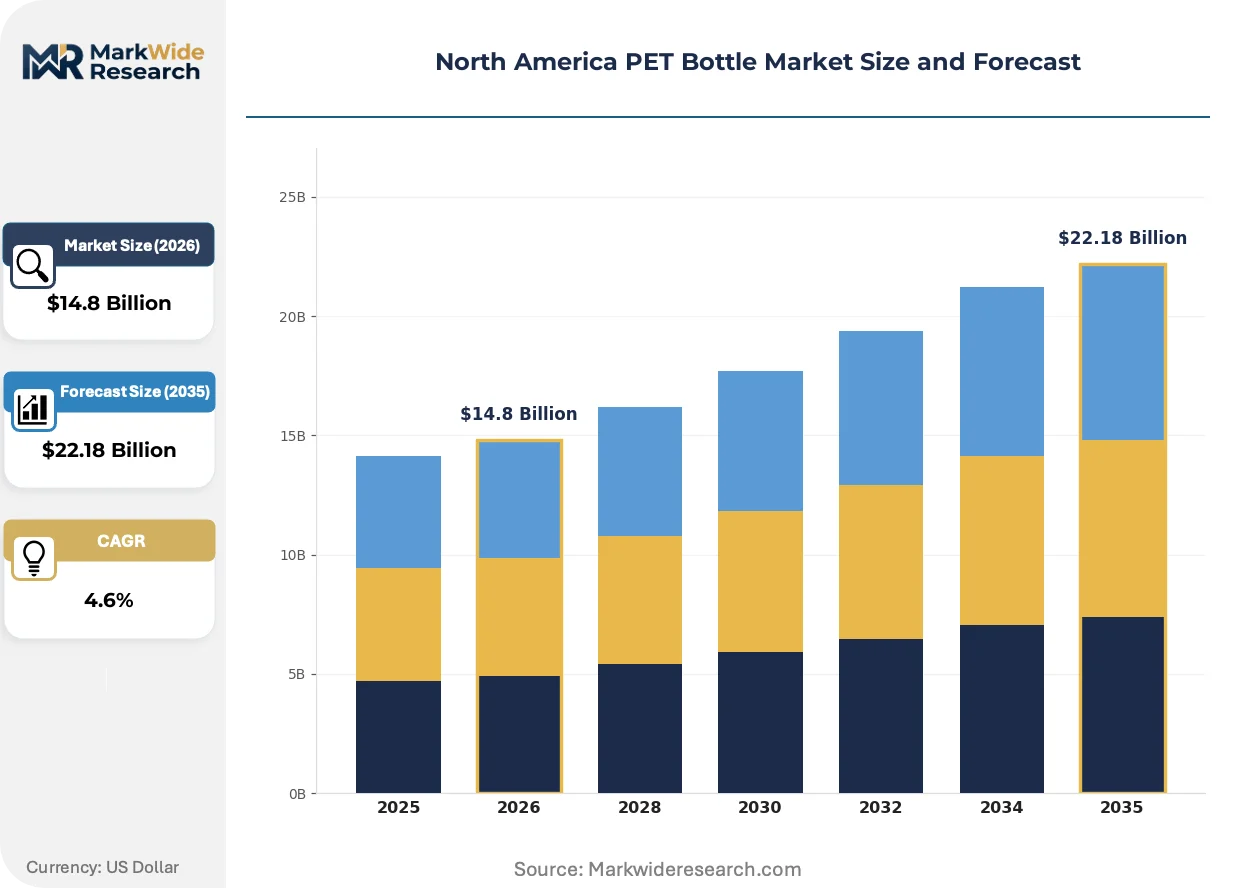
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recyclable, Biodegradable, Non-Biodegradable, Composite End User: Beverage Industry, Food Packaging, Personal Care, Household Chemicals Size: Small, Medium, Large, Extra Large Shape: Round, Square, Custom, Ergonomic |
| Companies Covered | Graham Packaging Company LP, Silgan Holdings Inc., Amcor plc, Alpha Packaging Inc., ALPLA Group, Berry Global Inc., Altium Packaging, Niagara Bottling, LLC., Plastipak Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America PET Bottle Market Strategic Shifts & Innovations
Digital traceability platforms and advanced recycling technologies are compressing the loop between post-consumer collection and food-grade reprocessing, tightening material provenance standards.
Distributed recycling units using chemical depolymerization are decentralizing rPET purification by enabling regional processors to convert contaminated flake back to virgin-quality resin without centralized mega-facility investment. Small-scale operators in Texas and Arizona are piloting these systems to serve local bottlers. This geographic dispersion reduces transportation emissions and insulates converters from Gulf Coast resin price shocks.
EPA state recycling mandates under emerging frameworks are forcing converters to document chain-of-custody from bale to bottle through blockchain-enabled tracking systems. The compliance burden falls heaviest on mid-tier converters lacking integrated collection partnerships. California's SB 54 implementation timeline is accelerating software procurement decisions ahead of 2030 reporting deadlines.
Beverage procurement teams are consolidating supplier relationships around converters offering integrated preform-to-bottle operations with certified rPET percentages. Long-term offtake agreements now specify minimum recycled content tiers rather than spot-price virgin resin contracts. This preference shift concentrates volume with vertically integrated processors in the US Midwest and Southeast.
North America PET Bottle Market Segmentation
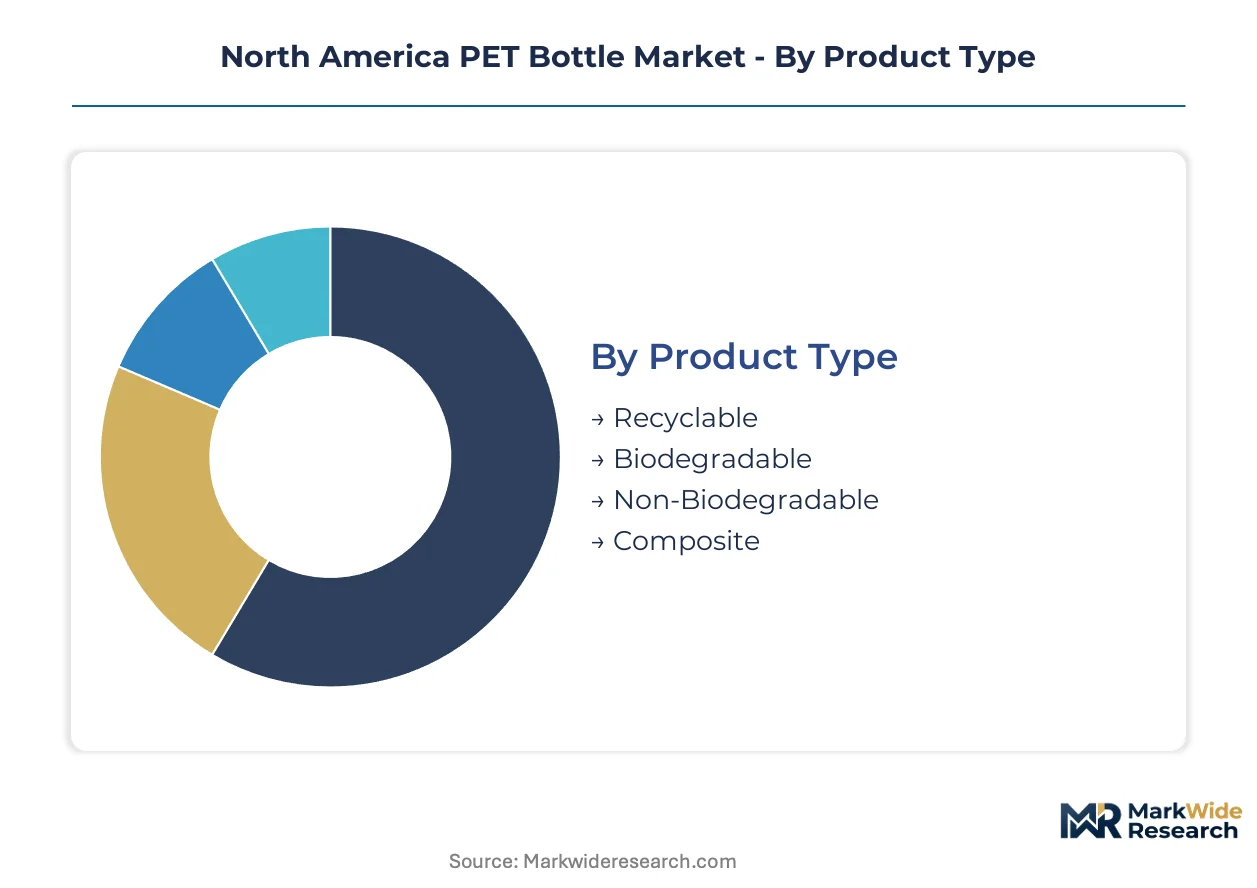
PET bottle converters configure production lines around specific performance requirements rather than generic capacity. Segmentation reveals where capital deployment and margin capture diverge across technical specifications and end-use demands.
Product Type:
Recyclable formats demand the heaviest upfront capital, requiring FDA-validated decontamination systems and food-contact certification infrastructure. Biodegradable alternatives need lower equipment investment but face limited offtake channels.
- Recyclable:These bottles incorporate post-consumer rPET at varying percentages, processed through injection-stretch blow molding with real-time viscosity monitoring. Demand concentrates in carbonated soft drinks and bottled water lines across the US Southeast, where state EPR mandates in California, Oregon, and Washington guarantee offtake. FDA food-contact purity requirements add certification lag that favors converters with captive recycling partnerships.
- Biodegradable:Formulated with additives enabling microbial breakdown under industrial composting conditions, these containers sacrifice barrier performance for end-of-life credentials. Demand clusters in premium personal care brands targeting coastal urban markets, constrained by absent regional composting infrastructure that traps volumes below commercial scale.
- Non-Biodegradable:Standard virgin-PET containers without enhanced degradation properties.
- Composite:Multi-layer structures combining PET with barrier resins or oxygen scavengers.
Most installed capacity flows through Recyclable. Expansion is steepest in Biodegradable.
End User:
Beverage procurement teams drive the highest volume throughput, while personal care buyers command premium pricing for clarity and shelf differentiation. Food packaging applications sit between these poles on margin and technical complexity.
- Beverage Industry:Carbonated soft drinks, bottled water, juices, and ready-to-drink teas dominate tonnage, with carbonation pressure dictating wall thickness between 0.25 and 0.50 millimeters. Demand concentrates in the US Southeast manufacturing corridor, where resin production clusters and bottling infrastructure overlap within 500-mile supply radii.
- Personal Care:Shampoos, body washes, and cosmetics are switching from HDPE to PET for glass-like clarity and premium shelf appeal. Demand is climbing fastest in branded mass-market lines, with converters capturing margin pools outside beverage commoditization through color-matched preform capabilities.
- Food Packaging:Edible oils, dressings, and condiments require enhanced oxygen barrier properties.
- Household Chemicals:Cleaners and detergents utilize thicker-walled constructions for chemical resistance.
Volume leadership sits with Beverage Industry. Margin expansion is strongest in Personal Care.
Size:
Capital allocation across size categories tracks filling line speeds and transportation economics, with mid-range formats offering the optimal balance of mold utilization and logistics density.
- Small:Single-serve and travel-size containers under 250 milliliters.
- Medium:Standard retail formats between 250 milliliters and 1 liter.
- Large:Family-size and club-store formats between 1 and 3 liters.
- Extra Large:Bulk and refill containers exceeding 3 liters.
Equipment utilization peaks in Medium. Lightweighting investment targets Large.
Shape:
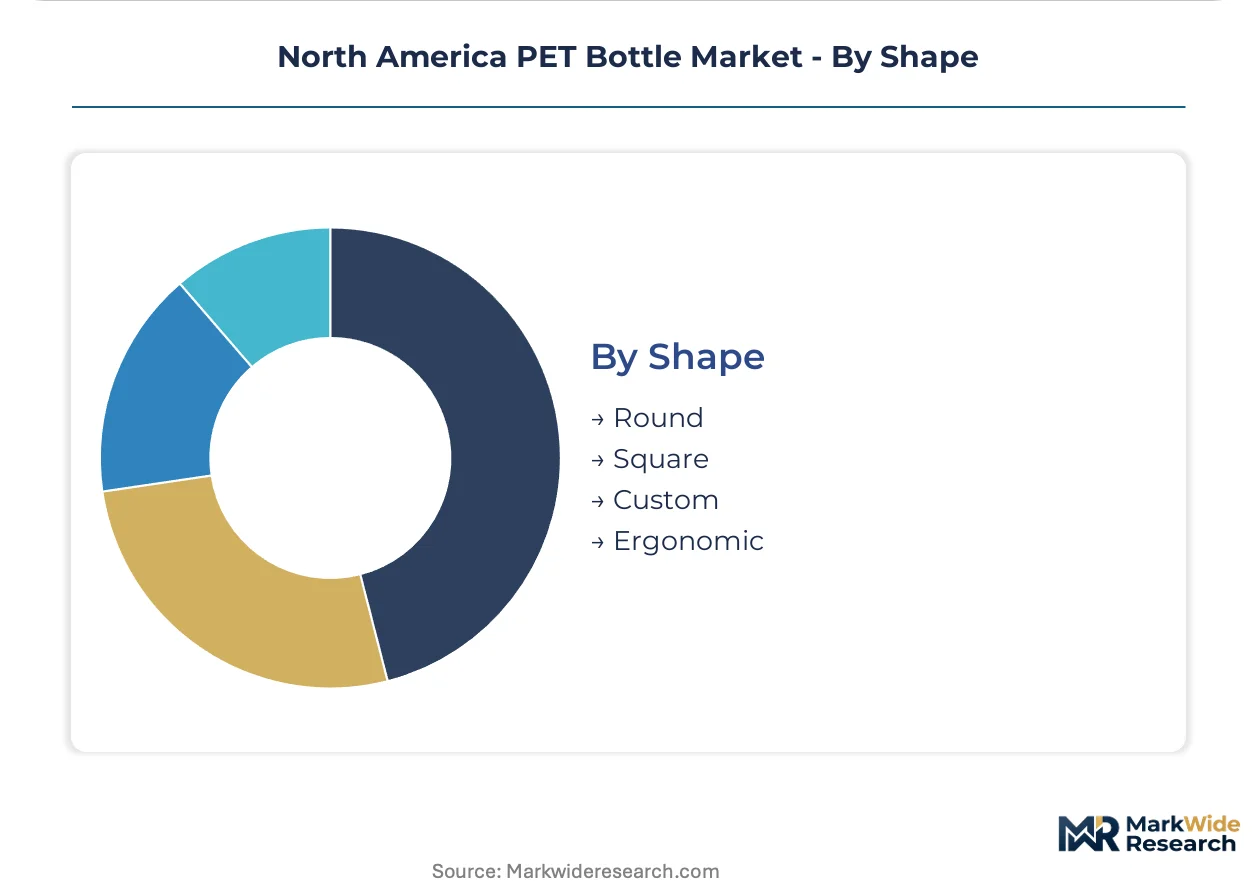
Custom and ergonomic tooling requires specialized mold fabrication that extends lead times and elevates minimum order quantities. Round formats maximize production efficiency on standard blow-molding platforms.
- Round:Cylindrical profiles optimized for carbonation pressure distribution and label adhesion.
- Square:Rectangular cross-sections maximizing pallet density for still beverages.
- Custom:Proprietary silhouettes requiring dedicated mold investments.
- Ergonomic:Contoured grips and textured surfaces for handling security.
Throughput dominance belongs to Round. Design differentiation concentrates in Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Southeast manufacturing corridor concentrates North American PET bottle capacity within a 500-mile radius of Gulf Coast resin production clusters.
United States
Carbonated soft drink and bottled water lines drive volume demand across the Southeast and Midwest. FDA food-contact notifications govern resin purity and additive migration limits for converters. Charlotte, North Carolina and Atlanta, Georgia anchor blow-molding operations that serve Coca-Cola and PepsiCo distribution networks.
California
State EPR mandates under SB 54 create guaranteed offtake for rPET processors ahead of 2030 deadlines. California's Air Resources Board coordinates with EPA on recycled content verification protocols. Los Angeles and Central Valley recycling hubs feed food-grade reprocessing facilities serving coastal beverage brands.
Texas
Gulf Coast petrochemical complexes supply virgin PET resin to converters within 300 miles of Houston. OSHA plant safety standards for high-pressure compressed air systems govern blow-molding operations. Distributed chemical depolymerization pilots in Dallas-Fort Worth and Austin convert contaminated flake to virgin-quality resin.
Canada
Ontario and Quebec beverage bottlers import preforms from US Midwest converters under USMCA tariff preferences. Health Canada aligns food-contact regulations with FDA migration limits through mutual recognition protocols. Toronto-Waterloo corridor recycling infrastructure supplies rPET flake to cross-border processors.
Mexico
Baja California and Monterrey bottling operations export tariff-advantaged finished goods to US Southwest distribution networks. Mexican environmental regulators implement extended producer responsibility frameworks modeled on California's SB 54. Nuevo León industrial parks attract blow-molding investment from US converters seeking labor cost arbitrage.
North America PET Bottle Market Key Industry Players
Global majors compete with regional champions across integrated preform-to-bottle operations and specialized lightweighting capabilities. The market structures around three tiers: multinational converters with captive recycling networks, mid-scale regional fabricators serving single-state beverage accounts, and niche specialists in personal care color-matching. Consolidation pressure intensifies as brand procurement teams consolidate supplier relationships around certified rPET percentages. Capacity expansion and backward integration into resin procurement represent the dominant competitive vectors.
Among North American converters, Graham Packaging Company LP, Amcor plc, and Berry Global Inc. occupy positions across the scale spectrum. Graham Packaging exemplifies the captive blow-molding network archetype sustaining supply continuity. Amcor anchors integrated preform-to-bottle operations in the Midwest and Southeast. Berry Global represents scale-driven competition through multiple facilities optimized for lightweighting.
| Leading Market Players |
|---|
| Graham Packaging Company LP |
| Silgan Holdings Inc. |
| Amcor plc |
| Alpha Packaging Inc. |
| ALPLA Group |
| Berry Global Inc. |
| Altium Packaging |
| Niagara Bottling, LLC. |
| Plastipak Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
Chemical depolymerization pilots in Texas and Arizona are compressing rPET purification economics while dispersing supply geographically away from Gulf Coast resin clusters. This dual shift simultaneously reduces transportation cost exposure and fragments pricing power among regional processors.
Pricing Analysis
Input-cost pass-through from post-consumer bale volatility dominates converter margin management. Pricing stratifies across FDA-certified food-grade, industrial non-contact, and export-grade tiers. Cost compression in food-grade rPET is intensifying because decontamination verification rejects increase batch failure rates. Beverage procurement teams show lowest price sensitivity due to EPR compliance deadlines, while household chemical buyers resist premium rPET sourcing.
Supply Chain Analysis
FDA food-contact certification gates access to beverage and food packaging accounts, filtering supplier pools to converters with validated decontamination infrastructure. Geographic supply concentration centers on the United States, Mexico, and Canada within USMCA trade preferences. Raw material dependencies draw from Gulf Coast virgin resin, post-consumer bale streams, and chemical depolymerization outputs. Single-source vulnerability runs through concentrated Gulf Coast petrochemical complexes. Distribution runs through integrated preform-to-bottle networks serving 500-mile bottling radii.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America PET Bottle Market functions as a stable compounder anchored by state EPR mandates that guarantee recycled content offtake across regulatory cycles.
For Market Incumbents: Acquire captive recycling partnerships to secure post-consumer bale access before California SB 54 deadlines tighten. Backward integration into resin procurement insulates margin pressure from virgin PET price shocks. Expand decontamination capacity in the US Southeast to defend food-grade certification against emerging distributed chemical depolymerization competitors.
For New Entrants and Emerging Players: The price-point gap between premium personal care color-matched PET and economy beverage-grade rPET offers white-space entry. Target personal care conversion from HDPE in branded mass-market lines. Pursue nearshored bottling operations in Baja California for tariff-advantaged US Southwest distribution.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional fabricators lacking integrated collection partnerships but holding FDA-validated infrastructure. Long-term viability frames around converters with documented chain-of-custody capabilities spanning the analysis window. Watch California Air Resources Board recycled content verification protocol changes as inflection indicators for compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Collection | Secures post-consumer bale supply ahead of state EPR mandate deadlines. |
| FDA Food-Contact Certification Investment | Unlocks beverage and food packaging accounts with migration limit compliance. |
| Mexico Nearshoring Expansion | Captures USMCA tariff advantages for US Southwest distribution network access. |
| Lightweighting Technology Deployment | Enables sub-10 gram bottle weights without carbonation barrier performance loss. |
| Blockchain Traceability Implementation | Satisfies California SB 54 chain-of-custody documentation requirements ahead of deadlines. |
Research Approach
Bottom-up beverage and personal care demand modeling reconciled against top-down resin production and recycling capacity tracking forms the analytical core. Primary interviews with blow-molding plant managers, beverage procurement leads, personal care brand managers, and rPET collection facility operators combined with secondary validation from FDA food-contact notifications, EPA state recycling framework filings, and USMCA trade flow data. Top-down and bottom-up triangulation cross-checks volume assumptions against supply-side capacity constraints.
Historical trendline analysis of resin price volatility, rPET adoption rates, and state regulatory implementation timelines informs projection mechanics. Segmentation dimensions span product type, end-user industry, size category, and geographic manufacturing cluster. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection points. Industry-specific forecast inputs include California SB 54 compliance trajectory and chemical depolymerization pilot scale-up rates.
Caveats apply where FDA migration limit revisions or EPA recycled content mandate acceleration could materially shift the outlook. Forecasts reflect assumptions about state EPR implementation pacing and rPET collection infrastructure investment cycles. A model refresh is warranted upon material change in California Air Resources Board verification protocol stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
Plastic Shrink Wrap Market