
 North America Retail Bags Market | 2026-2036
North America Retail Bags Market Size, Share, and Industry Trends Forecast 2026-2036
North America Retail Bags Market Analytics
ASTM D6400 certification for compostable plastics is bifurcating the North America Retail Bags Market into qualified and non-qualified supplier tiers. Novolex Holdings Inc. leverages its integrated film-to-bag manufacturing footprint across the Midwest to sustain volume leadership in polyethylene formats. Mondi Group PLC anchors its position through kraft paper specialization and mill-level vertical integration that controls fiber sourcing costs.
Retail bags in North America encompass single-use and multi-use carry containers fabricated from polyethylene films, kraft paper webs, non-woven polypropylene, or certified compostable polymers, typically ranging from 0.5 to 2.5 mil in gauge and designed to transport purchased goods from point-of-sale to consumer destination. Paper bags, manufactured through multiwall adhesive bonding or twisted-handle construction, serve grocery and apparel channels where plastic restrictions have tightened. Plastic bags still dominate unit volume across convenience stores and discount formats, though biodegradable alternatives represent the fastest-expanding material category as procurement shifts toward certified compostable inventory. Reusable non-woven fabric bags command premium shelf positioning in specialty retail and department store segments where brand aesthetics and repeat-trip utility justify higher unit economics.
The US EPA oversees municipal solid waste frameworks that influence bag disposal infrastructure and recycling economics, while state regulators in California and New York enforce extended producer responsibility mandates that reshape manufacturer cost structures. Health Canada and the Canadian Environmental Protection Act govern chemical migration limits and labeling requirements for food-contact retail bags sold across provincial borders. Stakeholders must monitor pending federal preemption debates that could override patchwork state legislation and reset compliance baselines across the entire North American supply base.
Market Dynamics
Single-use plastic bans across California, New York, and Ontario are forcing material transitions faster than supply chain reconfiguration can absorb, compressing conversion timelines for converters and retailers simultaneously.
Growth Catalysts
- ASTM D6400 Certification Mandates:Municipal procurement rules in California and New York now require compostable polymer validation, creating qualified supplier preference tiers for grocery and foodservice contracts.
- Kraft Paper Capacity Expansion:Integrated paper mills in the US Midwest and Canadian Prairie provinces are adding extrusion coating lines to serve moisture-resistant grocery bag demand.
- Extended Producer Responsibility Laws:State-level EPR frameworks in California and New York shift disposal cost burdens upstream, incentivizing lightweight material innovation and recyclability design.
Market Restraints
- Resin Price Volatility:Ethylene and propylene feedstock swings compress margin predictability for polyethylene bag converters operating on thin conversion spreads.
- Pulp Supply Concentration:Softwood kraft fiber sourcing concentrates among Canadian and Southeastern US mill complexes, exposing paper bag manufacturers to regional logistics bottlenecks.
- Composting Infrastructure Gaps:Industrial composting facility scarcity limits ASTM D6400-certified bag end-of-life value realization despite certification compliance.
Strategic Opportunities
- Underpenetrated Canadian Prairie Provinces:Alberta and Saskatchewan lag Ontario and British Columbia in municipal bag ban adoption, creating first-mover positioning windows for certified compostable suppliers.
- How2Recycle Label Integration:Retailers are demanding standardized recycling communication on all carry bag formats, opening specification consulting and pre-printed substrate opportunities.
- Reusable Bag Subscription Models:Grocery chains in dense urban corridors are piloting deposit-return fabric bag programs that convert single-trip transactions into recurring customer touchpoints.
Industry Challenges
- Certification Timeline Compression:ASTM D6400 and BPI compostability validation cycles stretch 12-18 months, misaligning with municipal ban enforcement dates and stranding inventory investments.
- Legacy Heat-Seal Equipment Retrofit Costs:Converters with existing polyethylene bag lines face capital-intensive sealing jaw and cooling system modifications to handle compostable polymer rheology.
- Cross-Border Labeling Complexity:Health Canada chemical migration limits diverge from US FDA food-contact thresholds, forcing dual-SKU production runs for integrated North American retail chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Retail Bags Market |
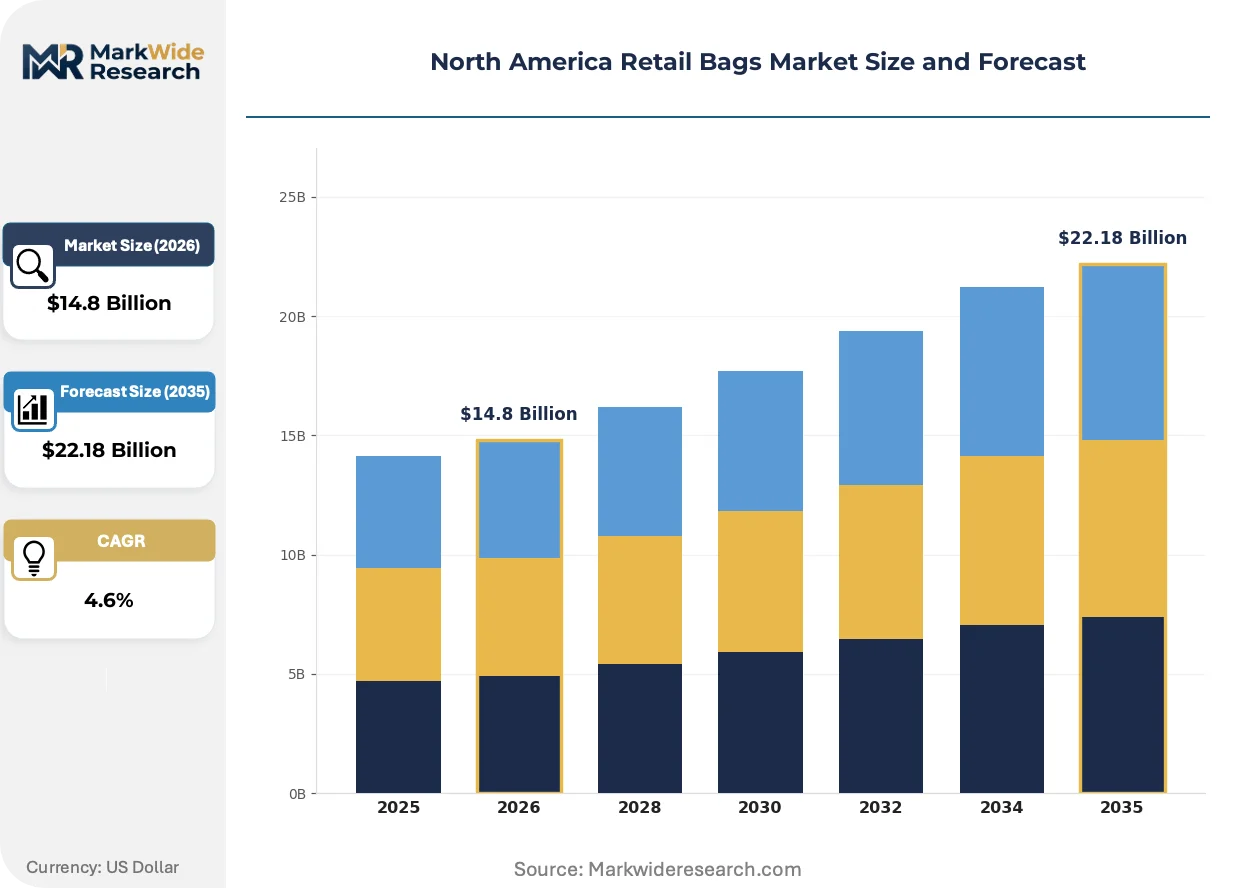
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Paper Bags, Reusable Bags, Biodegradable Bags Distribution Channel: Supermarkets, Convenience Stores, Department Stores, Online Retailers End User: Grocery Stores, Apparel Retailers, Electronics Retailers, Specialty Shops Material: Low-Density Polyethylene, High-Density Polyethylene, Kraft Paper, Non-Woven Fabric |
| Companies Covered | Novolex Holdings Inc., Smurfit Kappa Group PLC, Mondi Group PLC, El Dorado Packaging Inc., International Paper company, Berry Global Inc., Sealed Air Corporation, ProAmpac, Superbag Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Retail Bags Market Evolving Landscape
Material science advances and regulatory label standardization are converging to redefine competitive advantage in retail bag supply, separating specification-compliant suppliers from commodity converters.
Compostable polymer formulations incorporating PBAT-PLA blends are bifurcating the North American supplier base. Grocery chains with 2025-2027 plastic elimination deadlines are fast-tracking ASTM D6400-certified bag trials. This technology is compressing market share for conventional polyethylene converters unable to achieve certification compliance.
California's SB 54 extended producer responsibility framework and New York's Packaging Reduction and Recycling Infrastructure Act are mandating recycled content minimums and recyclability labeling. These laws force converters to re-engineer multi-layer structures or exit food-contact segments entirely. The grocery channel is responding by consolidating supplier panels around vertically integrated paper and certified compostable specialists.
Retailers are unbundling bag procurement from store-brand packaging decisions, creating separate specification tracks for carry bags versus merchandise packaging. This pattern concentrates buying power among national grocery banners and weakens regional converter relationships. The shift is most visible in California and New York metro corridors where sustainability scorecarding drives vendor selection.
North America Retail Bags Market Segmentation
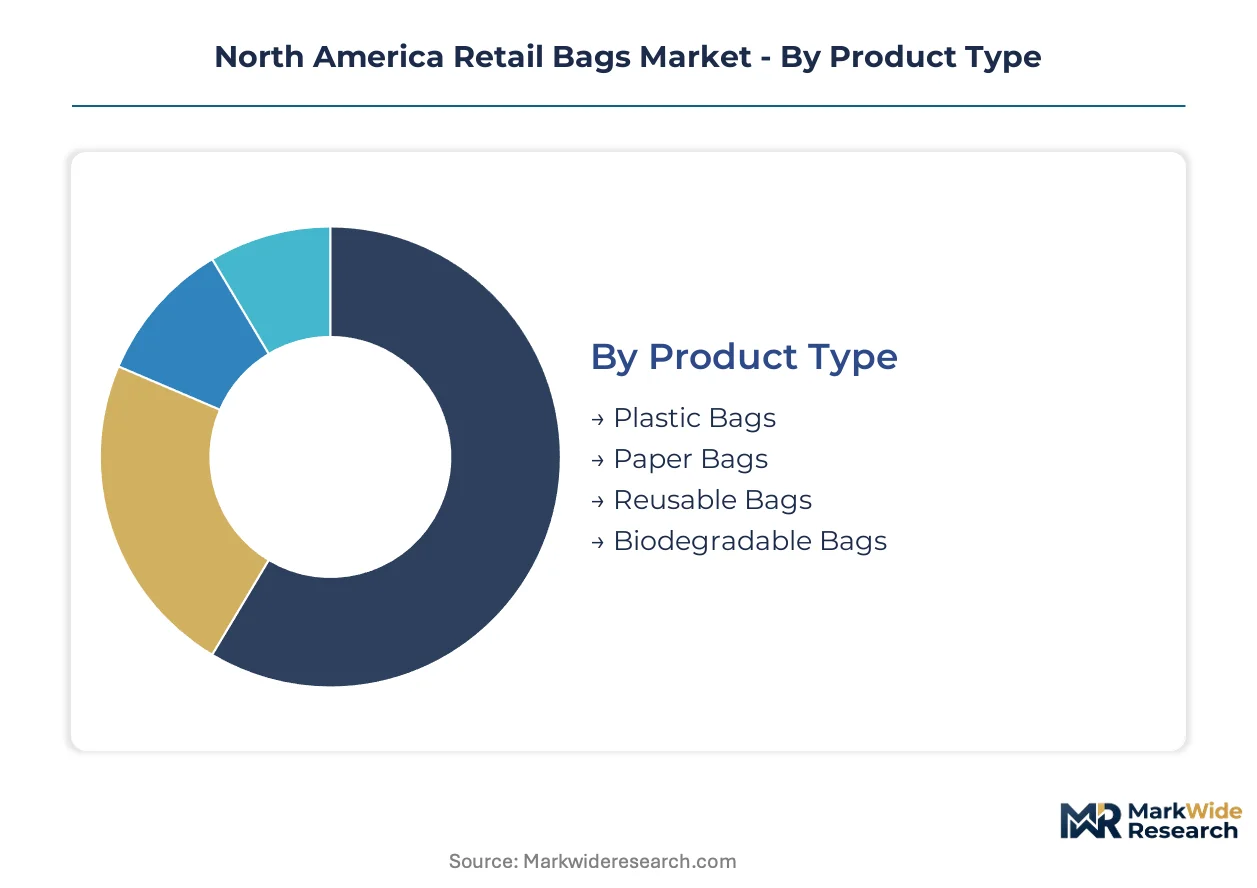
Segmentation in the North America Retail Bags Market reveals how regulatory pressure and channel economics reshape procurement priorities. Material certification tiers and distribution format requirements create divergent growth trajectories across product categories.
Product Type:
Domestic demand concentrates in formats compliant with California and New York municipal bans, while biodegradable alternatives face export-led traction into Canadian provinces with lagging regulation.
- Plastic Bags:Conventional polyethylene formats still dominate unit volume in convenience retail and discount channels where enforcement remains patchy. California's SB 54 and New York's packaging laws are compressing shelf space allocation for non-recycled content variants.
- Paper Bags:Multiwall kraft constructions with twisted handles or adhesive-bonded sidewalls serve grocery and apparel channels facing plastic restrictions. Midwestern US and Canadian Prairie mill proximity controls landed cost competitiveness for regional converters.
- Reusable Bags:Non-woven polypropylene totes command premium positioning in specialty retail and urban grocery formats where deposit-return pilot programs are emerging.
- Biodegradable Bags:ASTM D6400-certified compostable polymers represent the steepest demand climb as procurement shifts toward certified inventory in regulated municipalities.
Plastic bags command the established base. The steepest expansion runs through biodegradable bags.
Distribution Channel:
Channel concentration reflects the cost-tier split between high-volume grocery procurement and fragmented convenience retail purchasing.
- Supermarkets:National grocery banners consolidate bag procurement through sustainability scorecarding that favors vertically integrated paper and certified compostable suppliers. California and New York metro corridors drive specification tightening.
- Convenience Stores:Thin-margin operators prioritize lowest unit cost, sustaining polyethylene bag demand despite municipal bans. Regional distributor relationships dominate sourcing decisions.
- Department Stores:Reusable bag programs and brand aesthetics justify premium substrate selection, with How2Recycle label integration becoming a baseline requirement.
- Online Retailers:E-commerce fulfillment demands lightweight, durable formats optimized for dimensional weight shipping economics rather than point-of-sale display.
Supermarkets anchor volume procurement. Online retailers are climbing fastest as fulfillment packaging specifications diverge from carry bag standards.
End User:
End-use segmentation tracks the regulatory intensity gradient from food-contact grocery applications to discretionary specialty retail.
- Grocery Stores:Food-contact compliance requirements under FDA and Health Canada rules force dual-SKU production for cross-border chains. ASTM D6400 certification is becoming a contract eligibility gate.
- Apparel Retailers:Brand-conscious merchants favor kraft paper with custom print surfaces and reusable totes that extend customer touchpoint duration beyond the transaction.
- Electronics Retailers:Anti-static and moisture-resistant specifications favor coated paper or multi-layer plastic formats with higher gauge tolerances.
- Specialty Shops:Premium positioning supports higher unit economics for boutique reusable bag programs and compostable formats that align with sustainability marketing.
Grocery stores dominate procurement scale. Specialty shops are expanding most quickly as premium positioning justifies certified substrate premiums.
Material:
Material selection bifurcates between legacy petroleum-based formats and fiber or biopolymer alternatives driven by extended producer responsibility frameworks.
- Low-Density Polyethylene:LDPE film extrusion serves high-clarity applications and lightweight carry formats where flexibility and seal strength are prioritized over rigidity.
- High-Density Polyethylene:HDPE's stiffness-to-weight ratio dominates t-shirt bag and merchandise sack production, though recycled content mandates are forcing resin re-engineering.
- Kraft Paper:Softwood fiber sourcing from Canadian and Southeastern US mill complexes underpins moisture-resistant grocery bag demand, with extrusion coating lines adding barrier properties.
- Non-Woven Fabric:Spunbond polypropylene serves reusable tote applications where stitch durability and print surface quality support repeat-trip utility and brand visibility.
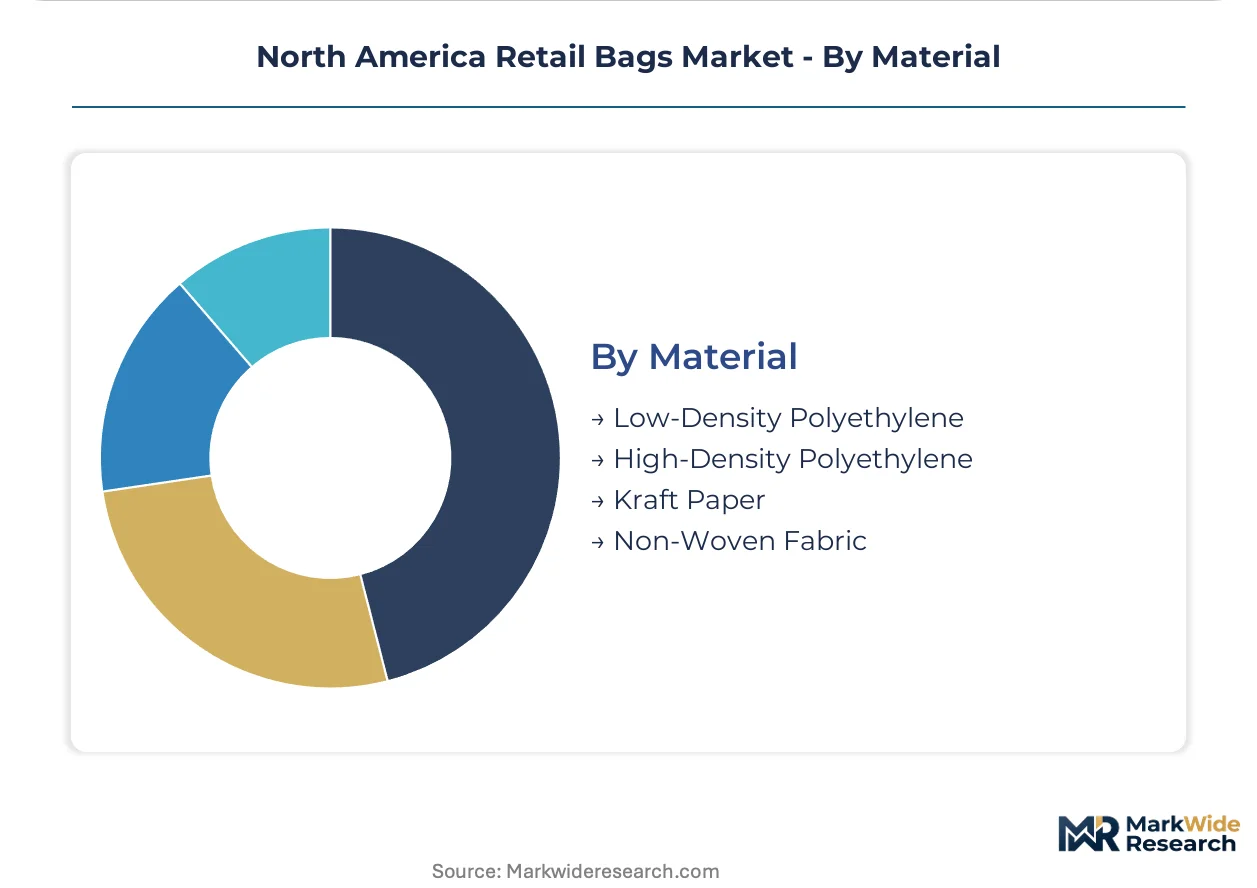
Polyethylene formats command the established base. Kraft paper is gaining share fastest as grocery channels accelerate plastic phase-out timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grocery chains and municipal procurement offices in California, New York, and Ontario drive the highest specification intensity for certified compostable and paper formats. Convenience retail and discount channels sustain polyethylene demand in enforcement-lagging jurisdictions.
United States
California's SB 54 mandates recycled content minimums and recyclability labeling for food-contact bags, compressing shelf space for conventional polyethylene variants. The EPA oversees municipal solid waste frameworks that influence bag disposal infrastructure economics. Midwestern mill clusters in Wisconsin and Michigan anchor kraft paper supply for grocery channel conversions.
Canada
Ontario's extended producer responsibility framework shifts disposal cost burdens upstream, accelerating procurement shifts toward certified compostable inventory. Health Canada governs chemical migration limits that diverge from US FDA thresholds, forcing dual-SKU production for cross-border retail chains. Prairie province mills in Alberta and Saskatchewan lag Ontario in municipal ban adoption, creating positioning windows for certified suppliers.
Mexico
Retail modernization in Mexico City and Monterrey metro corridors drives demand for branded reusable totes and kraft paper formats at department store and specialty retail banners. Federal environmental standards remain less prescriptive than California or New York mandates, sustaining polyethylene unit volumes in convenience and discount channels. Northern border states face cross-border supply chain influence from US converter networks.
North America Retail Bags Market Competitive Landscape
Player mix skews toward integrated paper and film converters with captive fiber or resin supply. Market structure concentrates around vertically integrated specialists controlling upstream material costs and certification-qualified tiers capturing grocery procurement consolidation. Strategic archetypes separate kraft paper mill-integrated suppliers, polyethylene film converters with regional distribution density, and certified compostable polymer specialists. Competitive moves center on ASTM D6400 certification acquisition and extrusion coating capacity additions for moisture-resistant grocery formats.
Within the integrated paper tier, Mondi Group PLC and Smurfit Kappa Group PLC exemplify mill-level backward integration that controls softwood fiber sourcing costs. Novolex Holdings Inc. anchors the film converter archetype with Midwest manufacturing footprint density. These three entities occupy positions that align with grocery channel sustainability scorecarding requirements and municipal procurement mandates in California and New York.
| Leading Market Players |
|---|
| Novolex Holdings Inc. |
| Smurfit Kappa Group PLC |
| Mondi Group PLC |
| El Dorado Packaging Inc. |
| International Paper company |
| Berry Global Inc. |
| Sealed Air Corporation |
| ProAmpac |
| Superbag Corporation |
| Others |
Value Network & Pricing Analysis
Ninety-day resin inventory cycles at Midwest polyethylene converters compress margin buffers when ethylene feedstock swings accelerate, tethering pricing power directly to captive supply arrangements and contract indexation clauses. California and New York grocery procurement offices exploit this vulnerability through sustainability scorecarding that extracts certified-compostable premiums from suppliers lacking backward integration into fiber or biopolymer sources.
Pricing Analysis
Cost-plus contracts indexed to ethylene and pulp futures dominate polyethylene and kraft paper tiers, with ASTM D6400 certification premiums separating qualified from commodity suppliers. Price differentiation centers on certification grade and volume scale, with national grocery banners leveraging consolidated procurement to compress conversion spreads. Pricing pressure stems from resin volatility and pulp logistics bottlenecks, while convenience store operators exhibit highest price sensitivity and specialty retailers absorb certified substrate premiums.
Supply Chain Analysis
Just-in-time resin delivery prevails among polyethylene converters, while paper bag manufacturers maintain strategic fiber stockpiles against Canadian mill concentration. Supply draws from United States, Canada, and Mexico, with softwood kraft fiber, ethylene feedstock, and PBAT-PLA biopolymer resins anchoring input dependencies. Tariff exposure on Canadian pulp imports constitutes the primary structural risk. Distribution runs through regional converter networks serving grocery banners and convenience distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against paper and certified-compostable formats displacing conventional polyethylene volumes. Incumbents must navigate regulatory compression in California and New York while securing captive fiber or resin supply.
For Market Incumbents: Compound ASTM D6400 certification acquisition with extrusion coating capacity additions in Wisconsin or Michigan mill corridors. Secure long-term softwood fiber offtake from Canadian Prairie suppliers before Ontario's extended producer responsibility framework tightens further. Certification investment represents the critical lever against grocery procurement consolidation.
For New Entrants and Emerging Players: Lead with certified-compostable polymer formulations targeting Alberta and Saskatchewan municipal procurement offices, where ban adoption lags Ontario and British Columbia. White-space concentration sits with Prairie province grocery chains seeking first-mover sustainability positioning. Go-to-market execution should anchor on How2Recycle label integration consulting.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated paper mill parents seeking to monetize retail bag divisions amid sustainability capital reallocation. Five-to-ten year viability favors vertically integrated kraft specialists over pure-play polyethylene converters. Monitor California SB 54 enforcement intensity as inflection signal for portfolio reweighting toward certified-compostable exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| ASTM D6400 Certification Investment | California and New York procurement mandates gate contract eligibility for grocery volumes. |
| Backward Integration into Softwood Fiber | Canadian Prairie mill proximity controls landed cost competitiveness for kraft paper conversions. |
| Extrusion Coating Capacity Addition | Moisture-resistant grocery bag specifications require barrier property investments at Midwest facilities. |
| How2Recycle Label Integration | Standardized recycling communication opens specification consulting revenue with national retail banners. |
| Reusable Bag Subscription Pilot | Deposit-return fabric programs convert single-trip transactions into recurring customer touchpoints. |
Research Methodology
Operator-level perspectives from bag manufacturing plant managers, grocery category buyers, municipal procurement officers, and resin distribution specialists anchored the qualitative base. Secondary validation drew from US EPA municipal solid waste reports, Health Canada chemical migration guidelines, ASTM certification registries, and trade customs data. Bottom-up volume modeling triangulated against top-down market sizing across material, channel, and end-use segments.
Sensitivity analysis tested forecast outputs against resin price volatility scenarios and regulatory acceleration cases across the projection horizon. Segmentation dimensions modeled include material certification tier, distribution channel concentration, end-use regulatory intensity, and regional enforcement gradient. CAGRs derived from trend extrapolation of conversion capacity additions and procurement shift velocities, with grocery channel sustainability scorecarding and municipal ban adoption curves serving as primary demand inputs.
Forecasts assume regulatory continuity in California SB 54, New York packaging laws, and Ontario extended producer responsibility frameworks; material policy shifts would require re-modeling. Pulp logistics disruptions, resin feedstock shocks, or federal preemption debates constitute specific revision triggers. Revision becomes warranted when industrial composting facility deployment crosses thresholds enabling ASTM D6400 bag end-of-life value realization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Waterproof Bags Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
MSW Bag Opener Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Bin Liners Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Mesh Bags Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Liquid Packaging Bag Market
Bags and Containers
Inner Bulk Liners Market