
 United States Plastic Packaging Films Market | 2026-2036
United States Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
United States Plastic Packaging Films Market Insights
Direct-to-retail film supply channels are rewriting procurement relationships between converters and grocery chains. Amcor leverages its multi-site North American manufacturing network to sustain consistent supply to national retailers. Berry Global anchors its position through backward integration into resin compounding and blown film extrusion. Sealed Air differentiates via proprietary barrier technologies for protein packaging applications.
Plastic packaging films are thin, flexible polymer sheets typically ranging from 10 to 150 microns in thickness, manufactured through cast or blown extrusion processes and engineered to provide moisture, oxygen, and light barrier protection for packaged goods. PE films dominate volume consumption across industrial and retail applications due to cost efficiency and sealability, while PET films command premium positioning in electronics and healthcare segments where optical clarity and dimensional stability matter. The food preservation application draws the thickest film specifications as processors shift toward vacuum skin packaging for fresh proteins.
FDA food contact regulations, EPA emissions standards for extrusion operations, and OSHA workplace exposure limits collectively shape resin selection, equipment investment, and plant location decisions for domestic film producers. State-level extended producer responsibility frameworks in California and New York are beginning to influence post-consumer recycling content mandates. Stakeholders must weigh circularity commitments against the technical limitations of mechanical recycling for multi-layer barrier structures.
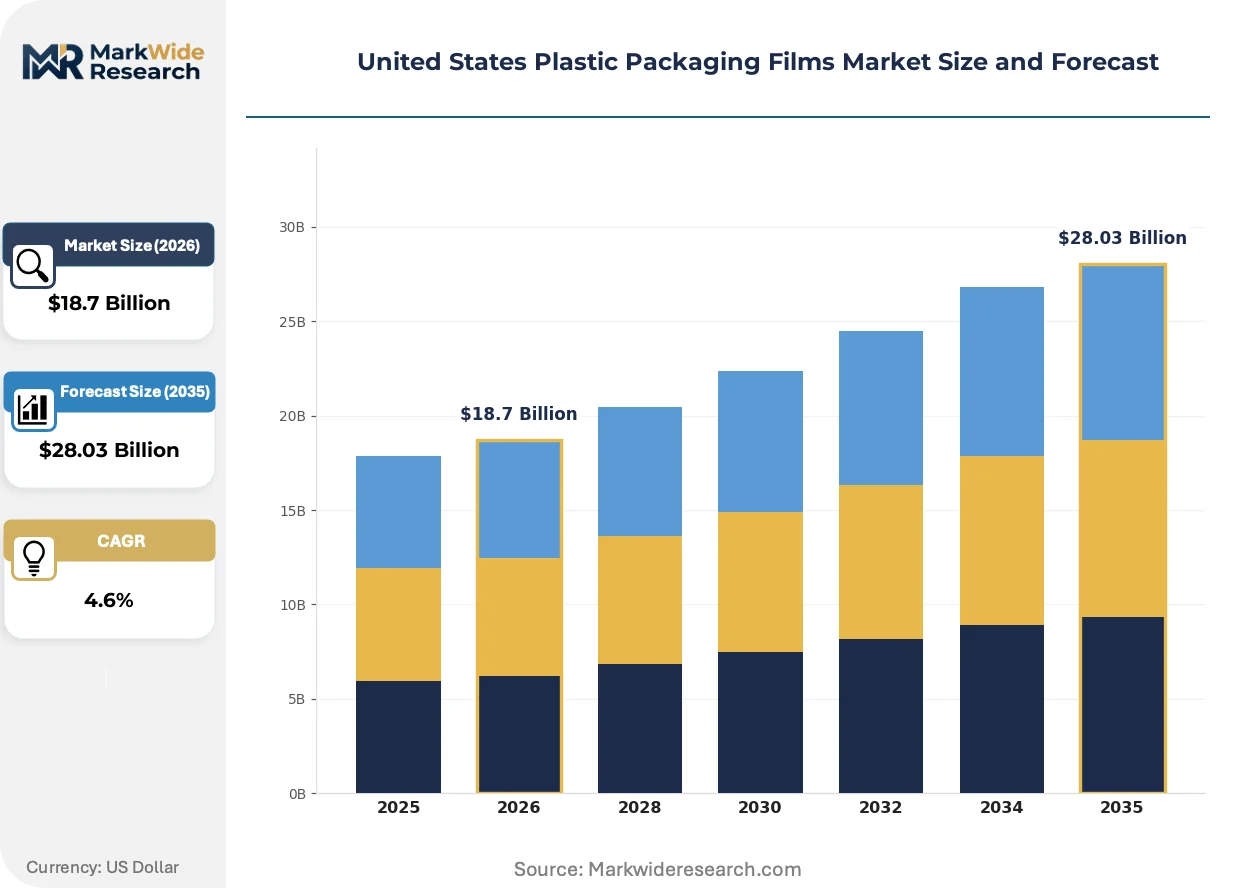
Market Dynamics
The FDA's evolving food contact substance notification requirements are forcing resin reformulation investments across the domestic compounder base. Midwest food processing clusters in Illinois and Wisconsin concentrate demand while reshaping regional supply chain configurations.
Growth Catalysts
- Modified-Atmosphere Packaging:Fresh food retail chains are expanding film deployment to extend produce shelf life, driving specification upgrades across protein and vegetable segments.
- Extended Producer Responsibility:California and New York state frameworks are mandating post-consumer recycled content thresholds, pulling investment into mechanical recycling infrastructure.
- Midwest Manufacturing Belt Concentration:Food processing clusters in Illinois and Wisconsin generate localized demand density that rewards proximate film extrusion capacity.
Market Restraints
- Resin Price Volatility:Ethylene and propylene feedstock exposure creates margin compression for non-integrated converters lacking captive resin supply.
- Multi-Layer Barrier Recycling Limitations:Current mechanical recycling infrastructure cannot process bonded polymer layers, constraining circularity claims for high-barrier meat and cheese packaging.
- OSHA Workplace Exposure Compliance:Extrusion operation ventilation and particulate monitoring requirements add fixed cost burdens to plant operations.
Strategic Opportunities
- Mono-Material Barrier Films:Single-polymer high-barrier structures compatible with existing recycling streams address EPR compliance while maintaining shelf-life performance.
- Direct-to-Retail Supply Channels:Grocery chains are consolidating procurement relationships, creating volume consolidation opportunities for converters with national manufacturing footprints.
- Vacuum Skin Packaging:Fresh protein processors are shifting from modified-atmosphere to vacuum skin formats, demanding thicker gauge specifications and specialized forming films.
Industry Challenges
- Compounder Technical Talent Scarcity:Resin formulation chemistry expertise required for FDA food contact compliance is concentrating among a shrinking pool of experienced domestic compounders.
- Blown Film Line Retrofit Costs:Barrier layer co-extrusion upgrades demand seven-figure capital commitments with extended payback periods under current resin pricing volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Plastic Packaging Films Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: PE, PP, PVC, PET End User Industry: Food & Beverage, Healthcare, Personal Care, Electronics Thickness: Lightweight, Standard, Heavy Duty, Ultra-Thin Application: Retail, Industrial Packaging, Food Preservation, Shrink Wrapping |
| Companies Covered | Sealed Air, Cosmo Films, Amcor, Pactiv Evergreen, Taghleef Industries, Berry Global, Flex Films (USA) Inc., Sonoco, Profol Americas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Plastic Packaging Films Market Trends and Innovations
Film specification evolution is compressing traditional product lifecycles as barrier performance demands collide with circularity mandates. Three active shifts are restructuring converter investment priorities and customer procurement criteria.
Mono-material polyethylene barrier films with plasma-enhanced surface treatments are rendering obsolete conventional multi-layer EVOH and nylon structures in fresh protein packaging. National grocery retailers are accelerating qualification timelines for these recyclable alternatives. The shift is compressing R&D amortization periods for incumbent barrier technology suppliers.
EPA emissions standards for extrusion operations are tightening volatile organic compound thresholds, forcing thermal oxidizer installations or solvent-free adhesive conversions. Smaller regional converters face disproportionate compliance cost burdens relative to integrated producers with centralized environmental controls. The regulation is accelerating plant consolidation in the Ohio River Valley extrusion corridor.
Brand-led packaging reduction commitments are shortening film gauge tolerance windows and eliminating over-specification buffers previously built into retailer technical standards. Protein processors are accepting thinner structures with equivalent barrier performance through advanced orientation techniques. The recalibration is most visible in Wisconsin dairy and Illinois beef packaging operations where direct converter-retailer technical collaboration has replaced distributor-mediated specification setting.
United States Plastic Packaging Films Market Segmentation
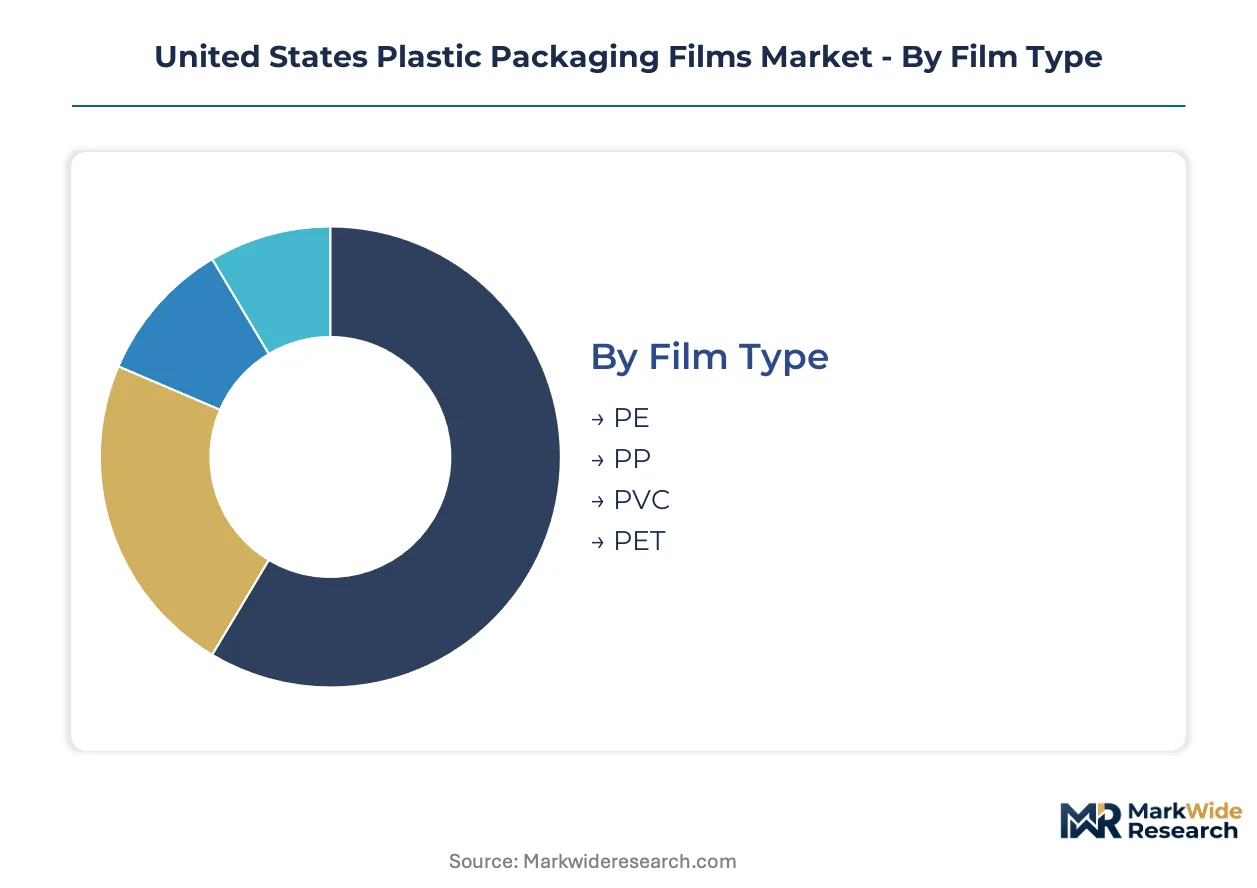
Segmentation in the United States plastic packaging films market reveals how resin chemistry, end-use performance requirements, and gauge specifications create distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure.
Film Type:
Use-case spectrum spans from commodity bulk packaging to precision barrier applications, with resin selection dictating recyclability pathways and FDA compliance burden.
- PE:Polyethylene films dominate volume throughput across stretch wrap, retail carry bags, and food storage applications due to sealability and mechanical recycling compatibility. Midwest food processors in Illinois and Wisconsin specify PE for modified-atmosphere produce packaging where oxygen transmission rates below 5 cc/m²/day are required.
- PP:Polypropylene films command premium positioning in high-clarity retail and microwaveable food trays where dimensional stability above 120°C matters. Demand concentrates in Wisconsin dairy operations for thermoformed cheese packaging where FDA food contact substance notification requirements drive resin grade selection.
- PVC:Chlorinated polymer films retain niche use in medical device blister packs and shrink sleeve labeling where clarity and dielectric sealing properties justify regulatory compliance costs.
- PET:Polyester films anchor electronics and healthcare segments requiring optical clarity above 90% haze-free transmission and dimensional stability under humidity cycling.
The dominant share belongs to PE, while PP is closing the gap fastest as protein processors shift toward vacuum skin packaging formats demanding higher thermal resistance.
End User Industry:
Customer concentration varies sharply by regulatory intensity and specification volatility, with food contact applications driving the steepest reformulation cycles.
- Food & Beverage:Modified-atmosphere and vacuum skin packaging specifications for fresh proteins and produce generate the thickest film demand. California and New York extended producer responsibility mandates are pulling recycled content requirements into retailer procurement contracts.
- Healthcare:Sterile barrier systems for medical devices demand particulate-free manufacturing environments and lot-level traceability. FDA 21 CFR compliance for indirect food contact resins overlaps with USP Class VI biocompatibility testing.
- Personal Care:Flexible sachets and pillow pouches for cosmetics and toiletries prioritize printability and fragrance barrier over oxygen exclusion.
- Electronics:Static-dissipative films for semiconductor and display component shipping require controlled surface resistivity between 10⁴ and 10¹¹ ohms per square.
Food & Beverage retains the volume anchor position, though Healthcare is expanding most quickly as domestic medical device manufacturing reshoring accelerates.
Thickness:
Gauge specification directly determines extrusion line output rates, resin consumption per unit area, and the technical feasibility of downgauging for sustainability claims.
- Lightweight:Films below 25 microns serve overwrap and secondary bundling where tensile strength requirements are minimal. Retailers are pushing gauge reductions here to meet packaging reduction commitments.
- Standard:25-75 micron specifications balance barrier performance with processing efficiency across the broadest application set.
- Heavy Duty:Gauges above 75 microns accommodate vacuum skin packaging for fresh beef and pork where puncture resistance and deep draw forming are essential. Illinois beef processors are specifying 100+ micron structures for direct-to-retail case-ready programs.
- Ultra-Thin:Sub-12 micron films for pharmaceutical strip packaging and precision electronics wrapping demand specialized extrusion die technology and tension control.
Standard gauges hold the installed base majority, yet Heavy Duty specifications are gaining share fastest as protein processors eliminate foam tray secondary packaging.
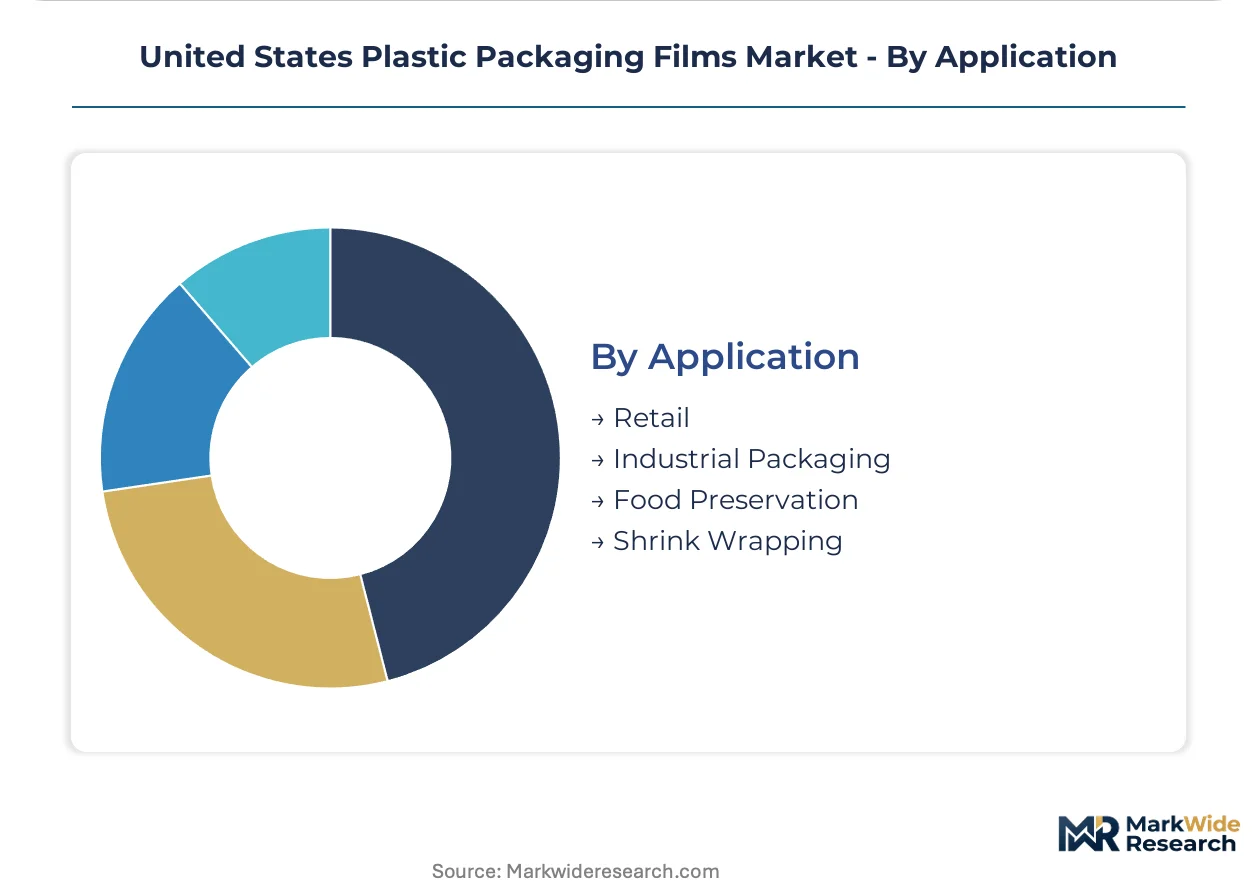
Application:
Functional performance requirements and supply chain configuration diverge between retail-facing and industrial end-uses.
- Retail:Consumer-facing films require print registration accuracy and shelf appeal through haze control and gloss surface treatments. Direct-to-retail supply channels are consolidating procurement around converters with national manufacturing footprints.
- Industrial Packaging:Stretch wrap and pallet unitization films prioritize load containment force and puncture propagation resistance over optical properties. Midwest manufacturing belt concentration rewards proximate extrusion capacity.
- Food Preservation:Barrier performance for protein and produce shelf-life extension drives the most complex multi-layer co-extrusion specifications. Mono-material recyclable alternatives are displacing EVOH and nylon structures.
- Shrink Wrapping:Biaxially oriented films for beverage multipacks and printed label sleeves require controlled shrink force curves to prevent container distortion.
Industrial Packaging maintains the volume leadership, while Food Preservation is climbing the fastest as modified-atmosphere specifications penetrate vegetable segments beyond proteins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level extended producer responsibility frameworks are redirecting capital toward Midwest extrusion corridors and coastal recycling infrastructure. The FDA's evolving food contact substance notification requirements are concentrating technical expertise near food processing clusters. Regional supply chain configurations are hardening around proximity to resin compounding capacity and retail distribution density.
California
Extended producer responsibility mandates under SB 54 are mandating post-consumer recycled content thresholds for flexible packaging. CalRecycle enforcement timelines are accelerating converter qualification of mechanically recycled PE streams. Los Angeles Basin food distributors are consolidating procurement around suppliers with verified circularity certifications.
Illinois
Chicago-area beef and pork processors are specifying heavy-duty vacuum skin packaging films above 100 microns for direct-to-retail case-ready programs. EPA Region 5 air quality permits for extrusion operations are requiring thermal oxidizer installations or solvent-free adhesive conversions. The I-55 corridor from Joliet to Bloomington-Normal hosts the densest concentration of blown film capacity serving protein packaging demand.
Wisconsin
Dairy processors in the Fox River Valley are thermoforming PP films for cheese packaging where FDA food contact substance notification requirements drive resin grade selection. OSHA workplace exposure limits for extrusion particulates are adding fixed cost burdens to plant operations. Green Bay and Appleton manufacturing clusters reward proximate film supply through reduced freight costs for temperature-sensitive dairy products.
New York
The state's extended producer responsibility framework is pulling investment into mechanical recycling infrastructure for multi-layer film recovery. Department of Environmental Conservation rulemaking is aligning with California's recycled content mandates. Rochester and Buffalo converters are qualifying mono-material barrier films to service Northeast grocery retailer procurement contracts.
Ohio
EPA emissions standards for volatile organic compounds are tightening across the Ohio River Valley extrusion corridor. Cincinnati and Dayton regional converters face disproportionate compliance cost burdens relative to integrated producers with centralized environmental controls. The concentration of stretch wrap and industrial packaging demand from Midwest manufacturing belt distribution centers sustains gauge-optimized PE film production.
United States Plastic Packaging Films Market Competitive Landscape
On the supply side, the industry is consolidating around integrated producers with captive resin compounding and national manufacturing footprints. Three strategic archetypes dominate competitive positioning: multi-site North American converters with direct-to-retail supply channels, backward-integrated compounders controlling resin formulation chemistry, and specialists in proprietary barrier technologies for protein packaging. Dominant competitive moves include capacity consolidation through strategic partnerships and portfolio diversification into mono-material recyclable structures.
Among the named players, Sealed Air, Amcor, and Berry Global exemplify the three archetypes. Sealed Air occupies a position within the proprietary barrier technology tier. Amcor anchors the multi-site North American manufacturing network segment. Berry Global represents backward integration into resin compounding and blown film extrusion capacity.
| Leading Market Players |
|---|
| Sealed Air |
| Cosmo Films |
| Amcor |
| Pactiv Evergreen |
| Taghleef Industries |
| Berry Global |
| Flex Films (USA) Inc. |
| Sonoco |
| Profol Americas |
| Others |
Pricing and Supply Chain Analysis
Ethylene feedstock volatility determines both pricing tier spreads and supply chain shape across the United States plastic packaging films market, compressing margins for non-integrated converters while rewarding compounders with captive resin supply. FDA food contact substance notification requirements add compliance cost layers that stratify pricing across certification-grade boundaries.
Pricing Analysis
Certification level creates the primary spread between FDA food contact compliant films and industrial-grade alternatives, with PE barrier structures commanding premium positioning over commodity stretch wrap. Volume scale drives secondary differentiation as national grocery chains consolidate procurement around converters with multi-site manufacturing footprints. Cost compression in standard-grade PE films is intensifying because Midwest food processors are eliminating over-specification buffers and accepting thinner gauge structures. Small regional converters show highest price sensitivity due to disproportionate compliance cost burdens relative to integrated producers.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates supply chain risk calculations for resin compounders serving the Great Lakes extrusion corridor. Geographic supply concentration centers on Texas and Louisiana for ethylene feedstock, Ohio and Illinois for blown film extrusion capacity, and California for post-consumer recycling infrastructure. Raw material dependencies rest on naphtha and natural gas liquids for ethylene production, calcium carbonate for filler masterbatch, and adhesive resins for lamination. Distribution runs through direct-to-retail channels consolidating around national grocery chain procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
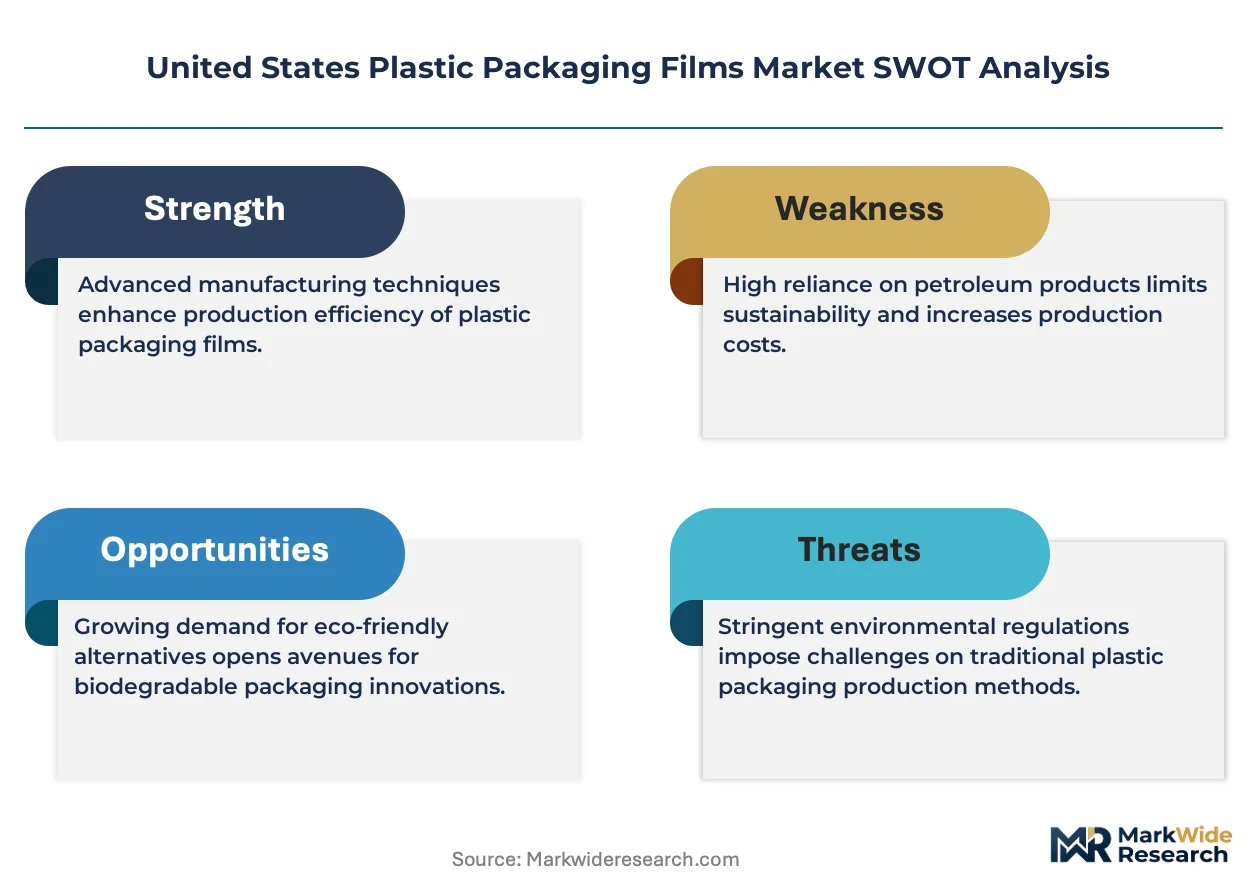
Mono-material barrier film innovation represents a high-growth disruption as California and New York extended producer responsibility mandates force rapid qualification of recyclable alternatives. The regulatory inflection compresses traditional multi-layer technology lifecycles and rewards first-movers with circularity-certified capacity.
For Market Incumbents: Insulate margin position through backward integration into resin compounding and captive supply of FDA-compliant food contact grades. Accelerate thermal oxidizer installations or solvent-free adhesive conversions ahead of EPA emissions standard tightening. Defend against mono-material displacement by acquiring plasma surface treatment technology specialists. For New Entrants and Emerging Players: Regional dairy processors in Wisconsin and protein packagers in Illinois represent the most penetrable entry points given localized demand density and incumbent supply constraints. Mono-material PE barrier films for vacuum skin packaging applications offer specification upgrade opportunities without multi-layer co-extrusion capital requirements. Pursue direct technical collaboration with retailer sustainability procurement teams rather than distributor-mediated channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated producers with circularity infrastructure and national manufacturing footprints. Long-term viability hinges on mechanical recycling compatibility and verified post-consumer content supply chains. Watch California CalRecycle enforcement timelines as the inflection signal for accelerated EPR compliance investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of FDA food contact grades insulates margin from ethylene volatility. |
| Mono-Material Barrier Film Development | Plasma-enhanced PE structures satisfy California SB 54 recycled content mandates. |
| Thermal Oxidizer Installation | EPA Region 5 air quality compliance enables continued Ohio River Valley operations. |
| Direct-to-Retail Supply Channel Establishment | National grocery chain procurement consolidation rewards proximate extrusion capacity. |
| Vacuum Skin Packaging Capacity Expansion | Illinois beef processors specify 100+ micron structures for case-ready programs. |
Research Methodology
Desk research of FDA food contact substance notifications, EPA emissions compliance filings, and trade association resin consumption data preceded structured interviews with blown film plant managers, grocery chain packaging procurement directors, and resin compounder technical directors. Primary fieldwork across the Midwest manufacturing belt captured operational constraints and qualification timelines for mono-material alternatives. Secondary validation drew from American Chemistry Council reports, SEC 10-K filings of integrated producers, and CalRecycle regulatory dockets. Bottom-up demand modeling triangulated against top-down resin consumption aggregates.
Assumptions held fixed include FDA food contact notification processing timelines, California SB 54 recycled content phase-in schedules, and ethylene feedstock cost pass-through elasticity. Variables tested across the projection horizon encompassed EPR framework adoption in additional states, mechanical recycling yield rates for multi-layer structures, and protein processor shift rates from modified-atmosphere to vacuum skin formats. Segmentation dimensions modeled include resin chemistry, end-use industry, gauge specification, and application function. CAGRs derived from unit consumption growth applied to resin price trajectory scenarios.
Practitioners should monitor EPA Region 5 permit issuance patterns and CalRecycle enforcement acceleration for early signals of regulatory cost compression. Forecasts reflect assumptions about circularity infrastructure buildout pace and retailer procurement consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Polyethylene Terephthalate (PET) Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Corrugated Plastic Box Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Blow Moulded Plastic Packaging Market