
 Poland Plastic Bottles Market | 2026-2036
Poland Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Plastic Bottles Market Insights
Private-label beverage bottlers are unwinding share from traditional dairy and edible-oil packagers across Poland's plastic bottles sector. Berry Global Inc. leverages pan-European blow-molding capacity to serve Polish retail chains with standardized PET formats. Alpla Group anchors regional supply through its dedicated Polish production footprint, while Plastan Kacprzyk SP. Z O.O. specializes in custom HDPE containers for domestic chemical and cosmetic brands.
Plastic bottles are hollow thermoplastic containers manufactured through extrusion blow molding, injection blow molding, or stretch blow molding, typically ranging from 50 milliliters to 20 liters in capacity and engineered for barrier protection, stackability, and label adhesion. PET bottles dominate Poland's beverage and personal care segments due to clarity, lightweighting potential, and established recycling streams via rPET integration. HDPE bottles capture pharmaceutical and household care applications where chemical resistance and opaque protection command premium positioning. Closure type selection increasingly tracks end-use safety requirements, with tamper-evident caps expanding in pharmaceutical and premium food segments.
Polish packaging converters navigate overlapping compliance obligations from EU REACH chemical registration, the EU Single-Use Plastics Directive setting mandatory recycled content floors, and BIS-equivalent Polish Committee for Standardization (PKN) quality certifications for food-contact materials. These frameworks elevate capital requirements for resin traceability and testing documentation, filtering smaller molders from pharmaceutical and export-qualified supply chains. Stakeholders must monitor pending revisions to extended producer responsibility fee structures, as these will recalibrate the economics of virgin versus recycled feedstock procurement.
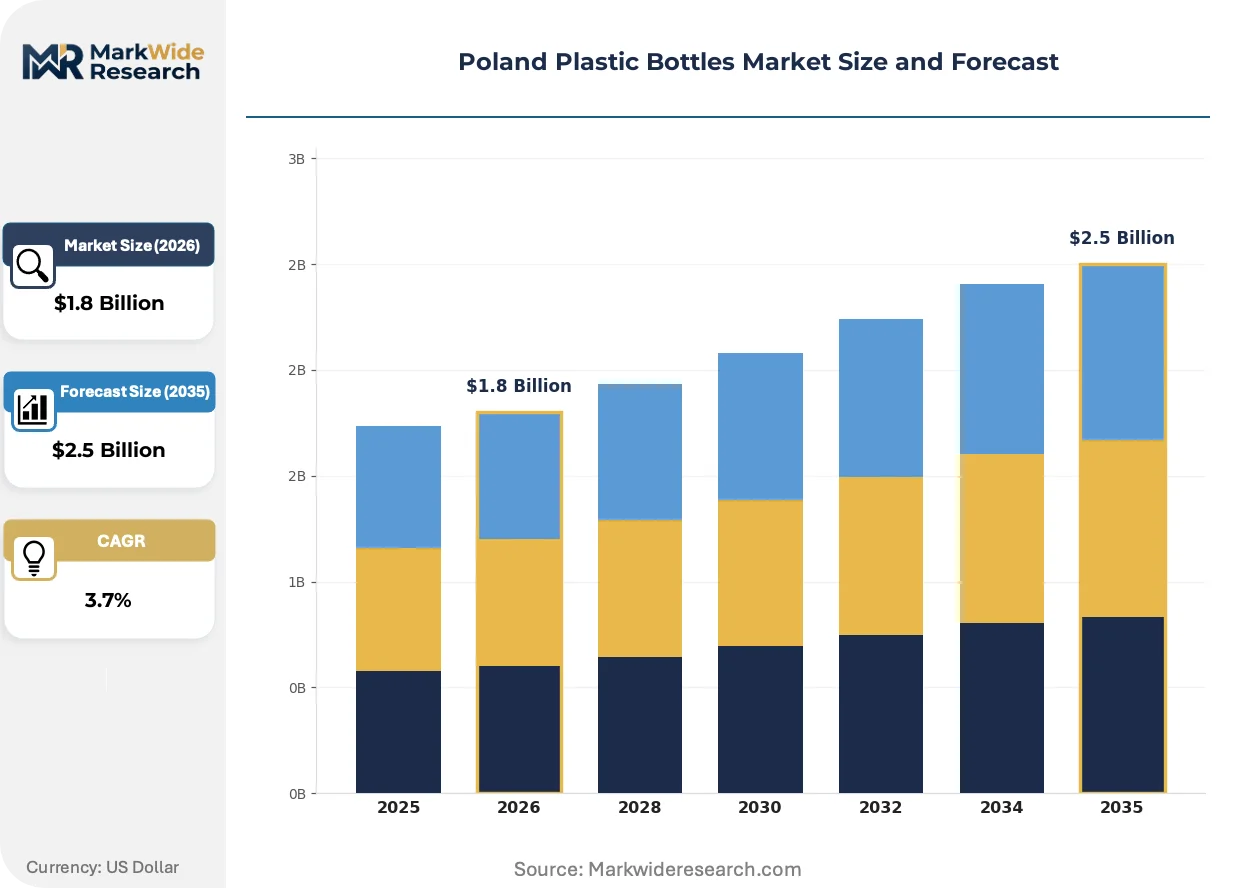
Market Dynamics
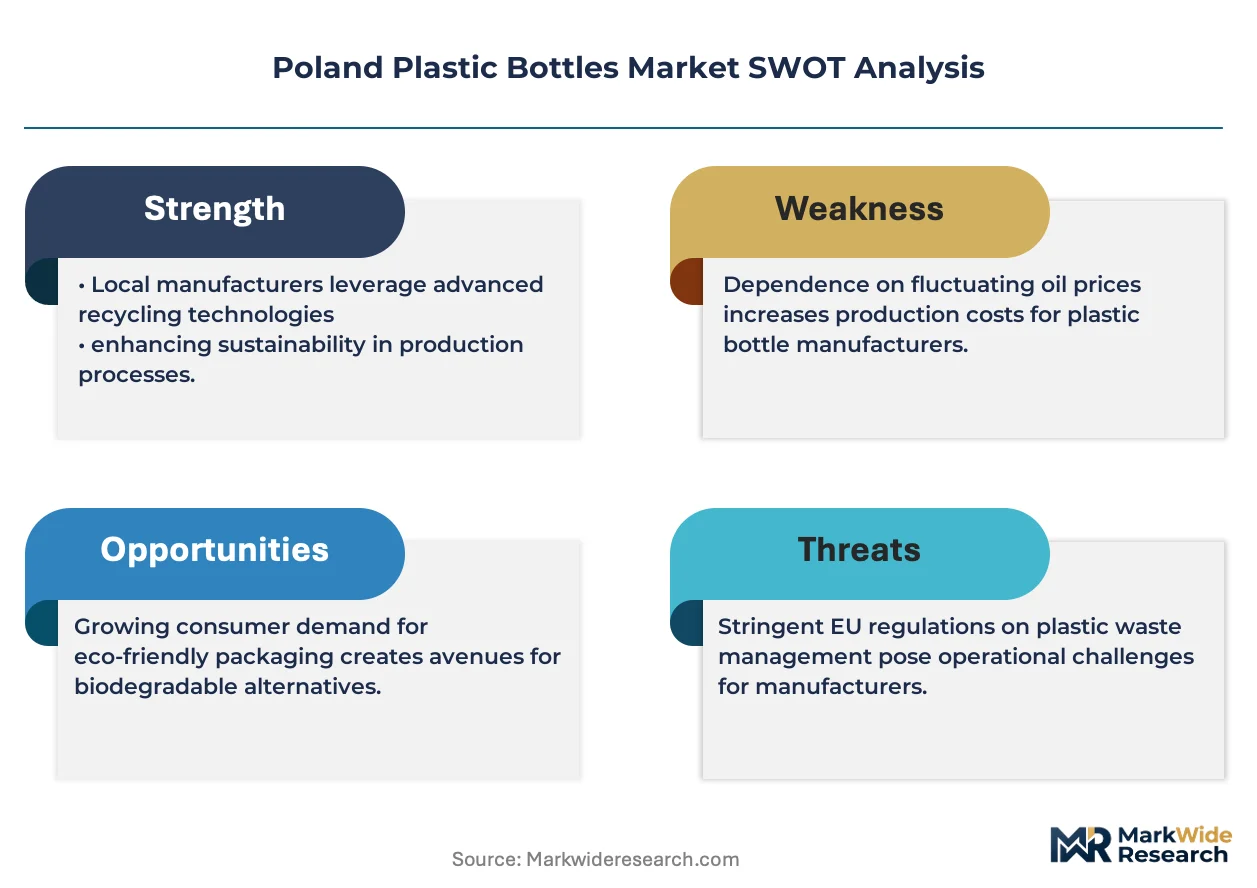
The EU Single-Use Plastics Directive is compressing converter margins as recycled PET feedstock premiums widen against virgin resin, forcing Polish molders to reengineer blow-molding lines for rPET compatibility while maintaining optical clarity standards.
Growth Catalysts
- Masovian logistics corridor:Just-in-time delivery networks surrounding Warsaw enable beverage bottlers to slash inventory carrying costs and respond to retail promotional cycles within 48-hour windows.
- REACH chemical registration:Harmonized EU safety documentation allows Polish converters to export food-contact bottles across the single market without redundant national testing protocols.
- Stretch blow molding:Lightweighting technology reduces PET gram weights by 15-20% per bottle, cutting resin consumption and transport fuel costs for FMCG brands.
Market Restraints
- rPET feedstock volatility:Post-consumer flake supply concentrates in Western European collection systems, exposing Polish converters to freight surcharges and quality inconsistency.
- Energy cost structure:Natural gas-dependent extrusion blow-molding operations face input cost spikes during winter demand peaks, eroding contract profitability.
- HDPE substitution ceiling:Barrier performance limitations prevent polyethylene bottles from penetrating carbonated beverage segments where PET dominates.
Strategic Opportunities
- Lesser Poland pharmaceutical cluster:Kraków-region drug manufacturers seek compliant HDPE packaging for light-sensitive formulations, creating premium positioning for certified molders.
- Extended producer responsibility fee revisions:Pending Polish ministry adjustments to EPR modulation fees will reward high-recycled-content bottles with reduced compliance levies.
- Smart closure integration:Convergence of NFC-enabled caps with tamper-evident designs opens traceability contracts for premium spirits and cosmetic brands.
Industry Challenges
- rPET processing expertise gap:Blow-molding technicians trained on virgin resin struggle to manage IV degradation and yellowing in recycled feedstock streams.
- PKN food-contact certification timelines:Polish Committee for Standardization documentation reviews extend 4-6 months, delaying new product launches for export-bound converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Plastic Bottles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET Bottles, HDPE Bottles, LDPE Bottles, PVC Bottles End Use Industry: Food & Beverage, Personal Care, Household Care, Pharmaceuticals Closure Type: Screw Caps, Snap-On Caps, Sport Caps, Tamper Evident Caps Shape: Round, Square, Recycled, Custom Shapes |
| Companies Covered | Gerresheimer AG, Berry Global Inc., Alpla Group, CANPACK, Embaco A/S, Plastan Kacprzyk SP. Z O.O., Polimer sp. z o.o., Goodway Plastic Products, PetRing Sp. z o.o., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Plastic Bottles Market Trends and Innovations
Lightweighting technologies and regulatory compliance automation are redefining competitive advantage across Poland's plastic bottle sector. Converters investing in process digitization and material science capabilities are capturing share from legacy operators.
Mono-material PET bottle designs are eliminating multi-layer barrier structures and incompatible label adhesives to streamline mechanical recycling streams. Beverage bottlers in Poland are adopting these formats ahead of 2025 EPR fee incentives. The technology is miniaturizing separation costs for waste processors and improving rPET yield rates.
EU Single-Use Plastics Directive recycled content mandates are forcing resin procurement restructuring across Polish converter supply chains. The regulation requires 25% recycled plastic in PET beverage bottles by 2025, compelling molders to secure long-term rPET offtake agreements. Smaller operators lacking balance-sheet capacity for forward contracting are exiting pharmaceutical and export-qualified segments.
Direct procurement relationships between retail chains and converters are displacing traditional distributor intermediaries in Warsaw and Łódź corridors. Discounters and private-label beverage brands now negotiate volume commitments directly with Berry Global and Alpla production facilities. The shift concentrates order books among pan-European suppliers with dedicated Polish blow-molding assets.
Poland Plastic Bottles Market Segmentation
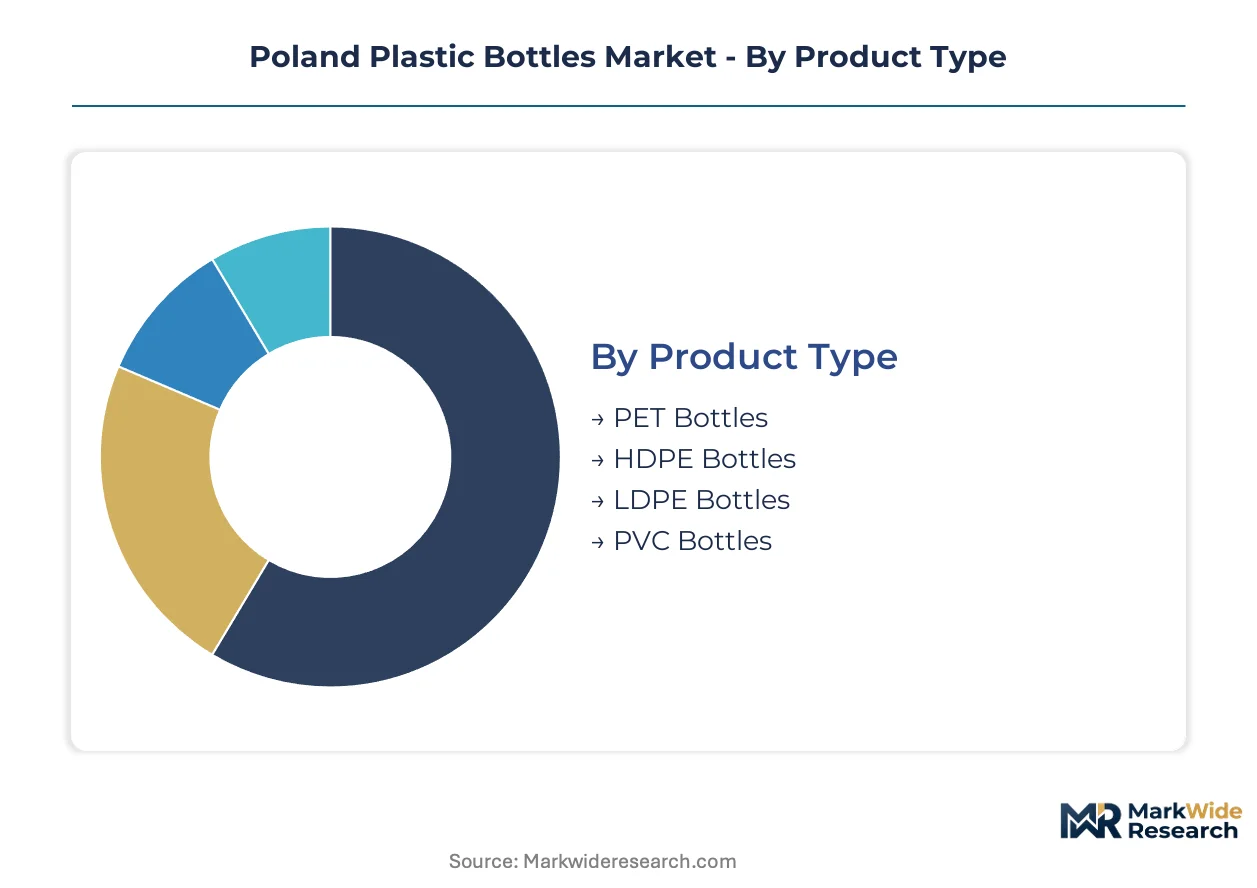
Segmentation in Poland's plastic bottles market tracks how resin chemistry, closure engineering, and container geometry align with distinct supply chain economics. Each dimension reveals where converters capture margin and where regulatory pressure reshapes procurement priorities.
Product Type:
Channel mix varies sharply by resin: PET dominates beverage direct-to-retail supply chains, while HDPE and specialty polymers flow through chemical and pharmaceutical distributors with stricter certification requirements.
- PET Bottles:Clear thermoplastic polyester formed through stretch blow molding delivers lightweight, barrier-protected containers. Beverage bottlers in the Masovian corridor command the largest procurement volumes, driven by on-the-go consumption formats and rPET compliance deadlines under the EU Single-Use Plastics Directive.
- HDPE Bottles:Opaque high-density polyethylene resists chemical permeation and provides UV protection for sensitive formulations. Pharmaceutical manufacturers in Lesser Poland's Kraków cluster specify certified HDPE for light-sensitive drugs, creating premium positioning for converters with PKN food-contact documentation.
- LDPE Bottles:Low-density polyethylene offers squeeze flexibility for dispensing applications. Domestic cosmetic brands source LDPE containers through specialized converters serving mid-tier personal care distributors.
- PVC Bottles:Polyvinyl chloride provides rigid barrier properties for industrial chemical storage. Niche demand concentrates in agricultural and automotive fluid packaging where chemical compatibility overrides sustainability preferences.
By volume, PET bottles lead. By growth pace, HDPE pharmaceutical applications are climbing the fastest.
End Use Industry:
Margin structures diverge by customer procurement sophistication: FMCG brands negotiate long-term volume contracts, while pharmaceutical and specialty chemical buyers pay certification premiums.
- Food & Beverage:Carbonated soft drinks, bottled water, and edible oils drive PET procurement at scale. Retail chain direct sourcing in Warsaw and Łódź corridors compresses distributor margins and concentrates orders among pan-European blow-molders.
- Pharmaceuticals:Oral dosage and topical formulations require light-resistant HDPE with tamper-evident closures. Kraków-region drug manufacturers prioritize converters with validated sterilization compatibility and PKN export certification.
- Personal Care:Shampoos, lotions, and cosmetics favor PET clarity or LDPE squeeze functionality. Private-label brands source through packaging distributors serving Poland's retail pharmacy chains.
- Household Care:Detergents, disinfectants, and cleaning agents specify chemical-resistant HDPE or PVC. Industrial buyers in Silesian manufacturing zones prioritize container durability over recycled content ratios.
Food & Beverage commands the largest volume share. Pharmaceuticals delivers the steepest margin expansion trajectory.
Closure Type:
Closure selection increasingly determines which converters qualify for premium segments, with tamper-evident and smart-cap designs filtering supplier pools.
- Screw Caps:Threaded polypropylene closures provide resealable convenience across beverage and household applications. Standardized 28mm and 38mm formats dominate high-volume FMCG procurement.
- Tamper Evident Caps:Break-ring or shrink-band designs signal first-open integrity. Pharmaceutical and premium spirits brands in Masovian and Lesser Poland corridors mandate these closures for regulatory compliance and brand protection.
- Snap-On Caps:Press-fit closures enable single-handed dispensing for personal care and household products. Mid-tier cosmetic brands favor snap-on designs for shelf differentiation.
- Sport Caps:Push-pull or flip-top mechanisms target active consumption occasions. Bottled water and isotonic drink brands specify sport closures for convenience-store and gym channel distribution.
Screw caps lead by installed base. Tamper-evident designs are gaining share fastest among premium segment suppliers.
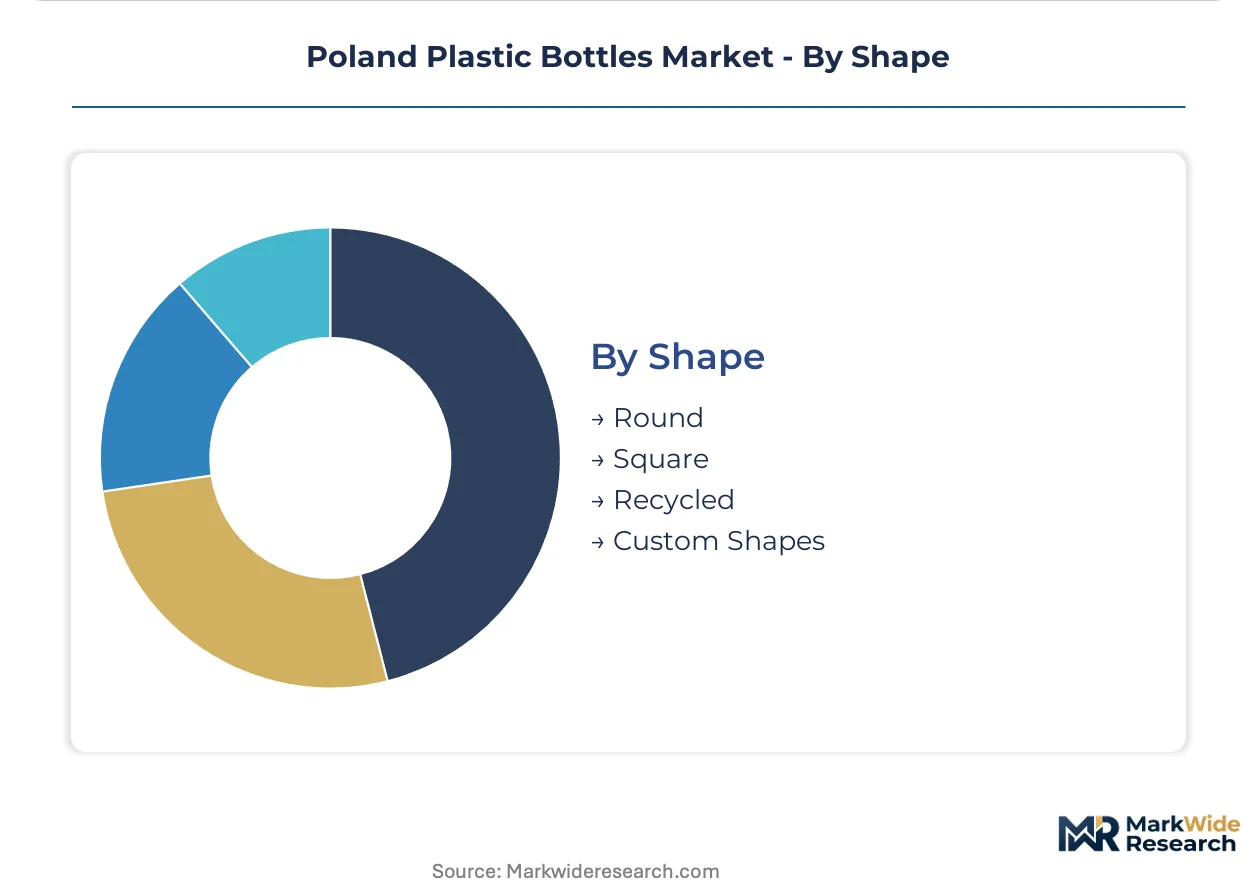
Shape:
Geometry decisions balance shelf presence, pallet density, and recycling stream compatibility, with sustainability pressures favoring standardized formats.
- Round:Cylindrical profiles maximize internal pressure resistance for carbonated beverages and optimize blow-molding cycle speeds. Round PET bottles dominate Warsaw-region beverage production.
- Square:Rectangular cross-sections improve pallet cube utilization and shelf-facing efficiency. Edible oil and household chemical brands specify square HDPE for logistics cost reduction.
- Recycled:Post-consumer rPET or mechanically recycled HDPE formats align with EU Single-Use Plastics Directive mandates. Beverage bottlers adopt these ahead of EPR fee modulation adjustments.
- Custom Shapes:Proprietary molds deliver brand differentiation for premium cosmetics and gift-market spirits. Lower volumes and higher tooling costs limit adoption to niche positioning strategies.
Round bottles dominate volume throughput. Recycled formats are expanding most quickly as compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters along Poland's central logistics spine, with blow-molding assets concentrating where rail and road networks enable just-in-time replenishment of Warsaw and Łódź retail distribution centers.
Masovian Voivodeship
Beverage bottlers in the Warsaw corridor command the largest PET procurement volumes, driven by carbonated soft drink and bottled water demand from retail chains. The EU Single-Use Plastics Directive recycled content mandates are forcing local converters to secure rPET supply contracts ahead of 2025 deadlines. Industrial parks in Radom and Płock host dedicated blow-molding facilities serving pan-European FMCG brands.
Lesser Poland Voivodeship
Pharmaceutical packaging demand from Kraków-region drug manufacturers is accelerating HDPE bottle procurement for light-sensitive oral dosage formulations. Polish Committee for Standardization (PKN) food-contact certification requirements filter supplier pools to converters with validated sterilization protocols. The Nowa Huta industrial zone anchors specialized chemical-resistant container production for domestic generic drug exporters.
Silesian Voivodeship
Household care and industrial chemical bottlers in the Katowice-Gliwice corridor specify durable HDPE and PVC containers where chemical resistance outweighs sustainability preferences. Energy-intensive extrusion blow-molding operations face margin pressure from natural gas price volatility during winter heating peaks. The Upper Silesian Industrial Region retains legacy chemical packaging infrastructure serving Polish and Czech manufacturing zones.
Łódź Voivodeship
Central Poland's textile-to-packaging industrial transition has attracted stretch blow-molding investments targeting lightweight PET formats for edible oil and personal care brands. Direct procurement relationships between retail chains and converters are displacing traditional distributor intermediaries. The Łódź Special Economic Zone offers tax incentives for packaging machinery upgrades enabling rPET processing compatibility.
Pomeranian Voivodeship
Gdańsk and Gdynia port infrastructure supports export-oriented bottle production for Nordic and Baltic markets, with converters leveraging maritime freight advantages over land-based Western European supply routes. REACH chemical registration harmonization allows PKN-certified molders to ship food-contact bottles across the EU single market without redundant national testing. The Tricity logistics hub enables 48-hour delivery windows to Scandinavian retail procurement centers.
Poland Plastic Bottles Market Competitive Landscape
Concentration sits with pan-European packaging conglomerates operating dedicated Polish production footprints, while mid-tier domestic specialists capture niche pharmaceutical and chemical segments through certification depth. The competitive terrain splits between scale-driven blow-molders serving high-volume beverage contracts and regional fabricators delivering custom HDPE formats. Strategic moves center on rPET supply chain integration and direct retail chain partnerships that bypass traditional distribution layers.
Among pan-European suppliers with Polish assets, Berry Global Inc. and Alpla Group exemplify the scale-driven archetype with standardized PET production serving FMCG procurement consolidation. Plastan Kacprzyk SP. Z O.O. represents the domestic specialist tier, occupying a position in custom HDPE container fabrication for certified pharmaceutical and cosmetic applications. These three anchors illustrate the market's bifurcation between volume efficiency and regulatory compliance depth.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Berry Global Inc. |
| Alpla Group |
| CANPACK |
| Embaco A/S |
| Plastan Kacprzyk SP. Z O.O. |
| Polimer sp. z o.o. |
| Goodway Plastic Products |
| PetRing Sp. z o.o. |
| Others |
Pricing and Supply Chain Analysis
Long-term rPET offtake contracts lock in both feedstock access and price visibility for Polish converters navigating EU Single-Use Plastics Directive compliance deadlines. These agreements insulate beverage bottlers from virgin resin volatility while committing molders to fixed-volume minimums that reshape working capital requirements.
Pricing Analysis
Volume-discount tiering structures separate pan-European blow-molders from domestic specialists across Poland's plastic bottles sector. Three-tier pricing stratifies across premium certified pharmaceutical grades, standard food-contact tiers, and economy non-export formats. Price differentiation hinges on PKN certification depth and rPET content ratios. Cost compression in standard PET beverage tiers is intensifying as retail chains consolidate direct procurement. Pharmaceutical buyers show lowest price sensitivity due to sterilization validation requirements.
Supply Chain Analysis
Inbound logistics costs from Western European rPET collection hubs expose Polish converters to freight surcharges and flake quality inconsistency. Raw material sourcing draws from Germany, Italy, and domestic post-consumer streams. Virgin PET resin supply rests on Middle Eastern and Asian petrochemical exports. Single-source vulnerability concentrates in rPET flake procurement where collection infrastructure lags demand. Distribution runs through just-in-time rail networks serving Masovian and Łódź retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's plastic bottles market operates as a defensive-moat story where regulatory entrenchment creates durable barriers. PKN certification timelines and rPET processing expertise gaps filter supplier pools in ways that protect validated incumbents.
For Market Incumbents: Shield market position by deepening backward integration into rPET flake processing and securing captive supply agreements with Western European collection systems. The rPET processing expertise gap threatens converters dependent on spot feedstock markets. Capacity addition in Lesser Poland's pharmaceutical corridor captures premium HDPE demand from Kraków-region drug manufacturers. For New Entrants and Emerging Players: Custom small-batch HDPE fabrication for light-sensitive pharmaceutical formulations represents an underserved service layer where certification depth matters more than scale. The most penetrable segment sits in certified cosmetic packaging for mid-tier domestic brands. A go-to-market angle anchored in rapid PKN documentation turnaround differentiates against legacy molders with 4-6 month review cycles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors converters with validated sterilization protocols and rPET processing capabilities. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than pure manufacturing scale. The signal to watch is pending Polish ministry revisions to extended producer responsibility fee structures that will recalibrate virgin versus recycled feedstock economics.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Processing Line Retrofit | EU Single-Use Plastics Directive mandates 25% recycled content thresholds for PET beverage bottles. |
| Direct Retail Chain Partnership | Warsaw and Łódź corridor discounters now negotiate volume commitments bypassing distributor intermediaries. |
| PKN Certification Investment | Polish Committee for Standardization documentation qualifies converters for pharmaceutical and export supply chains. |
| Lesser Poland Capacity Expansion | Kraków-region drug manufacturers seek compliant HDPE packaging for light-sensitive oral dosage formulations. |
| Smart Closure Integration | NFC-enabled tamper-evident designs open traceability contracts for premium spirits and cosmetic brands. |
Research Methodology
A spread of perspectives from blow-molding plant managers, procurement leads at FMCG brands, PKN certification auditors, and rPET feedstock traders converged on the working assumptions. Secondary validation drew from EU Single-Use Plastics Directive implementation reports, Polish Central Statistical Office trade data, and packaging machinery import records. Bottom-up volume estimates triangulated against top-down resin consumption figures.
Segmentation dimensions modeled include resin chemistry tiers, closure engineering specifications, end-use industry verticals, and regional production clusters across the analysis window. CAGRs were derived from trend extrapolation of historical procurement patterns and regulatory compliance timelines. Industry-specific forecast inputs incorporated rPET supply elasticity and extended producer responsibility fee modulation scenarios.
Material uncertainties — rPET flake availability disruptions, natural gas price spikes affecting extrusion energy costs, and PKN certification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation schedules and feedstock market development. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Sugarcane Based PET Bottles Market
Plastic Packaging
Europe PET Packaging Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
France Plastic Bottles Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market