
 Brazil Plastic Bottles Market | 2026-2036
Brazil Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Plastic Bottles Market Insights
Supermarket private-label supply chains is tilting toward consolidated blow-mold converters with national logistics networks. ALPLA Group leverages integrated preform-to-bottle manufacturing across São Paulo and Minas Gerais industrial zones. Amcor Group anchors its position through lightweighting R&D programs serving carbonated soft drink bottlers. Berry Global Inc. competes via specialized multilayer barrier technologies for sensitive food applications.
Brazil plastic bottles are hollow thermoplastic containers manufactured through extrusion or injection blow-molding processes, typically ranging from 10ml to 20L in capacity with wall thickness calibrated for internal pressure, chemical resistance, or UV protection. These vessels primarily store, transport, and dispense liquid and semi-liquid consumer and industrial products. Polyethylene Terephthalate dominates beverage applications due to clarity, recyclability infrastructure, and established collection streams under Brazil's reverse logistics framework. High-Density Polyethylene sustains growth in household cleaner bottles where chemical compatibility and squeezability matter. The 500ml to 1L capacity band captures premium personal care and on-the-go beverage segments where portability commands margin premiums.
ANVISA governs pharmaceutical bottle material migration limits and child-resistant closure standards, while the National Solid Waste Policy (PNRS) mandates post-consumer recycled content thresholds that reshape virgin resin procurement. BIS-equivalent INMETRO certification for food-contact plastics creates compliance barriers for imported converted products. Stakeholders must monitor pending federal decree implementations on extended producer responsibility fee structures and their cascading effects on regional converter economics.
Market Dynamics
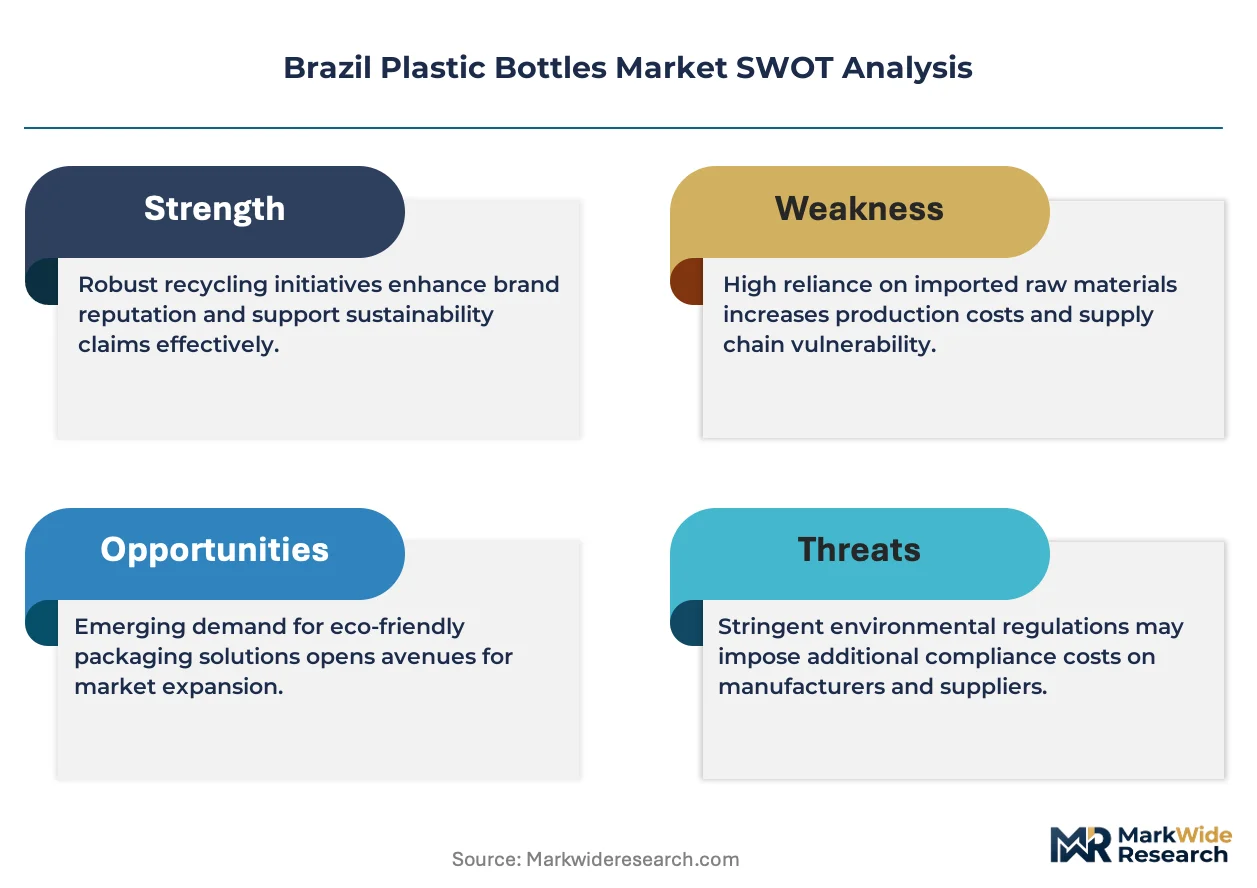
Brazil's National Solid Waste Policy (PNRS) mandates on post-consumer recycled content are compressing virgin resin procurement timelines while PET chemical recycling investments by São Paulo converters accelerate material substitution cycles.
Growth Catalysts
- PNRS recycled content thresholds:Federal mandates force beverage bottlers to integrate rPET streams, driving blow-molding equipment upgrades across Southeast industrial corridors.
- Minas Gerais dairy cluster expansion:Ultra-high-temperature milk packaging demand pulls multilayer HDPE bottle volumes from specialized converters.
- Blow-molding automation:All-electric servo-hydraulic systems cut cycle times by one-third, enabling São Paulo converters to absorb national private-label volumes.
Market Restraints
- Ethylene feedstock volatility:Petrobras refinery output fluctuations transmit directly to PE resin contract pricing, squeezing converter margins in Q3 procurement cycles.
- Single-source preform supply:Southeast Brazil concentrates 70% of domestic preform injection capacity, creating geographic vulnerability to logistics disruptions.
- ANVISA pharmaceutical migration limits:Stringent extractables testing for high-barrier bottles extends qualification timelines by 8-14 months versus food-contact approvals.
Strategic Opportunities
- Northeast Brazil underpenetration:Pernambuco and Ceará beverage bottling capacity gaps create white space for converters with regional logistics networks.
- Cosmetic airless pump bottles:Premium personal care brands in Rio de Janeiro manufacturing corridors seek localized multilayer barrier production currently imported.
- Chemical recycling scale-up:Depolymerization investments by petrochemical majors position Brazil to export food-grade rPET pellets under Mercosur trade frameworks.
Industry Challenges
- Blow-mold technician scarcity:Servo-electric machine programming expertise concentrates in São Paulo state, forcing Northeast converters to poach talent or accept longer commissioning cycles.
- INMETRO food-contact certification backlog:Testing laboratory capacity constraints delay new product launches by 4-6 months, particularly affecting seasonal beverage introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Plastic Bottles Market |
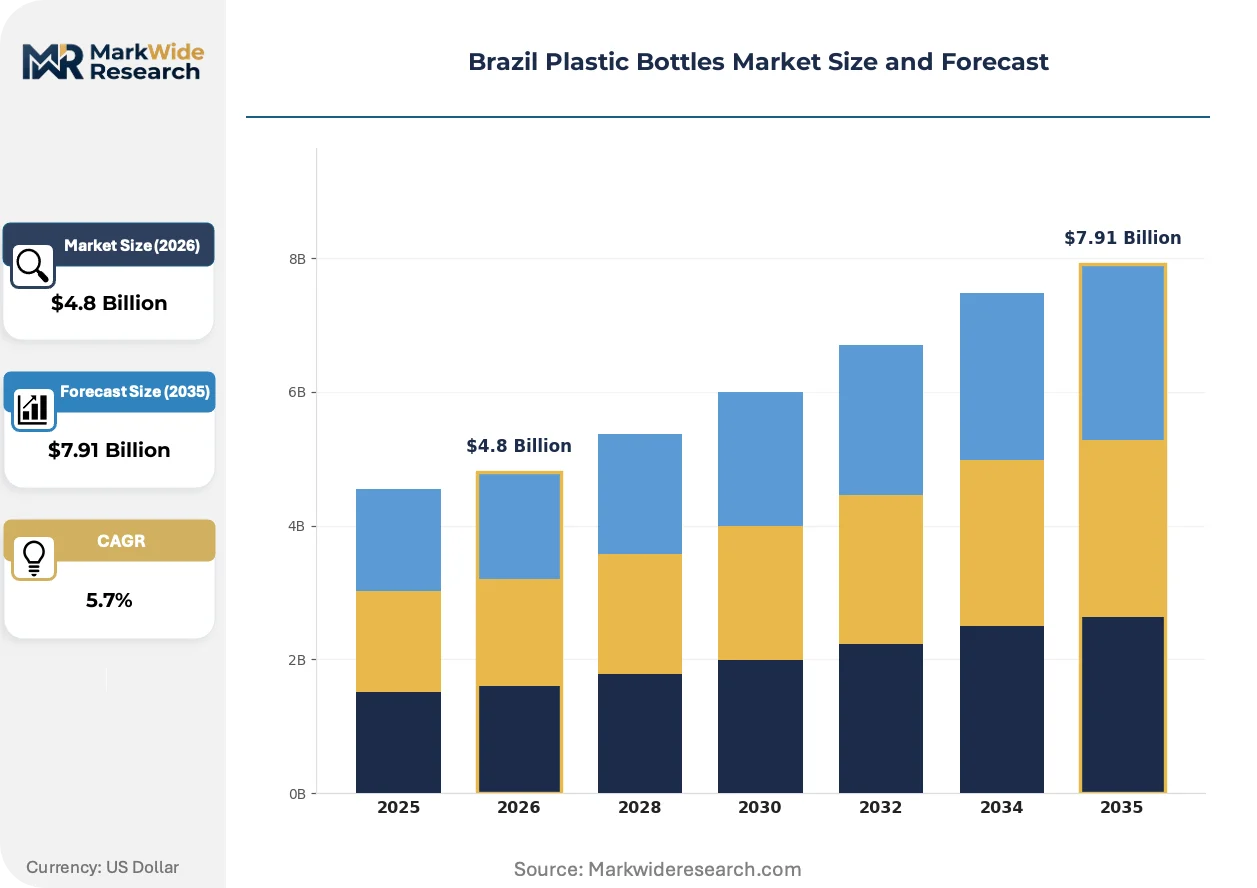
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beverage Bottles, Cosmetic Bottles, Pharmaceutical Bottles, Household Cleaner Bottles Material: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Others End User: Food & Beverage, Healthcare, Personal Care, Household Capacity: Under 500ml, 500ml to 1L, 1L to 2L, Over 2L |
| Companies Covered | ALPLA Group, Amcor Group, Berry Global Inc., Sidel Group, Velaplast, Graham Packaging, Gerresheimer AG, Logoplaste, KHS GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Plastic Bottles Market Trends and Innovations
Digital twin simulation and closed-loop recycling infrastructure are converging to compress Brazil's bottle development cycles while PNRS enforcement tightens material provenance requirements.
Digital blow-mold simulation software is virtualizing the traditional prototype-to-production pipeline for complex bottle geometries. São Paulo-based carbonated soft drink bottlers now adopt virtual cavity-balancing tools that cut mold commissioning from twelve weeks to four. This compression is virtualizing the competitive advantage of established toolrooms, enabling smaller converters to bid national contracts without captive mold-making assets.
ANVISA's 2023 updated pharmaceutical packaging guidance tightens elemental impurity thresholds for polymer additives. The regulation forces HDPE bottle suppliers serving generic drug manufacturers to reformulate masterbatch compositions or source medical-grade resins at 15-20% cost premiums. Injectable and ophthalmic segments face the steepest compliance curves, with several Rio de Janeiro contract manufacturers accelerating supplier audits to preempt batch rejection risks.
Supermarket private-label procurement teams now consolidate blow-mold converter relationships from fifteen-plus vendors to three national partners with integrated preform-to-label capabilities. The concentration displaces regional converters in Paraná and Santa Catarina who lack blow-fill-seal integration. Minas Gerais dairy processors exhibit the most aggressive consolidation, linking five-year volume commitments to dedicated production line investments.
Brazil Plastic Bottles Market Segmentation
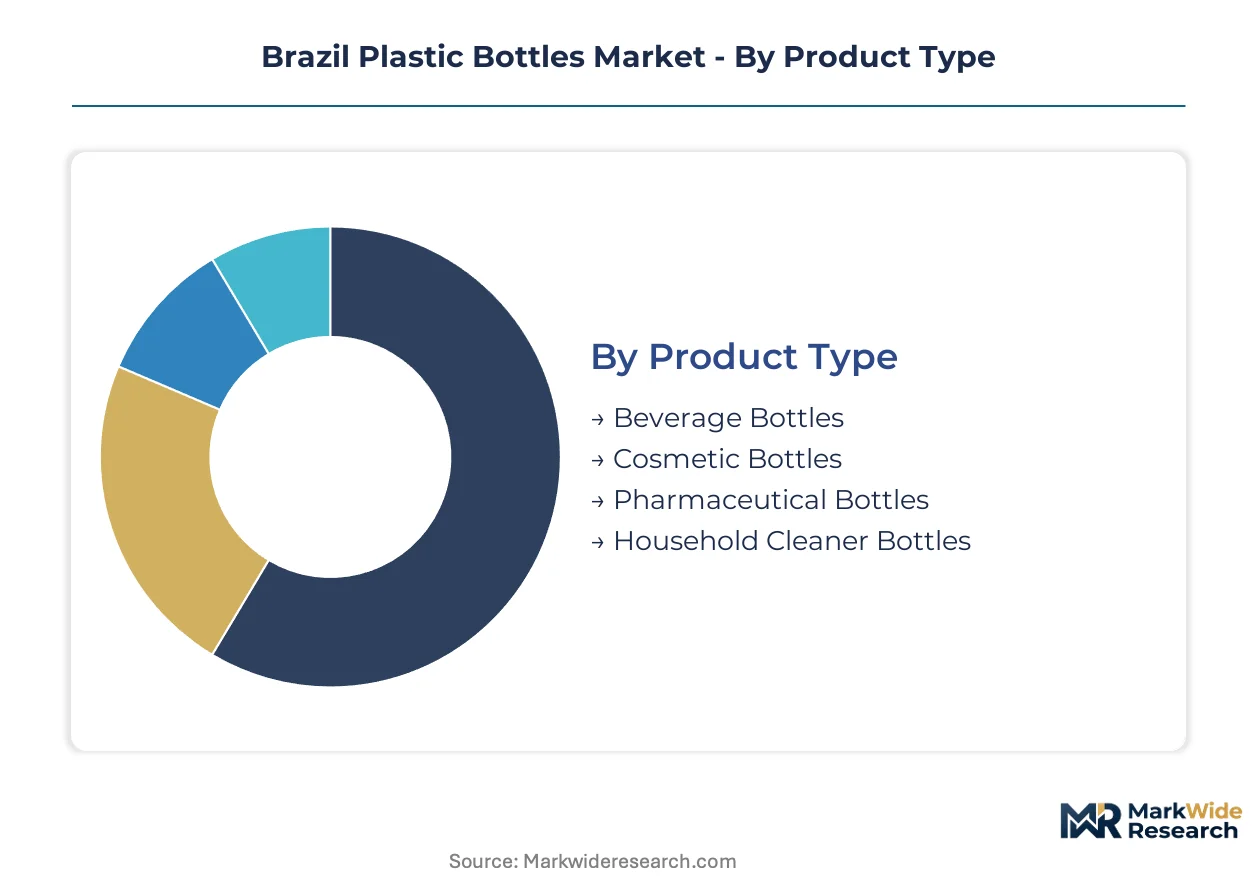
Segmentation in Brazil's plastic bottles market exposes how regulatory pressure and regional manufacturing specialization fragment procurement strategies. Buyers optimize across material compatibility, capacity banding, and end-use compliance requirements rather than treating bottles as commoditized containers.
Product Type:
Mature beverage packaging dominates volume flows while emerging pharmaceutical and cosmetic formats command premium positioning through specialized barrier requirements.
- Beverage Bottles:Carbonated soft drink and mineral water applications anchor PET resin consumption across São Paulo and Minas Gerais bottling corridors. PNRS recycled content mandates force rPET integration into these high-visibility formats ahead of other segments.
- Pharmaceutical Bottles:ANVISA migration limits and child-resistant closure standards impose 8-14 month qualification timelines. Rio de Janeiro generic drug manufacturers drive demand for HDPE formats with reformulated additive packages meeting tightened elemental impurity thresholds.
- Cosmetic Bottles:Premium personal care brands in Rio de Janeiro manufacturing corridors seek localized multilayer barrier production currently imported from Mercosur partners.
- Household Cleaner Bottles:HDPE squeezable formats dominate chemical compatibility requirements for bleach and detergent applications.
Beverage bottles handle the majority of throughput; pharmaceutical bottles are expanding most quickly on share as generic drug manufacturing localizes.
Material:
Cost tier stratification separates commodity resins from specialized grades, with compliance premiums widening spreads between virgin and recycled feedstocks.
- Polyethylene Terephthalate:Clarity and established collection infrastructure under Brazil's reverse logistics framework sustain dominance in beverage applications. São Paulo converters invest in chemical recycling depolymerization to secure food-grade rPET pellet supply.
- High-Density Polyethylene:Chemical resistance and squeezability sustain growth in household cleaner bottles where Petrobras ethylene feedstock volatility transmits directly to contract pricing.
- Polypropylene:Higher temperature tolerance serves hot-fill and retort applications with limited penetration in Brazil versus PET and HDPE.
- Others:Multilayer barrier technologies and bio-based alternatives occupy niche premium positioning for oxygen-sensitive food and cosmetic applications.
PET commands the largest installed conversion base; HDPE faces the steepest margin compression from feedstock volatility.
End User:
Customer type concentration in supermarket private-label procurement is consolidating supplier relationships toward national converters with integrated capabilities.
- Food & Beverage:Ultra-high-temperature milk packaging in Minas Gerais dairy clusters pulls specialized multilayer HDPE volumes from converters with blow-fill-seal integration.
- Healthcare:ANVISA pharmaceutical packaging guidance updates force reformulation of masterbatch compositions or sourcing of medical-grade resins at substantial cost premiums.
- Personal Care:Premium cosmetic brands seek airless pump bottle localization to displace Mercosur imports.
- Household:Private-label consolidation from fifteen-plus vendors to three national partners displaces regional converters lacking preform-to-label integration.
Food and beverage absorbs the dominant share of resin throughput; healthcare is climbing the fastest as domestic generic drug manufacturing expands.
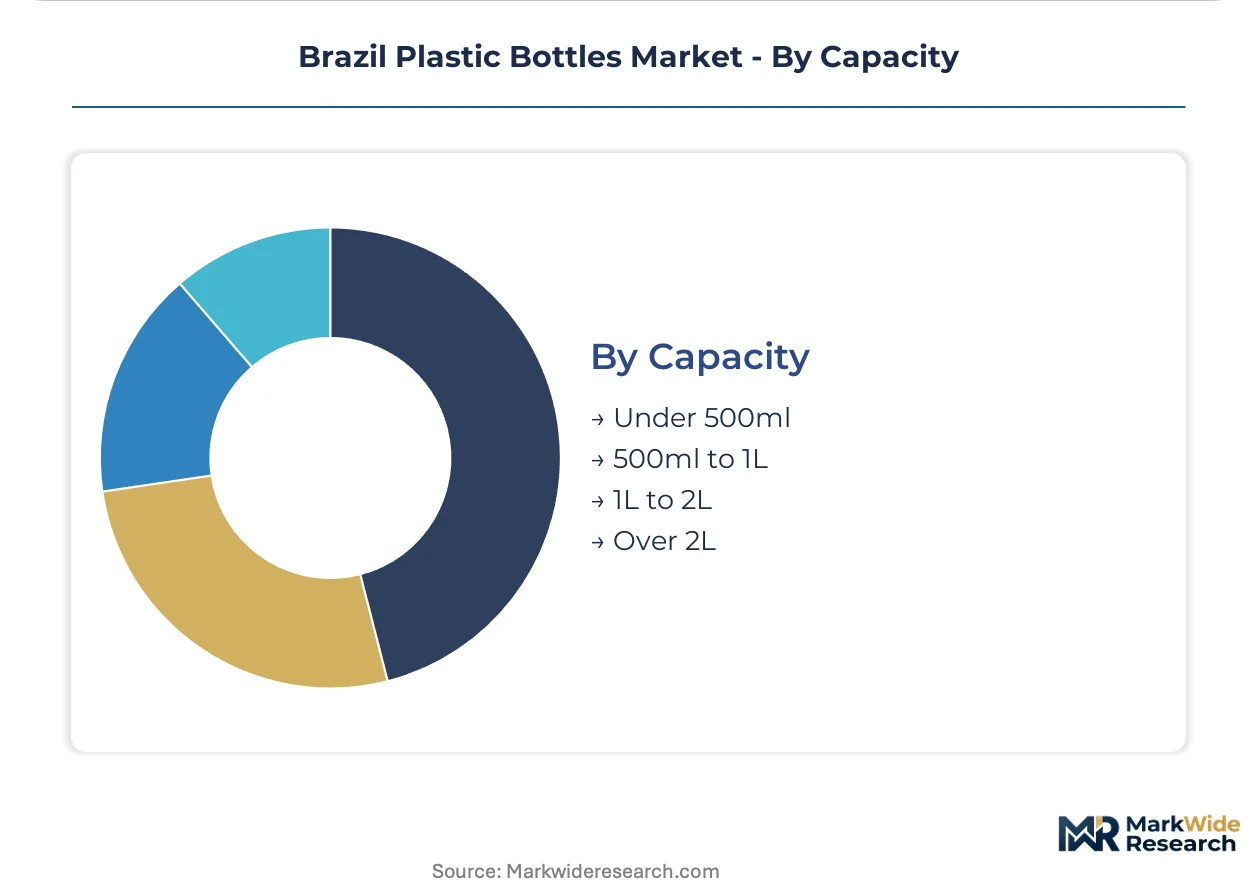
Capacity:
Volume banding aligns with distribution channel requirements, from single-serve portability premiums to bulk institutional formats.
- Under 500ml:Premium personal care and on-the-go beverage segments command margin premiums for portability-optimized designs.
- 500ml to 1L:Standard beverage and household cleaner applications dominate supermarket shelf positioning.
- 1L to 2L:Family-size beverage and bulk personal care formats serve value-conscious household purchasing.
- Over 2L:Institutional and economy-size applications concentrate in retail and foodservice channels with lower per-unit margins offset by volume throughput.
The 500ml to 1L band handles the majority of unit volume; under 500ml formats are gaining share fastest through premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Brazil commands pricing premiums through preform concentration and logistics integration, while Northeast converters absorb freight penalties to access underpenetrated beverage bottling corridors.
São Paulo
Carbonated soft drink and mineral water bottlers anchor PET resin consumption across the state's industrial zones. ANVISA pharmaceutical packaging standards force HDPE suppliers serving generic drug manufacturers to reformulate masterbatch compositions. Campinas and Sorocaba corridors concentrate blow-molding automation investments that cut cycle times by one-third.
Minas Gerais
Ultra-high-temperature milk packaging demand pulls multilayer HDPE bottle volumes from specialized converters with blow-fill-seal integration. PNRS recycled content mandates reshape virgin resin procurement timelines for dairy processors. Uberlândia and Juiz de Fora clusters link five-year volume commitments to dedicated production line investments.
Rio de Janeiro
Premium personal care brands seek localized multilayer barrier production currently imported from Mercosur partners. ANVISA's updated pharmaceutical guidance tightens elemental impurity thresholds for polymer additives. Duque de Caxias manufacturing corridors accelerate supplier audits to preempt batch rejection risks.
Rio Grande do Sul
Household cleaner bottle demand sustains HDPE squeezable format growth amid Petrobras ethylene feedstock volatility. INMETRO food-contact certification backlogs delay seasonal product launches by 4-6 months. Porto Alegre converters face displacement as supermarket private-label procurement consolidates toward national partners.
Bahia
Beverage bottling capacity gaps create white space for converters with regional logistics networks. PNRS enforcement tightens material provenance requirements for post-consumer recycled content integration. Salvador industrial zones attract poached blow-mold technician talent from São Paulo state.
Brazil Plastic Bottles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream of converter networks. The Brazil plastic bottles market consolidates around three national partners with integrated preform-to-label capabilities, displacing fifteen-plus regional vendors. Strategic archetypes span consolidated blow-mold converters with captive logistics, specialized multilayer barrier technology holders, and preform-to-bottle integrated manufacturers. Dominant competitive moves include supermarket private-label relationship consolidation and dedicated production line investments tied to multi-year volume commitments.
Among integrated manufacturing specialists, ALPLA Group, Amcor Group, and Berry Global Inc. exemplify distinct competitive positioning within the market structure. ALPLA Group represents the preform-to-bottle integrated archetype with manufacturing presence across São Paulo and Minas Gerais industrial zones. Amcor Group anchors lightweighting technology development serving carbonated soft drink bottlers. Berry Global Inc. occupies the specialized multilayer barrier tier for sensitive food and cosmetic applications.
| Leading Market Players |
|---|
| ALPLA Group |
| Amcor Group |
| Berry Global Inc. |
| Sidel Group |
| Velaplast |
| Graham Packaging |
| Gerresheimer AG |
| Logoplaste |
| KHS GmbH |
| Others |
Pricing and Supply Chain Analysis
São Paulo to Salvador freight corridors impose 12-18% logistics premiums on Northeast converters, compressing margins for regional players while Southeast preform concentration enables national blow-mold converters to extract volume-based price concessions from supermarket private-label buyers. This freight-cost asymmetry reinforces a two-tier pricing structure where integrated manufacturers with captive logistics networks capture margin premiums unavailable to single-site regional suppliers.
Pricing Analysis
The customization-premium spread separates standard 500ml PET beverage bottles from configured-to-order multilayer pharmaceutical and cosmetic formats. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—ANVISA-compliant pharmaceutical bottles command 15-20% cost premiums over food-contact tiers, while INMETRO backlog delays compress margins for seasonal beverage introductions. Cost compression in standard beverage formats is intensifying because Petrobras ethylene feedstock volatility transmits directly to PE resin contract pricing. Supermarket private-label procurement teams exhibit highest price sensitivity, whereas Rio de Janeiro premium cosmetic brands prioritize barrier performance over unit cost.
Supply Chain Analysis
ALPLA Group, Amcor Group, and Berry Global Inc. hold dominant contract-manufacturing capacity across Southeast Brazil's blow-molding corridors. Geographic supply concentrates in São Paulo, Minas Gerais, and Rio de Janeiro states, where 70% of domestic preform injection capacity creates single-source vulnerability to logistics disruptions. Raw material dependencies rest on Petrobras ethylene feedstock, imported PET resin, and medical-grade masterbatch additives. Supply chain risk centers on Southeast preform concentration—any disruption to Campinas or Sorocaba corridors would cascade through national beverage bottling networks. Distribution runs through supermarket private-label consolidation toward three national partners with integrated preform-to-label capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's plastic bottles market sits at a high-growth inflection as PNRS recycled content mandates force rPET integration ahead of chemical recycling scale-up, creating structural advantage for converters with backward integration into depolymerization assets.
For Market Incumbents: Entrench market position through captive chemical recycling investments and dedicated production line commitments tied to five-year supermarket private-label volume agreements. Defensive consolidation moves include acquiring Northeast regional converters to preempt logistics-based competition and securing ANVISA pre-qualification status ahead of tightened elemental impurity enforcement. The priority lever rests on blow-fill-seal integration for Minas Gerais dairy processors.
For New Entrants and Emerging Players: Establish a beachhead in Pernambuco and Ceará beverage bottling corridors where preform supply scarcity creates white space for regional logistics networks. Target cosmetic airless pump bottle localization for Rio de Janeiro manufacturing corridors currently dependent on Mercosur imports. The most penetrable segment is Northeast Brazil's underpenetrated beverage capacity, with go-to-market angle anchored by poached São Paulo blow-mold technician expertise.
For Investors and Strategic Acquirers: Specialized multilayer barrier technology holders with ANVISA pharmaceutical pre-qualification represent the most attractive acquisition archetype for long-term viability across the 5-10 year window. These targets command scarcity premiums as generic drug manufacturing localizes and compliance timelines extend. The signal to watch is INMETRO testing laboratory capacity expansion—acceleration indicates regulatory bottleneck easing and seasonal launch recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Depolymerization investments by petrochemical majors position Brazil for food-grade rPET pellet exports under Mercosur frameworks. |
| Blow-Fill-Seal Integration | Minas Gerais dairy processors link five-year volume commitments to dedicated production lines with ultra-high-temperature packaging capability. |
| ANVISA Pre-Qualification Investment | Reformulated masterbatch compositions meeting tightened elemental impurity thresholds secure 8-14 month qualification timeline advantages. |
| Northeast Logistics Network Buildout | Pernambuco and Ceará beverage bottling capacity gaps create first-mover advantage for converters absorbing freight penalties. |
| Digital Twin Simulation Adoption | Virtual cavity-balancing tools cut mold commissioning from twelve weeks to four, enabling smaller converters to bid national contracts. |
Research Methodology
A spread of perspectives from blow-mold converter operations directors, supermarket private-label procurement managers, petrochemical resin procurement leads, and ANVISA regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through Petrobras refinery output disclosures, INMETRO certification database tracking, and Brazilian Association of Plastic Industry (ABIPLAST) production statistics. Bottom-up resin consumption modeling triangulated against top-down packaging value chain estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include material type, capacity band, end-use compliance tier, and regional manufacturing cluster. CAGRs derived from weighted average of historical resin consumption trends and PNRS mandate implementation schedules. Industry-specific forecast inputs incorporated blow-molding automation adoption curves and chemical recycling capacity buildout timelines.
Sensitivities concentrate around Petrobras refinery output fluctuations, federal decree implementations on extended producer responsibility fee structures, and ANVISA pharmaceutical guidance enforcement intensity. Forecasts reflect assumptions on rPET integration rates and regional logistics network development. Cross-checking against ABIPLAST quarterly production surveys and customs import data for PET resin is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
PET Jars Market