
 North America Pallet Market | 2026-2036
North America Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pallet Market Intelligence
Mexico's industrial zones near Monterrey and Tijuana is fragmenting as new pallet manufacturing capacity comes online to serve nearshored automotive and electronics assembly. Brambles Limited sustains its pooled rental network dominance across the United States through dense depot infrastructure. UFP Industries, Inc. anchors western North American supply with integrated lumber-to-pallet manufacturing. Rehrig Pacific Holding, Inc. differentiates through specialized beverage sector designs that reduce truck loading times.
A pallet is a portable platform, typically constructed from wood slats, plastic resin, or metal, designed to support goods during storage, handling, and transportation by forklift or pallet jack; standard dimensions such as 48 by 40 inches dominate North American freight compatibility. Its primary purpose is unit load consolidation, enabling efficient movement through warehouse racking systems and intermodal transfer points. Wood material type retains volume leadership due to low input costs and established repair networks, though plastic formats capture margin pools in pharmaceutical cold chains where washability and contamination control command premium positioning. Composite material type grows fastest among sustainability-focused retail distributors seeking to reduce splinter damage and extend cycle life in closed-loop pooling.
The EPA oversees chemical emissions from plastic resin production, while OSHA sets workplace load-handling standards that influence pallet structural requirements. The USDA's Agricultural Marketing Service enforces sanitary protocols for wood pallets entering food distribution channels, creating compliance-driven demand for heat-treated or plastic alternatives. Stakeholders must monitor how state-level extended producer responsibility frameworks in California and New York reshape material recovery obligations and pooling economics.
Market Dynamics
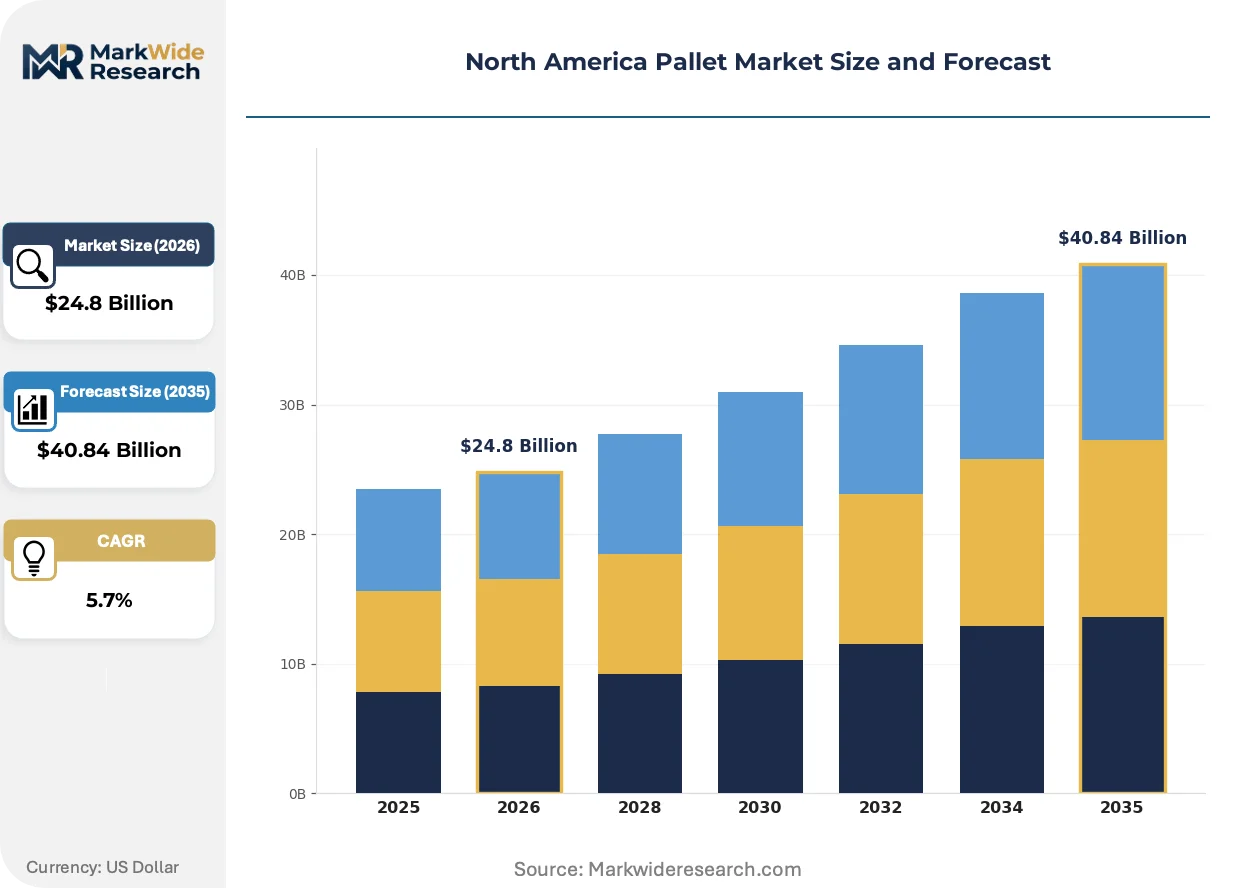
Nearshored manufacturing capacity in Mexico and the EPA's evolving waste frameworks are compressing traditional wood pallet supply chains while accelerating plastic and composite format adoption across automotive and e-commerce fulfillment networks.
Growth Catalysts
- USDA Sanitary Protocols:Heat-treatment mandates for wood pallets entering food distribution channels drive compliance-driven demand for certified alternatives and premium plastic formats in pharmaceutical cold chains.
- Automotive Nearshoring:Assembly plant relocations to Monterrey and Tijuana industrial corridors generate localized pallet manufacturing capacity and closed-loop pooling infrastructure.
- E-commerce Fulfillment Density:Amazon, Walmart, and Target distribution centers across Illinois, Michigan, and Ohio standardize on 48-by-40-inch plastic pallets for automated warehouse racking compatibility.
Market Restraints
- Lumber Input Volatility:Western US softwood supply constraints and Canadian tariff uncertainty destabilize cost structures for traditional wood pallet manufacturers dependent on integrated sawmill operations.
- Plastic Resin Emission Controls:EPA oversight of chemical emissions from polyethylene and polypropylene production adds compliance costs and capacity limitations for domestic resin converters serving pallet molders.
- Repair Network Concentration:Wood pallet refurbishment infrastructure clusters in the Great Lakes corridor, creating geographic dependency and transport cost penalties for coastal distribution networks.
Strategic Opportunities
- California Extended Producer Responsibility:State-level packaging recovery mandates create pooling economics advantages for rental network operators with reverse logistics capabilities.
- RFID-NFC Convergence:Embedded sensor pallets enabling real-time location tracking and temperature monitoring open premium positioning in pharmaceutical and high-value electronics logistics.
- Canadian Cold Chain Expansion:Underpenetrated protein and produce export corridors from Alberta and Saskatchewan offer growth white space for washability-certified plastic formats.
Industry Challenges
- Heat-Treatment Certification Backlogs:USDA Agricultural Marketing Service inspection capacity constraints delay wood pallet export approvals, disrupting just-in-time agricultural supply schedules.
- Automation Integration Complexity:Legacy warehouse management systems require costly retrofitting to recognize RFID-tagged pallets and synchronize with robotic picking equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pallet Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Plastic, Metal, Composite Application: Food & Beverage, Pharmaceuticals, Retail, Manufacturing End User: Logistics, Warehousing, Export, Construction Size: Standard, Custom, Heavy Duty, Lightweight |
| Companies Covered | Schoeller Allibert B.V., Craemer Holding GmbH, Brambles Limited, Millwood, Inc., Menasha Corporation, UFP Industries, Inc., Cabka Group GmbH, Loscam International Holdings Co., Ltd., Rehrig Pacific Holding, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pallet Market Strategic Shifts & Innovations
Material science advances and regulatory pressure on circularity are collapsing traditional format boundaries, with composite and embedded-sensor pallets capturing premium logistics segments previously dominated by commodity wood.
Embedded RFID and NFC sensor technology enables real-time pallet tracking, temperature logging, and chain-of-custody verification for pharmaceutical and electronics shipments. Cold chain distributors and high-value freight forwarders are adopting these smart pallets at accelerating rates, paying 3-4x commodity premiums for traceability compliance. The technology is rendering obsolete manual scanning and paper-based chain-of-custody documentation in temperature-sensitive logistics.
California's extended producer responsibility framework and New York's emerging packaging waste regulations are mandating material recovery and reuse targets for pallet suppliers serving retail and grocery channels. These state-level mandates compress disposal economics for single-use wood formats while creating compliance advantages for pooled rental networks with established reverse logistics. Food retail distributors operating across both states are consolidating procurement around heat-treated wood and certified plastic alternatives to simplify multi-jurisdiction compliance.
Outcome-based rental contracts with guaranteed cycle-life performance are displacing traditional per-trip pricing in beverage and grocery retail channels. Brambles and regional pooling operators now offer pallet-as-a-service models with damage liability transfer, compressing buyer procurement cycles from annual RFPs to multi-year partnership structures. This shift is most visible in California and Texas grocery distribution networks where retailer consolidation has concentrated buying power among three national chains.
North America Pallet Market Segmentation
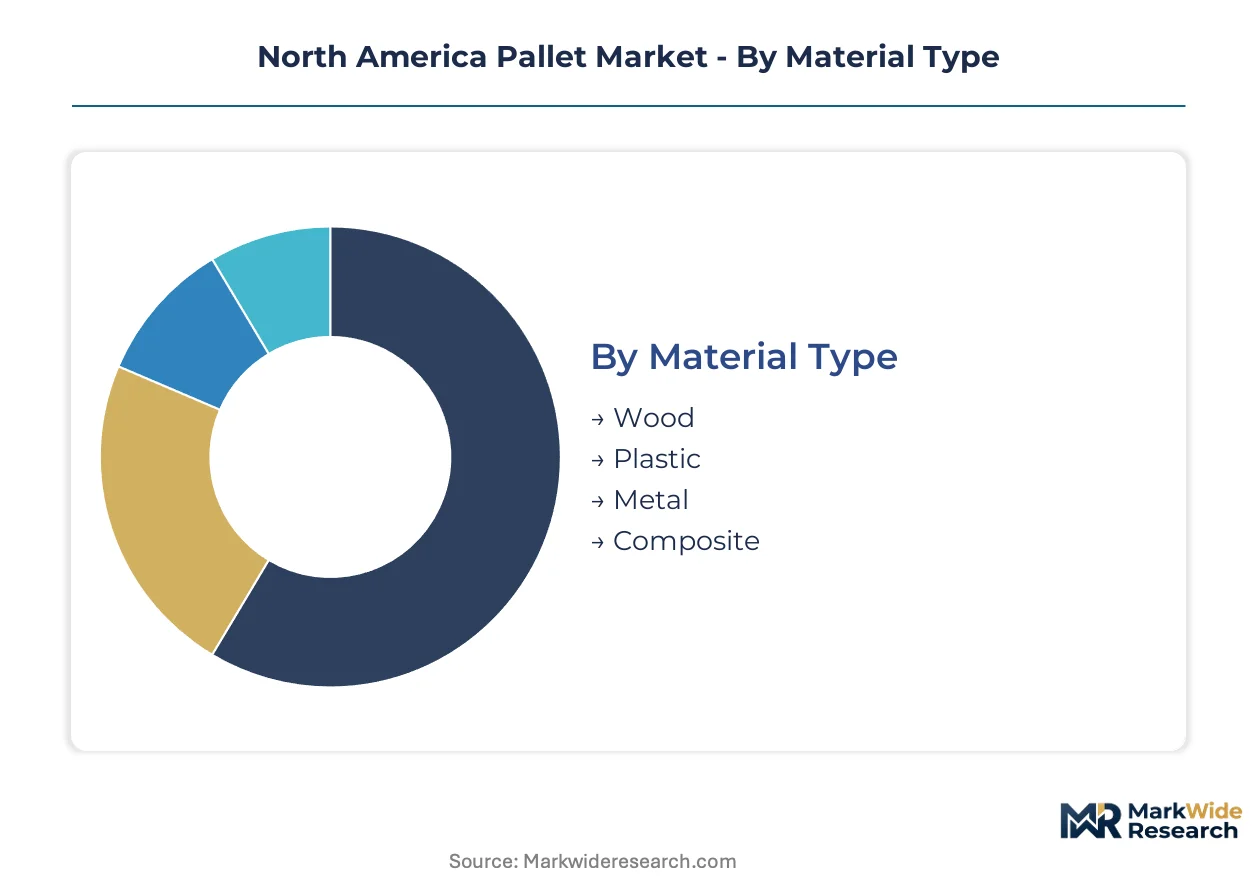
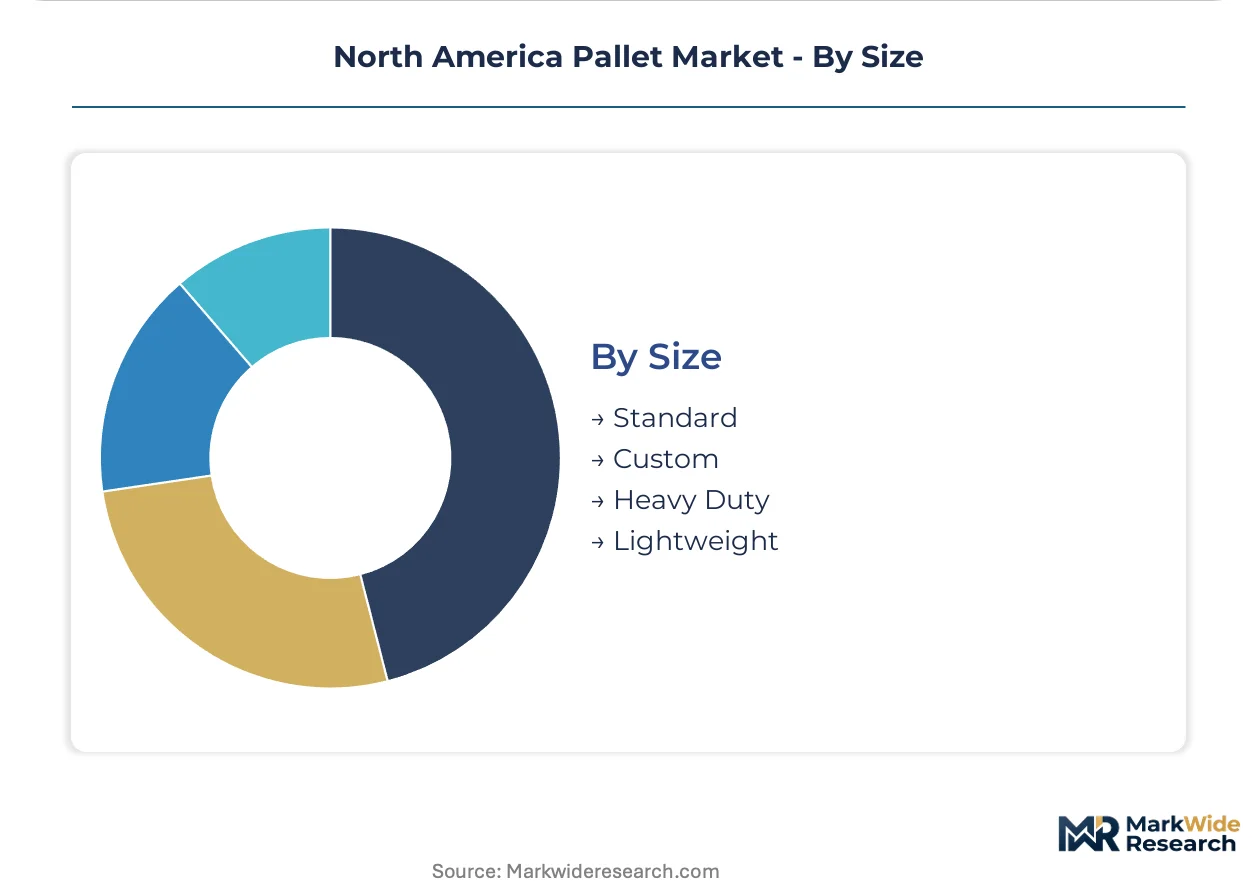
Pallet specification varies sharply across North American supply chains. Material selection, dimensional standards, and end-use requirements create distinct procurement clusters that shape supplier specialization and margin capture.
Material Type:
Material selection spans commodity wood through engineered composites, with cost tier and washability requirements driving format choice.
- Wood:Softwood and hardwood slat construction dominates unit economics across Great Lakes manufacturing corridors. Low input costs and established refurbishment networks in Illinois, Michigan, and Ohio sustain volume leadership despite splinter damage and moisture absorption constraints in food distribution.
- Plastic:High-density polyethylene and polypropylene formats command premium positioning in pharmaceutical cold chains where FDA contamination protocols and washability requirements eliminate wood alternatives. Automated warehouse racking compatibility drives standardization on 48-by-40-inch dimensions.
- Metal:Steel and aluminum pallets serve heavy industrial applications with extreme load requirements and fire-code restrictions in chemical storage facilities.
- Composite:Engineered wood-plastic blends capture sustainability-focused retail distributors seeking extended cycle life and reduced damage liability in closed-loop pooling arrangements.
The dominant share belongs to wood, while composite is closing the gap fastest.
Application:
Application segmentation reflects regulatory intensity and automation compatibility across vertical supply chains.
- Food & Beverage:USDA heat-treatment mandates for wood pallets entering agricultural distribution channels create compliance-driven demand for certified alternatives. California and New York extended producer responsibility frameworks accelerate plastic format adoption in grocery retail networks.
- Pharmaceuticals:Temperature-controlled logistics and FDA chain-of-custody requirements drive premium plastic pallet penetration with embedded RFID tracking for serialization compliance.
- Retail:E-commerce fulfillment density in Illinois, Michigan, and Ohio distribution centers standardizes on plastic formats for automated storage and retrieval system compatibility.
- Manufacturing:Just-in-time automotive assembly near Monterrey and Tijuana generates localized pallet manufacturing capacity with closed-loop pooling infrastructure.
Food and beverage commands the largest volume base, though pharmaceuticals shows the steepest expansion trajectory.
End User:
End-user categories align with asset ownership models and cycle intensity across North American logistics networks.
- Logistics:Third-party freight forwarders and pooled rental operators manage multi-customer asset rotation with damage liability transfer structures.
- Warehousing:Amazon, Walmart, and Target distribution centers deploy captive pallet fleets with automation-optimized specifications.
- Export:USDA Agricultural Marketing Service inspection requirements for heat-treated wood create certification backlogs disrupting agricultural export schedules.
- Construction:Project-based material handling favors low-cost disposable formats with minimal reverse logistics requirements.
Warehousing holds the dominant position, while export is gaining share fastest amid nearshored manufacturing expansion.
Size:
Size segmentation tracks load capacity, automation compatibility, and custom engineering requirements.
- Standard:The 48-by-40-inch GMA specification dominates North American freight compatibility across intermodal transfer points and warehouse racking systems.
- Custom:Automotive and aerospace manufacturers specify non-standard dimensions for oversized component handling.
- Heavy Duty:Reinforced construction supports steel coil, machinery, and concentrated load applications exceeding standard racking limits.
- Lightweight:Reduced-weight plastic formats optimize air freight cube utilization and manual handling ergonomics in parcel distribution networks.
Standard size maintains the dominant share, while lightweight formats are expanding most quickly in e-commerce parcel networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emission controls and USDA sanitary protocols anchor United States demand, while nearshored manufacturing reshapes Mexican supply corridors and Canadian cold chain expansion opens format diversification opportunities.
United States
E-commerce fulfillment density across Illinois, Michigan, and Ohio drives plastic pallet standardization for automated warehouse compatibility. EPA oversight of polyethylene and polypropylene resin emissions adds compliance costs for domestic molders. The Great Lakes manufacturing corridor sustains wood pallet volume leadership through established refurbishment networks and integrated sawmill operations.
Mexico
Automotive assembly relocations to Monterrey and Tijuana industrial zones generate localized pallet manufacturing capacity and closed-loop pooling infrastructure. Mexican federal environmental regulations under SEMARNAT align with corporate sustainability mandates from US parent companies. New manufacturing capacity is fragmenting traditional supply chains as domestic producers serve nearshored electronics and automotive sectors.
Canada
Underpenetrated protein and produce export corridors from Alberta and Saskatchewan create growth opportunities for washability-certified plastic formats. Health Canada and PMRA sanitary protocols for agricultural exports drive heat-treatment and alternative material adoption. Western softwood supply constraints and tariff uncertainty destabilize cost structures for traditional wood pallet manufacturers dependent on cross-border lumber flows.
North America Pallet Market Key Industry Players
Pooled rental network operators and integrated lumber-to-pallet manufacturers split the market between asset-light service models and captive supply chain control. The vendor base organizes around three strategic archetypes: dense depot infrastructure operators, vertically integrated wood processors, and specialized format designers. Consolidation pressure concentrates among rental networks seeking geographic coverage expansion and wood processors defending input cost positions through sawmill integration.
Within the pooled rental tier, Brambles Limited and Loscam International Holdings Co., Ltd. exemplify network density strategies built on reverse logistics infrastructure. Among integrated manufacturers, UFP Industries, Inc. anchors western North American supply with captive lumber sourcing. Rehrig Pacific Holding, Inc. occupies a specialized position through beverage sector format design that reduces truck loading times and damage liability exposure.
| Leading Market Players |
|---|
| Schoeller Allibert B.V. |
| Craemer Holding GmbH |
| Brambles Limited |
| Millwood, Inc. |
| Menasha Corporation |
| UFP Industries, Inc. |
| Cabka Group GmbH |
| Loscam International Holdings Co., Ltd. |
| Rehrig Pacific Holding, Inc. |
| Others |
Cost & Logistics Intelligence
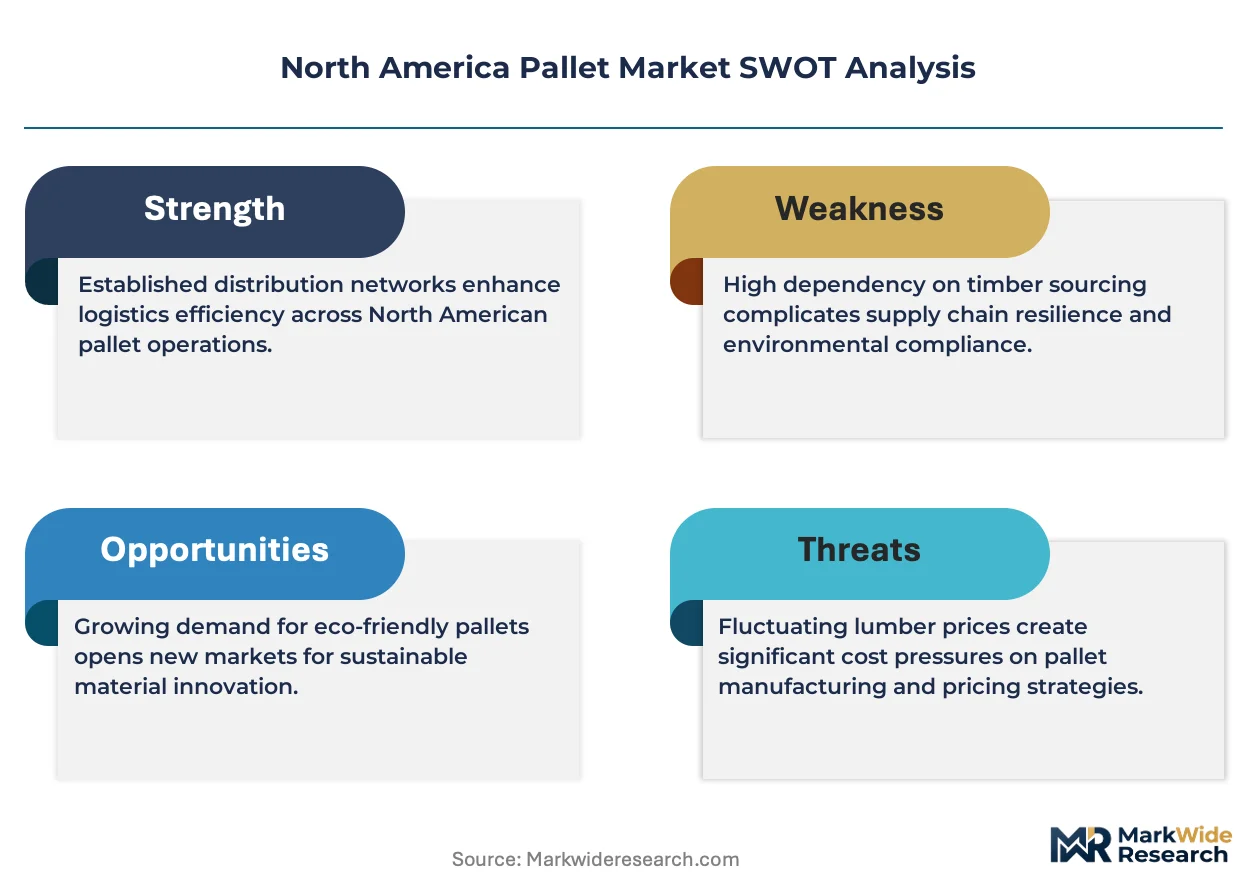
The Great Lakes manufacturing corridor's freight density compresses logistics costs for wood pallet refurbishment networks while amplifying price spreads between coastal plastic imports and Midwestern captive production. EPA resin emission controls and Canadian softwood tariff uncertainty feed directly into tiered pricing structures that separate commodity wood, certified heat-treated formats, and premium plastic alternatives.
Pricing Analysis
Geographic price spreads between Illinois-Michigan-Ohio wood refurbishment clusters and coastal plastic distribution points exceed transport-cost differentials alone. Three-tier pricing structure across premium RFID-enabled plastic, certified heat-treated wood, and economy untreated formats reflects automation compatibility and USDA compliance tier. Cost compression in standard wood formats is intensifying due to western softwood supply constraints and Mexican nearshored capacity expansion. Beverage distributors show highest price sensitivity to per-trip rental rates, while pharmaceutical cold chain buyers prioritize washability certification over unit cost.
Supply Chain Analysis
Contract manufacturing concentration among pooled rental operators Brambles and Loscam dominates reverse logistics infrastructure across the United States and Mexico. Geographic supply concentration centers on the Great Lakes corridor for wood refurbishment, Monterrey-Tijuana for automotive-optimized plastic production, and coastal ports for Asian resin imports. Raw material dependencies draw from western US softwood, Gulf Coast polyethylene resin, and Canadian hardwood feedstocks. Single-source vulnerability runs through integrated sawmill operations facing tariff exposure on cross-border lumber flows. Distribution runs through depot-based rental networks for closed-loop pooling and direct OEM sales for captive captive fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nearshored manufacturing fragmentation across Mexico's industrial zones creates niche opportunities for specialized format designers serving automotive and electronics assembly with localized production.
For Market Incumbents: Build depot density moats through accelerated reverse logistics infrastructure in California and Texas grocery corridors. Defend against RFID-NFC convergence threats by embedding sensor partnerships with warehouse automation vendors. Prioritize backward integration into resin compounding to offset EPA emission control cost pass-throughs. For New Entrants and Emerging Players: Build out washability-certified plastic capacity targeting underpenetrated Canadian protein export corridors from Alberta and Saskatchewan. White-space availability concentrates in pharmaceutical serialization compliance and aerospace custom dimension formats. Go-to-market leverage rests on USDA heat-treatment certification bypass positioning against wood format inspection backlogs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified lumber processors seeking pallet division divestitures amid softwood margin compression. Long-term viability favors pooled rental networks with established reverse logistics over commodity wood manufacturers exposed to input volatility. Monitor California extended producer responsibility enforcement intensity as inflection signal for pooling economics acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Network Expansion | Dense reverse logistics infrastructure in Texas and California captures EPR compliance advantages for rental operators. |
| RFID-NFC Integration Partnership | Embedded sensor alliances with warehouse automation vendors defend against technology displacement in pharmaceutical logistics. |
| Resin Compounding Backward Integration | Captive polyethylene supply hedges EPA emission control cost pass-throughs for plastic format manufacturers. |
| Heat-Treatment Certification Bypass Positioning | Plastic format specialization exploits USDA Agricultural Marketing Service inspection capacity constraints disrupting wood exports. |
| Canadian Cold Chain Format Development | Washability-certified designs target underpenetrated protein and produce export growth from Alberta and Saskatchewan. |
Research Approach
The analysis maps wood refurbishment networks, plastic molding capacity, composite format development, and pooled rental operations, each validated through plant managers, procurement leads at Amazon and Walmart distribution centers, beverage logistics directors, and USDA Agricultural Marketing Service compliance officers. Primary interview insights combined with secondary validation from EPA emission filings, SEMARNAT environmental registrations, Canadian trade data, and SEC 10-K disclosures from listed pallet manufacturers. Bottom-up capacity assessments and top-down demand modeling triangulate volume and value estimates.
Assumption sets held nearshoring momentum and EPR regulatory intensity fixed while varying softwood tariff trajectories and resin emission compliance costs across sensitivity bands. Segmentation dimensions modeled include material type, application vertical, end-user ownership model, and size specification across the projection horizon. CAGRs derive from installed base rotation rates, automation adoption curves, and format substitution elasticities. Industry-specific inputs incorporate warehouse racking compatibility standards and pharmaceutical serialization compliance timelines.
Stress conditions across lumber tariff rates, resin emission allowance prices, and EPR enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding nearshoring pace and regulatory adoption timelines. Quarterly review of USDA inspection capacity backlogs, California EPR implementation milestones, and Mexican federal environmental regulation alignment is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Pallet Labeler Market
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
Pallet Displays Market
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
Pallet Wraps Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Europe Pallet Market