
 HDPE Jug Market | 2026-2036
HDPE Jug Market Size, Share, and Industry Trends Forecast 2026-2036
HDPE Jug Market Foresight
Wholesale distributor networks for rigid packaging is fragmenting as e-commerce procurement platforms and direct manufacturer portals erode traditional three-tier supply arrangements. Berry Global leverages captive resin sourcing and blow-molding scale to sustain cost leadership across North American retail channels. Consolidated Container Company anchors its position through geographic density of reconditioning and recycling infrastructure near Midwest dairy processors.
HDPE jug denotes a blow-molded high-density polyethylene container, typically formed through extrusion blow molding at melt temperatures between 160°C and 240°C, engineered for chemical resistance, impact strength, and moisture barrier performance in liquid storage and transport. Square jug configurations dominate warehouse palletization efficiency and retail shelf density, while dispensing jug designs with integrated handles and vented closures command premium positioning in agricultural chemical and institutional cleaning segments. The five-liter capacity tier captures industrial and agricultural volume, whereas one-liter formats concentrate in household retail and food service channels where turnover velocity and shelf space constraints govern procurement.
FDA food-contact regulations under 21 CFR 177.1520 govern resin purity and additive thresholds for HDPE jugs serving beverage and food applications, while EPA container and containment regulations mandate specific permeation and closure standards for agricultural chemical packaging. The EU REACH framework and evolving national extended producer responsibility schemes are elevating post-consumer recycled content minimums, reshaping virgin resin demand curves and capital allocation toward compatibilizer technology and mechanical recycling infrastructure. Stakeholders must weigh recycled feedstock cost trajectories against virgin resin price volatility when committing to multi-year supply contracts.
Market Dynamics
The EU Single-Use Plastics Directive is compressing virgin resin demand curves while elevating mechanical recycling infrastructure investment, forcing HDPE jug producers to reconfigure feedstock sourcing and compatibilizer technology allocation across all capacity tiers.
Growth Catalysts
- REACH post-consumer recycled content mandates:The EU ECHA framework is elevating minimum recycled thresholds in rigid packaging, pulling capital toward compatibilizer R&D and mechanical recycling scale-up near industrial clusters.
- Agricultural chemical distribution expansion:Brazil's ANVISA-compliant bulk container procurement is accelerating five-liter jug volume for crop protection chemicals, with distributor networks consolidating around blow-molding capacity near São Paulo state processing centers.
- Extrusion blow-molding automation:Real-time melt temperature control between 160°C and 240°C is reducing wall-thickness variation, enabling lightweighting without sacrificing impact strength for dairy and water bottling lines.
Market Restraints
- Propylene co-monomer cost volatility:Feedstock price swings for HDPE resin disrupt margin stability for converters lacking captive cracker access or long-term supply contracts with integrated petrochemical producers.
- Midwest dairy processor supply concentration:Geographic clustering of large-format bottling operations near Wisconsin and Minnesota creates demand vulnerability to regional logistics disruptions and single-source dependency.
- Permeation performance ceilings:HDPE's inherent moisture barrier limitations versus multilayer PET alternatives constrain adoption in oxygen-sensitive pharmaceutical and nutraceutical liquid packaging segments.
Strategic Opportunities
- India FSSAI food-contact compliance pathways:The country's packaged food and edible oil sectors present white space for FDA-grade HDPE jug penetration as cold-chain infrastructure expands and organized retail formats consolidate procurement.
- Integrated dispensing closure systems:Vented handle designs with tamper-evident features command premium positioning in agricultural chemical and institutional cleaning channels where end-user safety protocols drive specification.
- E-commerce direct procurement platforms:Manufacturer portals and digital tendering systems are eroding traditional three-tier distributor networks, enabling margin capture and customer data ownership for blow-molding specialists.
Industry Challenges
- Recycled feedstock quality inconsistency:Post-consumer HDPE flake contamination variability complicates blow-molding process stability and FDA 21 CFR 177.1520 compliance for food-contact applications.
- Multi-site blow-molding equipment standardization:Legacy extrusion lines with varying screw designs and parison programming systems impede rapid product changeover and centralized quality assurance across distributed manufacturing footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDPE Jug Market |
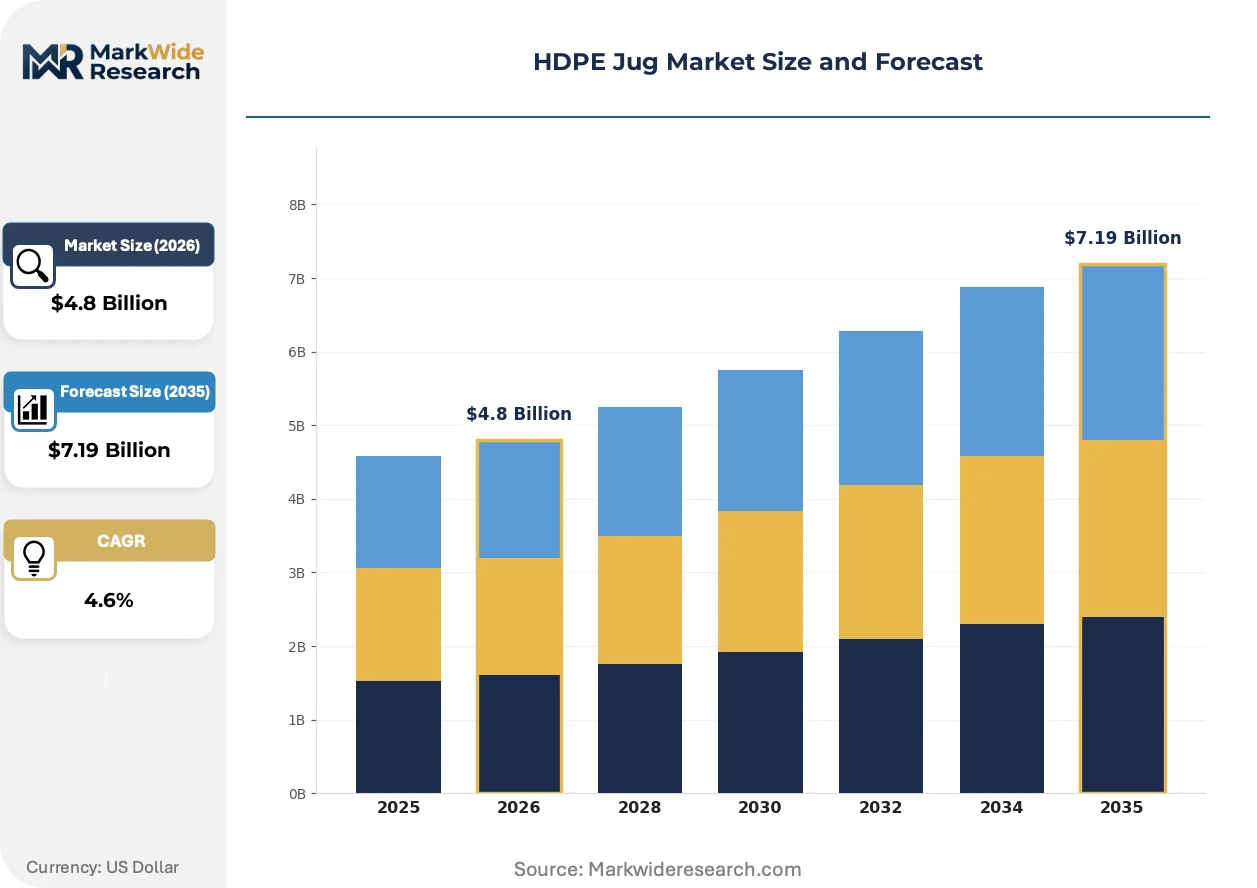
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Jug, Square Jug, Custom Jug, Dispensing Jug Capacity: 1 Liter, 2 Liters, 5 Liters, 10 Liters End User: Household, Industrial, Agricultural, Retail Closure Type: Screw Cap, Snap Cap, Flip Top, Others |
| Companies Covered | Berry Global, Consolidated Container Company, Alpha Packaging, Comar, Gateway Plastics, Plastic Ingenuity, ProAmpac, Sonoco Products, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDPE Jug Market Shifts & Advancements
Active barrier technologies and digital manufacturing controls are compressing traditional quality-assurance timelines while regulatory pressure on circularity accelerates material science investment across the HDPE jug value chain.
Co-extruded multilayer structures with ethylene vinyl alcohol (EVOH) or nylon tie layers are extending HDPE jug shelf-life performance for oxygen-sensitive agricultural chemicals and institutional cleaners. Midwest dairy processors and Brazil's agrochemical distributors are specifying these configurations for inventory holding and tropical climate stability. The technology is rendering obsolete single-layer HDPE designs in premium chemical and extended-shelf-life dairy segments where permeation failure carries liability exposure.
The EU Green Deal's packaging and packaging waste regulation is mandating extended producer responsibility fee modulation based on recyclability design scores. This industrial consequence is forcing closure-to-jug material compatibility and label adhesive reformulation across all export-bound production. Agricultural chemical packaging serving EU markets faces the most acute compliance timeline pressure, with reformulation deadlines compressing R&D cycles for compatibilizer suppliers.
Direct-to-procurement-manager digital platforms are consolidating spot-buying and contract negotiation for rigid packaging into centralized e-procurement dashboards. Traditional three-tier distributor networks face disintermediation as blow-molders deploy customer portals with real-time capacity visibility and dynamic lot-sizing. This channel shift is most visible in North American institutional cleaning and food service verticals where procurement teams prioritize supplier data integration over relationship-based sourcing.
HDPE Jug Market Segmentation
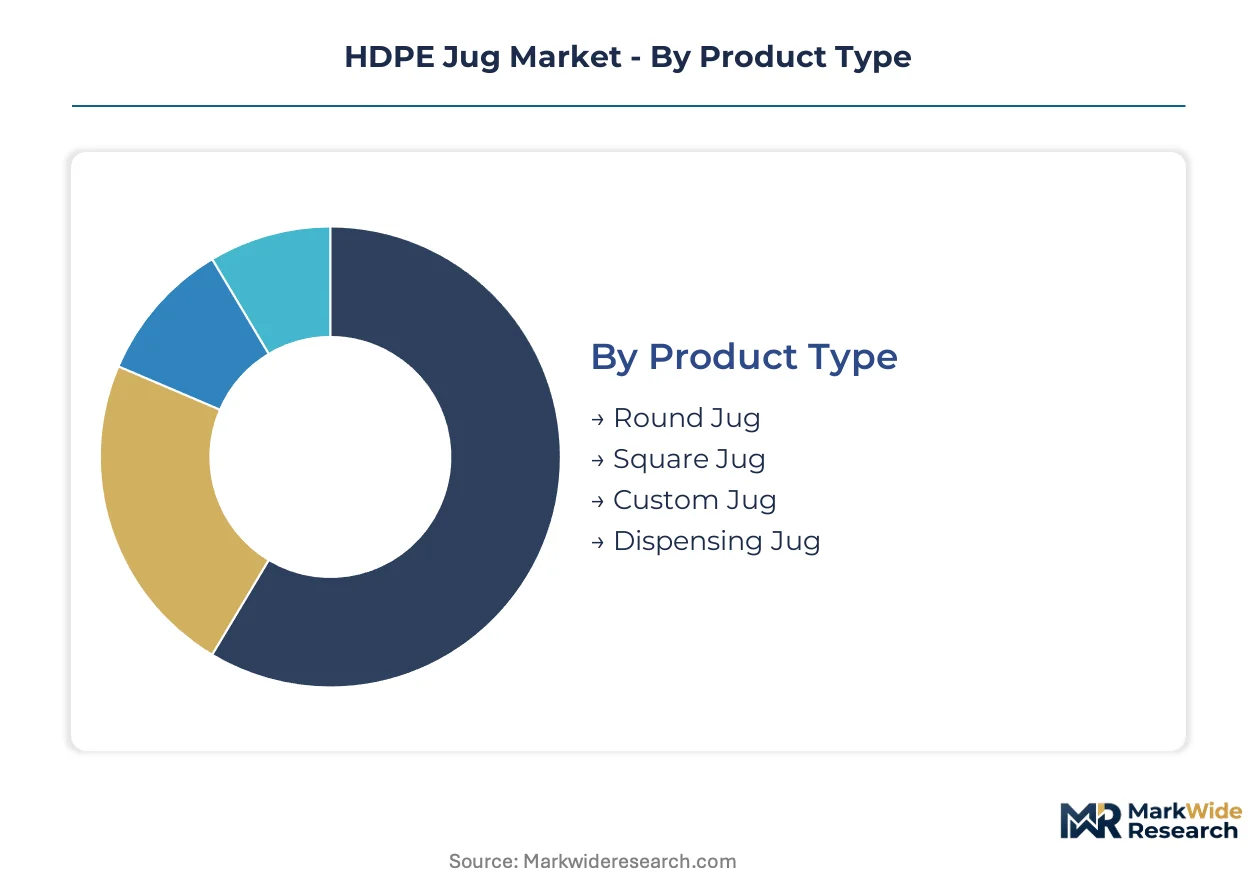
HDPE jug procurement patterns diverge sharply across product geometry, capacity tiers, and end-use specifications. Understanding these fault lines reveals where blow-molding capacity concentrates and where formulation investments yield differentiation.
Product Type:
After-sales service intensity varies dramatically by jug geometry, with custom and dispensing formats demanding technical support for closure integration and venting systems that standard rounds and squares do not require.
- Square Jug:Optimized for pallet density and warehouse stacking efficiency through uniform footprint geometry. Demand concentrates in Midwest dairy processing clusters and Brazil agricultural chemical distribution where cube utilization governs freight economics.
- Dispensing Jug:Engineered with integrated handles, vented closures, and controlled-flow neck designs for safe chemical handling. Agricultural chemical distributors in São Paulo state and institutional cleaning procurement managers specify these for end-user safety compliance and premium positioning.
- Round Jug:Legacy format prioritizing uniform wall thickness and simplified blow-molding tooling for commodity liquid packaging.
- Custom Jug:Application-specific designs requiring modified shoulder angles, label panels, or ergonomic grips for branded retail differentiation.
Square jug configurations hold the largest share; momentum sits with dispensing jug designs as safety regulations tighten.
Capacity:
Cost tier stratification separates high-volume commodity production from specialized mid-capacity runs serving institutional and agricultural channels.
- 5 Liters:Industrial workhorse format balancing manual handling ergonomics with transport efficiency for crop protection chemicals and institutional cleaners. Brazil ANVISA-compliant bulk procurement and Midwest dairy ingredient supply chains anchor demand for this tier.
- 1 Liter:Retail-optimized format governed by shelf-space constraints and household turnover velocity in food service and edible oil channels. India's FSSAI food-contact compliance expansion and organized retail consolidation are pulling this capacity tier.
- 2 Liters:Intermediate format serving household cleaning concentrates and small-scale agricultural applications where dilution ratios standardize packaging.
- 10 Liters:Bulk institutional format for commercial cleaning operations and agricultural refill stations where dispensing systems reduce per-use packaging costs.
Five-liter capacity dominates volume; one-liter formats are climbing the fastest as emerging market retail formalizes.
End User:
Customer type determines regulatory exposure and specification rigor, with agricultural and industrial segments demanding documentation that household retail does not.
- Agricultural:Crop protection chemical packaging governed by EPA container and containment regulations in the US and ANVISA standards in Brazil. Permeation performance, closure integrity, and UV stability specifications drive EVOH multilayer adoption and vented dispensing integration.
- Industrial:Institutional cleaning and chemical supply applications requiring UN-rated transport certification and ergonomic handling features for occupational safety compliance.
- Household:Mass-market beverage, edible oil, and cleaning product packaging where FDA 21 CFR 177.1520 food-contact compliance and shelf appeal govern procurement.
- Retail:Private-label and branded merchandise formats where label adhesion, stackability, and point-of-sale differentiation determine specification.
Agricultural end-use holds the largest share; momentum sits with household segments as cold-chain infrastructure expands in India.
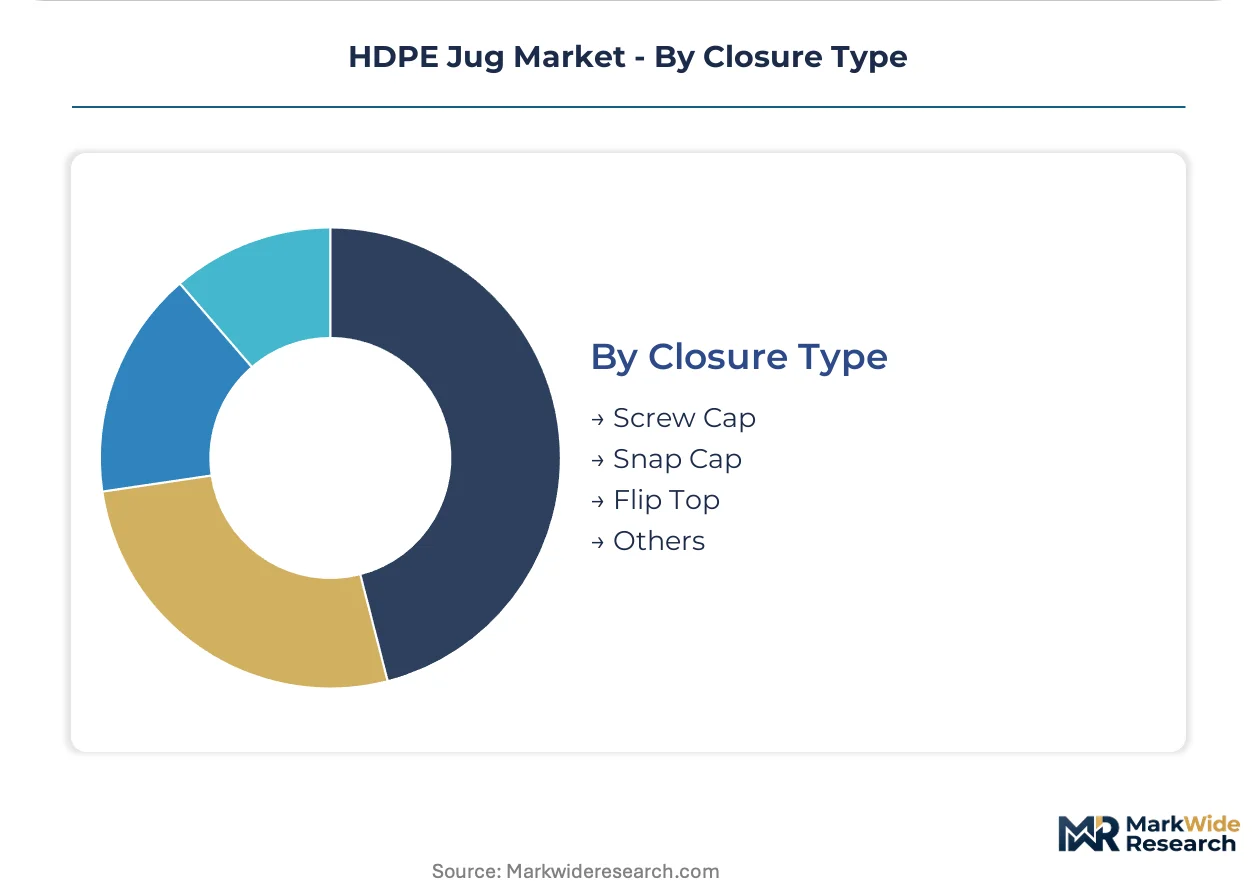
Closure Type:
Margin structure varies by closure complexity, with integrated dispensing and tamper-evident systems commanding premium positioning over commodity screw and snap configurations.
- Screw Cap:Standard threaded closure format offering resealability and broad tooling compatibility across blow-molding platforms. Commodity positioning in beverage and bulk chemical applications where cost minimization dominates specification.
- Flip Top:Hinged dispensing closure enabling single-handed operation for cleaning products and food service applications where convenience drives repeat purchase.
- Snap Cap:Press-fit closure for single-use or short-cycle applications where resealability is secondary to production speed and material minimization.
- Others:Specialized configurations including child-resistant closures, pump dispensers, and induction-sealed liners for pharmaceutical and high-liability chemical packaging.
Screw cap configurations hold the largest share; momentum sits with flip top designs as convenience positioning intensifies in retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's packaging waste regulation is redirecting capital toward mechanical recycling infrastructure in Germany and France. Brazil's ANVISA compliance mandates are accelerating bulk container procurement near São Paulo. India's FSSAI food-contact expansion is pulling one-liter format demand as organized retail consolidates.
United States
Midwest dairy processors in Wisconsin and Minnesota anchor five-liter jug procurement for ingredient supply chains. EPA container and containment regulations govern agricultural chemical packaging specifications for crop protection applications. Blow-molding capacity clusters near Chicago and Minneapolis serve both dairy and institutional cleaning channels with square and dispensing configurations.
Brazil
Agricultural chemical distributors are consolidating procurement around ANVISA-compliant bulk containers for crop protection chemicals. The São Paulo state processing centers anchor blow-molding capacity for five-liter dispensing jug formats. Distributor networks prioritize vented closure integration and UV stability specifications for tropical climate performance.
Germany
REACH post-consumer recycled content mandates are elevating compatibilizer R&D investment and mechanical recycling scale-up near industrial clusters. The EU Green Deal's extended producer responsibility fee modulation is forcing closure-to-jug material compatibility reformulation. Blow-molders in North Rhine-Westphalia are reconfiguring feedstock sourcing for export-bound agricultural chemical packaging.
India
FSSAI food-contact compliance pathways are opening for FDA-grade HDPE jug penetration in packaged food and edible oil sectors. Cold-chain infrastructure expansion in Maharashtra and Gujarat is enabling dairy and beverage bottling clusters. Organized retail consolidation in Delhi-NCR and Bangalore is standardizing one-liter format procurement for household turnover velocity.
China
Dual carbon goals under MEE oversight are elevating post-consumer recycled content minimums for rigid packaging serving domestic and export markets. Yangtze River Delta blow-molding capacity is retooling for compatibilizer technology integration. Pearl River Delta manufacturers are targeting India and Southeast Asia with cost-optimized square jug configurations for institutional cleaning channels.
HDPE Jug Market Competitive Landscape
On the supply side, the industry is consolidating around integrated resin sourcing and geographic density of reconditioning infrastructure. Tiered competitive positioning separates captive resin players from independent converters lacking cracker access. Three archetypes dominate: integrated petrochemical-packaging conglomerates, regional blow-molding specialists with recycling co-location, and private-equity-backed roll-up platforms. Capacity expansion and M&A consolidation represent the dominant competitive moves, with players acquiring distributed manufacturing footprints to anchor Midwest dairy and Brazil agrochemical supply chains.
Among North American packaging conglomerates, Berry Global and Consolidated Container Company exemplify divergent scale strategies. Berry Global occupies a position as an integrated resin-to-jug operator leveraging captive sourcing and blow-molding scale across retail channels. Consolidated Container Company anchors a regional density archetype through reconditioning and recycling infrastructure co-location near dairy processors. Amcor represents the multinational footprint archetype with diversified rigid packaging exposure spanning food, beverage, and industrial chemicals.
| Leading Market Players |
|---|
| Berry Global |
| Consolidated Container Company |
| Alpha Packaging |
| Comar |
| Gateway Plastics |
| Plastic Ingenuity |
| ProAmpac |
| Sonoco Products |
| Amcor |
| Others |
Supply & Pricing Matrix
Propylene co-monomer cost volatility determines both pricing tier spreads and supply chain shape across the HDPE jug market, forcing converters lacking captive cracker access into long-term supply contracts while compressing margins for spot-market dependent players.
Pricing Analysis
Certification level creates the primary spread between FDA-grade food-contact jugs and industrial chemical formats, with EPA container and containment compliance adding further premiums for agricultural applications. Pricing stratifies across premium multilayer EVOH configurations, standard virgin HDPE dairy formats, and economy recycled-content tiers for non-food industrial use. Cost compression in standard dairy jugs is intensifying because Midwest processor procurement consolidation squeezes converter margins. Household retail channels exhibit highest price sensitivity, while agricultural chemical distributors prioritize permeation performance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for blow-molding equipment and compatibilizer additives. Feedstock sourcing concentrates in the US Gulf Coast, Saudi Arabia, and Singapore, with resin distribution running through regional converter networks near Wisconsin dairy clusters and São Paulo agricultural chemical processors. The supply chain draws from virgin HDPE pellet suppliers, post-consumer recycled flake processors, and EVOH barrier film co-extruders. Single-source vulnerability persists in specialized vented closure molding tools. Downstream distribution feeds through three-tier wholesaler networks eroding under direct manufacturer portal expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated agricultural chemical distributors and Midwest dairy processor procurement teams, fragmenting traditional converter pricing leverage.
For Market Incumbents: Entrench position through backward integration into captive resin sourcing and mechanical recycling infrastructure co-location near Wisconsin dairy processing clusters. Accelerate compatibilizer R&D investment to meet EU REACH post-consumer recycled content mandates before reformulation deadlines compress. Defend against e-commerce procurement platform disintermediation by deploying direct customer portals with real-time capacity visibility. For New Entrants and Emerging Players: India's FSSAI food-contact compliance pathways represent the most penetrable entry point for FDA-grade HDPE jug penetration as organized retail consolidates procurement in Delhi-NCR and Bangalore. Brazil's ANVISA-compliant bulk container procurement near São Paulo state processing centers offers second-mover opportunity in five-liter dispensing formats. Target integrated closure system partnerships with agricultural chemical distributors seeking vented handle designs. For Investors and Strategic Acquirers: Regional blow-molding specialists with recycling infrastructure co-location offer the strongest acquisition profile for long-term viability across the analysis window. Monitor EU Green Deal extended producer responsibility fee modulation implementation as the inflection indicator for compatibilizer technology valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Sourcing | Insulates margin stability from propylene co-monomer price swings for converters serving Midwest dairy clusters. |
| Mechanical Recycling Infrastructure Scale-Up | Positions blow-molders to capture EU REACH post-consumer recycled content mandate premiums near industrial clusters. |
| Direct-to-Procurement-Manager Digital Platform Deployment | Erodes traditional three-tier distributor networks while enabling customer data ownership for North American converters. |
| EVOH Multilayer Co-Extrusion Capacity Addition | Extends shelf-life performance for oxygen-sensitive agricultural chemicals in tropical Brazil and extended-hold dairy. |
| Integrated Dispensing Closure System Development | Commands premium positioning in ANVISA-compliant agricultural chemical channels where end-user safety protocols govern specification. |
Research Methodology
A spread of perspectives from blow-molding plant managers, agricultural chemical procurement leads, dairy processor supply chain directors, and compatibilizer R&D heads converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA 21 CFR filings, EPA container and containment regulation updates, EU ECHA REACH guidance documents, and customs trade data for HDPE resin flows. Bottom-up capacity modeling across extrusion blow-molding lines triangulated against top-down demand aggregation from end-use sector consumption patterns.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product geometry tier, capacity format, end-use regulatory exposure cluster, and closure system complexity. CAGRs were derived from iterative reconciliation between historical production capacity utilization and forward-looking procurement intent signals from distributor networks. Forecast inputs incorporated melt temperature control automation adoption curves and post-consumer recycled flake quality variability assumptions.
Practitioners should monitor EU Green Deal packaging waste regulation implementation timelines and Brazil ANVISA compliance deadline shifts for early signals of feedstock sourcing reconfiguration. Forecasts reflect assumptions about mechanical recycling infrastructure deployment rates and virgin resin price volatility persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Indonesia Plastic Packaging Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
Clear Plastic Boxes Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
Plastic Caulk Tube Market