
 Plastic Shrink Wrap Market | 2026-2036
Plastic Shrink Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Shrink Wrap Market Analytics
E-commerce fulfillment channels is rewriting procurement patterns for protective packaging across North America and Asia-Pacific. Sealed Air Corporation leverages its automated packaging systems to anchor contract relationships with major retail distributors. Berry Global competes through vertical integration from resin compounding to finished film production. Amcor plc extends its sustainability credentials with certified recyclable shrink film portfolios across European grocery supply chains.
Plastic shrink wrap comprises thermoplastic films, primarily polyolefin, PVC, or polyethylene, that contract tightly around products when heated to temperatures between 100°C and 160°C, creating a tamper-evident protective barrier. The film's biaxial orientation and memory properties enable uniform conformance to irregular shapes, serving industrial bundling, retail display, and transit protection needs. Polyolefin formulations now lead food packaging applications due to superior clarity and FDA-compliant direct-contact approvals, while PVC persists in industrial bundling where cost sensitivity dominates purchasing decisions. Medical packaging represents the fastest-expanding application segment as sterilization-grade films gain traction in pharmaceutical distribution.
FDA food-contact regulations and EU REACH chemical restrictions shape material selection and converter certification requirements across export-oriented supply chains. EPA emissions guidelines and state-level extended producer responsibility laws in California and New York impose compliance costs that favor larger integrated manufacturers over regional converters. Stakeholders must monitor evolving state recycling mandates and bio-based resin certification standards to secure long-term supply contracts with sustainability-focused brand owners.
Market Dynamics
EU REACH chemical restrictions and California extended producer responsibility laws are forcing converters to abandon PVC formulations and certify recyclable polyolefin alternatives, restructuring material procurement across export supply chains.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Green Deal's circular economy action plan requires all plastic packaging to be recyclable by 2030, accelerating converter investment in certified polyolefin shrink film lines serving European grocery distribution.
- Medical sterilization packaging:Pharmaceutical distributors are adopting gamma-radiation-stable shrink films for surgical kit bundling, creating demand for FDA-validated, sterile-barrier-compliant formulations in North American hospital supply chains.
- E-commerce fulfillment automation:Automated packaging systems in US and Chinese distribution centers require consistent film gauge and seal integrity, pulling volume toward integrated film producers capable of tight specification control.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock costs fluctuate with crude oil benchmarks, compressing converter margins and destabilizing annual contract pricing for industrial bundling customers.
- Asian supply concentration:Over 60% of global biaxially oriented polyolefin capacity sits in Chinese and South Korean manufacturing clusters, exposing buyers to shipping disruption and tariff exposure.
- Mechanical recycling contamination:Multi-layer shrink films with incompatible polymer adhesives fail European mechanical recycling streams, limiting post-consumer content claims and circular economy participation.
Strategic Opportunities
- Indian cold-chain expansion:India's FSSAI-mandated food safety modernization is driving shrink wrap adoption for temperature-sensitive pharmaceutical and fresh produce distribution in Mumbai and Delhi logistics corridors.
- Bio-based resin certification:ASTM D6400 and EN 13432 compostable certifications for PLA shrink films open premium positioning in European organic food retail, where brand owners pay specification premiums for sustainability credentials.
- Digital printing integration:Convergence of shrink film extrusion with inline digital printing enables SKU-level customization for short-run promotional packaging, displacing pre-printed labels in North American craft beverage segments.
Industry Challenges
- Extrusion technician scarcity:Biaxial orientation line operators require specialized training in bubble stability and gauge control, with labor shortages concentrated in US Midwest manufacturing corridors.
- Recyclability certification timelines:How2Recycle and OPRL pre-qualification processes demand 12-18 month validation cycles, delaying product launches for converters serving sustainability-focused brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Shrink Wrap Market |
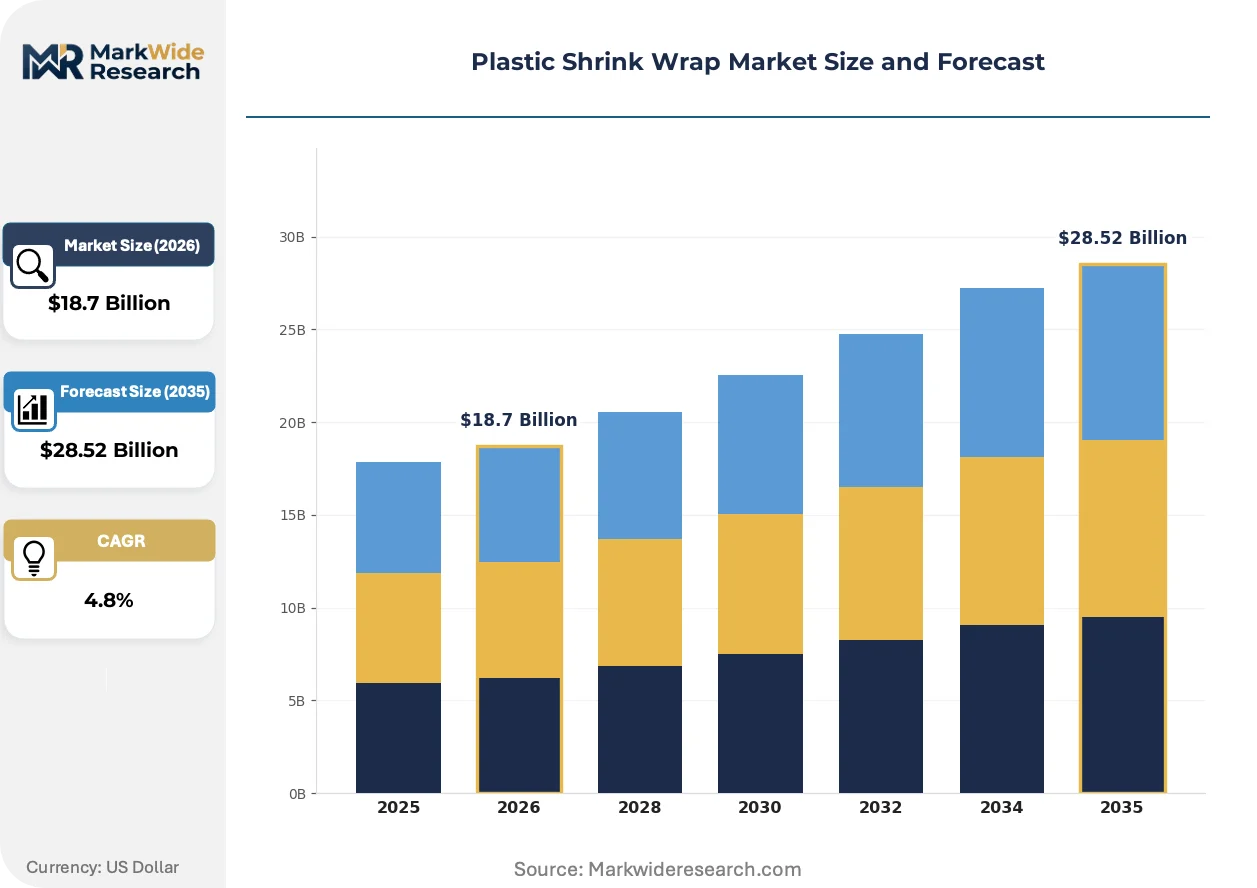
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, PVC, Polyester, Polyethylene Application: Food Packaging, Industrial Packaging, Retail Packaging, Medical Packaging Distribution Channel: Online Retail, Supermarkets, Distributors, Wholesale End User: Food Industry, Pharmaceuticals, Electronics, Consumer Goods |
| Companies Covered | Amcor plc, Coveris Holdings, Sealed Air Corporation, Fuji Seal International, AEP Industries, Berry Global, Intertape Polymer Group, Clondalkin Group Holdings, Sigma Plastics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Shrink Wrap Market Evolving Landscape
Material science advances and regulatory compliance automation are compressing development cycles for next-generation shrink films, while digital integration reconfigures converter-customer relationships across specification-heavy segments.
Cross-linked polyolefin shrink film is migrating from general industrial bundling into precision medical device packaging, where Boston Scientific and Medtronic suppliers demand sub-50-micron gauges with validated sterile barrier performance. European contract manufacturers are adopting these films at 15-20% annual volume expansion rates. This technology is displacing thermoformed trays in mid-volume surgical kit applications, reducing packaging mass and sterilization validation costs.
REACH Annex XVII restrictions on phthalate plasticizers have eliminated flexible PVC shrink film from European toy and cosmetics packaging, redirecting formulation R&D toward citrate-based plasticizers and bio-based alternatives. German converters report 30% formulation reformulation costs passed through to customers. Food-contact and personal-care segments are responding fastest, with French and Italian brand owners demanding full material disclosure documentation.
Brand owners now specify recyclability credentials ahead of optical or mechanical performance in initial procurement discussions, reversing traditional specification hierarchies. Retail distributors in Germany and the Netherlands are consolidating supplier bases to partners with EFSA-approved recycling stream compatibility data. This behavioral shift is most visible in private-label grocery, where Aldi and Lidl sourcing teams mandate How2Recycle-prequalified films for all new product introductions.
Plastic Shrink Wrap Market Segmentation
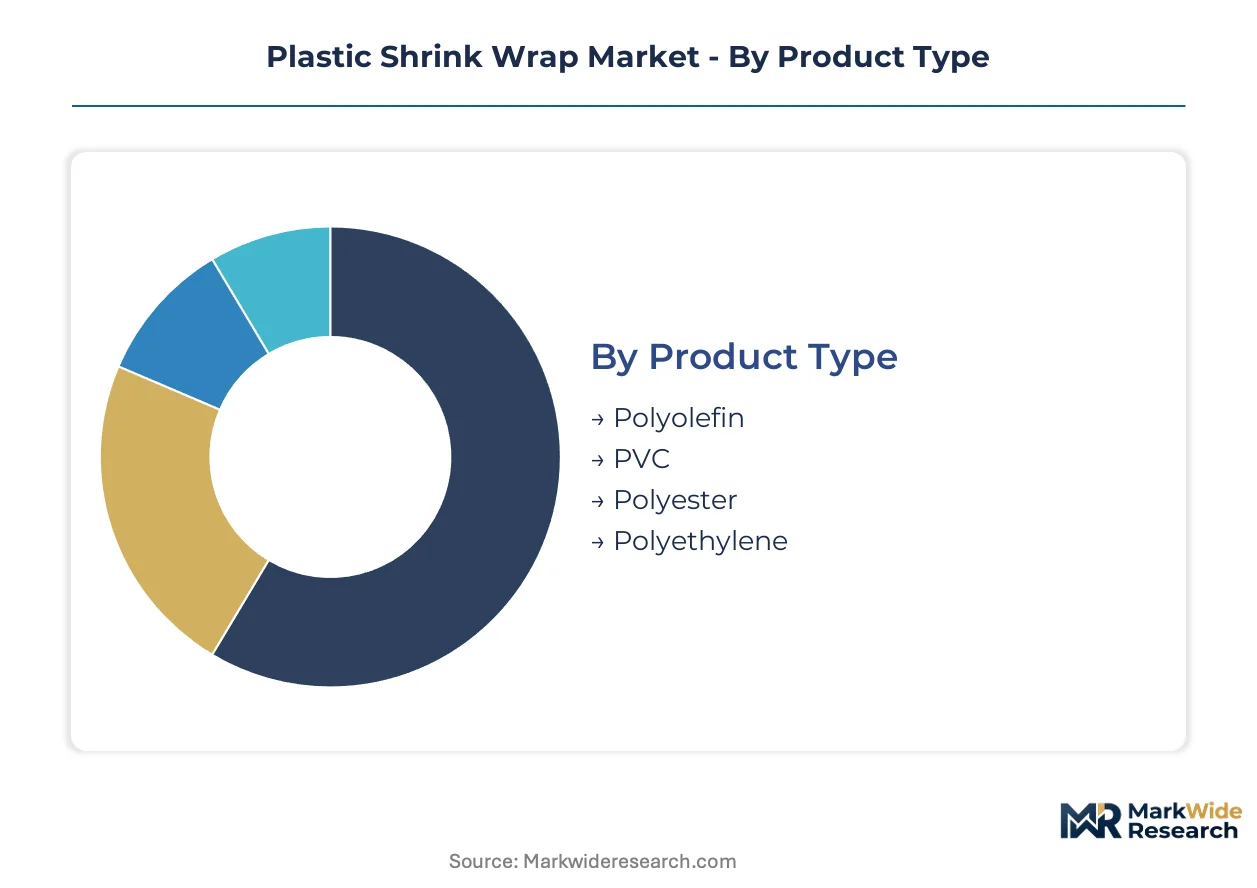
Segmentation in plastic shrink wrap reveals how material chemistry, end-use performance requirements, and channel economics partition converter capabilities. Procurement specifications diverge sharply between food-contact compliance and industrial bundling cost thresholds.
Product Type:
Mature commodity resins anchor volume, while specialty formulations capture specification premiums in regulated applications.
- Polyolefin:Cross-linked and non-cross-linked polypropylene and polyethylene copolymers deliver superior optical clarity and FDA-compliant direct food contact. German grocery distributors and US retail chains specify these films for high-visibility packaging where shelf appeal drives procurement decisions.
- PVC:Plasticized polyvinyl chloride persists in industrial bundling and construction material wrapping where cost sensitivity outweighs sustainability concerns. REACH Annex XVII phthalate restrictions have eliminated this material from European consumer-facing applications, concentrating residual demand in Asian manufacturing clusters and North American industrial corridors.
- Polyester:PET-based shrink films offer dimensional stability and higher shrink force for contour-heavy applications.
- Polyethylene:LDPE and LLDPE formulations serve general-purpose bundling with lower equipment temperature requirements.
Polyolefin retains volume leadership; medical-grade cross-linked variants hold the steepest expansion curve.
Application:
Application segmentation tracks regulatory intensity, with food and medical segments demanding validated compliance documentation.
- Food Packaging:Direct-contact polyolefin films require FDA 21 CFR 177.1520 or EFSA migration testing for fatty and aqueous foods. European supermarket private-label programs now mandate How2Recycle pre-qualification, filtering supplier bases toward integrated converters with recycling stream compatibility data.
- Medical Packaging:Gamma-radiation-stable, sterile-barrier-compliant films for surgical kit bundling command 40-60% specification premiums over industrial grades. Boston Scientific and Medtronic supply chains validate sub-50-micron gauges with seal integrity testing, displacing thermoformed trays in mid-volume kit configurations.
- Industrial Packaging:Pallet unitization and construction material bundling prioritize throughput speed and film yield economics.
- Retail Packaging:Point-of-sale display wrapping combines optical properties with tamper-evidence for consumer goods.
Food packaging dominates procurement volume; medical sterilization applications are gaining share fastest.
Distribution Channel:
Channel structure reflects customer scale and specification complexity, with automated fulfillment systems rewiring procurement patterns.
- Distributors:Regional and national industrial supply distributors aggregate fragmented demand from small and mid-sized converters, offering technical support and inventory financing. These intermediaries capture 25-35% margin on specialty films while pushing commodity grades toward price-competitive transparency.
- Online Retail:E-commerce platforms serve maintenance-repair-operations procurement and small-batch specialty film sourcing, with Alibaba and Amazon Business capturing growing share of standard gauge polyethylene orders from independent packaging operations.
- Supermarkets:Direct procurement relationships with retail grocery chains for private-label packaging.
- Wholesale:Volume aggregation for industrial bundling customers with predictable consumption patterns.
Distributors maintain channel leadership; online retail is climbing the fastest among procurement alternatives.
End User:
End-user segmentation aligns with regulatory exposure and supply chain consolidation patterns across vertically integrated industries.
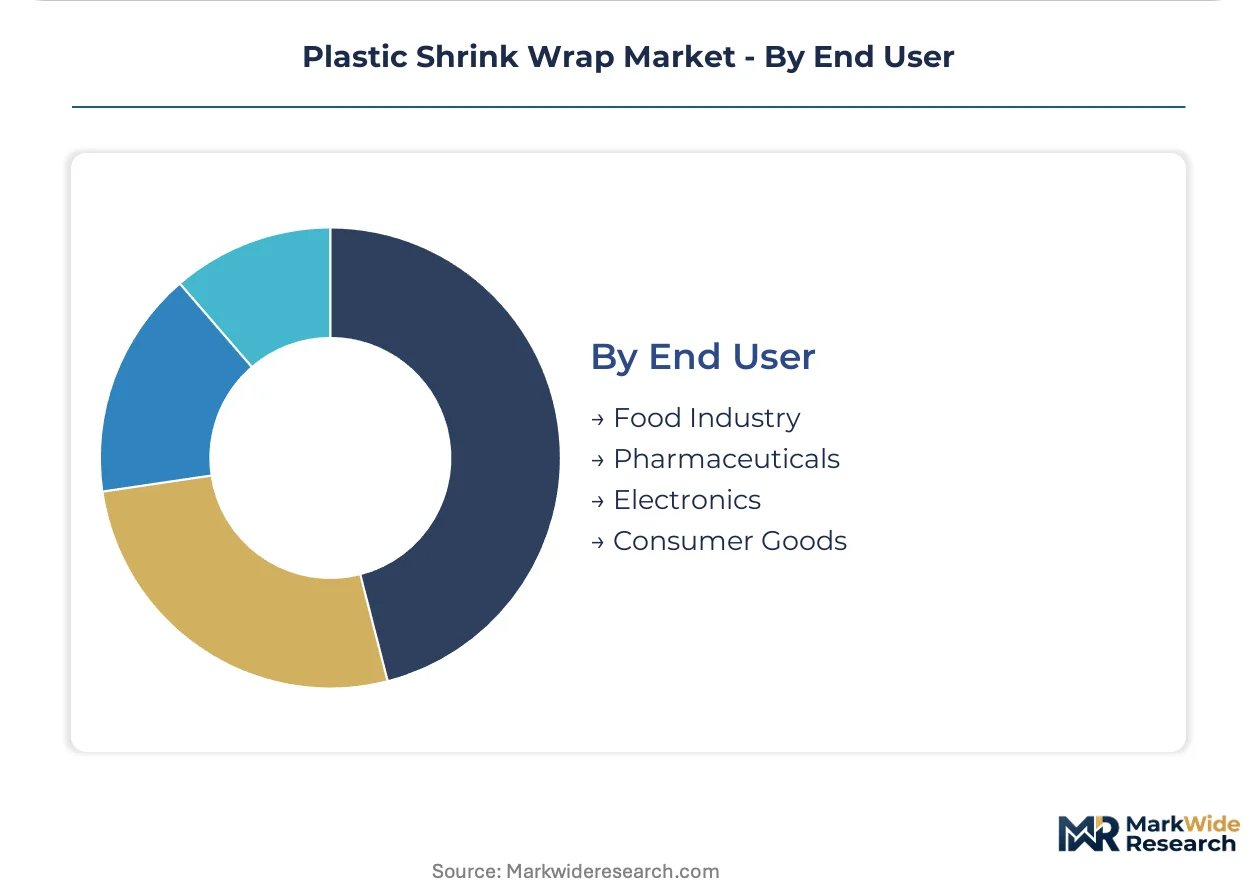
- Food Industry:Processors and co-packers serving retail grocery and foodservice channels specify films with direct-contact approvals and recyclability credentials. Aldi and Lidl sourcing teams in Germany and the Netherlands mandate EFSA-compatible recycling stream data, consolidating supplier relationships toward converters with vertical resin-to-film capabilities.
- Pharmaceuticals:Cold-chain and sterilization packaging for temperature-sensitive biologics and surgical supplies demands validated sterile barrier performance. India's FSSAI-mandated food safety modernization is extending pharmaceutical-grade specifications into fresh produce distribution in Mumbai and Delhi logistics corridors.
- Electronics:Anti-static and moisture-barrier films for component shipping and retail display.
- Consumer Goods:General merchandise bundling and promotional packaging with printed branding.
Food industry end users command procurement volume; pharmaceutical applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's 2030 recyclability mandate is restructuring converter investment across export supply chains, while India's FSSAI food safety modernization opens cold-chain packaging corridors in Mumbai and Delhi.
Germany
Aldi and Lidl sourcing teams mandate How2Recycle pre-qualification for all private-label shrink film procurement. REACH Annex XVII phthalate restrictions eliminated flexible PVC from toy and cosmetics packaging, redirecting demand toward certified polyolefin alternatives. The Düsseldorf-Cologne industrial corridor hosts integrated converters serving European grocery distribution networks with EFSA-compatible recycling stream documentation.
United States
FDA 21 CFR 177.1520 direct-contact approvals drive polyolefin specification for retail food packaging. California extended producer responsibility laws and New York state recycling mandates impose compliance costs favoring larger integrated manufacturers over regional converters. Automated fulfillment systems in Chicago and Dallas distribution centers pull volume toward film producers with tight gauge control capabilities.
China
Over 60% of global biaxially oriented polyolefin capacity concentrates in Chinese manufacturing clusters, exposing buyers to shipping disruption and tariff exposure. The country's dual carbon goals and MEE emissions guidelines are pressuring converters toward energy-efficient extrusion lines. The Yangtze River Delta and Pearl River Delta regions serve as primary export hubs for Asia-Pacific retail and industrial supply chains.
India
FSSAI-mandated food safety modernization is driving shrink wrap adoption for temperature-sensitive pharmaceutical and fresh produce distribution. Mumbai and Delhi logistics corridors see accelerating demand for cold-chain packaging as pharmaceutical distributors adopt gamma-radiation-stable films. Domestic converters are expanding biaxial orientation capacity to reduce import dependence from Chinese and South Korean suppliers.
Japan
METI industrial standards and JIS certification requirements shape material selection for precision packaging applications. Pharmaceutical distributors demand validated sterile barrier performance for surgical kit bundling, creating specification premiums over industrial grades. The Kanto and Kansai manufacturing belts concentrate medical-grade film production serving Boston Scientific and Medtronic supply chains.
Plastic Shrink Wrap Market Competitive Landscape
On the supply side, the industry is consolidating around integrated resin-to-film producers capable of vertical control over specification-heavy segments. Three archetypes dominate: multinational packaging conglomerates with automated systems integration, regional specialists with recycling stream certification capabilities, and commodity converters competing on throughput economics. Competitive moves center on M&A for recycling technology access and capacity expansion in India and Southeast Asia.
Among North American packaging conglomerates, Sealed Air Corporation and Berry Global exemplify the integrated archetype, with the former anchoring automated packaging system relationships and the latter representing backward integration from resin compounding to finished film production. Amcor plc occupies a position within the sustainability-certified tier, serving European grocery supply chains with recyclable portfolio offerings.
| Leading Market Players |
|---|
| Amcor plc |
| Coveris Holdings |
| Sealed Air Corporation |
| Fuji Seal International |
| AEP Industries |
| Berry Global |
| Intertape Polymer Group |
| Clondalkin Group Holdings |
| Sigma Plastics Group |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor's container rate volatility feeds directly into converter margin structures, amplifying price spreads between certified polyolefilm grades and commodity PVC alternatives while rewarding integrated producers with captive resin supply.
Pricing Analysis
Certification level creates the primary spread between medical-grade cross-linked polyolefin and industrial bundling films. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 21 CFR 177.1520 compliance, How2Recycle pre-qualification status, and gauge tolerance precision. Cost compression in commodity PVC runs through ethylene feedstock linkage to crude benchmarks, squeezing regional converter margins. Industrial bundling customers exhibit highest price sensitivity, while pharmaceutical distributors absorb specification premiums for sterile-barrier validation.
Supply Chain Analysis
Export-control scrutiny on advanced polymer processing equipment limits capacity expansion outside established manufacturing clusters. Over sixty percent of biaxially oriented polyolefin capacity concentrates in China, South Korea, and Germany, drawing from ethylene and propylene feedstocks tethered to naphtha cracking economics. Single-source vulnerability concentrates in Chinese biaxial orientation lines serving global pharmaceutical and food packaging demand. Distribution runs through integrated multinational producers for specification-heavy segments, with regional distributors aggregating fragmented industrial bundling volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from fiber-based packaging and molded pulp alternatives in European grocery channels, demanding defensive repositioning around recyclability credentials and automation integration.
For Market Incumbents: Insulate core relationships by securing How2Recycle and OPRL pre-qualification ahead of EU Green Deal enforcement timelines, while anchoring automated packaging system partnerships with major retail distributors to raise switching costs. Backward integration into resin compounding defends margin position against ethylene price volatility.
For New Entrants and Emerging Players: Establish a beachhead in India's FSSAI-mandated cold-chain expansion corridors, where domestic biaxial orientation capacity lags pharmaceutical and fresh produce demand growth. Target gamma-radiation-stable film niches for surgical kit bundling, leveraging technical service capabilities to displace imported Chinese supply.
For Investors and Strategic Acquirers: Regional specialists with EFSA-compatible recycling stream documentation and established Aldi or Lidl supply relationships represent priority acquisition targets. Long-term viability hinges on circular economy participation credentials. Watch for state-level extended producer responsibility law passage as inflection signal for consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Recyclability Certification Investment | How2Recycle pre-qualification unlocks Aldi and Lidl private-label procurement pipelines. |
| Backward Integration into Resin Compounding | Captive polyolefin supply hedges margin compression from ethylene feedstock volatility. |
| Medical-Grade Capacity Expansion | FDA-validated sterile barrier films capture 40-60% specification premiums over industrial grades. |
| Automation System Partnership | Sealed Air-style integrated packaging lines anchor long-term retail distributor contracts. |
| Indian Manufacturing Footprint | FSSAI modernization drives cold-chain film demand in Mumbai and Delhi logistics corridors. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings, and ECHA REACH registration data preceded structured interviews with biaxial orientation line operators, pharmaceutical packaging procurement managers, retail grocery category buyers, and resin compounding technical directors. Primary fieldwork across the Düsseldorf-Cologne corridor, Yangtze River Delta, and US Midwest manufacturing belts was cross-checked against ACC and Cefic industry statistics. Bottom-up capacity utilization data and top-down trade flow analysis were triangulated to validate volume estimates.
Assumptions around EU Green Deal enforcement timelines, crude oil benchmark linkage to ethylene spreads, and FDA validation cycle durations were held fixed across the projection horizon. The analytical framework modeled material type, application regulatory intensity, end-user industry vertical, and geographic production hub as core segmentation dimensions. CAGRs were derived from fitted trend extrapolation against historical capacity expansion patterns, with medical sterilization adoption curves and e-commerce fulfillment automation penetration serving as key demand-side inputs.
Stress conditions across resin price volatility bands, shipping disruption scenarios, and REACH Annex XVII expansion scopes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with mechanical recycling contamination thresholds and bio-based resin certification adoption representing primary revision risks. Cross-checking against ECHA substance volume tracking and national extended producer responsibility implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Italy Plastic Bottles Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Thailand Plastic Bottles Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
PCR Films Market
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
GCC Plastic Packaging Market
Plastic Packaging
Mushroom Plastics Market