
 Egypt Plastic Packaging Market | 2026-2036
Egypt Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Plastic Packaging Market Foresight
Subscription-based packaging design services is expanding as a distinct revenue layer, shifting converter economics from pure volume contracts toward recurring technical consulting. Amcor Plc leverages its global R&D network to anchor premium flexible film specifications for multinational food brands operating in Egypt. National Company for Packaging Industries (NatPack S.A.E.) sustains domestic manufacturing scale across rigid container lines serving local dairy and edible oil processors. Rotografia Group S.A.E. specializes in high-definition label printing, competing on short-run customization for regional personal care brands.
Egypt plastic packaging encompasses fabricated polymer structures engineered to contain, protect, and preserve goods through barrier control, mechanical strength, and seal integrity, typically manufactured via extrusion, blow molding, or thermoforming processes with wall thicknesses calibrated to product sensitivity. Polyethylene dominates material consumption due to its cost-efficiency in flexible film extrusion for food contact applications. Injection molding commands technology selection for rigid healthcare containers where dimensional precision and closure thread integrity are critical. Flexible Films represents the fastest-growing product category, driven by downgauging innovations that reduce resin input per unit while maintaining tensile performance.
Egypt's Ministry of Environment administers Extended Producer Responsibility compliance, while the Egyptian Organization for Standardization and Quality (EOS) governs food contact material migration limits under harmonized technical regulations. These frameworks elevate testing costs for imported resin grades and incentivize local certification capacity. Stakeholders must monitor forthcoming amendments to biodegradable content mandates, as draft provisions under national sustainable development strategy review could reshape material procurement specifications and converter capital allocation priorities.
Market Dynamics
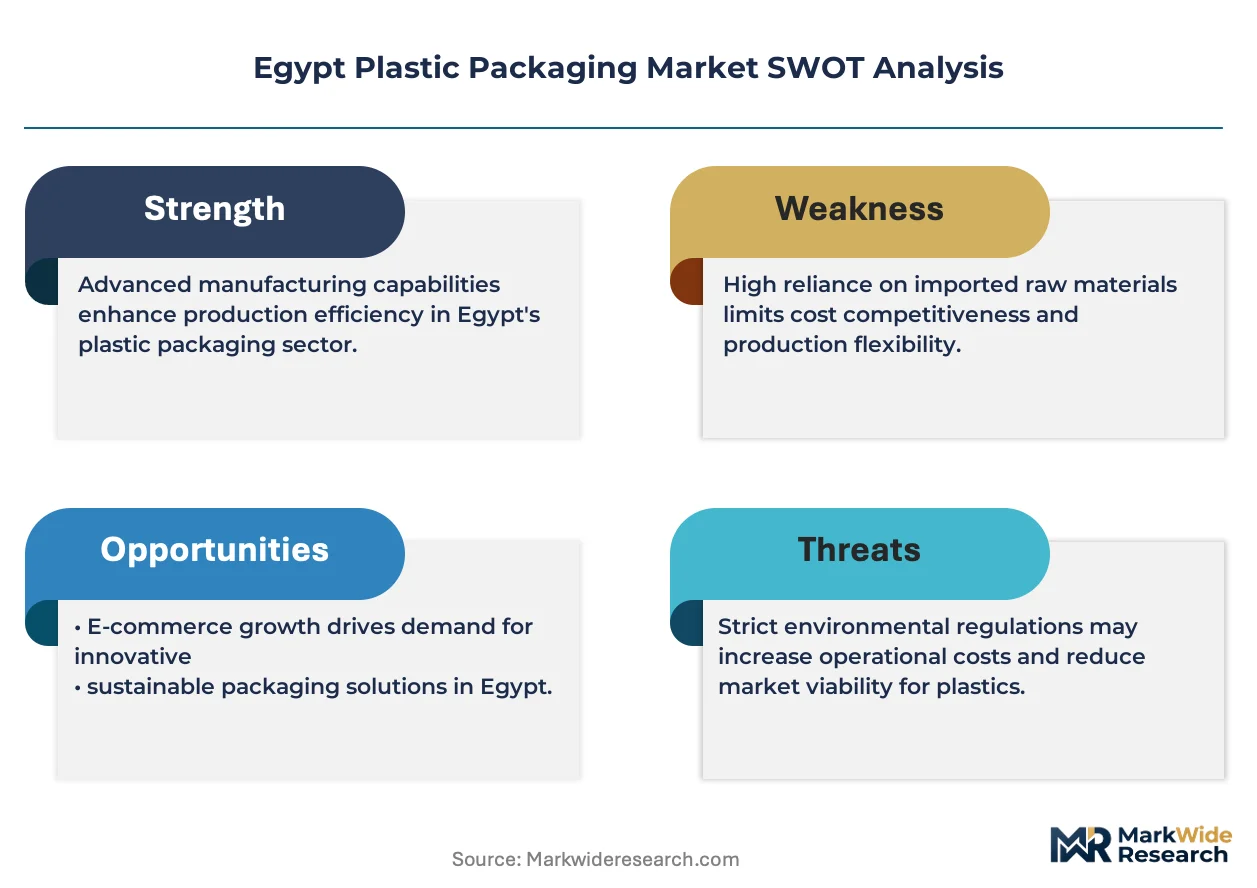
Extended Producer Responsibility enforcement by Egypt's Ministry of Environment is redirecting converter capital toward recyclable material streams and certified resin procurement, compressing margins for non-compliant processors while rewarding early certification adopters.
Growth Catalysts
- Food Contact Compliance:Egyptian Organization for Standardization and Quality migration limit enforcement drives demand for certified polyethylene grades in dairy and edible oil packaging.
- Suez Canal Logistics:Greater Cairo industrial corridor proximity to canal infrastructure reduces export lead times for flexible film converters serving European buyers.
- Downgauging Innovation:Thinner film extrusion technologies cut resin input per unit while maintaining tensile performance for extended shelf-life applications.
Market Restraints
- Resin Import Dependency:Testing cost escalation for non-certified imported polyethylene grades elevates working capital requirements for small-scale converters.
- Biodegradable Mandate Uncertainty:Draft provisions under Egypt's national sustainable development strategy review create procurement specification ambiguity and capital allocation paralysis.
- Substitution Pressure:Glass and metal packaging alternatives gain traction in premium personal care segments where barrier performance justifies cost premiums.
Strategic Opportunities
- Alexandria Port Expansion:New container terminal capacity enables direct resin import bypassing Cairo warehousing for Delta region converters.
- Subscription Design Services:Technical consulting contracts replace pure volume agreements, embedding converters deeper into multinational brand specification processes.
- Healthcare Rigid Containers:Injection molding precision requirements for pharmaceutical vials and closure systems command price premiums over commodity food packaging.
Industry Challenges
- Migration Testing Bottlenecks:Limited local EOS certification laboratory capacity extends product launch timelines for imported resin formulations.
- Skilled Extrusion Technician Scarcity:Multi-layer film coextrusion expertise concentrates at Amcor's technical center, constraining competitor process optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Plastic Packaging Market |
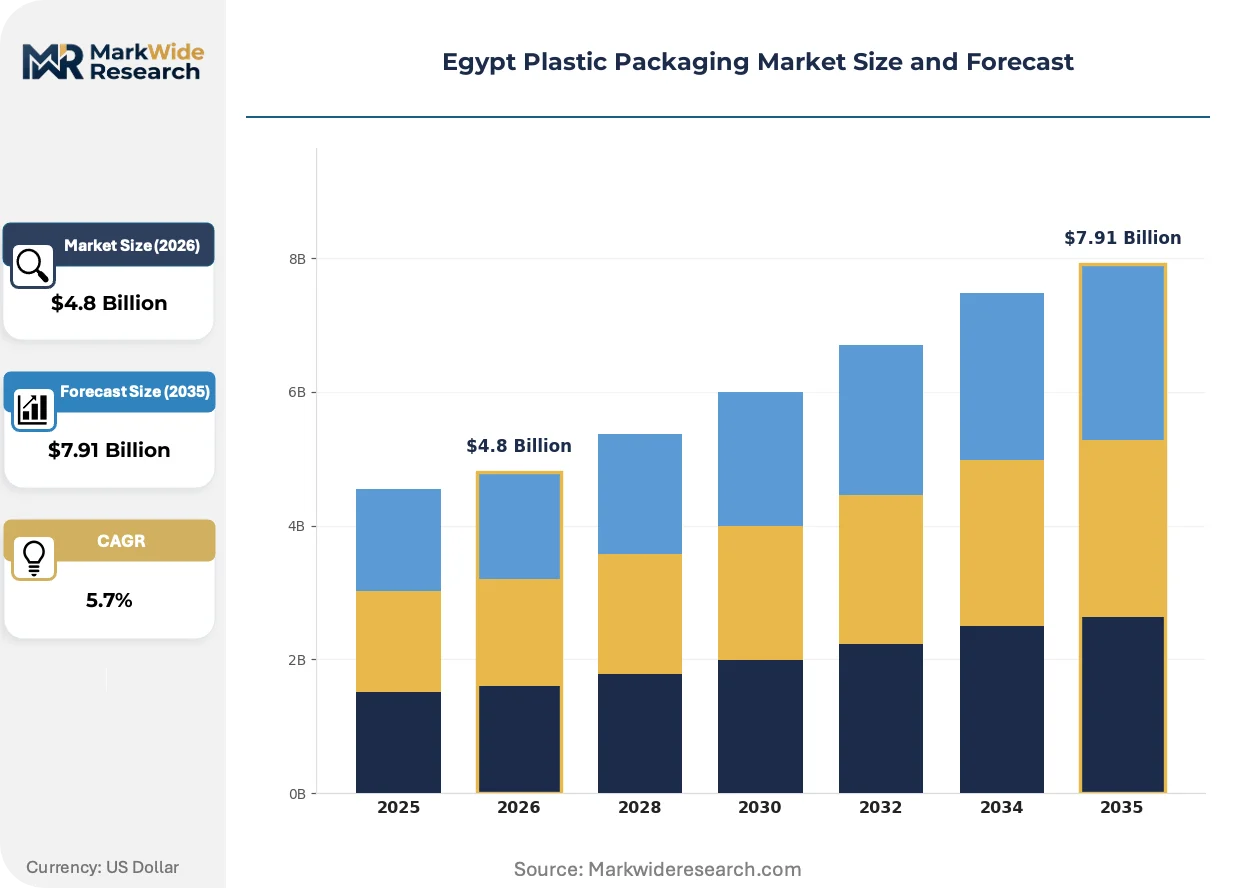
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Containers, Flexible Films, Labels, Bags Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Food & Beverage, Healthcare, Personal Care, Household Products Technology: Injection Molding, Blow Molding, Thermoforming, Extrusion |
| Companies Covered | Amcor Plc, National Company for Packaging Industries (NatPack S.A.E.), Rotografia Group S.A.E., Taghleef Industries LLC, Coveris Flexibles Egypt S.A.E., ALPLA Werke Alwin Lehner GmbH & Co KG, Uflex Limited, International Printing & Packaging Materials Co. (IPP), Huhtamaki Oyj, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Plastic Packaging Market Shifts & Advancements
Digital printing integration and mono-material flexible film architectures are compressing converter competitive cycles, forcing rapid equipment reinvestment and technical workforce expansion across Egypt's packaging corridor.
Multi-layer coextrusion with ethylene vinyl alcohol barrier cores is electrifying high-performance food packaging specifications. Multinational dairy processors operating in 10th of Ramadan City are adopting these structures at accelerated pace to replace metallized films. The technology is electrifying premium segment entry for mid-cap converters previously excluded from extended shelf-life contracts.
Egypt's Ministry of Environment Extended Producer Responsibility framework mandates annual recycling volume targets for packaging producers above defined thresholds. Industrial consequence includes mandatory reporting infrastructure investment and third-party audit costs. Flexible film converters in Obour City industrial zones are responding by consolidating scrap collection networks and pre-qualifying recyclers for compliance documentation.
Brand technical audits now precede volume procurement commitments for multinational food accounts. Large-scale processors are displacing spot-market resin purchasing with certified supplier master agreements spanning 24-36 month horizons. This pattern concentrates most visibly in Greater Cairo's industrial corridor where Amcor and NatPack compete for dairy sector specifications through embedded design engineering teams.
Egypt Plastic Packaging Market Segmentation
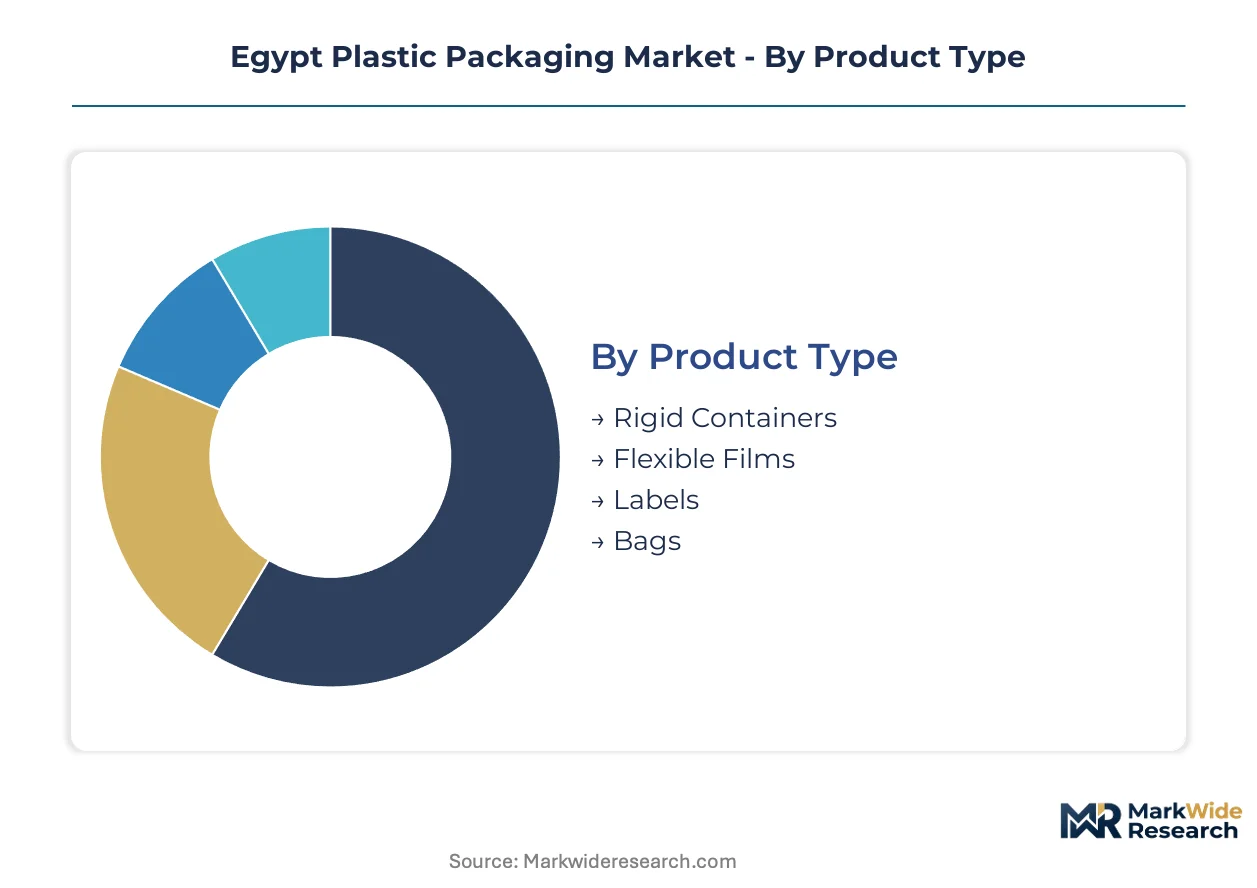
Segmentation in Egypt's plastic packaging market reveals how technology choices, material specifications, and end-use requirements create distinct competitive arenas. Each axis shapes capital allocation, certification burdens, and margin structures differently across Greater Cairo's industrial corridor.
Product Type:
Extrusion and forming technologies define performance thresholds across container architectures.
- Flexible Films:Multi-layer coextrusion with ethylene vinyl alcohol barrier cores dominates extended shelf-life dairy and edible oil applications. Downgauging innovations cut resin input per unit while maintaining tensile performance, driving specification upgrades among 10th of Ramadan City processors.
- Rigid Containers:Injection-molded structures with calibrated wall thicknesses serve dairy and edible oil processors requiring dimensional precision and closure thread integrity. NatPack S.A.E. sustains domestic manufacturing scale across these lines.
- Labels:High-definition printing for short-run customization serves regional personal care brands, with Rotografia Group S.A.E. competing on graphic fidelity and rapid turnaround.
- Bags:Commodity polyethylene extrusion for bulk commodity packaging faces margin compression from resin import dependency and Extended Producer Responsibility compliance costs.
Mature deployment sits with Rigid Containers. Newer deployment is concentrated in Flexible Films.
Material:
Cost efficiency and regulatory compliance drive procurement concentration across polymer grades.
- Polyethylene:Dominates material consumption through cost-efficient flexible film extrusion for food contact applications. Egyptian Organization for Standardization and Quality migration limit enforcement elevates demand for certified grades.
- Polypropylene:Stiffer molecular structure suits healthcare rigid containers and higher-temperature food applications. Testing cost escalation for non-certified imported grades elevates working capital requirements for small-scale converters.
- Polyvinyl Chloride:Barrier properties serve pharmaceutical blister packs and chemical-resistant industrial packaging, constrained by environmental scrutiny under Ministry of Environment frameworks.
- Polystyrene:Thermoformed trays and disposable foodservice items face substitution pressure from biodegradable mandate uncertainty and capital allocation paralysis.
Procurement volume concentrates in Polyethylene. Specification premiums accrue to Polypropylene.
End User:
Barrier requirements and regulatory exposure segment demand intensity across consumer sectors.
- Food & Beverage:Extended shelf-life specifications drive multi-layer film adoption among multinational dairy processors. Suez Canal logistics proximity reduces export lead times for flexible film converters serving European buyers.
- Healthcare:Injection molding precision for pharmaceutical vials and closure systems commands price premiums over commodity food packaging. EOS certification laboratory capacity constraints extend product launch timelines.
- Personal Care:Premium segments see glass and metal packaging alternatives gain traction where barrier performance justifies cost premiums. Short-run label customization demands compress converter competitive cycles.
- Household Products:Chemical resistance requirements favor rigid container specifications with thicker wall calibrations and threaded closure systems.
Technical audit intensity peaks in Food & Beverage. Margin expansion potential sits with Healthcare.
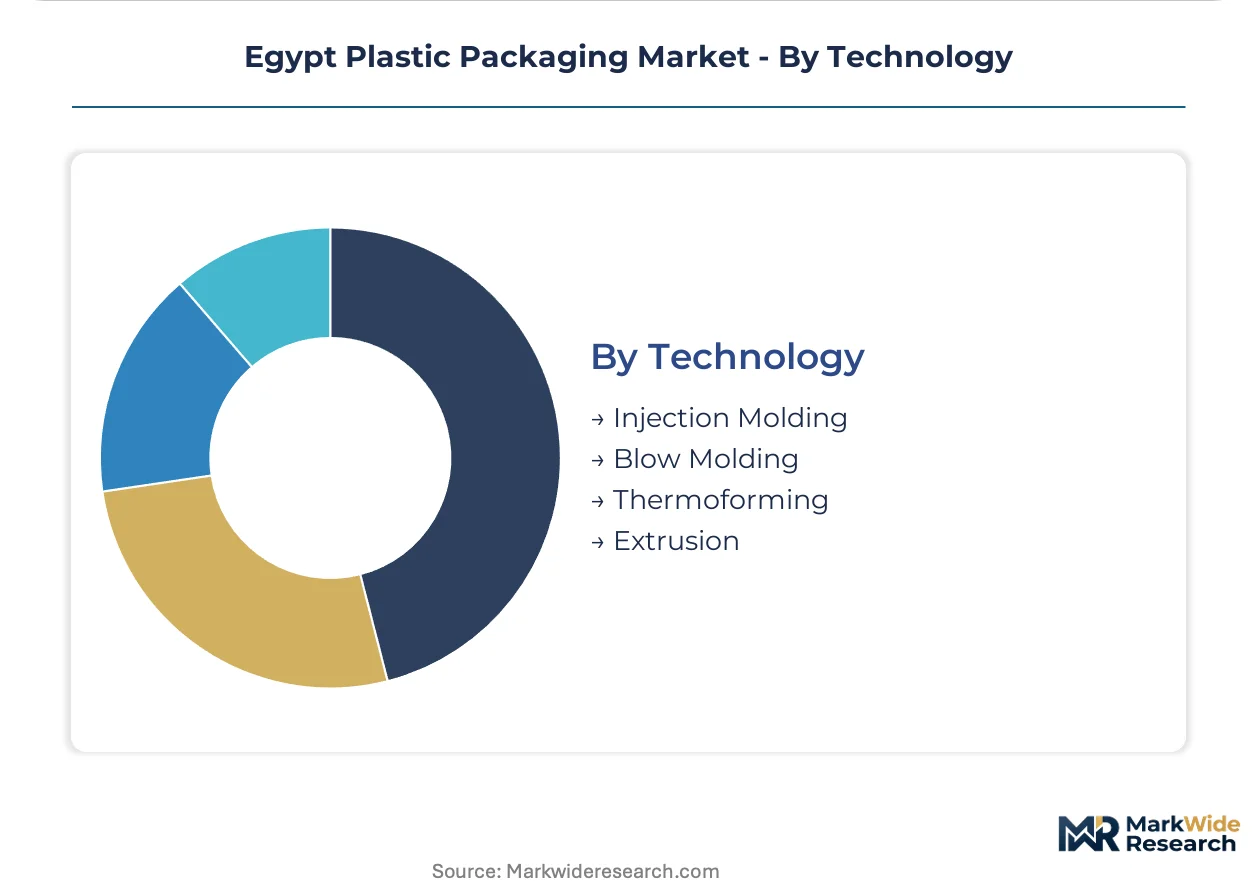
Technology:
Capital equipment requirements and workforce specialization create tiered competitive access.
- Extrusion:Dominates flexible film production through blown and cast film lines. Multi-layer coextrusion expertise concentrates at Amcor's technical center, constraining competitor process optimization.
- Injection Molding:Dimensional precision requirements for healthcare rigid containers and closure thread integrity command equipment investment premiums. Skilled technician scarcity limits mid-cap converter entry.
- Blow Molding:Hollow container formation for bottles and jerrycans serves edible oil and chemical packaging segments with moderate barrier specifications.
- Thermoforming:Sheet-fed forming of polystyrene and polypropylene trays targets foodservice and retail display applications with shorter production runs.
Equipment sophistication peaks in Injection Molding. Capacity expansion is accelerating in Extrusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Cairo absorbs the majority of domestic packaging output while Alexandria and the Delta corridor handle resin import flows. This production-consumption split concentrates converter investment along the Nile industrial belt.
Greater Cairo
Multinational dairy processors in 10th of Ramadan City drive multi-layer flexible film specifications for extended shelf-life products. Egypt's Ministry of Environment enforces Extended Producer Responsibility recycling targets that redirect capital toward certified resin procurement. Obour City industrial zones host consolidated scrap collection networks serving compliance documentation requirements.
Alexandria
Port terminal expansion enables direct polyethylene import bypassing Cairo warehousing for Delta region converters. The Egyptian Organization for Standardization and Quality governs food contact migration limits under harmonized technical regulations. El Amreya industrial cluster concentrates blow molding operations for edible oil and chemical packaging segments.
Suez Canal Corridor
Logistics proximity reduces export lead times for flexible film converters serving European food brand buyers. Draft biodegradable content mandates under national sustainable development strategy review create procurement specification uncertainty. Ismailia industrial zones attract injection molding investment for pharmaceutical rigid container exports.
Damietta
Furniture and consumer goods packaging demand supports thermoformed tray production for retail display applications. Central Bank of Egypt foreign exchange policies influence resin import working capital requirements for small-scale processors. New Damietta Port development targets containerized polymer feedstock direct discharge.
Egypt Plastic Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Egypt's packaging corridor. The market structures around three tiers: multinational converters with global R&D networks, domestic scale manufacturers serving local processors, and specialized printers competing on short-run customization. Strategic moves concentrate on certified supplier master agreements spanning 24-36 month horizons and embedded design engineering teams that displace spot-market resin purchasing.
Within the multinational tier, Amcor Plc anchors premium flexible film specifications through technical center concentration. National Company for Packaging Industries (NatPack S.A.E.) occupies a position among domestic scale manufacturers sustaining rigid container lines. Rotografia Group S.A.E. exemplifies the specialization archetype competing on high-definition label printing for regional personal care brands.
| Leading Market Players |
|---|
| Amcor Plc |
| National Company for Packaging Industries (NatPack S.A.E.) |
| Rotografia Group S.A.E. |
| Taghleef Industries LLC |
| Coveris Flexibles Egypt S.A.E. |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Uflex Limited |
| International Printing & Packaging Materials Co. (IPP) |
| Huhtamaki Oyj |
| Others |
Supply & Pricing Matrix
Captive resin sourcing through backward integration into polyethylene import channels anchors supply position for large converters while compressing spot-market purchasing power for mid-tier competitors. Egypt's Ministry of Environment Extended Producer Responsibility compliance costs feed directly into pricing power stratification, rewarding certified processors with multiyear contract security.
Pricing Analysis
Margin tightening in commodity polyethylene bags traces to resin import dependency and escalating Egyptian Organization for Standardization and Quality certification costs. Three-tier pricing structure across premium certified grades, standard commercial resins, and economy spot-market purchases separates multinational dairy processors from regional edible oil packers. Pricing pressure intensifies in flexible films as downgauging innovations reduce per-unit resin input and compress converter margins. Healthcare rigid container buyers show least price sensitivity due to dimensional precision requirements, while household product segments resist pass-through of compliance-driven cost increases.
Supply Chain Analysis
Regional distribution centers in Greater Cairo's Obour City industrial zones consolidate scrap collection networks for Extended Producer Responsibility documentation. Polyethylene feedstock draws from Saudi Arabia, the United Arab Emirates, and Kuwait petrochemical complexes. Single-source vulnerability concentrates in ethylene vinyl alcohol barrier core imports for multi-layer coextrusion. Distribution runs through Alexandria Port container terminals with direct discharge capabilities bypassing Cairo warehousing for Delta region converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's plastic packaging market functions as a cost-of-compliance story where Ministry of Environment Extended Producer Responsibility frameworks erect barrier-to-entry moats favoring early certification adopters over marginal processors.
For Market Incumbents: Extend certified supplier master agreements spanning 24-36 month horizons to lock in multinational dairy processor specifications before biodegradable mandate uncertainty resolves. Deepen backward integration into Alexandria Port direct import channels to bypass Cairo warehousing costs and compress working capital cycles. Amcor and NatPack S.A.E. anchor positions through embedded design engineering teams that displace spot-market competitors. For New Entrants and Emerging Players: The premium-economy price-point gap in healthcare rigid containers creates entry space for injection molding specialists with EOS certification capacity. Target Damietta thermoformed tray production for furniture and retail display applications where Central Bank of Egypt foreign exchange policies disadvantage resin-import-dependent competitors. Lead with rapid-turnaround label customization services for regional personal care brands underserved by Rotografia Group S.A.E.'s short-run capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational converters seeking Greater Cairo industrial corridor presence for Suez Canal logistics access. Five-to-ten year viability hinges on compliance infrastructure amortization across Extended Producer Responsibility reporting systems and third-party audit networks. Monitor draft biodegradable content mandate amendments as inflection signal for capital allocation priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-layer Coextrusion Capacity Expansion | Enables entry into extended shelf-life dairy specifications previously dominated by Amcor's technical center. |
| Backward Integration into Resin Import Channels | Alexandria Port direct discharge agreements reduce working capital requirements and bypass Cairo warehousing premiums. |
| EOS Certification Laboratory Investment | Local migration testing capacity shortens product launch timelines for pharmaceutical vial and closure systems. |
| Subscription-Based Design Services Launch | Technical consulting contracts embed converters deeper into multinational brand specification processes beyond pure volume agreements. |
| Scrap Collection Network Consolidation | Obour City industrial zone pre-qualified recycler relationships satisfy Ministry of Environment compliance documentation requirements. |
Research Methodology
Multi-period observation of resin import volumes, certification laboratory capacity utilization, and Extended Producer Responsibility compliance filings anchored the trend analysis, supplemented by interviews with plant managers at flexible film converters, procurement leads at multinational dairy processors, distribution channel partners in Alexandria Port logistics, and technical R&D directors at barrier film specialists. Secondary validation drew from Egyptian Organization for Standardization and Quality regulatory filings, Central Bank of Egypt foreign exchange policy circulars, customs and trade data on polyethylene grades, and Suez Canal Authority container throughput statistics. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
The input-output matrix framed demand projections across product type, material specification, end-use sector, and technology platform dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted volume trajectories incorporating downgauging innovation adoption curves, healthcare rigid container precision requirements, and personal care substitution patterns toward glass and metal alternatives. Industry-specific forecast inputs included ethylene vinyl alcohol barrier core availability and skilled extrusion technician supply concentration.
Inputs from Ministry of Environment compliance registries and EOS certification databases were available through the study window; gaps in draft biodegradable mandate amendment timelines introduce uncertainty bands around material procurement specification scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Indonesia Plastic Food Tray Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Plastic Battery Containers Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
Plastic Liners Market