
 South America Polyethylene Terephthalate (PET) Market | 2026-2036
South America Polyethylene Terephthalate (PET) Market Size, Share, and Industry Trends Forecast 2026-2036
South America Polyethylene Terephthalate (PET) Market Insights
Multi-source resin procurement is shifting toward vertically integrated petrochemical complexes across the Andean ridge and Brazilian coast. Alpek leverages captive PTA-PET integration at its Colombia and Brazil sites to lock in feedstock margins. Indorama Ventures anchors regional supply through its scaled recycling and resin operations. DAK Americas competes on bottle-grade specialization for Coca-Cola and PepsiCo bottling networks.
Polyethylene terephthalate is a thermoplastic polyester polymerized from purified terephthalic acid and ethylene glycol, exhibiting clarity, barrier properties, and melt-processability between 250-280°C for container and fiber applications. Blow molding dominates beverage packaging throughput due to its cost efficiency at billion-unit scale, while injection molding sustains higher-margin precision preform production for carbonated soft drinks. Fiber production occupies a mature volume position in Brazilian textile corridors, though food packaging represents the fastest margin expansion as shelf-life extension specifications tighten.
Brazil's ANVISA enforces food-contact migration limits that shape resin purity grades accepted for domestic beverage and food packaging. The EU Green Deal's extraterritorial recycling-content requirements are forcing export-oriented Brazilian converters to certify rPET traceability through EFSA-compliant recycling processes. Stakeholders must monitor how ANVISA harmonization with MERCOSUR technical standards alters cross-border resin qualification costs between Brazil, Argentina, and Uruguay.
Market Dynamics
rPET integration mandates from the EU Green Deal are forcing Brazilian export converters to requalify their entire supply chains, while lightweighting requirements from Coca-Cola and PepsiCo bottlers are accelerating resin specification changes across the continent.
Growth Catalysts
- EU Green Deal extraterritorial requirements:Export-oriented Brazilian converters must certify rPET traceability through EFSA-compliant recycling processes, pulling investment into São Paulo's recycling clusters.
- Beverage bottler lightweighting mandates:Coca-Cola and PepsiCo bottling networks are replacing glass with PET across Brazil and Argentina, concentrating resin demand in the Southeast industrial corridor.
- ANVISA-MERCOSUR harmonization:Brazil's food-contact migration standards are aligning with cross-border technical regulations, reducing resin qualification costs for converters operating in Uruguay and Argentina.
Market Restraints
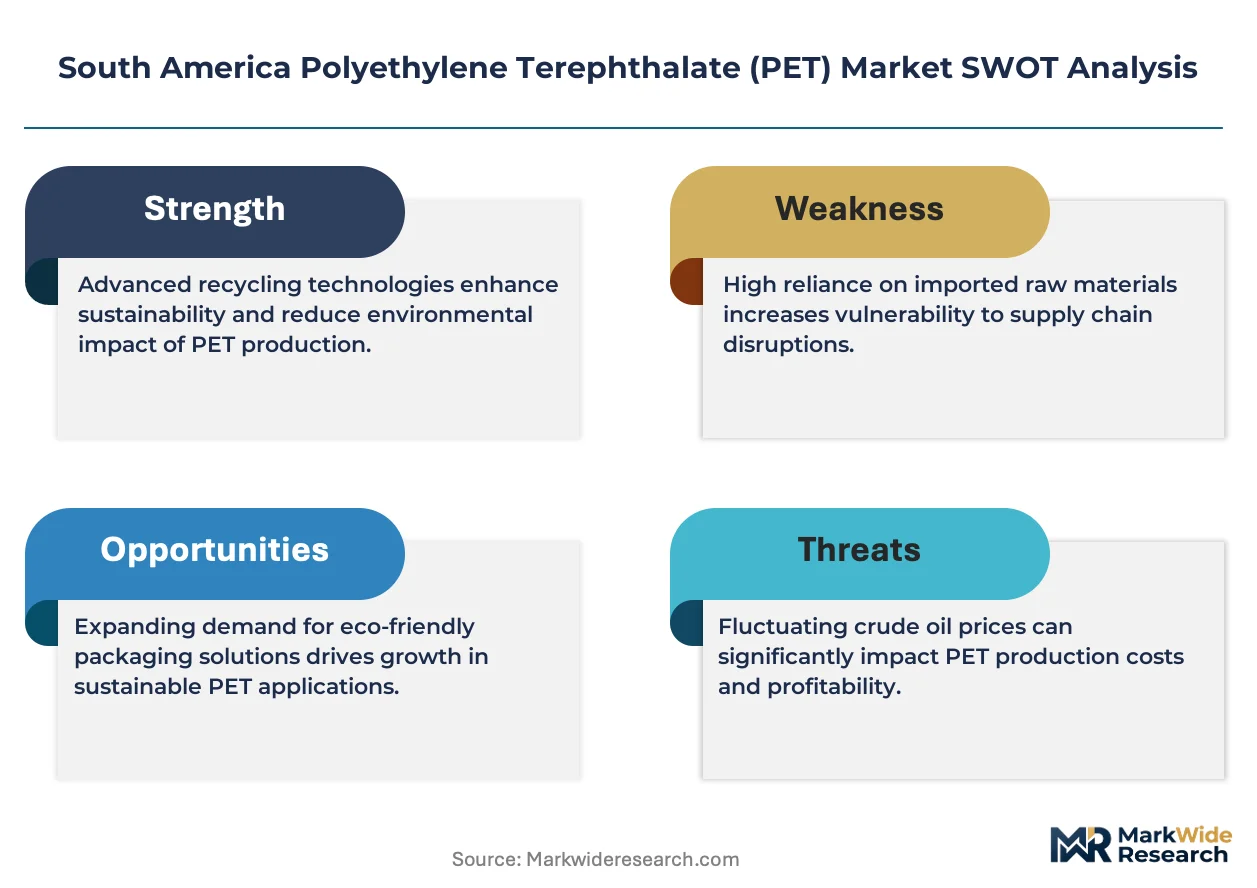
- PTA feedstock cost volatility:Purified terephthalic acid prices swing with paraxylene naphtha spreads, compressing margins for non-integrated PET resin producers.
- Andean supply concentration:Captive PTA-PET integration at Colombian and Brazilian coastal complexes limits third-party resin access for independent converters in Chile and Peru.
- rPET technical limitations:Mechanical recycling degrades polymer chain length, capping food-contact applications below virgin resin performance thresholds.
Strategic Opportunities
- Underpenetrated Peruvian packaging market:Lima's beverage bottlers still rely heavily on glass and aluminum, creating white space for PET preform suppliers with localized blow molding capacity.
- Chemical recycling convergence:Pyrolysis and glycolysis technologies are approaching commercial scale, enabling bottle-to-bottle rPET quality without mechanical degradation limits.
- ANVISA rPET food-contact pathway:Brazil's regulator is developing explicit approval frameworks for chemically recycled content, potentially unlocking premium pricing for certified circular resin.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for rPET-virgin blending and IV stabilization is concentrated among legacy resin producers, constraining independent converter technical capabilities.
- Multi-certification timeline compression:Simultaneous ANVISA domestic approval and EU EFSA export qualification requires parallel testing tracks, extending product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Polyethylene Terephthalate (PET) Market |
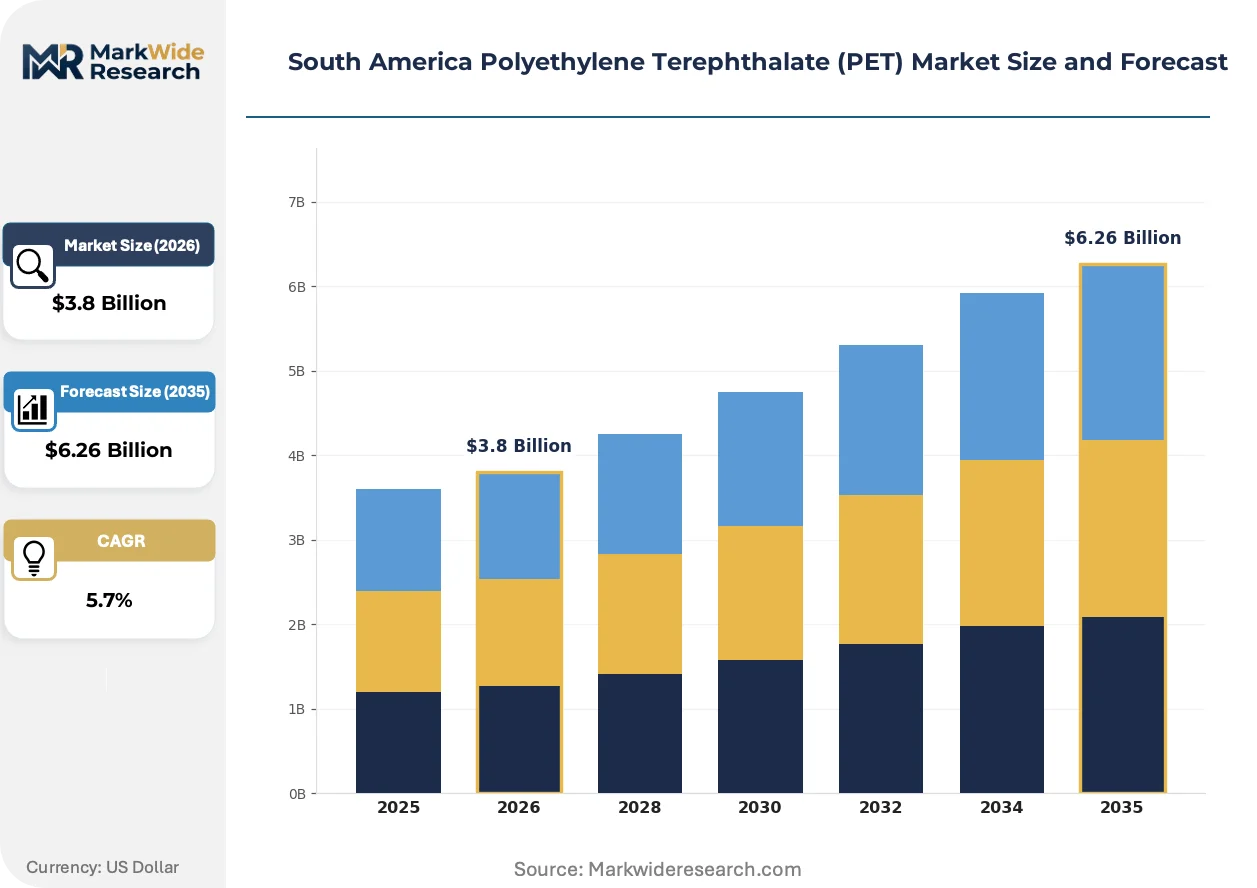
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Extrusion, Blow Molding, Thermoforming Application: Food Packaging, Beverage Bottles, Fiber Production, Container Manufacturing End User: Consumer Goods, Automotive, Textile, Electronics Distribution Channel: Direct Sales, Online Sales, Retail, Wholesale |
| Companies Covered | Alpek, DAK Americas, Indorama Ventures, Maxipet, SABIC, DuPont, Reliance Industries, Far Eastern New Century, Nan Ya Plastics Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Polyethylene Terephthalate (PET) Market Trends and Innovations
Active pharmaceutical and food-contact specifications are tightening across South American resin grades, while mechanical and chemical recycling technologies are converging to address quality degradation barriers that have historically capped circular content ratios.
Advanced rPET decontamination systems using super-cleaning and solid-state polymerization are integrating into São Paulo's recycling infrastructure. Brazilian beverage bottlers with export exposure to EU markets are adopting these systems at pace to meet EFSA traceability requirements. This technology is integrating food-contact rPET into premium bottle applications previously reserved for virgin resin, compressing the quality gap between circular and linear supply chains.
ANVISA is revising its food-contact polymer positive list to explicitly address mechanically and chemically recycled PET, with draft standards circulating for industry comment. The industrial consequence is a bifurcation in converter investment strategies between domestic-only and export-qualified production lines. Brazilian resin producers serving both markets are responding by segregating rPET handling facilities and dual-certifying output streams.
Beverage bottlers are consolidating resin procurement around pre-approved supplier lists with integrated recycling capabilities, displacing spot-market purchasing for commodity grades. This channel consolidation is most visible in Brazil's Southeast industrial corridor, where Coca-Cola FEMSA and Ambev bottlers have narrowed their approved resin sources to vertically integrated PTA-PET producers with captive rPET supply. The shift is compressing margins for independent resin traders and forcing backward integration investments among mid-scale converters.
South America Polyethylene Terephthalate (PET) Market Segmentation
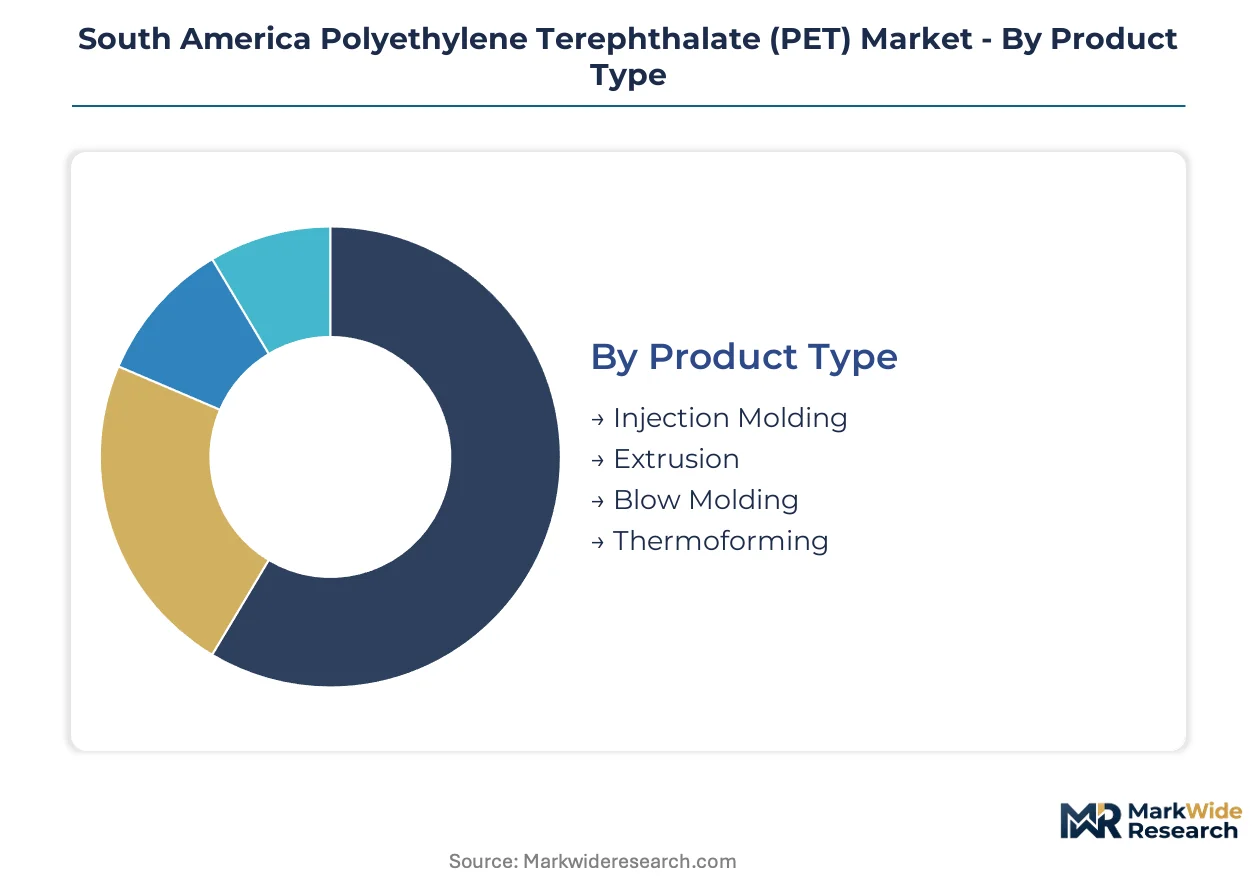
PET resin specifications diverge sharply across South American processing methods, with beverage bottlers and textile manufacturers driving incompatible viscosity and purity requirements. Understanding these segment boundaries reveals where margin compression and premium pricing opportunities concentrate for converters.
Product Type:
Converters select processing technology based on part complexity, production scale, and the trade-off between capital intensity and unit economics.
- Blow Molding:Stretch-blow and injection-blow variants dominate billion-unit beverage production, with IV-stabilized resins processed at 280°C enabling thin-wall carbonated bottle structures. Coca-Cola FEMSA and Ambev bottlers in São Paulo's industrial corridor concentrate demand here, locking in multi-year resin supply contracts to secure lightweighting-compliant specifications.
- Injection Molding:Precision preform production for carbonated soft drinks sustains higher margins through dimensional tolerances and neck finish standardization. Brazilian converters serving PepsiCo networks prioritize this technology for its compatibility with high-speed rotary blow-fill-seal lines.
- Extrusion:Sheet and film extrusion serves thermoformed food trays with amorphous PET grades requiring slower crystallization control.
- Thermoforming:Clamshell packaging and blister packs utilize extruded sheet feedstock, with ANVISA food-contact certification limiting supplier pools for domestic Brazilian converters.
Volume sits with blow molding; growth tilts toward injection molding as preform-to-bottle outsourcing expands.
Application:
End-use specifications fragment the resin market into purity tiers, with food-contact migration limits and mechanical property thresholds creating non-substitutable demand pockets.
- Beverage Bottles:Carbonated soft drink containers require IV 0.80-0.85 dL/g resin with acetaldehyde content below 1 ppm to prevent flavor scalping. Brazil's Southeast corridor concentrates this demand, where rPET integration mandates from EU export requirements are pulling investment into EFSA-compliant super-cleaning infrastructure.
- Food Packaging:Thermoformed trays and barrier films face tightening shelf-life extension specifications, with oxygen transmission rates below 0.1 cc/m²/day becoming standard for protein packaging. ANVISA's draft recycled content framework is unlocking premium pricing for chemically certified circular resin in this segment.
- Fiber Production:Brazilian textile corridors consume textile-grade PET with lower IV requirements for polyester staple and filament spinning.
- Container Manufacturing:Non-food industrial containers operate outside migration-limited certification, accessing broader resin supply pools.
Revenue concentrates in beverage bottles; margin expansion tilts toward food packaging as active and intelligent barrier specifications proliferate.
End User:
Customer technical capabilities determine whether resin procurement flows through spot markets or integrated supply agreements.
- Consumer Goods:Multinational bottlers with dedicated polymer scientists specify custom IV ranges and additive packages, consolidating procurement around vertically integrated PTA-PET producers with captive rPET supply. São Paulo's recycling clusters anchor this demand through EFSA-traceable output streams.
- Textile:Brazilian polyester fiber manufacturers in Santa Catarina and Paraná operate on commodity resin specifications with higher tolerance for mechanical recycling degradation.
- Automotive:Underhood applications and interior trim utilize glass-filled PET compounds with heat deflection temperature above 200°C.
- Electronics:Connector housings and coil bobbins demand flame-retardant grades with UL94 V-0 certification, a specification tier with limited South American compounder capacity.
Procurement scale sits with consumer goods; technical complexity tilts toward electronics as regional compounder capacity expands.
Distribution Channel:
Channel selection reflects buyer scale, certification burden, and the need for technical service support in resin qualification.
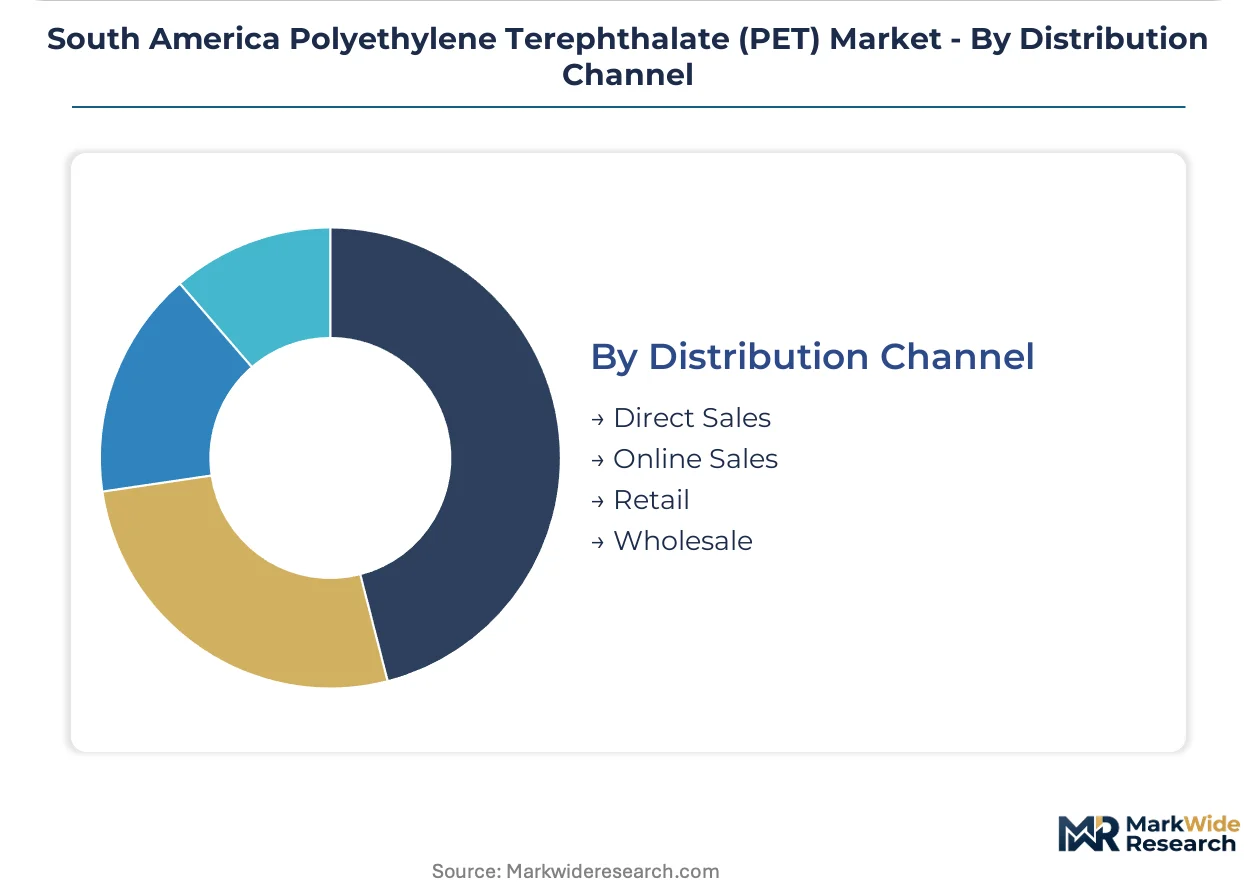
- Direct Sales:Alpek, Indorama Ventures, and DAK Americas maintain dedicated technical service teams for beverage bottlers and food packaging converters, embedding polymer scientists at customer sites to accelerate ANVISA and EU dual-certification timelines. This channel captures premium pricing through specification lock-in.
- Wholesale:Independent distributors serve mid-scale textile and industrial container manufacturers with standard-grade resins, carrying inventory risk in volatile PTA feedstock environments.
- Retail:Small-lot specialty grades and compounded products reach job shops through regional plastics distributors.
- Online Sales:Technical data sheet availability and sample ordering platforms are emerging for standardized commodity grades, though food-contact certification requirements limit adoption.
Revenue concentration sits with direct sales; channel diversification tilts toward wholesale as independent converter technical capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paraxylene feedstock availability along Brazil's Southeast industrial corridor anchors South American PET resin production, with PTA-PET integration concentrating in coastal petrochemical complexes from São Paulo to Rio de Janeiro.
Brazil
Beverage bottlers Coca-Cola FEMSA and Ambev drive resin offtake for lightweight carbonated bottle production. ANVISA enforces food-contact migration limits that shape domestic purity grades while harmonizing with MERCOSUR technical standards. São Paulo's recycling clusters integrate super-cleaning infrastructure to meet EU EFSA traceability requirements for export-oriented converters.
Argentina
PepsiCo bottling networks expand PET substitution for glass containers across Buenos Aires and Córdoba provinces. The national food-contact regulator aligns technical standards with MERCOSUR cross-border frameworks. Rosario's industrial corridor hosts mid-scale converters qualifying resin for both domestic and Brazilian export markets.
Colombia
Captive PTA-PET integration at coastal petrochemical sites supplies Andean beverage and textile markets. The national standards body implements food-contact polymer regulations converging with regional trade bloc requirements. Barranquilla's Caribbean coast complex anchors resin output for northern Andean distribution.
Chile
Santiago-based bottlers source resin through cross-border supply agreements given limited domestic polymer production. The national economic development agency promotes packaging sector investment under circular economy frameworks. Valparaíso's port logistics cluster handles import throughput for Chilean and Bolivian converter demand.
Peru
Lima's beverage bottlers maintain heavy reliance on glass and aluminum packaging, creating undeveloped terrain for PET preform suppliers. The national quality institute drafts food-contact material standards following regional technical cooperation patterns. Callao's port district processes resin imports serving Peruvian and Ecuadorian manufacturing demand.
South America Polyethylene Terephthalate (PET) Market Competitive Landscape
Global majors compete with regional champions across feedstock integration and recycling infrastructure. The market exhibits tiered concentration with vertically integrated PTA-PET producers commanding premium positioning against independent resin traders. Three archetypes dominate: petrochemical conglomerates with captive feedstock supply, specialized bottle-grade resin producers, and integrated recycling-resin operators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure rPET certification pathways for EU export compliance.
Among Mexico-based petrochemical conglomerates, Alpek exemplifies the captive integration archetype through its Colombian and Brazilian coastal operations. Indorama Ventures anchors the recycling-resin integration model with scaled regional recovery and resin production capabilities. DAK Americas occupies a position within the bottle-grade specialization tier, serving multinational bottling network requirements. These three represent distinct strategic postures in a market where technical service embedding and dual-certification capabilities determine procurement relationships.
| Leading Market Players |
|---|
| Alpek |
| DAK Americas |
| Indorama Ventures |
| Maxipet |
| SABIC |
| DuPont |
| Reliance Industries |
| Far Eastern New Century |
| Nan Ya Plastics Corporation |
| Others |
Pricing and Supply Chain Analysis
Chemical recycling technology adoption across São Paulo's recycling clusters is compressing the cost gap between virgin and circular resin grades while concentrating supply among vertically integrated producers with EFSA-compliant super-cleaning infrastructure. This dual shift is reshaping how Brazilian converters negotiate contract terms and allocate procurement spend across domestic and export-qualified supply streams.
Pricing Analysis
Technical service bundling separates contract structures in the South America PET market, with Alpek and Indorama Ventures embedding polymer scientists at customer sites to accelerate dual-certification timelines while independent traders offer unbundled commodity grades without qualification support. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with EU EFSA-traceable rPET commanding significant premiums over domestic-only ANVISA grades. Cost compression in standard-grade spot markets is intensifying because of PTA feedstock volatility and non-integrated producer margin pressure. Mid-scale converters without captive recycling capabilities exhibit the highest price sensitivity, while Coca-Cola FEMSA and Ambev bottlers prioritize specification lock-in over unit cost.
Supply Chain Analysis
Polymer chemist and formulation specialist scarcity across Brazil's Southeast industrial corridor and Colombia's Caribbean coast complexes is constraining independent converter technical capabilities and reinforcing procurement consolidation around legacy resin producers. Supply concentrates in Brazil, Colombia, and Argentina, with captive PTA-PET integration at coastal petrochemical sites anchoring regional output. Raw material flows draw from paraxylene naphtha spreads, purified terephthalic acid intermediates, and post-consumer PET flake streams. Single-source vulnerability around EFSA-compliant super-cleaning infrastructure in São Paulo's recycling clusters presents structural risk. Distribution runs through direct sales channels for beverage bottlers and wholesale networks for textile and industrial container manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America PET market functions as a cost-of-compliance arena where ANVISA's evolving food-contact migration standards and EU EFSA extraterritorial requirements erect substantial barrier-to-entry moats for players with dual-certification capabilities.
For Market Incumbents: Deepen backward integration into captive rPET supply by acquiring or partnering with São Paulo's super-cleaning infrastructure operators, while expanding technical service teams to compress ANVISA-EFSA parallel testing timelines. Threat from emerging chemical recycling entrants with bottle-to-bottle quality capabilities demands preemptive capacity positioning in pyrolysis and glycolysis technologies. For New Entrants and Emerging Players: E-commerce platforms for standardized commodity grades offer a lower-friction entry route than direct technical service competition with integrated majors. White space concentrates in Peru's underpenetrated beverage packaging market and Ecuadorian thermoformed food tray applications where ANVISA-equivalent standards are still developing. A specialty rPET-virgin blending service model targeting mid-scale converters without in-house formulation expertise provides the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by global petrochemical conglomerates seeking South American PTA-PET integration and EFSA-compliant recycling assets. Long-term viability favors vertically integrated producers with captive feedstock supply and dual-certification infrastructure. Watch ANVISA's final rulemaking on chemically recycled PET food-contact approval as the critical inflection signal for premium circular resin pricing realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive rPET Supply | Locks in EFSA-traceable feedstock margins for EU export-qualified converters. |
| Dual-Certification Technical Service Expansion | Compresses ANVISA-EFSA parallel testing timelines by 8-14 months for bottler customers. |
| Chemical Recycling Capacity Buildout | Enables bottle-to-bottle rPET quality without mechanical degradation limits. |
| Peruvian Market Preform Supply Localization | Captures white space as Lima bottlers transition from glass and aluminum. |
| Long-term Supply Agreement with Coca-Cola FEMSA | Secures volume commitment through lightweighting-compliant specification lock-in. |
Research Methodology
Multi-period observation of PTA feedstock spreads, rPET integration rates, and ANVISA regulatory comment periods anchored the trend analysis, supplemented by interviews with plant managers at Brazilian and Colombian petrochemical complexes, procurement leads at beverage bottling networks, distribution channel partners in the Andean ridge, and technical R&D directors at recycling infrastructure operators. Secondary validation drew from customs and trade data, ANVISA draft standard filings, SEC 10-K disclosures from listed petrochemical conglomerates, and MERCOSUR technical regulation harmonization documents. Bottom-up resin consumption estimates by end-use segment were triangulated against top-down production capacity assessments across coastal PTA-PET complexes.
Input-output matrices connecting paraxylene naphtha spreads to resin grade pricing, rPET contamination levels to super-cleaning capital requirements, and certification status to customer procurement behavior structured the analytical framework across the projection horizon. Segmentation dimensions modeled include processing technology, application purity tier, end-user technical capability, and distribution channel. CAGRs were derived from trend extrapolation of resin offtake patterns and capacity expansion announcements, with sensitivity testing around PTA cost volatility and EU Green Deal implementation timing. Forecast inputs incorporated beverage bottler lightweighting mandates and ANVISA-MERCOSUR harmonization progress.
The model holds under stable PTA feedstock availability and continued EU EFSA extraterritorial enforcement; deviation in paraxylene naphtha spread volatility or ANVISA rulemaking delays would shift resin grade pricing and certification timeline assumptions. A small set of triggers—chemical recycling technology cost curves, Peruvian packaging regulatory finalization, and Coca-Cola FEMSA procurement consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
United States Plastic Bottles Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
France Plastic Bottles Market
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
China Plastic Packaging Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
PCR Plastic Packaging Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market