
 Mexico Glass Packaging Market | 2026-2036
Mexico Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Glass Packaging Market Foresight
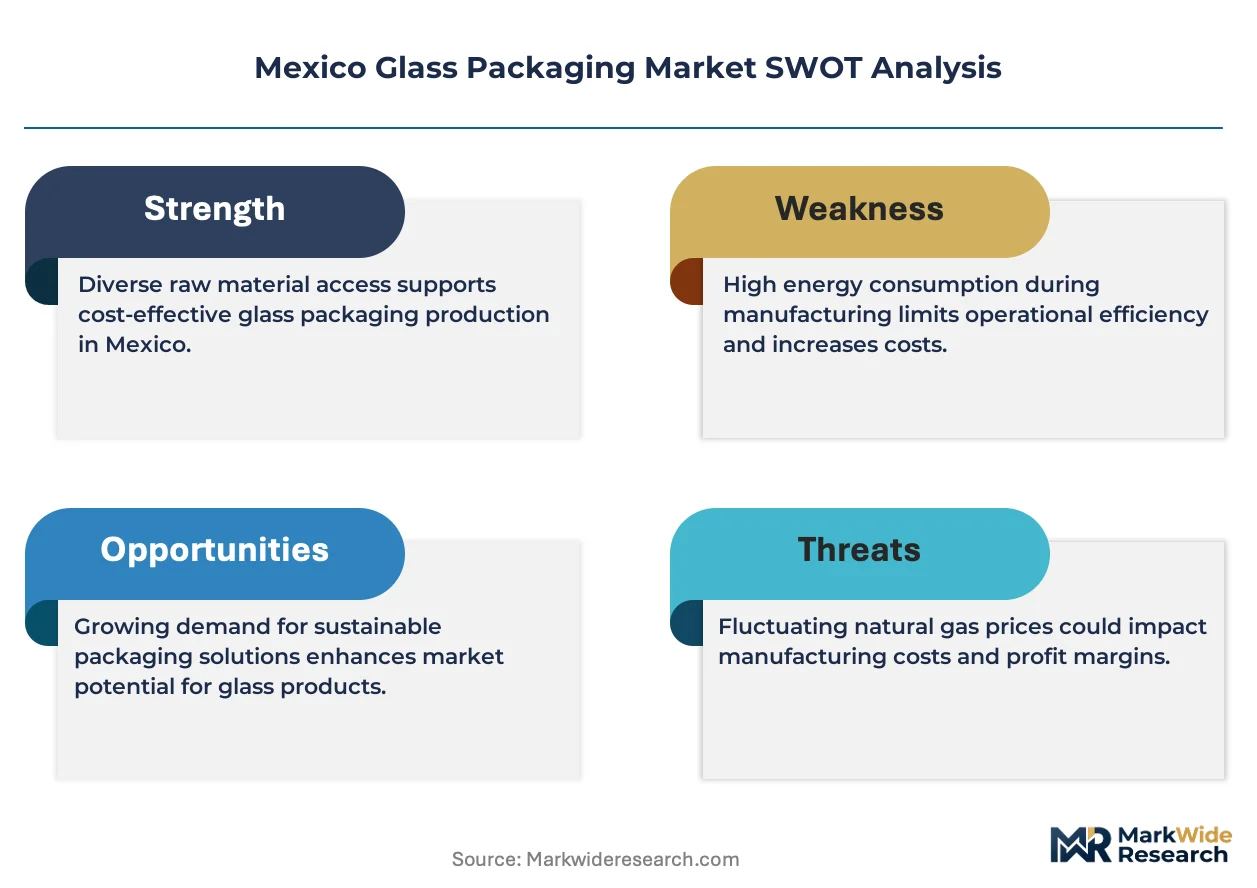
Container-as-a-service leasing models for returnable spirits bottles is recalibrating how distilleries manage packaging procurement. Verallia México S.A. de C.V. anchors its position through captive furnace operations in Guadalajara that supply Grupo Modelo and Casa Cuervo. Vitro S.A.B. de C.V. leverages vertical integration from silica sand mining through decorated finishing to control cost layers across the value chain. O-I Glass, Inc. competes on lightweighting technology that reduces per-unit silica consumption for export-bound beer brands.
Mexico glass packaging comprises silica-soda-lime formulations formed through IS machine blowing or press-and-blow molding, then annealed to relieve thermal stress before surface treatment or decoration. The primary commercial purpose centers on hermetic containment with chemical inertness for oxygen-sensitive consumables. Bottles dominate product type revenue due to spirits and beer volume, while jars capture margin concentration in premium salsas and specialty foods. Recyclable form categories lead volume as Nestlé México and PepsiCo México enforce post-consumer content mandates, though coated glass commands price premiums in cosmetics end uses where UV protection extends shelf stability.
COFEPRIS enforces NOM-141-SCFI/SSA1 on food-contact materials, while SEMARNAT implements Extended Producer Responsibility frameworks that obligate glass recovery quotas. PROFECO monitors labeling accuracy for net content claims on packaged goods. These regulators collectively elevate compliance costs for imported cullet and incentivize domestic closed-loop collection infrastructure. Stakeholders must track how Jalisco's state-level environmental tax on virgin raw material extraction reshapes plant location decisions relative to Guanajuato and Nuevo León alternatives.
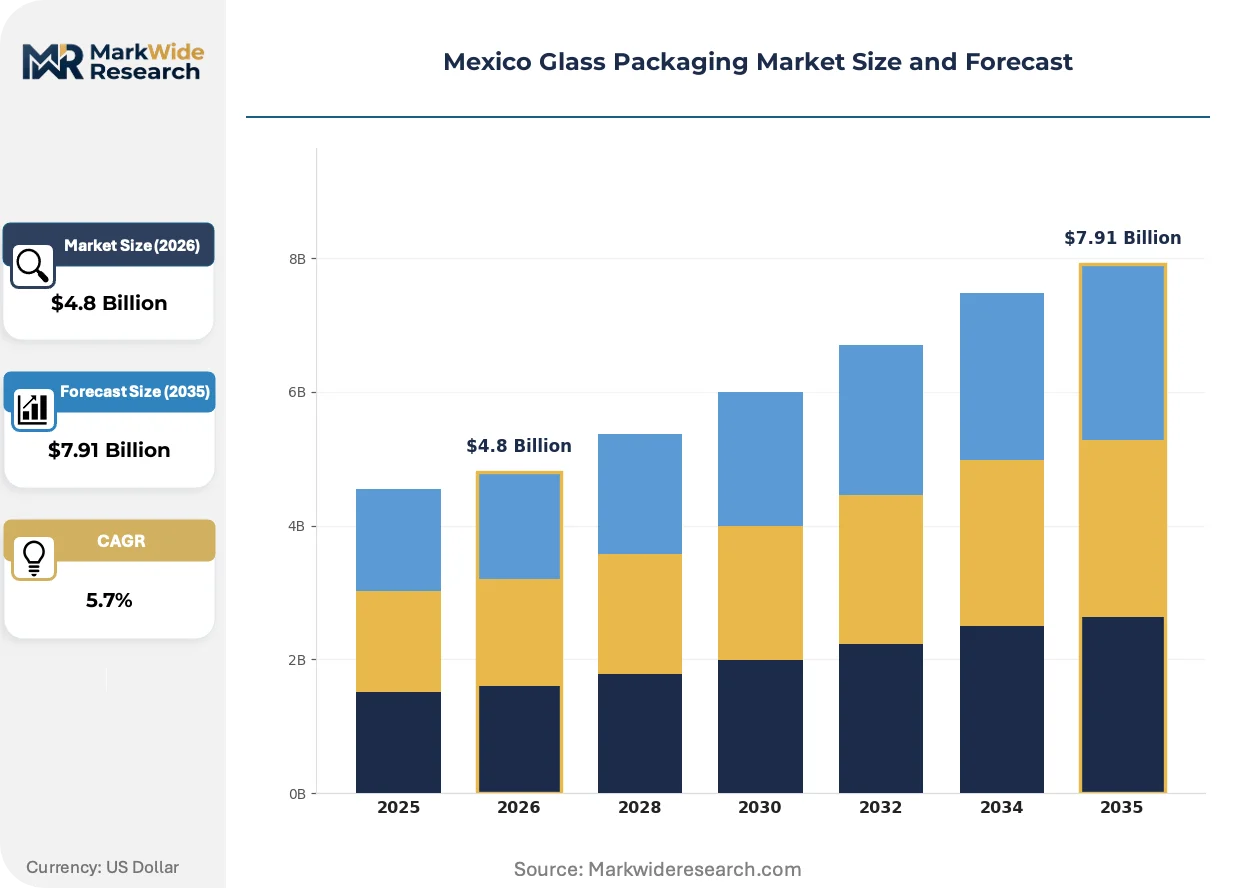
Market Dynamics
Container-as-a-service leasing models for returnable spirits bottles are recalibrating distillery procurement patterns across Jalisco. SEMARNAT's Extended Producer Responsibility frameworks now mandate domestic cullet recovery quotas that reshape furnace feedstock sourcing.
Growth Catalysts
- NOM-141-SCFI/SSA1 compliance:COFEPRIS enforcement on food-contact materials accelerates investment in annealing and surface treatment upgrades across Guadalajara furnace operations.
- Tequila and mezcal export expansion:Premium spirits bottling demand concentrates in Jalisco state where distillery clustering sustains high-volume offtake for decorated glass.
- Lightweighting technology diffusion:IS machine optimization reduces per-unit silica consumption for export-bound beer brands seeking freight cost containment.
Market Restraints
- Natural gas price volatility:Furnace energy inputs account for substantial share of conversion costs, exposing margins to PEMIX-linked tariff fluctuations.
- Quartzite and soda ash supply concentration:Domestic silica sand mining clusters in limited geographies create feedstock security vulnerabilities during transport disruptions.
- Aluminum and PET substitution:Beverage brands in value-tier segments migrate to alternative materials where hermetic performance requirements permit.
Strategic Opportunities
- Guanajuato state expansion:Underdeveloped furnace capacity relative to Jalisco offers greenfield locations with favorable state-level environmental tax treatment on virgin extraction.
- UV-coated cosmetic glass:Premium skincare brands demand oxygen-sensitive containment with photostability that commands price premiums over standard recyclable form categories.
- Closed-loop collection infrastructure:PROFECO-monitored labeling mandates create compliance-driven demand for post-consumer content verification systems.
Industry Challenges
- IS machine technician scarcity:Specialized press-and-blow molding expertise concentrates among retiring workforce cohorts in legacy Guadalajara operations.
- Furnace rebuild capex cycles:Seven-to-ten-year refractory relining timelines demand capital allocation discipline during raw material cost squeezes.
- NOM environmental standard transition:Multi-jurisdictional compliance across SEMARNAT, COFEPRIS and state-level tax regimes extends certification timelines for imported cullet streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Glass Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tumblers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Capacity: Small, Medium, Large, Extra Large Form: Recyclable, Non-Recyclable, Multi-Layer, Coated |
| Companies Covered | Verallia México S.A. de C.V., Ardagh Group S.A., Vitro S.A.B. de C.V., Favisa Glass, Glasser S.A. de C.V., O-I Glass, Inc., Saverglass México, Inova Glass SA DE CV, Gerresheimer Querétaro S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Glass Packaging Market Shifts & Advancements
Digital furnace control systems and surface treatment automation are compressing defect rates while enabling smaller production runs. These advances intersect with regulatory pressure on carbon intensity and buyer demand for packaging differentiation.
Electrical boosting technology in hybrid furnace designs is modularizing how producers balance melting efficiency against grid dependency. Mid-scale spirits bottlers in Nuevo León adopt phased electrode retrofits to reduce natural gas exposure without full rebuilds. This modularizing approach allows capacity scaling in 50-tonne increments rather than conventional 200-tonne furnace commitments.
SEMARNAT's Extended Producer Responsibility framework obligates brand owners to finance post-consumer glass recovery through registered collection schemes. Distilleries now face traceability mandates linking each bottle to verified cullet reprocessing volumes. Premium tequila exporters absorb compliance costs through packaging line item surcharges passed to international distributors.
Distillery procurement teams consolidate supplier relationships around furnace-captive partners offering decoration and logistics bundling. Smaller mezcal producers in Oaxaca shift from spot market bottle purchasing to multi-year returnable container leases with Jalisco-based lessors. This concentration pattern accelerates as freight cost volatility makes distant single-source supply uneconomical for craft-scale volumes.
Mexico Glass Packaging Market Segmentation
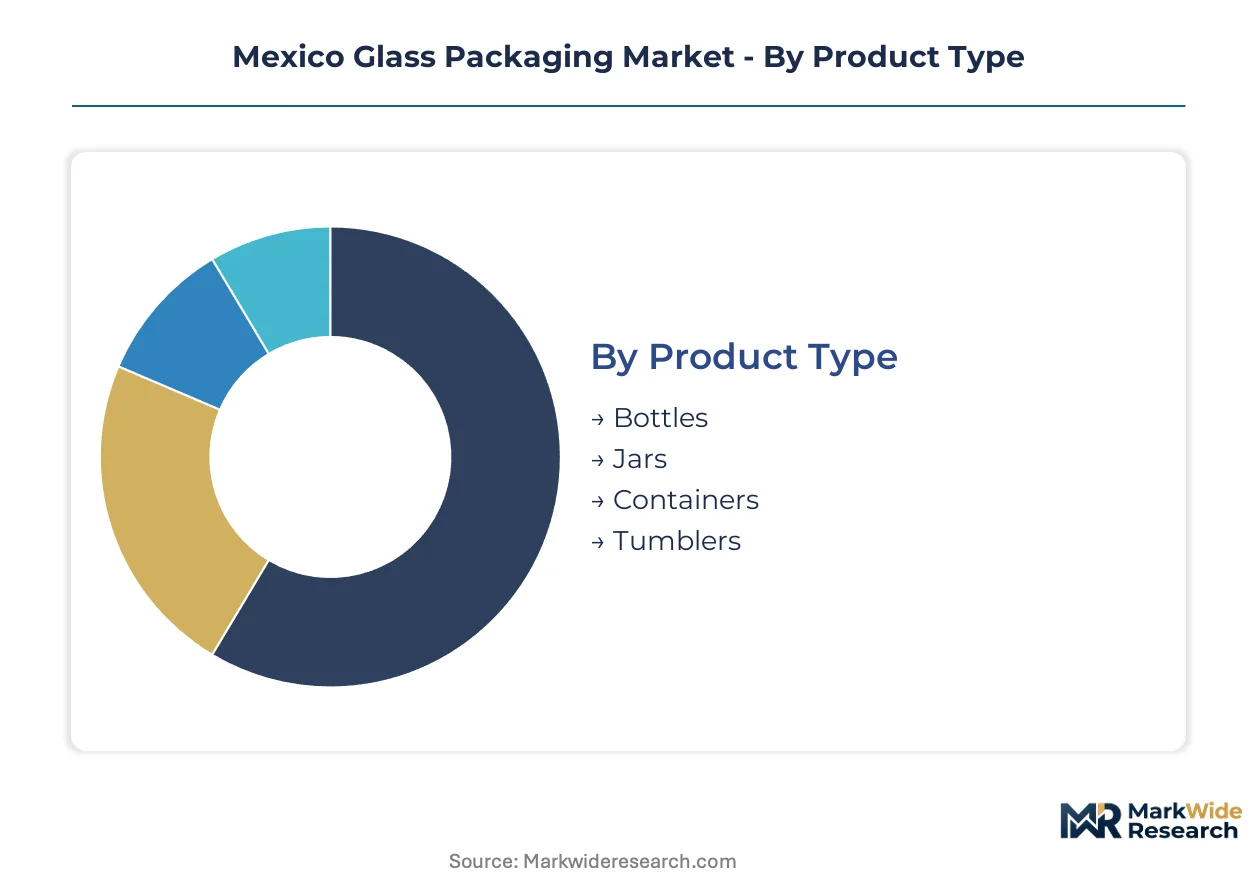
Segmentation in Mexico glass packaging exposes how COFEPRIS certification burdens and SEMARNAT recovery mandates concentrate margin capture across distinct product tiers. Each dimension reveals divergent compliance costs and furnace feedstock requirements that reshape supplier positioning.
Product Type:
COFEPRIS NOM-141-SCFI/SSA1 food-contact certification applies uniformly across all product types, though spirits bottles demand additional annealing documentation for thermal stress relief.
- Bottles:Silica-soda-lime formulations formed through IS machine blowing or press-and-blow molding dominate tequila and mezcal spirits packaging. Distillery clustering in Jalisco sustains high-volume offtake for decorated glass with hermetic sealing specifications.
- Jars:Wide-mouth press-and-blow containers capture premium salsas and specialty foods where oxygen sensitivity meets shelf visibility requirements. Nestlé México and PepsiCo México enforce post-consumer content mandates that elevate recyclable form specifications.
- Containers:Rectangular and cylindrical storage formats serve bulk food service and institutional procurement with standardized neck finishes.
- Tumblers:Drinking glasses for hospitality and retail channels carry lower certification burdens but face aluminum and PET substitution in value-tier segments.
Bottles sits at the top of the volume ranking, with Jars climbing the fastest.
End User:
Cost tier stratification separates premium spirits exporters absorbing compliance surcharges from value-tier beverage brands migrating to alternative materials.
- Food & Beverage:Beer and spirits producers account for dominant furnace throughput, with Grupo Modelo and Casa Cuervo anchoring Guadalajara captive supply arrangements. Lightweighting technology diffusion targets export-bound freight cost containment.
- Pharmaceuticals:Amber and flint glass vials and bottles require COFEPRIS pharmaceutical-grade certification with enhanced chemical inertness documentation for oxygen-sensitive drug stability.
- Cosmetics:UV-coated glass commands price premiums in premium skincare where photostability extends shelf stability beyond standard recyclable formulations.
- Household Products:Standard flint containers for cleaning agents and industrial chemicals carry lower margin profiles but steady volume through retail distribution.
Food & Beverage holds the dominant volume position, while Cosmetics gains share fastest on premium pricing power.
Capacity:
Volume scale determines furnace batch economics and decoration line configuration, with mid-scale producers adopting modular electrical boosting retrofits.
- Small:Sub-200ml formats for spirits samples and pharmaceutical unit doses require precision molding with higher per-unit defect sensitivity.
- Medium:200-750ml standard spirits and wine bottles constitute the core furnace output optimized for Jalisco distillery procurement patterns.
- Large:750ml-1.5L family-size containers for juices and bulk food service run on dedicated IS machine lines with reduced changeover frequency.
- Extra Large:Above-1.5L industrial and institutional formats concentrate in Guanajuato greenfield locations with favorable state-level environmental tax treatment.
Medium capacity commands the highest furnace allocation, with Extra Large expanding most quickly on Guanajuato capacity additions.
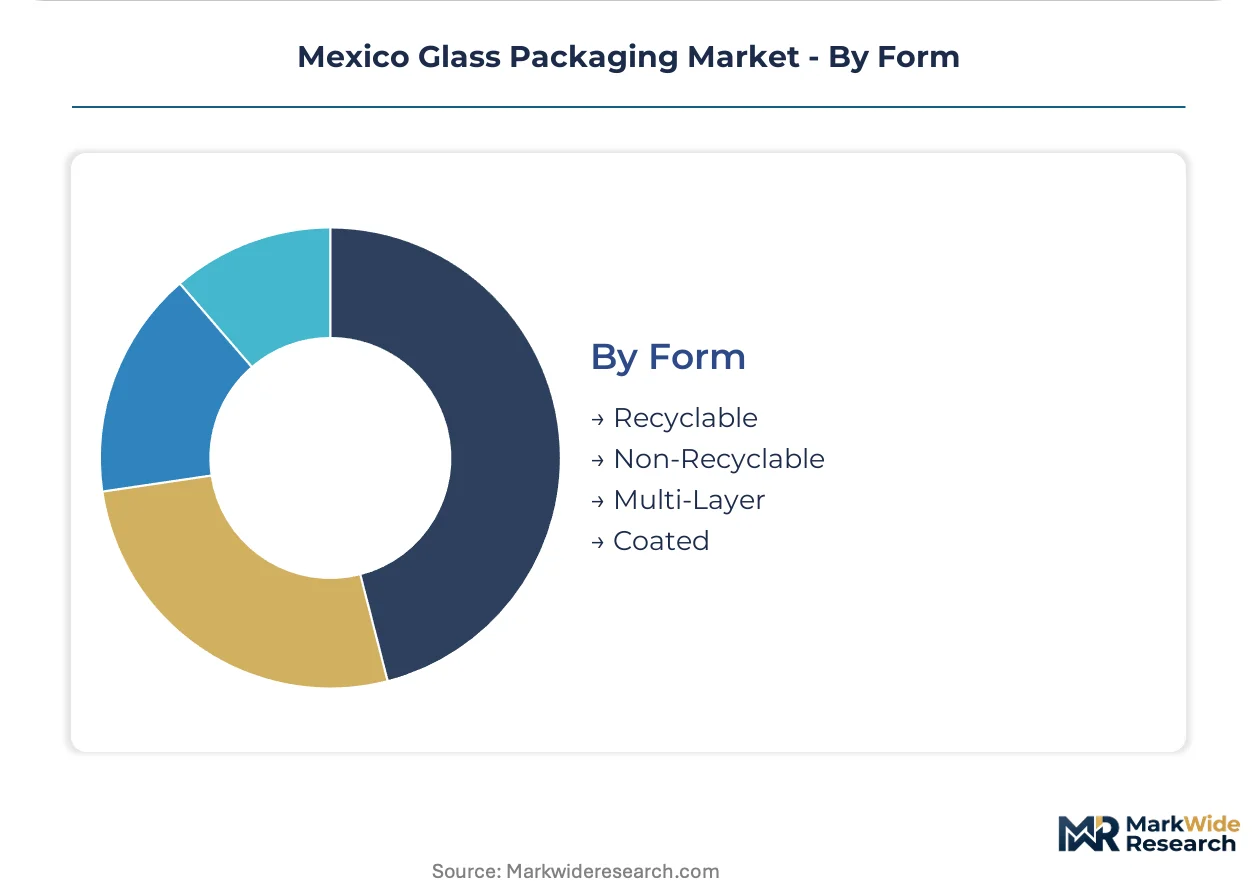
Form:
Margin structure separates standard recyclable forms from coated premium variants, with SEMARNAT traceability mandates linking each unit to verified cullet reprocessing.
- Recyclable:Standard flint and amber glass dominates volume as brand owners finance post-consumer recovery through registered collection schemes. PROFECO-monitored labeling mandates drive compliance-driven demand for content verification systems.
- Non-Recyclable:Ceramic-coated and metallized decorative finishes for gift and promotional packaging carry higher disposal costs and limited cullet value.
- Multi-Layer:Composite structures with internal barrier coatings target oxygen-sensitive pharmaceuticals and premium cosmetics where hermetic performance exceeds single-layer capabilities.
- Coated:UV-blocking and scratch-resistant surface treatments command price premiums in export cosmetics and high-end spirits where shelf differentiation justifies material cost elevation.
Recyclable form leads absolute volume, with Coated glass showing the steepest expansion trajectory on premium end-use adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico outpaces Brazil in spirits-driven glass demand while both trail the United States in absolute pharmaceutical packaging volume. Regional furnace capacity clusters along specific transport corridors and state-level regulatory regimes.
Jalisco
Tequila and mezcal distillery clustering sustains the highest per-capita bottle consumption in Mexico. SEMARNAT's Extended Producer Responsibility frameworks mandate traceable cullet recovery for every exported spirits container. Guadalajara's captive furnace operations supply Grupo Modelo and Casa Cuervo with decorated glass featuring hermetic sealing specifications.
Nuevo León
Mid-scale spirits bottlers adopt modular electrical boosting retrofits to reduce natural gas exposure without full furnace rebuilds. State-level environmental tax treatment favors phased capacity additions in 50-tonne increments rather than conventional 200-tonne commitments. Monterrey's industrial corridor attracts glass distributors serving northern beverage markets.
Guanajuato
Greenfield furnace locations offer favorable state-level environmental tax treatment on virgin raw material extraction relative to Jalisco. Extra-large container formats for bulk food service concentrate in underdeveloped capacity zones. León's logistics connectivity supports distribution to central Mexico retail channels.
Mexico City Metro
Cosmetics and pharmaceutical end-users demand UV-coated glass with photostability specifications that command price premiums. COFEPRIS pharmaceutical-grade certification requirements concentrate quality-sensitive procurement in the capital region. Toluca's manufacturing belt hosts secondary decoration facilities serving premium skincare brands.
Northern Border States
Export-bound beer brands prioritize lightweighting technology to contain cross-border freight costs. PEMIX-linked natural gas tariff fluctuations expose furnace margins in Baja California and Chihuahua. Tijuana and Ciudad Juárez assembly plants supply United States beverage distributors with reduced per-unit silica consumption.
Mexico Glass Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with spirits bottling favoring captive furnace relationships while pharmaceutical procurement tolerates multi-source supply. The vendor base concentrates around three operational archetypes: multinational furnace operators with decoration bundling, domestic silica-to-finish integrated producers, and regional specialists in premium coated formats. Consolidation pressure intensifies as freight cost volatility makes distant single-source supply uneconomical for craft-scale volumes. Competitive moves center on capacity expansion in Guanajuato greenfield sites and strategic partnerships linking collection infrastructure to SEMARNAT compliance verification.
Among Mexico-based integrated producers, Verallia México S.A. de C.V. and Vitro S.A.B. de C.V. exemplify the furnace-captive archetype controlling cost layers from raw material through decorated finishing. O-I Glass, Inc. occupies a position representing multinational lightweighting technology diffusion for export-bound brands. These three anchors illustrate how geographic concentration in Jalisco and Guanajuato shapes supplier procurement consolidation around logistics-bundled relationships.
| Leading Market Players |
|---|
| Verallia México S.A. de C.V. |
| Ardagh Group S.A. |
| Vitro S.A.B. de C.V. |
| Favisa Glass |
| Glasser S.A. de C.V. |
| O-I Glass, Inc. |
| Saverglass México |
| Inova Glass SA DE CV |
| Gerresheimer Querétaro S.A. |
| Others |
Supply & Pricing Matrix
SEMARNAT's Extended Producer Responsibility framework gates qualified supply access and premium-tier pricing power for Mexico glass packaging producers. Compliance-driven cullet recovery mandates concentrate furnace feedstock sourcing among verified domestic collectors, while non-compliant imports face certification delays that push buyers toward premium-priced domestic supply.
Pricing Analysis
Capacity additions in Guanajuato are reshaping price floors for standard recyclable glass formats. Three-tier pricing structure across premium, standard, and economy levels separates UV-coated cosmetic glass from standard flint containers from undecorated commodity bottles. Price differentiation hinges on COFEPRIS certification grade and volume scale, with Jalisco distillery clustering enabling freight-cost absorption for bulk offtake. Cost compression in economy-tier beer bottles is intensifying because aluminum substitution campaigns target value-conscious brand owners. Small-scale mezcal producers in Oaxaca demonstrate highest price sensitivity, while premium tequila exporters absorb compliance surcharges with minimal volume elasticity.
Supply Chain Analysis
Silica sand supply rests on domestic mining clusters in Jalisco, Guanajuato, and Nuevo León with limited geographic diversification. Soda ash draws from United States and Mexican synthetic production, while natural gas feeds from PEMIX-linked distribution networks. Single-source vulnerability concentrates in quartzite feedstock transport corridors subject to seasonal disruption. Distribution runs through furnace-captive partnerships linking Guadalajara decoration facilities to distillery procurement teams, with secondary wholesale channels serving craft-scale bottlers in Oaxaca and northern border states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico glass packaging represents a late-cycle quality story as spirits export demand shifts toward decorated, traceable containers with verified post-consumer content. Premium specification requirements now dominate procurement criteria for tequila and mezcal brands targeting United States and European markets.
For Market Incumbents: To counter aluminum and PET substitution in value-tier beer segments, Verallia México and Vitro S.A.B. de C.V. should accelerate lightweighting technology deployment through IS machine optimization. Furnace rebuild cycles present consolidation leverage—acquiring distressed mid-scale assets in Nuevo León extends captive supply relationships without greenfield capex exposure. For New Entrants and Emerging Players: Direct-to-distillery digital procurement platforms offer white-space entry around SEMARNAT traceability compliance. Target Oaxaca mezcal cooperatives underserved by Jalisco-based logistics networks with container-as-a-service leasing models bundling decoration and recovery verification. Specialty UV-coated cosmetic glass for Mexico City Metro skincare brands presents the most penetrable premium segment with lower incumbent furnace dedication. For Investors and Strategic Acquirers: Roll-up economics work for regional decoration specialists because SEMARNAT compliance verification creates scalable infrastructure moats. Five-to-ten year viability hinges on electrical boosting technology adoption rates displacing natural gas exposure. Watch Jalisco state environmental tax escalation as the inflection signal for Guanajuato capacity migration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Mining | Vitro S.A.B. de C.V. controls feedstock security from sand extraction through furnace melting. |
| Electrical Boosting Retrofit Programs | Mid-scale Nuevo León producers reduce PEMIX-linked gas exposure through modular electrode installation. |
| Closed-Loop Collection Infrastructure | PROFECO-monitored labeling mandates create compliance-driven demand for verified cullet reprocessing systems. |
| UV-Coating Capability Expansion | Premium skincare brands in Toluca manufacturing belt demand photostability specifications commanding price premiums. |
| Guanajuato Greenfield Furnace Development | Favorable state-level environmental tax treatment attracts capacity migration from Jalisco extraction zones. |
Research Methodology
Coverage spans Jalisco, Nuevo León, Guanajuato, and Mexico City Metro, with primary inputs from each region's furnace operators and distillery procurement teams. The analysis combines interviews with plant managers, technical R&D directors, and COFEPRIS regulatory affairs leads with secondary validation from SEMARNAT enforcement bulletins, customs trade records, and SEC filings of multinational parent companies. Bottom-up furnace capacity modeling triangulates against top-down spirits export volume projections.
Segment-level granularity applies product type, end user, capacity tier, and form category dimensions across the projection horizon. CAGRs derive from IS machine throughput optimization curves and distillery clustering density indices. The analytical framework incorporates natural gas tariff elasticity, electrical boosting adoption scenarios, and aluminum substitution elasticity in value-tier beer packaging.
The model assumes a particular technology adoption path; alternative pathways for hybrid furnace electrical boosting would alter the outlook if grid reliability constraints accelerate faster than anticipated. Forecasts reflect documented assumptions around SEMARNAT enforcement intensity and Jalisco state tax regime stability. A small set of triggers—PEMIX tariff spikes, COFEPRIS certification backlog expansion, and Oaxaca mezcal export quota shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Congo Container Glass Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Panama Container Glass Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Denmark Container Glass Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
Mason Jars Market
Glass Packaging
Global Glass Bottles and Containers Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Glass Veil Market
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
United States Container Glass Market