
 PET Clamshell Market | 2026-2036
PET Clamshell Market Size, Share, and Industry Trends Forecast 2026-2036
PET Clamshell Market Analytics
The fresh food retail sector is pivoting toward PET clamshell formats as grocers prioritize shelf visibility and waste reduction in produce departments. Lacerta Group leverages its East Coast manufacturing footprint to supply major supermarket chains with custom thermoformed designs. Pactiv Evergreen anchors the North American market through its integrated resin-to-package operations and broad foodservice distribution network. Amcor competes globally with specialized barrier-enhanced clamshells that extend produce shelf life.
PET clamshells are thermoformed containers manufactured from polyethylene terephthalate resin, typically with wall thicknesses ranging from 0.010 to 0.030 inches, designed to provide transparent product visibility while protecting contents from mechanical damage and environmental exposure. The manufacturing process involves heating PET sheet to its glass transition temperature, then vacuum-forming or pressure-forming the material over a mold to create hinged or separate-lid configurations. Tray formats dominate unit volume in food packaging applications where standardized produce weights require consistent cavity dimensions. RPET material grades are gaining structural share as retailers impose minimum recycled content thresholds on suppliers. Multi-compartment packaging types command margin premiums in prepared meal and snack applications where portion separation enhances consumer convenience.
FDA food contact regulations govern resin purity and additive migration limits for PET clamshells sold into U.S. food applications, while EPA guidelines influence recycling stream contamination standards that affect post-consumer feedstock availability. The EU Green Deal and associated packaging waste directives are tightening recycled content mandates for imported packaging materials, altering sourcing strategies for multinational suppliers. California's SB 54 extended producer responsibility framework and similar state-level legislation are forcing domestic manufacturers to redesign for recyclability and fund collection infrastructure. Stakeholders must monitor evolving mechanical recycling capacity and chemical recycling scale-up timelines to secure compliant feedstock positions.
Market Dynamics
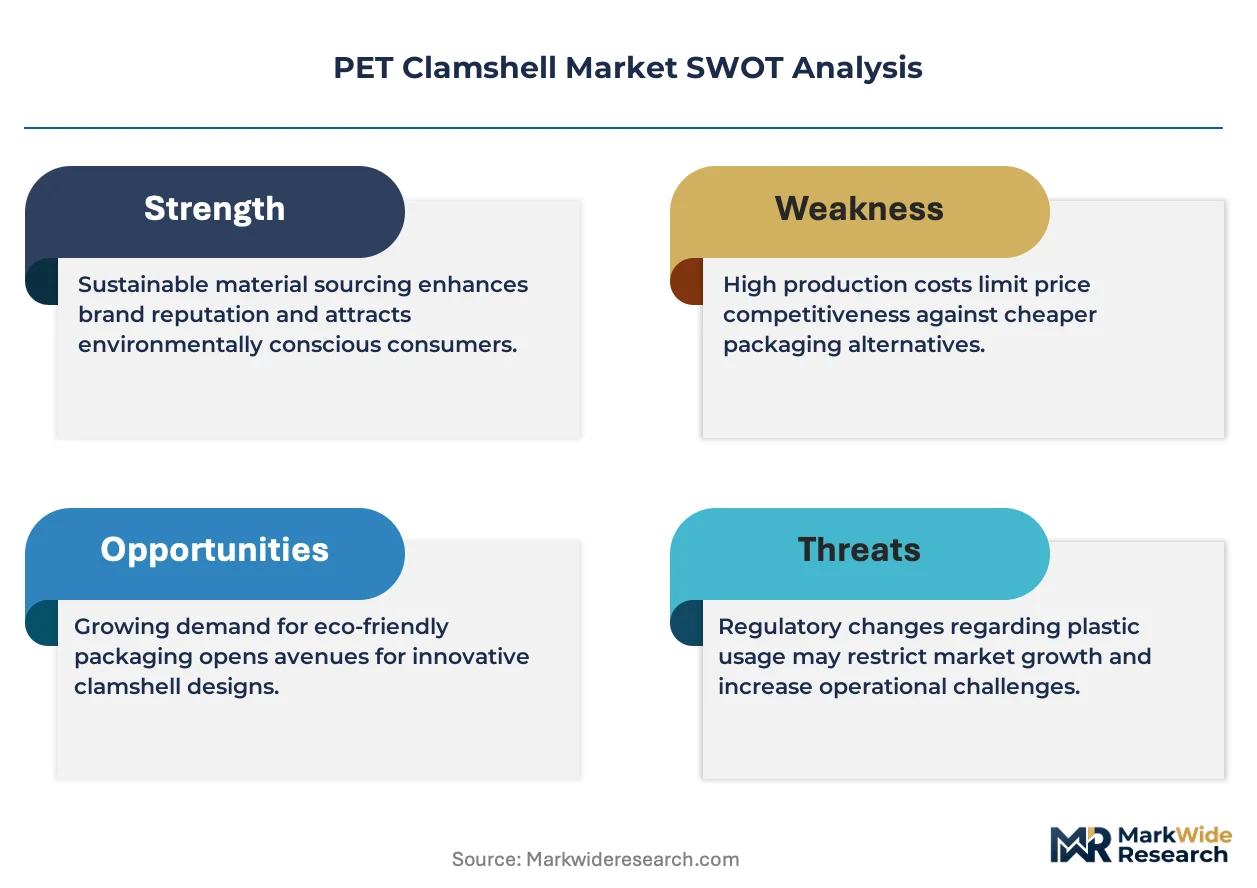
Extended producer responsibility frameworks in California and New York are forcing PET clamshell manufacturers to redesign for recyclability while funding collection infrastructure, compressing margins and accelerating consolidation among mid-tier thermoformers.
Growth Catalysts
- California SB 54 mandates:Minimum recycled content thresholds for food-contact packaging are pulling RPET demand forward and rewarding early movers with compliant feedstock positions.
- E-commerce grocery platforms:Fresh produce delivery services in Germany and China specify clamshell formats for damage reduction during last-mile handling.
- Thermoforming automation:Servo-driven pressure-forming lines cut cycle times and enable thinner-gauge designs without sacrificing structural integrity.
Market Restraints
- RPET feedstock scarcity:Mechanical recycling capacity lags demand growth in the United States, creating spot-price volatility for post-consumer flake.
- Resin import concentration:Virgin PET pellet supply clusters with Asian producers, exposing converters to freight cost swings and currency risk.
- Polypropylene substitution:PP tubs with integrated lids compete in berry and cut-vegetable segments where microwaveability matters.
Strategic Opportunities
- India organized retail expansion:Reliance Fresh and BigBasket are standardizing clamshell formats for private-label produce, creating first-mover advantages for converters with local tooling.
- Chemical recycling scale-up:Pyrolysis and glycolysis projects in the Netherlands and Texas promise food-grade RPET from mixed-waste streams beyond mechanical limits.
- Prepared meal kits:Multi-compartment designs with tamper-evident features capture margin premiums in subscription foodservice channels.
Industry Challenges
- Tooling lead times:Custom thermoform mold fabrication stretches 14-20 weeks, constraining speed-to-market for seasonal produce programs.
- FDA migration testing:Additive reformulations for recycled content trigger lengthy extraction studies, delaying product launches by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Clamshell Market |
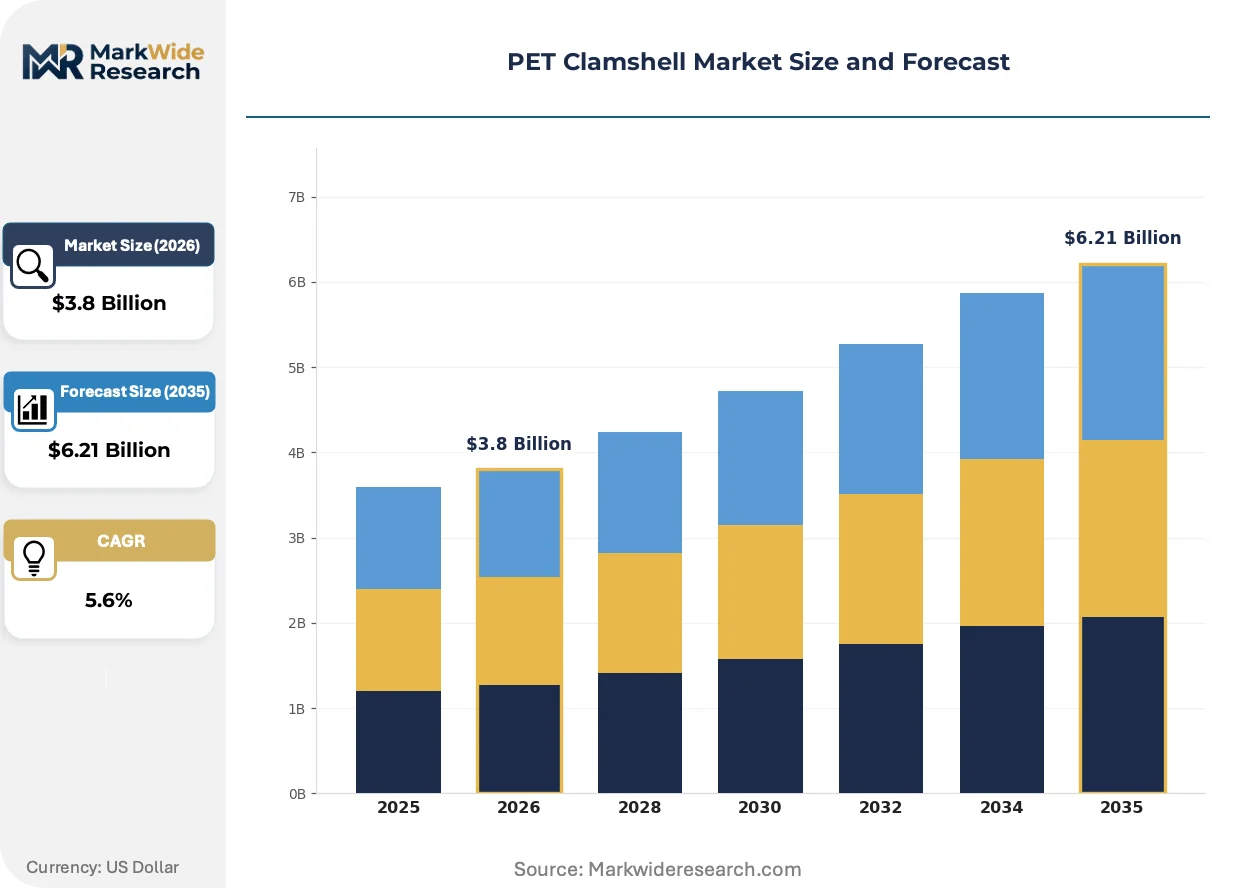
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tray, Box, Container, Insert End User: Food Packaging, Consumer Electronics, Retail Products, Medical Supplies Material: RPET, Virgin PET, Biodegradable PET, Recyclable PET Packaging Type: Single Compartment, Multi-Compartment, With Lid, Without Lid |
| Companies Covered | Lacerta Group, Pactiv Evergreen, Placon, Novolex Holdings, Amcor, VisiPak, Display Pack, EasyPak, Dordan Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Clamshell Market Evolving Landscape
Digital printing and smart packaging integrations are reshaping how brand owners communicate provenance and freshness, while regulatory pressure on recyclability accelerates material science investment.
Digital print-on-demand for clamshell lidding films is decentralizing short-run customization for regional produce brands. Berry packers in the Pacific Northwest and Veneto region adopt inkjet-decorated top webs to swap SKUs without plate changes. This compresses minimum order quantities and enables hyper-local marketing campaigns previously uneconomical at thermoforming volumes.
EU Green Deal packaging waste directives are tightening recycled content mandates for imported materials. Multinational suppliers must certify post-consumer percentages through mass-balance accounting or face market exclusion. German retailers are demanding 50% RPET minimums by 2025, forcing Asian exporters to reconfigure resin sourcing or cede shelf space.
Buyers are consolidating supplier relationships around full-service packaging partners. Mid-size supermarket chains in the United States now award three-year produce packaging contracts to single vendors managing design, tooling, and logistics. This displaces fragmented procurement across regional thermoformers and rewards converters with in-house sheet extrusion and distribution networks.
PET Clamshell Market Segmentation
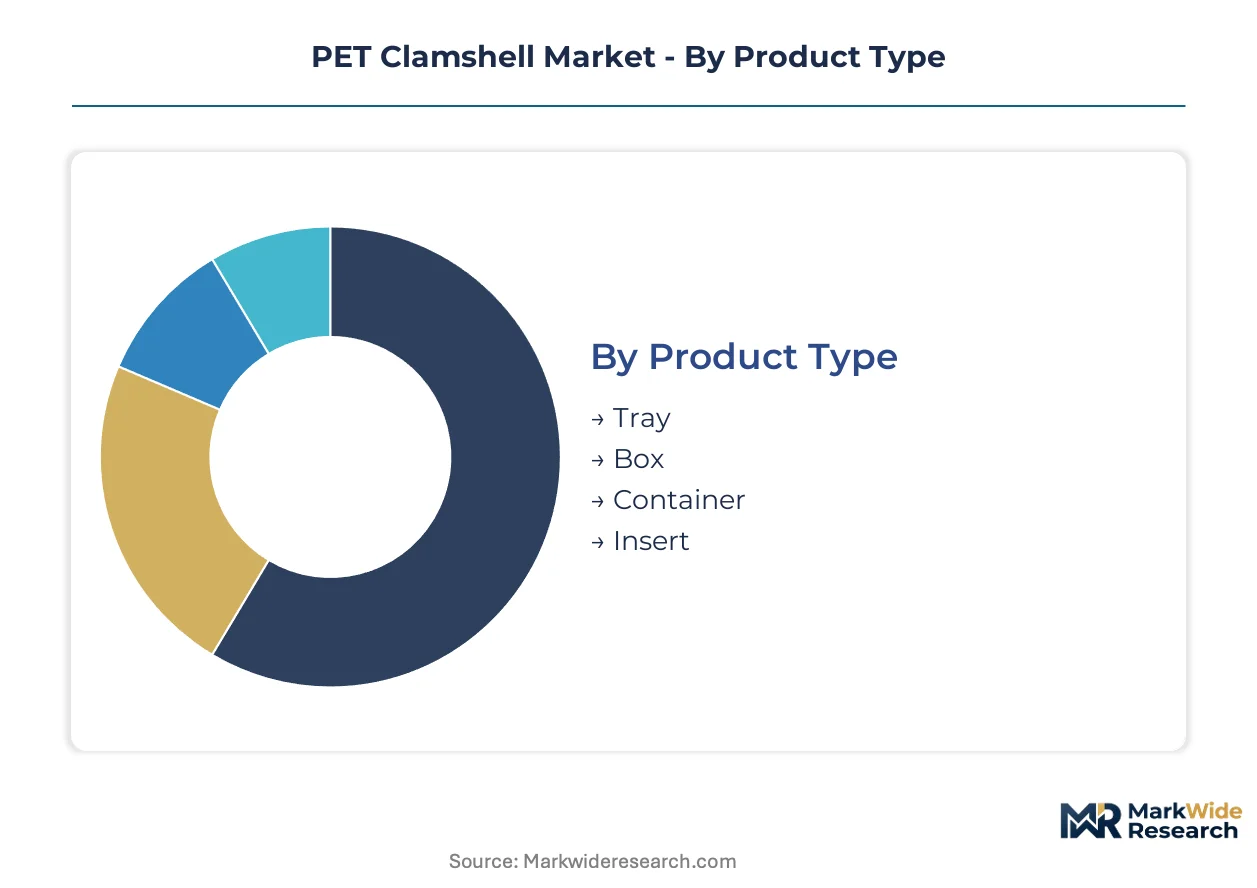
PET clamshell demand fragments across functional requirements that trade off visibility, protection, and sustainability credentials. Converters must align tooling investments with the specific performance thresholds each segment demands.
Product Type:
Tray formats dominate unit economics through standardized cavity dimensions, while box and container variants capture premium positioning through customization.
- Tray:Vacuum-formed designs with 0.010-0.020 inch wall thickness handle standardized produce weights across United States supermarket chains. Reliance Fresh in India and German discounters specify tray formats for automated filling lines.
- Box:Pressure-formed corners and reinforced edges protect consumer electronics during e-commerce last-mile handling. Demand concentrates in China where Shenzhen-based electronics exporters specify anti-static grades.
- Container:Deep-draw designs with integrated stacking features serve prepared meal kits and medical supply kits requiring sterility maintenance.
- Insert:Precision-molded cavities cradle fragile retail products during display and transport.
Mature deployment sits with Tray formats. Newer deployment is concentrated in Container configurations for subscription foodservice channels.
End User:
Application requirements split between regulated food contact and industrial protection use cases with divergent certification burdens.
- Food Packaging:FDA migration-tested formulations dominate United States retail produce, while EU Green Deal recycled content mandates reshape German and French sourcing. Berry packers and cut-vegetable processors specify barrier-enhanced grades.
- Consumer Electronics:Anti-static and ESD-safe formulations protect semiconductors and components during Asia-Pacific assembly and export. Shenzhen and Seoul electronics corridors drive specification intensity.
- Retail Products:Cosmetics and premium goods demand crystal-clear clarity and tamper-evident hinge designs.
- Medical Supplies:ISO 13485-certified cleanroom production meets FDA and EMA sterility requirements for surgical kits and diagnostic components.
Volume concentration favors Food Packaging. Margin expansion is steepest in Medical Supplies where validation timelines limit supplier pools.
Material:
Feedstock selection now hinges on regulatory thresholds rather than purely technical performance, reshaping converter resin procurement.
- RPET:Post-consumer flake content of 30-100% satisfies California SB 54 and German retailer minimums. Mechanical recycling capacity constraints in the United States create spot-price volatility that compresses thermoformer margins.
- Virgin PET:Resin purity ensures consistent optical clarity and predictable processing windows for high-speed forming lines. Asian pellet supply concentration exposes converters to freight and currency risk.
- Biodegradable PET:Additive-modified grades target composting infrastructure in France and Italy where separate organic waste streams exist.
- Recyclable PET:Design-for-recycling certifications from APR and RecyClass enable streamlined MRF sorting in North American and European collection systems.
Regulatory pull concentrates in RPET. Virgin PET retains share where optical consistency and FDA food-contact certainty outweigh sustainability premiums.
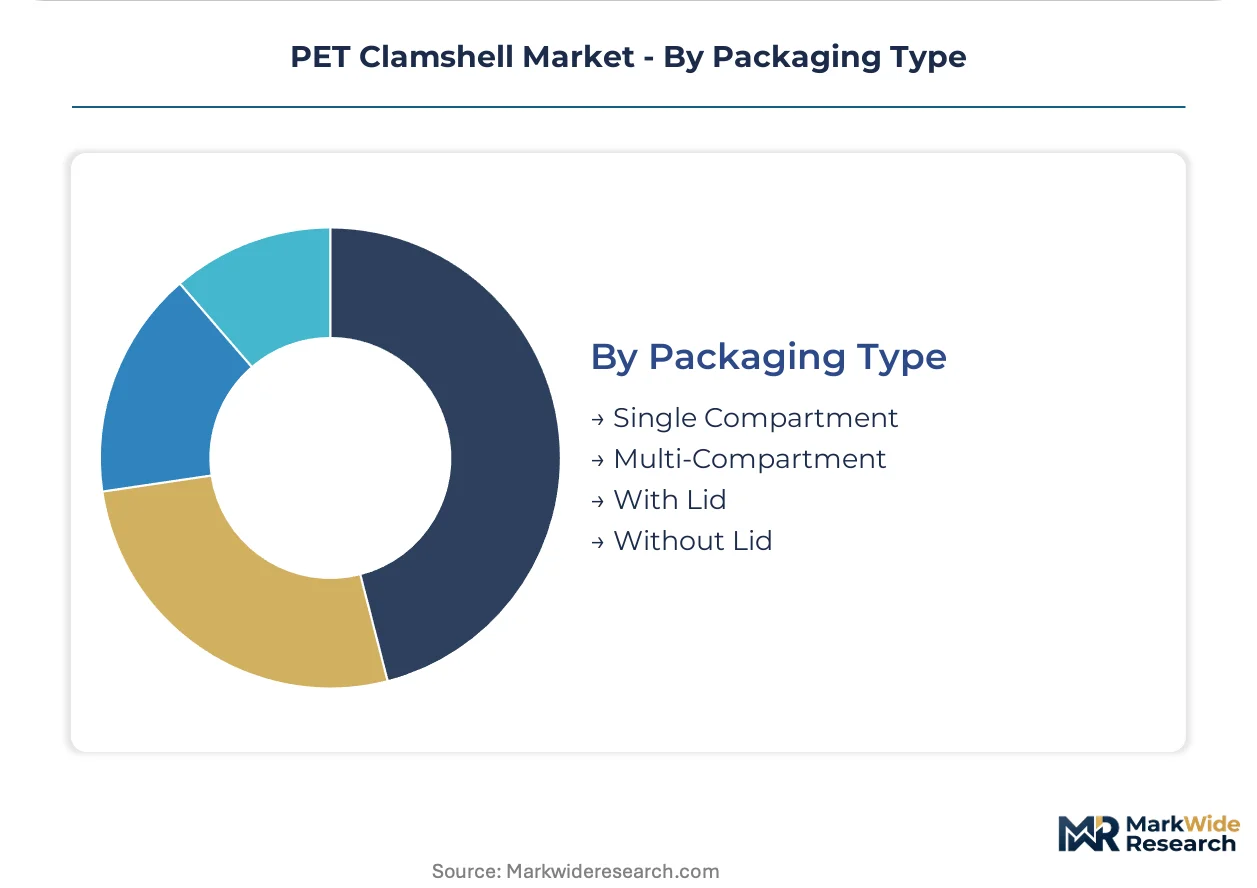
Packaging Type:
Compartment configuration and lid integration determine automation compatibility and consumer convenience trade-offs.
- Single Compartment:Standardized footprints maximize thermoforming line efficiency and minimize tooling amortization per unit. United States berry and grape shippers specify this format for high-velocity retail distribution.
- Multi-Compartment:Separated cavities enable portion control in prepared meals and snack packs. Meal kit providers in Germany and subscription services in China pay margin premiums for tamper-evident multi-chamber designs.
- With Lid:Hinged or separate-lid configurations protect against contamination and enable reclosure. E-commerce grocery platforms in China mandate lidded formats for damage reduction during delivery.
- Without Lid:Open designs reduce material weight and suit automated retail environments with immediate consumption or secondary overwrap.
Operational scale clusters around Single Compartment formats. Fastest adoption is occurring in Multi-Compartment configurations for foodservice subscription channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in China and the United States while consumption concentrates in developed retail markets. Germany and India represent diverging demand profiles shaped by regulatory stringency versus retail modernization. Regional strategies must navigate feedstock access, extended producer responsibility frameworks, and supermarket chain consolidation patterns.
United States
Supermarket chains including Kroger and Albertsons drive standardized clamshell specifications for produce departments. California's SB 54 extended producer responsibility law mandates minimum recycled content thresholds and funds collection infrastructure. The Central Valley berry-growing region sources barrier-enhanced formats from thermoformers with West Coast extrusion capacity.
Germany
Discounters Aldi and Lidl impose 50% RPET minimums on packaging suppliers by 2025. The EU Green Deal packaging waste directives tighten recycled content mandates for imported materials. The Rhine-Ruhr industrial corridor hosts mechanical recycling facilities supplying post-consumer flake to converters serving Dutch and French retail markets.
China
E-commerce grocery platforms JD.com and Missfresh specify lidded clamshell formats for fresh produce delivery. National dual carbon goals accelerate chemical recycling pilot projects in Guangdong province. The Yangtze River Delta manufacturing cluster supplies both domestic supermarket chains and electronics exporters requiring anti-static packaging grades.
India
Organized retail expansion by Reliance Fresh and BigBasket standardizes clamshell formats for private-label produce. The Food Safety and Standards Authority of India governs food-contact material compliance for imported resin. Maharashtra's Pune-Ahmednagar industrial belt attracts first-mover thermoformers establishing local tooling capabilities.
PET Clamshell Market Competitive Landscape
Top-tier vendors anchor North American supermarket supply chains, while mid-tier regional thermoformers compete on tooling flexibility and seasonal program responsiveness. The vendor base stratifies across integrated resin-to-package operators, specialized food-contact converters, and electronics-focused fabricators. Strategic archetypes include backward-integrated sheet extruders, design-forward custom thermoformers, and scale-driven commodity producers. Competitive moves center on RPET feedstock securing through offtake agreements and automation investments in servo-driven pressure-forming lines.
Among North American integrated packaging groups, Pactiv Evergreen and Amcor exemplify scale-driven archetypes with captive resin sourcing and broad foodservice distribution networks. Lacerta Group occupies a position within the custom-design tier, leveraging East Coast manufacturing proximity to major supermarket headquarters for rapid prototyping and seasonal program turnaround.
| Leading Market Players |
|---|
| Lacerta Group |
| Pactiv Evergreen |
| Placon |
| Novolex Holdings |
| Amcor |
| VisiPak |
| Display Pack |
| EasyPak |
| Dordan Manufacturing |
| Others |
Value Network & Pricing Analysis
Supermarket chain procurement concentration in the United States, Germany, and China anchors contract-based long-term offtake pricing for PET clamshells, with volume scale and RPET certification grade separating premium converters from commodity thermoformers.
Pricing Analysis
Margin tightening in mid-tier thermoforming reflects RPET feedstock scarcity and California SB 54 compliance costs. Pricing stratifies across premium barrier-enhanced grades, standard FDA-compliant formats, and economy virgin-PET designs. Price differentiation traces to certification level and vertical integration depth. Small regional converters exhibit highest price sensitivity; integrated resin-to-package operators defend margin through captive flake sourcing.
Supply Chain Analysis
Virgin PET pellet supply rests on producers in China, South Korea, and Thailand, while mechanical recycling capacity concentrates in the United States and Germany. Raw material dependencies span ethylene glycol, terephthalic acid, and post-consumer baled PET. Single-source vulnerability in Asian resin imports exposes converters to freight cost swings. Distribution runs through supermarket chain direct contracts and foodservice redistribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical recycling scale-up is displacing mechanical recycling limits as the dominant feedstock technology, creating first-mover advantages for converters securing pyrolysis and glycolysis offtake positions.
For Market Incumbents: Hedge against RPET spot-price volatility through backward integration into mechanical recycling or chemical recycling joint ventures. Defend market position by accelerating servo-driven pressure-forming automation to cut cycle times. Counter polypropylene substitution threats with barrier-enhanced clamshell designs that extend produce shelf life beyond PP tub performance. For New Entrants and Emerging Players: Chemical recycling technology-first wedge opens white-space in India and Southeast Asia where organized retail standardization is nascent. Target Reliance Fresh and BigBasket private-label programs with local tooling partnerships. Pursue prepared meal kit multi-compartment formats where tamper-evident design capabilities limit incumbent responsiveness. For Investors and Strategic Acquirers: The window for entry favors converters with secured chemical recycling feedstock positions and in-house sheet extrusion capabilities. Long-term viability hinges on mass-balance certification infrastructure for EU Green Deal compliance. Watch mechanical recycling capacity expansion announcements as inflection indicators for RPET spot-price stabilization.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Pyrolysis projects in Texas and the Netherlands unlock food-grade RPET from mixed-waste streams. |
| Servo-Driven Automation | Pressure-forming line upgrades enable thinner-gauge designs without sacrificing structural integrity. |
| RPET Feedstock Securing | Long-term offtake agreements with mechanical recyclers in California and Germany lock in compliant positions. |
| Multi-Compartment Design Investment | Tamper-evident configurations capture margin premiums in German and Chinese meal kit channels. |
| Mass-Balance Certification | EU Green Deal compliance enables continued access to Aldi and Lidl supplier rosters. |
Research Methodology
Document review covered FDA food-contact guidance documents, EPA recycling stream standards, EU Green Deal packaging waste directives, and state-level extended producer responsibility legislation, complemented by interviews with thermoforming plant managers, supermarket category buyers, resin procurement leads, and mechanical recycling facility operators. Secondary sources included customs and trade data, SEC filings from integrated packaging groups, and industry association reports from the Association of Plastic Recyclers. Bottom-up capacity estimates triangulated against top-down demand projections from supermarket chain produce volume data.
Unit volume and value outputs synthesized thermoforming line capacity utilization, resin price indices, and regulatory compliance cost premiums across the projection horizon. Segmentation modeling incorporated product type, material grade tier, end-use application, and regional regulatory cluster dimensions. CAGRs derived from historical supermarket produce packaging conversion rates and e-commerce grocery platform growth trajectories. Forecast inputs included California SB 54 implementation timelines and German retailer RPET minimum threshold deadlines.
Several conditions sit outside the modeled scope, including unforeseen FDA additive migration rule changes, breakthroughs in alternative barrier materials, and macroeconomic shocks to Asian resin export pricing. Forecasts reflect documented assumptions regarding mechanical recycling capacity expansion and chemical recycling commercialization timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
PCR Plastic Packaging Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
PCR Films Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Saudi Arabia Plastic Packaging Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
Egypt Plastic Bottles Market