
 Plastic Packaging Market | 2026-2036
Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Packaging Market Intelligence
A divergence in capital investment for advanced recycling and material science R&D is redrawing the competitive landscape. Global players like Amcor leverage significant scale for resin procurement and new polymer development. In contrast, Constantia Flexibles specializes in high-barrier flexible films for niche applications. Novolex Holdings competes with a diversified portfolio across both rigid and flexible packaging formats, serving a wide customer base.
Plastic packaging involves forming synthetic polymers into containers and films. Materials like Polyethylene Terephthalate (PET) are selected for properties including high tensile strength and chemical resistance, primarily to preserve, protect, and transport goods. Bottles and films command significant volume within packaging formats, especially for the food and beverage sector. Polypropylene and High-Density Polyethylene represent dominant material types due to their versatility across rigid and flexible applications.
Regulatory frameworks like the EU Green Deal and directives from the US Food and Drug Administration (FDA) govern material safety and recyclability. Concurrently, ISO standards for packaging influence design and testing protocols, shaping market access in multiple countries. Stakeholder decisions will increasingly hinge on balancing performance requirements with escalating circular economy mandates and material sustainability.
Market Dynamics
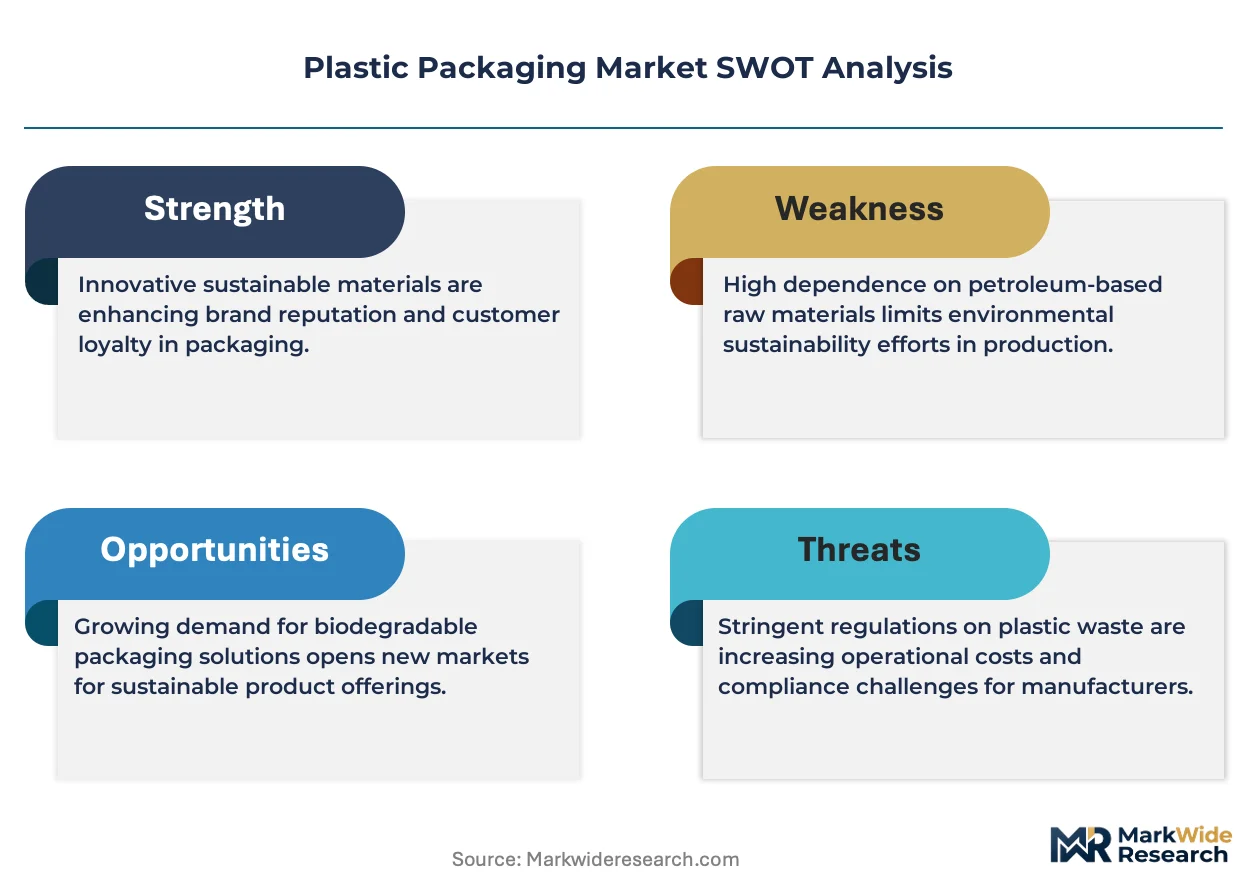
The central structural force shaping the plastic packaging market is the direct conflict between the material's unparalleled performance-to-cost ratio and the escalating global pressure for circularity, driven by regulations like the EU's Single-Use Plastics Directive.
Growth Catalysts
- Pharmaceutical Sector Expansion:Demand from the pharmaceuticals industry for sterile, lightweight, and tamper-evident packaging, such as blisters and vials, is a significant growth driver, especially for high-performance polymers.
- Food Processing in India:India's expanding food processing and consumer goods industries are fueling high-volume demand for flexible films and rigid containers to improve food safety and extend shelf life.
- Bio-Based Polymer Innovation:Advances in bio-based and biodegradable polymers, such as Polylactic Acid (PLA), offer alternatives that align with corporate sustainability goals for specific single-use applications.
Market Restraints
- Feedstock Price Volatility:The market is exposed to price fluctuations of crude oil and natural gas, which are the primary feedstocks for virgin polymer resins and can create significant cost instability.
- Inconsistent Recycling Infrastructure:A lack of standardized and efficient collection and sorting systems on a global scale hinders the availability of high-quality post-consumer recycled (PCR) material.
- Substitution from Alternative Materials:A persistent threat comes from materials like glass, aluminum, and paper-based composites, which are gaining preference in segments like beverages due to consumer perception of sustainability.
Strategic Opportunities
- Advanced Recycling Technologies:Investing in chemical recycling methods like pyrolysis and gasification can unlock new value streams by converting mixed and contaminated plastic waste back into virgin-quality resins.
- High-Barrier Film Development:There is a significant opportunity in creating multi-layer films with enhanced oxygen and moisture barriers to reduce food waste, catering to the fresh food and ready-to-eat meal segments.
- Smart Packaging Integration:Incorporating technologies like RFID and QR codes into packaging offers enhanced traceability, consumer engagement, and authentication, particularly for high-value pharmaceutical and electronic goods.
Industry Challenges
- Recycled Content Compliance:Meeting stringent food-contact safety standards, such as those from the FDA and EFSA, for plastics containing recycled content presents a major technical and regulatory hurdle.
- Capital Investment for Circularity:The transition to a circular economy demands massive capital expenditure to build advanced sorting facilities and chemical recycling plants capable of processing post-consumer waste at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Packaging Market |
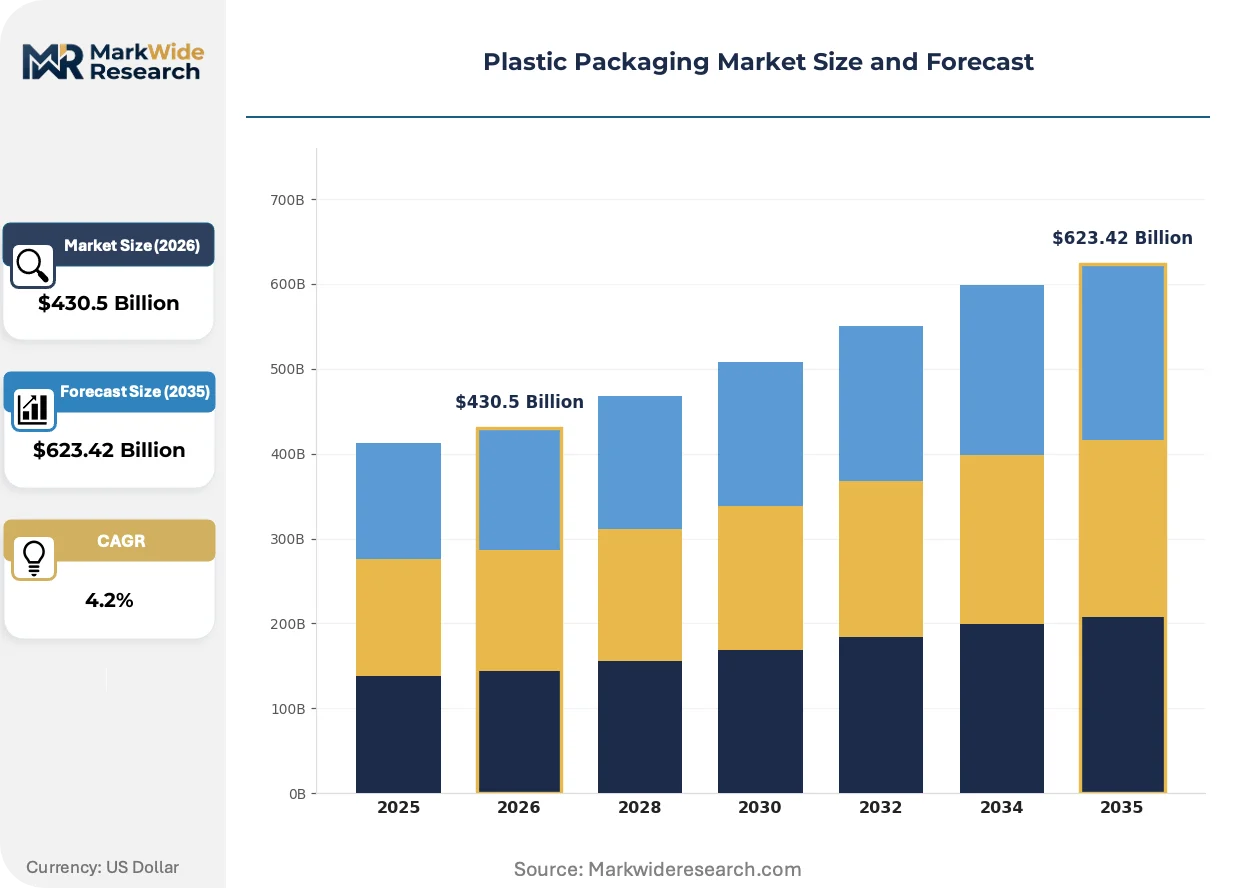
| Market Size in 2026 | $430.5 Billion |
| Market Size in 2035 | $623.42 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
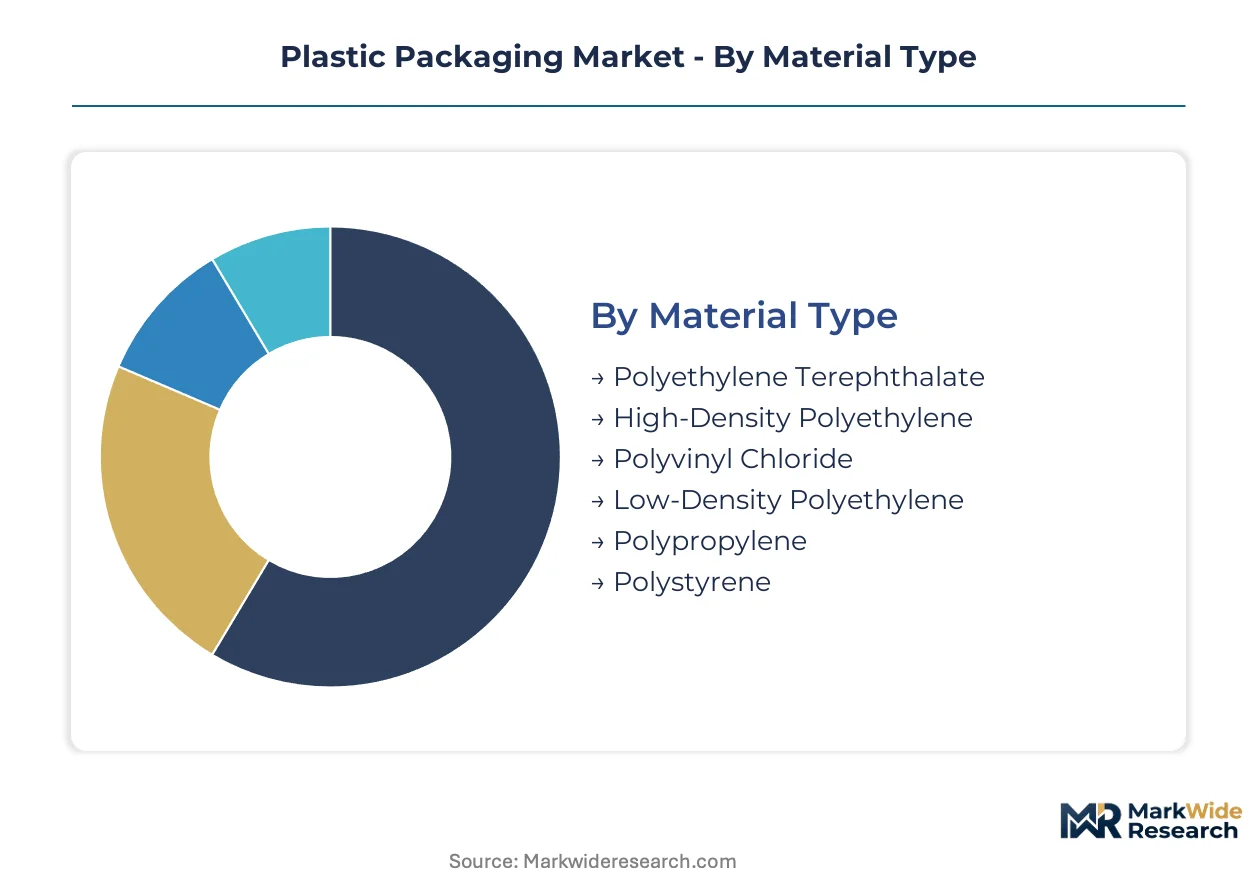
| Segmentation | Material Type: Polyethylene Terephthalate, High-Density Polyethylene, Polyvinyl Chloride, Low-Density Polyethylene, Polypropylene, Polystyrene Packaging Format: Bottles, Films, Containers, Trays, Bags, Wraps Application Sector: Food & Beverage, Personal Care, Pharmaceuticals, Electronics, Automotive Components, Household Goods End User Industry: Consumer Goods Manufacturers, Pharmaceutical Producers, Electronics Suppliers, Automotive Assemblers, Cosmetic Brands, Food Producers |
| Companies Covered | Huhtamaki Oyj, Dart Container Corporation, Amcor, Genpak, Anchor Packaging, Sealed Air, CCL Industries, Novolex Holdings, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Packaging Market Strategic Shifts & Innovations
Material science and regulatory mandates are compelling a fundamental shift in the plastic packaging industry. The market is moving away from a linear model towards a circular one, where waste is designed out and materials are kept in use, redefining product design and supply chain logistics.
Enzymatic recycling is a novel depolymerization technology that utilizes engineered enzymes to break down polymers like PET into their constituent monomers. Food and beverage brand owners are actively exploring this for creating high-purity recycled plastics, though adoption remains in early, developmental stages. This process is decomposing the traditional division between mechanical and chemical recycling, enabling a pathway to true bottle-to-bottle circularity for food-grade packaging.
The EU's Single-Use Plastics Directive imposes stringent rules, including recycled content targets for beverage bottles and bans on specific products like cutlery and plates. This regulation forces a comprehensive redesign of packaging portfolios and drives investment in collection infrastructure across all member states. The beverage sector is most directly impacted, creating intense competition to secure sufficient rPET supply to meet compliance deadlines.
A clear shift in corporate procurement behavior now prioritizes packaging with verified sustainability credentials over purely cost-driven decisions. This change is displacing conventional purchasing models, as buyers increasingly demand materials with certifications like ISCC PLUS to validate recycled content claims. This trend is most prominent for consumer-facing goods in European and North American markets, where ESG commitments heavily influence supply chain choices.
Plastic Packaging Market Segmentation
Understanding the Plastic Packaging Market through its various segments reveals how material science and application demands converge. This granular breakdown clarifies diverse requirements of end-user industries and specific roles different packaging formats play.
Material Type:
The selection of plastic material types directly influences processing channels and machinery, impacting cost and performance attributes.
- Polyethylene Terephthalate:This polymer exhibits high tensile strength, chemical resistance, and superior barrier properties. Demand concentrates in the beverage sector across Europe, driven by recycling mandates.
- Polypropylene:Known for its heat resistance, chemical inertness, and versatility. The food packaging industry in India drives high-volume application.
- High-Density Polyethylene:HDPE offers high strength-to-density ratio and chemical resistance, suitable for bottles and containers.
- Polyvinyl Chloride:PVC provides clarity and impact resistance, used in pharmaceutical blister packaging.
- Low-Density Polyethylene:LDPE is highly flexible and transparent, primarily utilized for films and bags.
- Polystyrene:PS offers rigidity and insulation, often used in disposable food service items.
By volume, Polyethylene Terephthalate leads the market. By growth pace, bio-based variations of Polypropylene are ahead.
Packaging Format:
Packaging formats are shaped by product functional requirements, dictating design, material choice, and protective capabilities.
- Bottles:Rigid, hollow containers from PET or HDPE, for liquids like beverages and personal care. Robust demand in North American beverage sector due to convenience.
- Films:Thin, flexible sheets, often multi-layered, providing barrier protection and sealability. European food processing uses films for fresh produce, prioritizing extended shelf life.
- Containers:Broad range of rigid or semi-rigid plastic vessels for food, dairy, and household goods, typically from PP or PS.
- Trays:Shallow, open plastic forms, commonly used for packaging fresh meat and baked goods, offering visibility.
- Bags:Flexible pouches or sacks, often from LDPE or PP, for bulk goods and groceries.
- Wraps:Stretchable or shrinkable plastic films, used for bundling and protecting items during transport.
Bottles command the largest share of market volume. Films are expanding most quickly, particularly in high-barrier applications.
Application Sector:
The diverse needs of various application sectors dictate specific packaging functionalities, influencing material selection and regulatory compliance.
- Food & Beverage:This sector uses plastic packaging for preservation, hygiene, and convenience. Demand in India's urban markets drives consumption for extended shelf life.
- Pharmaceuticals:Requires sterile, tamper-evident, and child-resistant packaging for drugs and medical devices. European EMA imposes strict safety and traceability standards.
- Personal Care:Encompasses packaging for cosmetics and toiletries, prioritizing aesthetic appeal and dispensing functionality.
- Electronics:Utilizes plastic packaging for protection against shock, static discharge, and moisture during transport.
- Automotive Components:Requires durable and custom-molded plastic packaging for parts, ensuring protection during logistics.
- Household Goods:Covers packaging for cleaning products, balancing cost-effectiveness with chemical resistance.
The Food & Beverage sector represents the largest consumer of plastic packaging. Pharmaceuticals exhibit a steep expansion trajectory.
End User Industry:
The specific operational models and procurement strategies of end-user industries significantly influence margin structures within the plastic packaging supply chain.
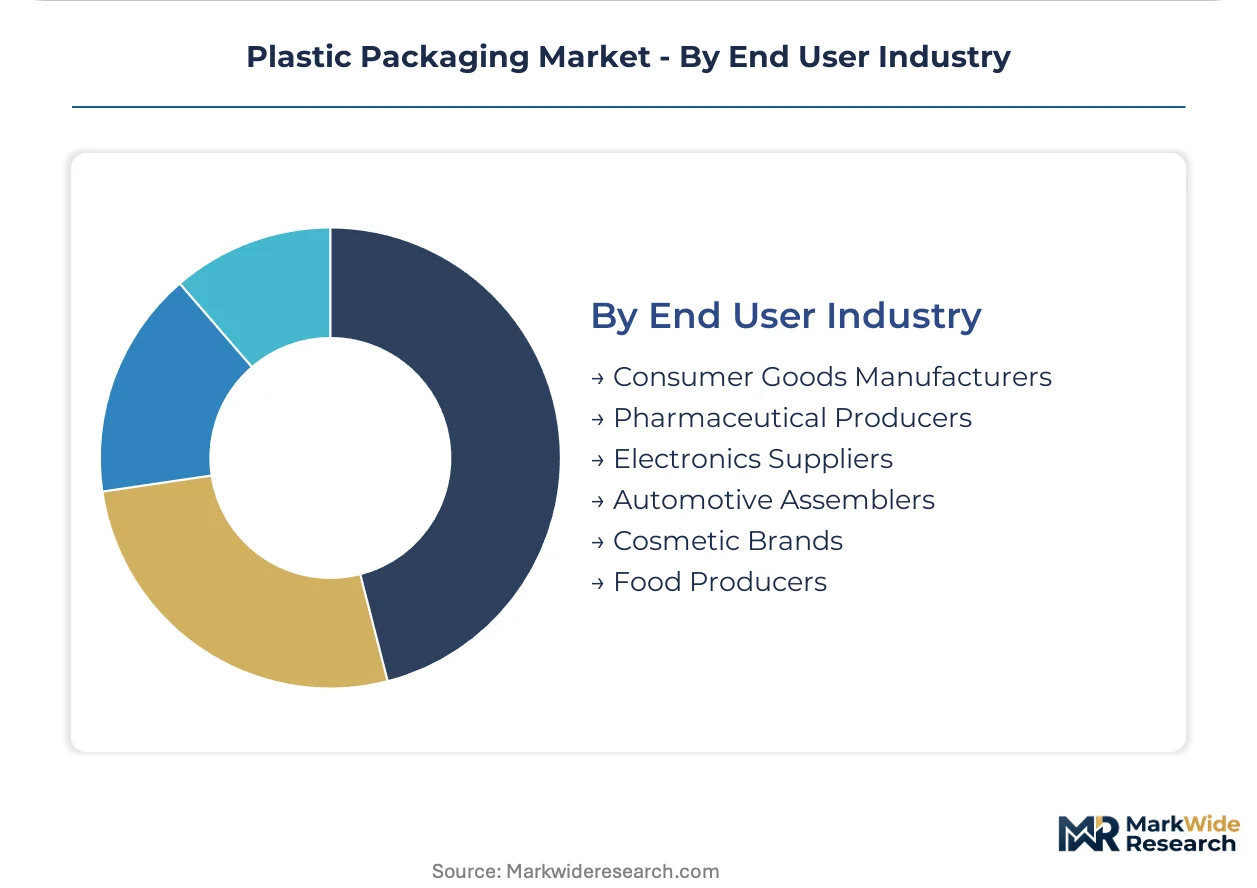
- Consumer Goods Manufacturers:These entities require packaging balancing brand aesthetics, performance, and cost-efficiency. Procurement prioritizes sustainable options and designs enhancing shelf appeal in North American retail.
- Food Producers:Focus on packaging solutions ensuring food safety, extended shelf life, and stringent regulatory standards. Indian food producers drive demand for efficient distribution packaging.
- Pharmaceutical Producers:Seek highly specialized, compliant packaging guaranteeing product integrity and patient safety, adhering to US FDA regulations.
- Electronics Suppliers:Demand packaging offering robust protection against physical damage and electrostatic discharge for sensitive components.
- Automotive Assemblers:Require industrial-grade packaging for components, emphasizing durability and logistical efficiency.
- Cosmetic Brands:Prioritize packaging conveying luxury, protecting formulations, and incorporating innovative dispensing mechanisms.
Consumer Goods Manufacturers represent the largest segment by volume. Pharmaceutical Producers are gaining share fastest due to specialized requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry is evident, with North American markets often commanding higher margins for specialized packaging solutions compared to the cost-sensitive, high-volume demands of Southeast Asian economies. This divergence shapes investment flows and material procurement strategies across the plastic packaging market. Regulatory divergence also plays a significant role in market development.
United States
Demand for plastic packaging in the United States is driven by the vast consumer goods sector and pharmaceutical industry. The US Food and Drug Administration (FDA) sets rigorous standards for food-contact materials and pharmaceutical packaging, influencing material innovation. Major innovation hubs like Silicon Valley and research clusters in Boston drive smart packaging integration and bio-based polymer development.
Germany
Germany's plastic packaging market sees strong demand from its advanced automotive components and high-end consumer goods industries. The EU Green Deal and national packaging laws like VerpackG enforce stringent recyclability and recycled content targets. The Rhine-Ruhr region, a major industrial heartland, concentrates packaging manufacturers focusing on sustainable material solutions and circular economy initiatives.
India
India's expanding food processing sector and burgeoning e-commerce drive significant demand for flexible films and rigid containers. The Food Safety and Standards Authority of India (FSSAI) mandates specific packaging standards to ensure product safety and extend shelf life. Urban centers like Mumbai and Delhi act as key consumption hubs, fueling demand for cost-effective and protective packaging solutions.
China
Consumer electronics manufacturing and the massive domestic food and beverage market propel China's plastic packaging consumption. China's dual carbon goals and national environmental protection policies are accelerating the shift towards more sustainable packaging materials. Industrial parks in the Yangtze River Delta concentrate packaging production, emphasizing advanced manufacturing and material science R&D.
Plastic Packaging Market Key Industry Players
Concentration sits with large, integrated packaging manufacturers offering diversified portfolios across multiple material types. The market structure exhibits a tiered consolidation, with global conglomerates at the top and numerous regional specialists addressing niche applications. Strategic archetypes include scale players leveraging raw material procurement and innovation-driven firms specializing in high-barrier or sustainable solutions. Dominant competitive moves involve strategic partnerships for new material development and targeted acquisitions to expand geographic reach.
Scale-driven players like Amcor and Novolex Holdings exemplify the strategy of broad market coverage across diverse packaging formats and end-use sectors. Amcor, a global entity, leverages its extensive operational footprint for efficient resin procurement and new polymer development, serving a wide array of consumer goods manufacturers. Novolex Holdings, with its diversified portfolio, caters to both rigid and flexible packaging needs across North American markets. Constantia Flexibles, in contrast, represents specialized expertise in high-barrier flexible films for demanding applications, often focusing on pharmaceutical and food processing clients in Europe. These distinct approaches underscore the varied competitive dynamics within the plastic packaging industry.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Dart Container Corporation |
| Amcor |
| Genpak |
| Anchor Packaging |
| Sealed Air |
| CCL Industries |
| Novolex Holdings |
| Constantia Flexibles |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for virgin polymer resins provide stability for large manufacturers. This ensures material access and price predictability amidst feedstock volatility.
Pricing Analysis
Configured-to-order high-barrier films command a premium over standard commodity packaging, reflecting specialized performance requirements. The market operates on a hybrid pricing model, blending contract-based long-term offtake for base resins with per-unit transactional pricing for specialized solutions. Price differentiation stems from customization levels and specific certification tiers, such as FDA/EFSA compliance for food contact. Pricing pressure arises from the increasing preference for alternative materials and escalating circularity mandates. Pharmaceutical producers exhibit lower price sensitivity compared to highly cost-conscious consumer goods manufacturers.
Supply Chain Analysis
Inbound logistics costs, particularly port congestion in major trade lanes like the Suez Canal, influence material availability and final product pricing. Geographic supply concentrates in China, the United States, and Germany for manufacturing, while India is a major consumption hub. The industry depends on crude oil and natural gas as primary feedstocks, alongside emerging bio-based alternatives. Inconsistent recycling infrastructure represents a structural risk, limiting the availability of high-quality post-consumer recycled content. Distribution runs through direct sales channels to large brand owners and regional distributors serving smaller businesses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic packaging market presents a fragmentation opportunity as escalating circularity mandates and specific end-user performance requirements create numerous unmet niches. Demand for certified recycled content is reshaping competitive positioning.
For Market Incumbents: Compound operational scale with targeted R&D in advanced recycling technologies like enzymatic depolymerization. Leverage extensive resin procurement networks to secure certified post-consumer recycled (PCR) material, addressing the threat from inconsistent recycling infrastructure. Invest in high-barrier film development to reduce food waste, a key lever against substitution from alternative materials.
For New Entrants and Emerging Players: Lead with bio-based polymer innovations, targeting specific single-use applications where sustainability goals are paramount. The pharmaceutical sector, with its high-performance polymer needs, represents a penetrable segment for specialized bio-plastic vials and blisters. A go-to-market angle focusing on verifiable circularity credentials and superior barrier properties can capture early adopters.
For Investors and Strategic Acquirers: The market sits at a transformative phase that favors innovation-driven firms specializing in circular economy solutions. Long-term viability depends on investments in advanced recycling technologies and sustainable material science. Acquisition targets should be mid-cap specialists with patented high-barrier film technologies or established bio-polymer production capabilities. The signal to watch is the widespread adoption of enzymatic recycling for food-grade plastics.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for rPET | Secures material supply for beverage bottle compliance. |
| Joint Venture in Chemical Recycling | Unlocks value from mixed plastic waste streams. |
| Bio-based Polymer Product Launch | Addresses corporate sustainability targets for single-use items. |
| Smart Packaging Integration | Enhances traceability and consumer engagement for high-value goods. |
| Certification Investment (ISCC PLUS) | Validates recycled content claims for consumer-facing brands. |
Research Approach
Initial hypotheses were tested against primary input from packaging engineers, brand procurement managers, regulatory affairs specialists, and polymer scientists, and refined through iterative feedback. Primary interviews were triangulated with secondary validation from sources like FDA filings, EU Green Deal reports, and national trade association publications. This approach ensured a robust understanding of market dynamics, integrating both bottom-up granular insights and top-down industry trends.
Variance decomposition identified key drivers impacting market growth across the analysis window, including material type, packaging format, application sector, and end-user industry. CAGRs were derived using a multi-factor regression model, incorporating variables such as crude oil prices and regulatory compliance costs. This framework provided granular forecasts for bio-based polymer adoption and high-barrier film expansion.
The analysis sits within stated boundaries; outcomes outside significant shifts in global petrochemical supply or unforeseen regulatory bans would require recalibration. Forecasts reflect assumptions regarding technological advancements in recycling and consumer acceptance of sustainable packaging. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Europe PET Packaging Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
Plastic-Based Egg Packaging Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Plastic Keg Market