
 Latin America Plastic Bottles Market | 2026-2036
Latin America Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Plastic Bottles Market Insights
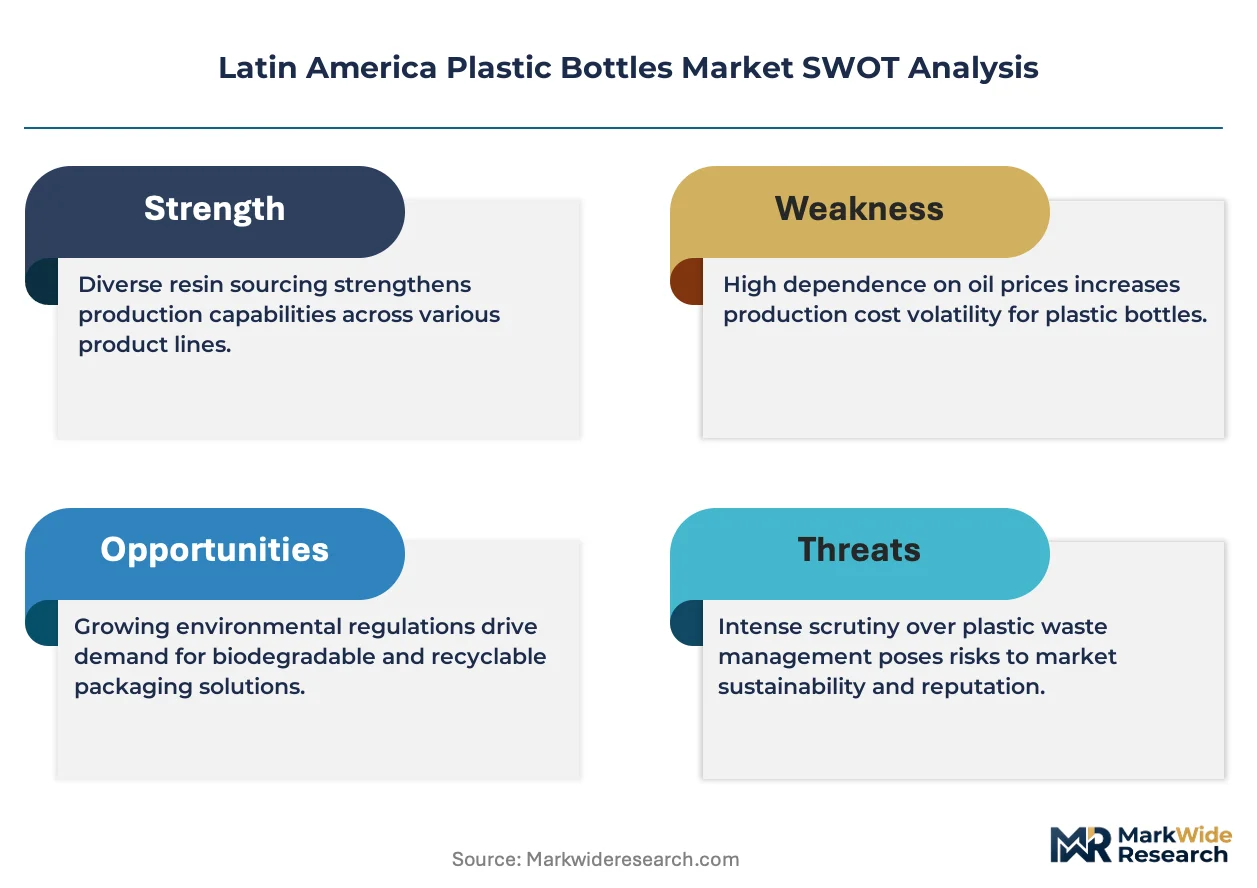
A shortage of certified blow-molding technicians is redrawing competitive boundaries across Latin America's plastic bottles sector. ALPLA Group leverages its technical training academies in Brazil and Mexico to sustain operational continuity at high-output facilities. Amcor Group anchors regional supply through integrated preform and bottle production networks spanning the Andean ridge. Indorama Ventures Public Company Limited dominates resin-to-bottle value streams with captive PET polymer capacity near key Brazilian converters.
Latin America plastic bottles are hollow containers manufactured primarily through blow-molding and injection-stretch-blow processes, typically formed from polyethylene terephthalate (PET) with wall thicknesses calibrated between 0.25 mm and 0.45 mm for carbonated beverage applications, serving as primary packaging for liquids requiring barrier protection against oxygen ingress and UV degradation. Polyethylene Terephthalate leads material type value contribution due to its recyclability alignment with Latin American extended producer responsibility frameworks. Blow Molding occupies the dominant production type position given its throughput efficiency for high-volume beverage contracts, while the Personal Care end user segment generates premium margin pools through specialized bottle geometries and decoration requirements.
ANVISA in Brazil enforces pharmaceutical-grade plastic bottle purity standards that restrict recycled content thresholds for drug packaging, while Mexico's NOM-252-SSA1-2011 governs food-contact plastic safety and labeling protocols. Brazil's ABETRE recycling certification and Mexico's environmental ministry circular economy guidelines are reshaping post-consumer collection infrastructure investments. Stakeholders must monitor evolving EPR legislation across Mercosur and Pacific Alliance jurisdictions to anticipate compliance cost trajectories and recycling partnership obligations.
Market Dynamics
ANVISA pharmaceutical-grade purity standards are compressing recycled content thresholds for drug packaging while simultaneously tightening material traceability across Brazilian converter networks. This regulatory pressure is forcing resin-to-bottle value chain reconfiguration.
Growth Catalysts
- Extended Producer Responsibility frameworks:Brazil's ABETRE recycling certification and Mexico's circular economy guidelines are mandating post-consumer collection infrastructure investments that expand bottle-to-bottle recycling capacity.
- Carbonated soft drink bottling expansion:Beverage producers across São Paulo's industrial corridor are commissioning high-output PET lines to capture volume growth in Latin America's largest consumption basin.
- Injection-stretch-blow process optimization:Wall thickness calibration advances between 0.25 mm and 0.45 mm are improving barrier performance against oxygen ingress for sensitive liquid applications.
Market Restraints
- PET resin price volatility:Crude oil derivative fluctuations transmit directly to converter margins, compressing profitability for non-integrated blow-molding operations without captive polymer supply.
- Technician certification scarcity:Certified blow-molding specialists concentrate disproportionately in Brazil and Mexico, creating operational continuity risks for facilities in Argentina and Colombia.
- Food-contact safety compliance friction:Mexico's NOM-252-SSA1-2011 labeling protocols impose documentation burdens that extend new product qualification timelines for cross-border suppliers.
Strategic Opportunities
- Colombian Andean ridge penetration:Underdeveloped converter density in Bogotá's manufacturing belt offers first-mover positioning for integrated preform-to-bottle producers.
- Personal Care premium geometry specialization:Specialized bottle decoration and asymmetric shaping capabilities command margin premiums in cosmetics and haircare segments.
- UV barrier technology convergence:Combination of PET co-injection with oxygen-scavenger additives opens pharmaceutical and nutraceutical applications previously reserved for glass.
Industry Challenges
- Multi-jurisdiction EPR synchronization:Mercosur and Pacific Alliance member states maintain divergent post-consumer collection mandates, complicating pan-regional packaging standardization.
- Legacy preform inventory reconfiguration:Existing toolsets calibrated for virgin resin specifications require capital-intensive retrofitting to process certified recycled PET feedstock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Plastic Bottles Market |
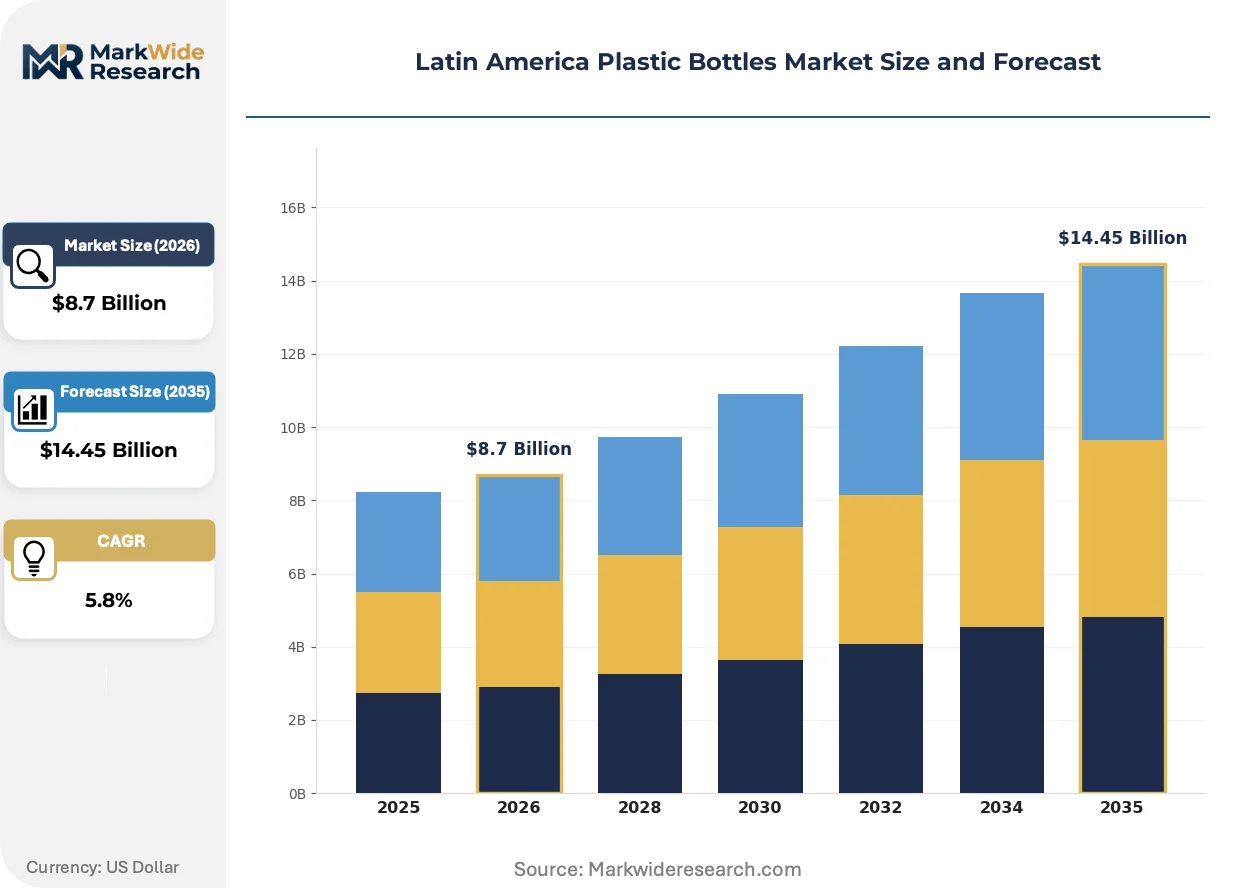
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Type: Injection Molding, Blow Molding, Extrusion, Thermoforming Material Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Others End User: Beverage Industry, Personal Care, Household Products, Food Industry Distribution Channel: Direct Sales, Online Retail, Supermarkets, Convenience Stores |
| Companies Covered | ALPLA Group, Amcor Group, Berry Global Inc, Graham Packaging, Sidel Group, Velaplast, Gerresheimer AG, Indorama Ventures Public Company Limited, Plastipak Holdings Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Plastic Bottles Market Trends and Innovations
Lightweighting technologies and circular material flows are actively reconfiguring competitive boundaries across Latin American plastic bottle manufacturing. Converter investments increasingly prioritize barrier performance optimization alongside recyclability credentials.
Mono-material PET bottle construction is fragmenting multi-layer barrier packaging adoption in pharmaceutical and sensitive food applications. Brazilian drug manufacturers are accelerating qualification timelines for single-polymer formats that simplify post-consumer sorting. This technology is fragmenting legacy co-extrusion equipment valuations as converters retire complex multi-resin lines.
ANVISA pharmaceutical packaging purity standards are restricting recycled content thresholds for drug-contact applications while mandating batch-level resin traceability. Brazilian converters must now document virgin resin provenance through polymerization-to-bottle chain-of-custody records. Pharmaceutical-grade blow-molders are responding by segregating production lines between food-contact and drug-contact specifications.
Beverage bottlers are consolidating procurement around integrated preform suppliers capable of delivering decorated bottles direct-to-filling lines. This specification compression is displacing independent preform converters in Mexico's central highlands manufacturing belt. Argentina's Córdoba industrial cluster exhibits the most visible procurement consolidation, with major soft drink brands mandating supplier vertical integration.
Latin America Plastic Bottles Market Segmentation
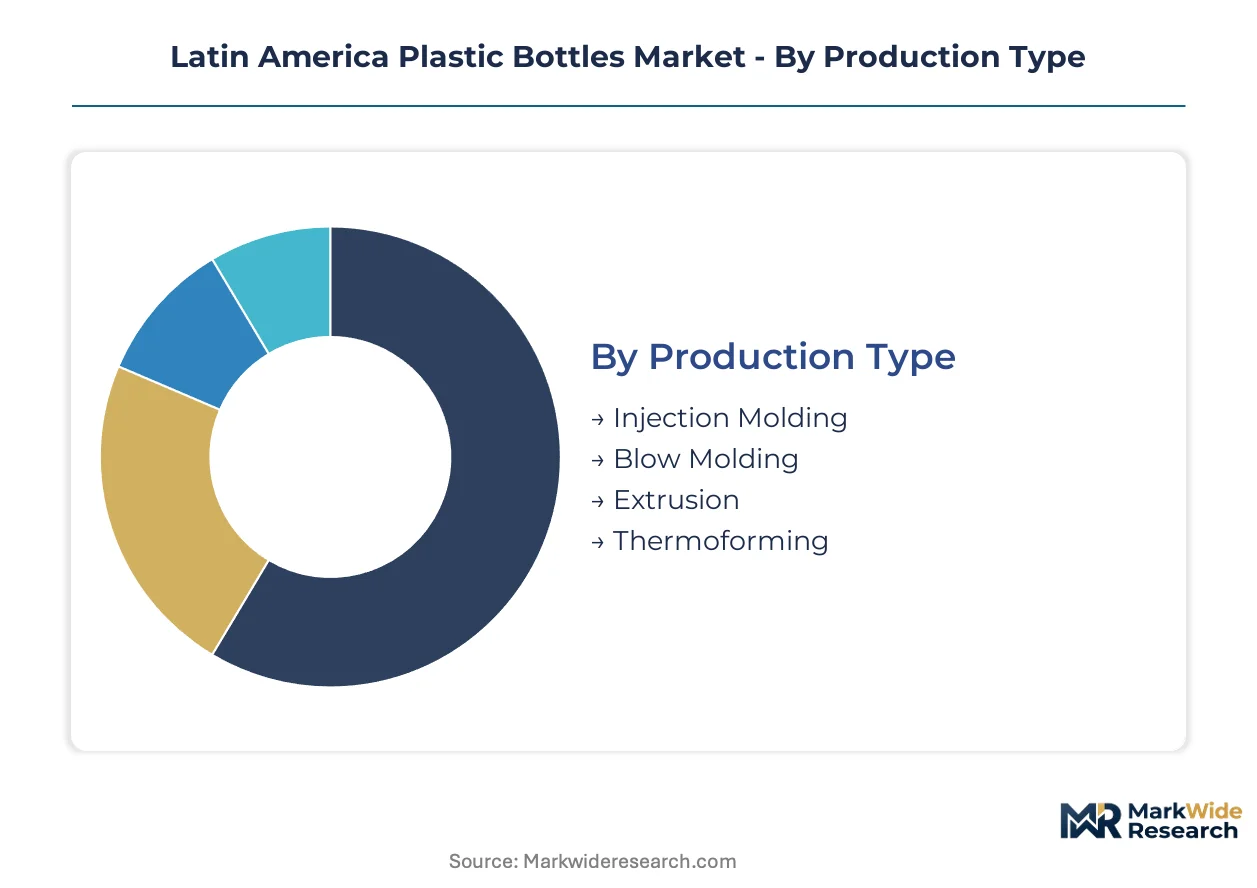
Segmentation across Latin America's plastic bottles market reveals distinct procurement patterns between domestic beverage bottlers and export-oriented personal care manufacturers. Understanding these divides clarifies where converter investments concentrate versus where margin premiums persist.
Production Type:
Domestic beverage bottlers in Brazil and Mexico favor high-throughput methods, while export-facing personal care producers prioritize precision forming for decorative finishes.
- Blow Molding:Stretch-blow and extrusion-blow processes dominate carbonated soft drink and bottled water applications with cycle times optimized for 0.25 mm to 0.45 mm wall thicknesses. São Paulo's industrial corridor hosts the densest concentration of high-output rotary blow-molding systems serving Coca-Cola FEMSA and Ambev filling lines.
- Injection Molding:Preform production and closure manufacturing rely on multi-cavity hot-runner systems with precision tolerance control. Mexican converters near Toluca supply preforms across the central highlands manufacturing belt, capturing economies from resin-to-preform integration.
- Extrusion:Continuous profile forming serves industrial chemical containers and large-format storage bottles with thicker wall specifications.
- Thermoforming:Sheet-based forming addresses shallow-draw pharmaceutical trays and blister packs requiring barrier laminates.
Blow Molding commands the established base. The steepest expansion runs through Injection Molding as preform-to-bottle integration accelerates.
Material Type:
Cost tiers separate commodity resin applications from specialized barrier formulations, with recycling certification requirements reshaping procurement specifications.
- Polyethylene Terephthalate:PET delivers clarity, mechanical strength, and established recycling infrastructure alignment with Brazil's ABETRE certification. Brazilian resin producers Braskem and Indorama supply virgin and rPET grades to converters facing ANVISA traceability mandates for pharmaceutical applications.
- High-Density Polyethylene:HDPE provides chemical resistance and stress-crack performance for household cleaners and agrochemical packaging. Demand concentrates in Argentina's Córdoba industrial cluster where detergent manufacturers source blow-molded jerrycans.
- Polypropylene:PP offers elevated temperature resistance for hot-fill and retort applications in sauces and condiments.
- Others:Polycarbonate and bio-based polymers address niche pharmaceutical and premium cosmetic segments requiring glass-like clarity or sustainability credentials.
Polyethylene Terephthalate dominates volume and value. Polypropylene is climbing the fastest as hot-fill food applications expand.
End User:
Customer type segmentation separates high-volume, price-sensitive beverage contracts from specification-intensive personal care relationships.
- Beverage Industry:Carbonated soft drinks, bottled water, and juices consume the majority of PET bottle output with standardized cylindrical geometries and pressure-rated designs. Mexico's Grupo Modelo and Brazil's Ambev consolidate procurement around integrated suppliers capable of direct-to-filling-line delivery.
- Personal Care:Shampoos, conditioners, and cosmetics demand asymmetric shaping, metallized decoration, and specialized dispensing closures. Colombian converters in Bogotá's manufacturing belt capture premium margins through decoration capabilities serving export markets.
- Household Products:Cleaners, disinfectants, and laundry detergents utilize HDPE bottles with chemical-resistant formulations and trigger-spray compatibility.
- Food Industry:Edible oils, sauces, and condiments require oxygen barrier performance and hot-fill stability in multi-layer or monolayer PET constructions.
Beverage Industry anchors procurement volume. Personal Care generates the steepest margin expansion through decoration specialization.
Distribution Channel:
Supply concentration patterns differ between direct converter-to-filler relationships and fragmented retail-facing routes.
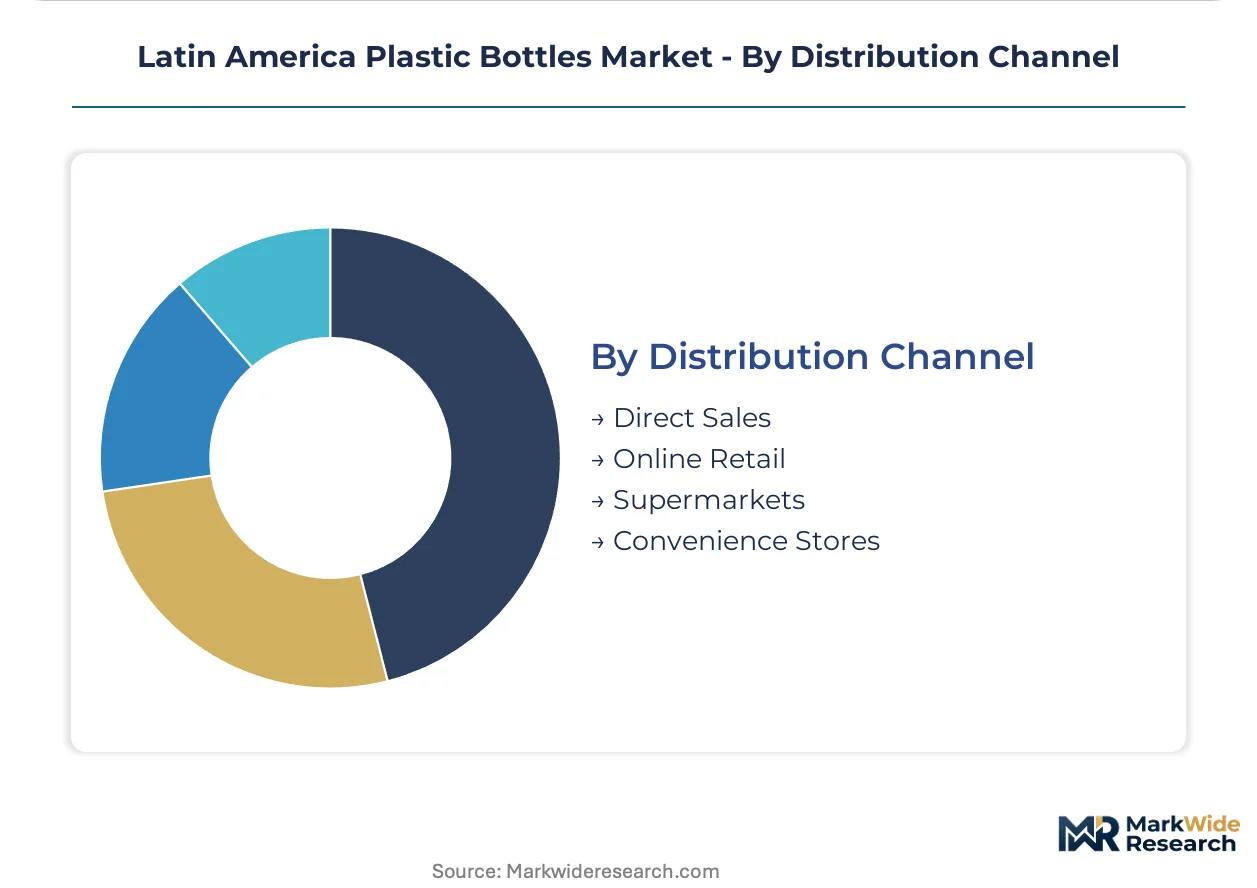
- Direct Sales:Long-term supply agreements between converters and major beverage bottlers eliminate intermediaries and enable just-in-time preform and bottle delivery. Argentina's soft drink brands increasingly mandate direct procurement from vertically integrated suppliers.
- Supermarkets:Private-label water and beverage programs source bottles through converter-distributor networks serving retail chains across Brazil's southeast and Mexico's central region.
- Convenience Stores:Small-format retail drives demand for single-serve bottles with localized distribution from regional converters.
- Online Retail:E-commerce channels for specialty and premium bottles remain nascent, constrained by shipping economics for empty container logistics.
Direct Sales commands converter capacity allocation. Convenience Stores are expanding most quickly alongside urban retail densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA pharmaceutical packaging standards anchor Brazil's regulatory environment, driving material traceability investments across the region's largest converter base. Brazil's ABETRE recycling certification and Mexico's NOM environmental protocols are reshaping compliance cost structures for multinational bottle suppliers.
Brazil
Carbonated soft drink bottlers in São Paulo's industrial corridor are commissioning high-output PET lines to capture volume growth in Latin America's largest consumption basin. ANVISA enforces pharmaceutical-grade purity standards that restrict recycled content thresholds for drug packaging while mandating batch-level resin traceability. São Paulo hosts the densest concentration of rotary blow-molding systems serving Coca-Cola FEMSA and Ambev filling lines.
Mexico
Beverage producers across the central highlands manufacturing belt are expanding preform-to-bottle integration to secure supply continuity for export-facing contracts. NOM-252-SSA1-2011 governs food-contact plastic safety and labeling protocols, imposing documentation burdens that extend new product qualification timelines. Toluca-based converters supply preforms across the region, capturing economies from resin-to-preform integration.
Argentina
Detergent manufacturers in Córdoba's industrial cluster source blow-molded HDPE jerrycans for household cleaner applications, anchoring chemical-resistant packaging demand. The national pharmaceutical regulator maintains drug-contact material standards that align with Mercosur harmonization efforts. Córdoba exhibits visible procurement consolidation, with major soft drink brands mandating supplier backward integration.
Colombia
Cosmetics and haircare exporters in Bogotá's manufacturing belt drive premium margin pools through specialized bottle geometries and metallized decoration capabilities. The national environmental ministry's circular economy guidelines are reshaping post-consumer collection infrastructure investments. Bogotá's underdeveloped converter density offers first-mover positioning for integrated preform-to-bottle producers.
Chile
Wine and spirits bottlers in the Central Valley are adopting mono-material PET constructions to simplify post-consumer sorting for export markets. Extended producer responsibility frameworks mandate post-consumer collection infrastructure investments that expand bottle-to-bottle recycling capacity. Santiago's converter base is retrofitting legacy preform toolsets to process certified recycled PET feedstock.
Latin America Plastic Bottles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive dynamic across Latin American plastic bottle manufacturing. The integrated tier controls captive resin supply and high-output blow-molding capacity, while specialists concentrate in decoration-intensive personal care segments. Three archetypes dominate: resin-integrated converters with polymerization-to-bottle value streams, preform specialists supplying decorated bottles direct-to-filling lines, and regional fabricators serving localized chemical and agricultural packaging. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players seek to secure technician talent and recycling certification credentials.
Within the integrated tier, ALPLA Group and Indorama Ventures Public Company Limited exemplify the resin-captive archetype that controls polymer supply near key Brazilian converters. Amcor Group anchors regional supply through production networks spanning the Andean ridge. These three entities occupy positions that reflect the market's bifurcation between high-volume beverage contracts and specification-intensive pharmaceutical applications.
| Leading Market Players |
|---|
| ALPLA Group |
| Amcor Group |
| Berry Global Inc |
| Graham Packaging |
| Sidel Group |
| Velaplast |
| Gerresheimer AG |
| Indorama Ventures Public Company Limited |
| Plastipak Holdings Inc |
| Others |
Pricing and Supply Chain Analysis
Sixty-day resin inventory cycles at São Paulo converters compress margin buffers when PET feedstock prices spike, concentrating pricing power among Indorama and Braskem's captive supply networks while forcing independent blow-molders into spot market exposure. This inventory-lead dynamic ties converter profitability directly to polymer integration depth across Brazil's industrial corridor.
Pricing Analysis
Price spreads between São Paulo and Bogotá converters exceed freight-adjusted differentials, reflecting ANVISA certification premiums in pharmaceutical-grade PET versus commodity beverage contracts. Three-tier pricing structure across premium, standard, and economy levels separates ABETRE-certified rPET from virgin resin and uncertified recycled grades. Cost compression in standard-tier beverage contracts is intensifying because Ambev and FEMSA consolidate procurement around integrated suppliers. Export-facing personal care bottlers in Colombia exhibit least price sensitivity due to decoration premiums and asymmetric geometry specifications.
Supply Chain Analysis
Port congestion at Santos and Manzanillo extends inbound resin delivery windows, elevating working capital requirements for non-integrated converters dependent on Asian PET pellet imports. Supply concentrates in Brazil, Mexico, and Argentina, with Brazilian resin production anchored by Braskem's integrated petrochemical complexes and Indorama's PTA-PET operations. Raw material dependencies center on purified terephthalic acid, monoethylene glycol, and recycled flake feedstock certified under ABETRE protocols. Single-source vulnerability runs through Indorama's dominance of regional polymerization capacity. Distribution runs through direct converter-to-filler agreements for beverage volumes and distributor networks serving fragmented personal care demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery as carbonated soft drink bottling investment rebounds from pandemic-depressed capacity utilization, with São Paulo's industrial corridor leading capital deployment.
For Market Incumbents: Secure captive rPET certification capacity ahead of ABETRE mandate expansion, locking in post-consumer collection partnerships before collection infrastructure scarcity intensifies. Deepen backward integration into preform tooling to defend against procurement consolidation pressure from Coca-Cola FEMSA and Ambev direct-to-filling-line specifications. ANVISA traceability requirements threaten margin compression for converters lacking batch-level resin documentation systems. For New Entrants and Emerging Players: Lead with decoration-intensive personal care specialization in Bogotá's manufacturing belt, where converter density remains underdeveloped and premium margins persist for metallized and asymmetric bottle geometries. Target Colombia's Andean ridge for first-mover positioning in integrated preform-to-bottle production, exploiting freight advantages to Pacific Alliance export markets. Pursue white-label supply agreements with cosmetics exporters seeking dedicated molding capacity. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging parents seeking to divest non-core Latin American assets amid portfolio rationalization pressures. Mid-term viability through the next decade hinges on recycling certification infrastructure ownership and technician training academy assets. Monitor ANVISA pharmaceutical-grade purity standard revisions as inflection signal for drug-contact packaging margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Certification Investment | ABETRE compliance secures access to Coca-Cola FEMSA and Ambev volume contracts. |
| Preform-to-Bottle Integration | Backward control over resin-to-preform conversion captures margin from polymer volatility. |
| Technician Training Academy | ALPLA's academy model addresses certified blow-molding specialist scarcity in Argentina. |
| Personal Care Decoration Capability | Metallized and asymmetric geometries command premium pricing from Bogotá cosmetics exporters. |
| Pharmaceutical-Grade Line Segregation | ANVISA-mandated drug-contact purity standards create defensible specialty margin pools. |
Research Methodology
A standing panel of blow-molding plant managers, beverage procurement directors at FEMSA and Ambev, personal care brand packaging engineers, and ANVISA regulatory affairs specialists provided ongoing calibration against operational realities. Primary fieldwork combined structured interviews with converter operations heads and secondary validation through Brazilian customs export data, ANVISA pharmaceutical packaging filings, ABETRE certification registries, and SEC 10-K disclosures from Indorama and Amcor. Bottom-up capacity tallies across São Paulo, Toluca, and Córdoba industrial clusters were triangulated against top-down resin consumption estimates from Braskem and Indorama.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation modeled across production type, material grade tier, end-use industry, and geographic regulatory cluster. CAGRs were derived from production capacity expansion announcements, bottling line commissioning schedules, and EPR mandate implementation timelines. Forecast inputs incorporated ANVISA purity standard evolution, NOM-252-SSA1-2011 labeling protocol revisions, and Mercosur-Pacific Alliance regulatory harmonization progress.
The analysis sits within stated boundaries; outcomes outside sustained PET resin price stability, ABETRE certification infrastructure buildout, and technician training pipeline expansion would require recalibration. Forecasts reflect documented assumptions regarding EPR implementation pace and pharmaceutical-grade recycled content threshold relaxation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Plastic Sterilization Trays Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Australia Plastic Packaging Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Post-Consumer Recycled Plastic Packaging Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Vacuum Forming Plastic Market