
 Global Single Use Plastic Packaging Market | 2026-2036
Global Single Use Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Single Use Plastic Packaging Market Foresight
ISO 18606 compostability certification is reorganizing supplier eligibility across the Global Single Use Plastic Packaging Market, disqualifying legacy converters that lack accredited testing infrastructure. Amcor plc leverages its integrated film extrusion network to sustain compliance across multiple certification tiers simultaneously. Berry Global Inc. anchors North American flexible packaging supply through captive resin compounding operations that bypass third-party qualification delays. Huhtamaki Oyj competes primarily in molded fiber-alternative segments, positioning its portfolio ahead of pending European single-use directives.
Single use plastic packaging denotes thermoformed, extruded, or injection-molded polymer articles designed for one-time product containment and disposal, typically manufactured from polyethylene terephthalate, polypropylene, or polystyrene with wall thicknesses below 0.5 millimeters for flexible variants. Its primary commercial purpose centers on cost-efficient hygiene preservation and extended shelf stability for perishable and sensitive goods. Films dominate value capture within flexible packaging formats due to their irreplaceable barrier performance in modified-atmosphere food applications, while containers face structural pressure from fiber substitution mandates in food service channels. Healthcare packaging represents a defensive margin pool where regulatory sterilization requirements preserve polymer dependence despite consumer-sector backlash against disposables.
The European Commission's Packaging and Packaging Waste Regulation intersects with FDA food contact notification requirements and China's GB standards to create a fragmented compliance topography that favors multinational converters with distributed certification capabilities. REACH substance restrictions and emerging extended producer responsibility frameworks in multiple jurisdictions are redirecting R&D budgets toward mono-material designs that simplify mechanical recycling streams. Stakeholders must monitor the divergence between regional biodegradability standards and industrial composting infrastructure availability, as certification alignment without processing capacity creates stranded asset risk in emerging markets.
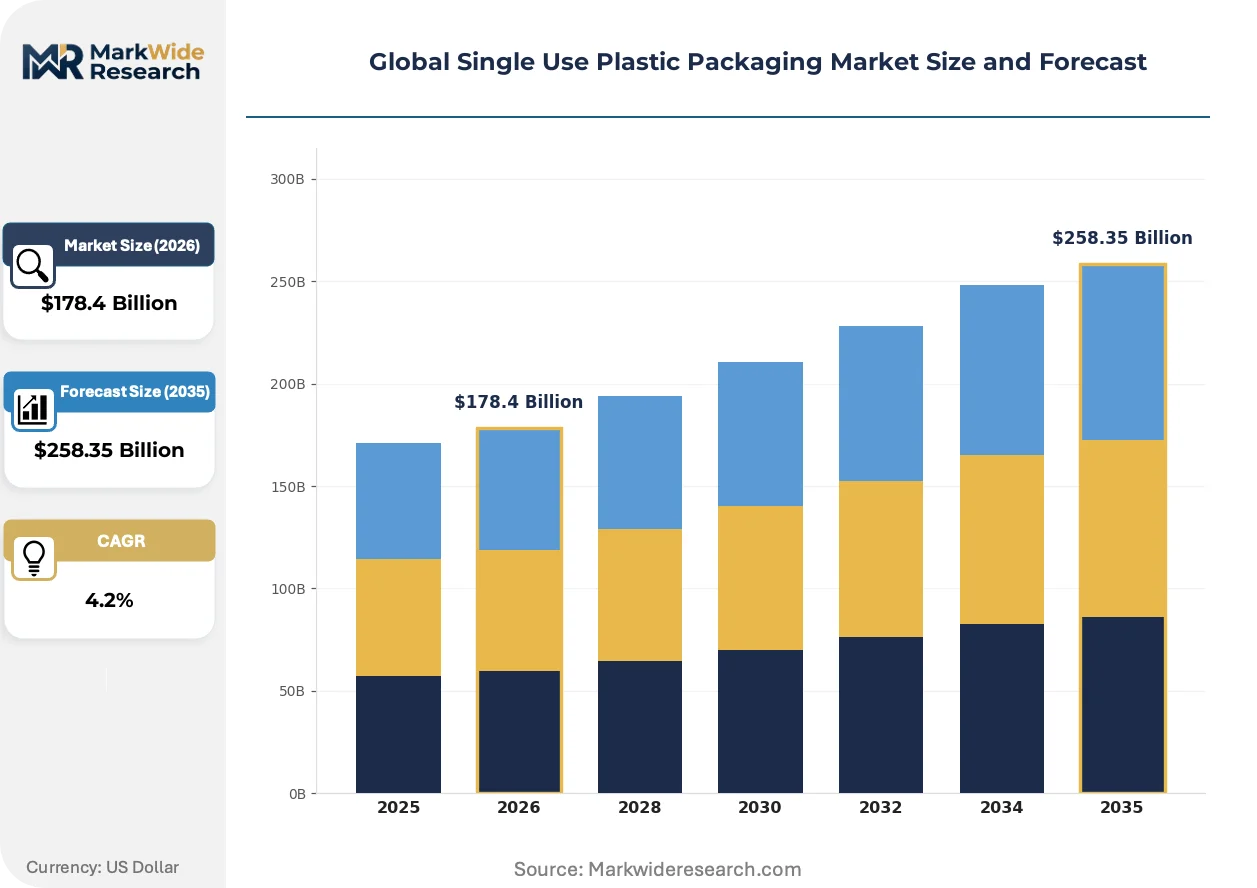
Market Dynamics
REACH substance restrictions and extended producer responsibility frameworks are forcing converters toward mono-material designs that simplify mechanical recycling streams, while divergent regional biodegradability standards create stranded asset risk in emerging markets lacking composting infrastructure.
Growth Catalysts
- Quick-service restaurant takeaway expansion:Food packaging applications are scaling as chains deepen penetration in India and Southeast Asia, driving thermoformed container demand for ready-to-eat meals.
- EU Green Deal compliance deadlines:Member states are accelerating material substitutions ahead of Packaging and Packaging Waste Regulation implementation, creating captive demand for certified alternatives.
- Healthcare sterilization requirements:FDA and EMA medical device packaging mandates preserve polymer dependence in pharmaceutical and diagnostic segments despite consumer-sector disposables backlash.
Market Restraints
- Resin supply concentration:Polypropylene and polystyrene feedstock availability clusters around Gulf Coast petrochemical complexes, exposing converters to hurricane-related disruption and price volatility.
- Industrial composting infrastructure gaps:ISO 18606 certification alignment without processing capacity in Brazil and Indonesia creates stranded asset risk for biodegradable packaging investments.
- Fiber substitution mandates:European food service channels face structural pressure from molded fiber alternatives as France and Germany advance single-use plastic bans in hospitality.
Strategic Opportunities
- India urban consumption deepening:FMCG distribution network expansion into tier-2 and tier-3 cities creates underpenetrated demand for flexible film sachets and pouches.
- Modified-atmosphere barrier innovation:Ethylene vinyl alcohol and polyamide coextrusion convergence enables extended shelf stability for fresh protein exports to Middle Eastern markets.
- China GB standards harmonization:SAMR food contact notification streamlining creates regulatory tailwind for multinational converters with distributed certification capabilities.
Industry Challenges
- Multi-jurisdiction certification timelines:ISO 18606, ASTM D6400, and EN 13432 divergent testing requirements extend product qualification cycles by 18-24 months for global suppliers.
- Legacy extrusion asset reconfiguration:Mechanical recycling stream compatibility demands capital-intensive retrofit of existing film lines for mono-material output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Single Use Plastic Packaging Market |
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $258.35 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Films, Containers, Trays, Cups, Straws Application: Food Packaging, Beverage Packaging, Healthcare Packaging, Personal Care Packaging, Electronics Packaging, Industrial Packaging End User: Food & Beverage Manufacturers, Pharmaceutical Firms, Cosmetic Producers, Electronics Suppliers, Chemical Vendors, Agricultural Firms Packaging Format: Flexible Packaging, Rigid Packaging, Blister Packaging, Vacuum Packaging, Pouch Packaging, Clamshell Packaging |
| Companies Covered | Amcor plc, Berry Global Inc., Huhtamaki Oyj, Sealed Air Corporation, Novolex, Dart Container Corporation, Sonoco Products Company, Mondi plc, DS Smith plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Single Use Plastic Packaging Market Shifts & Advancements
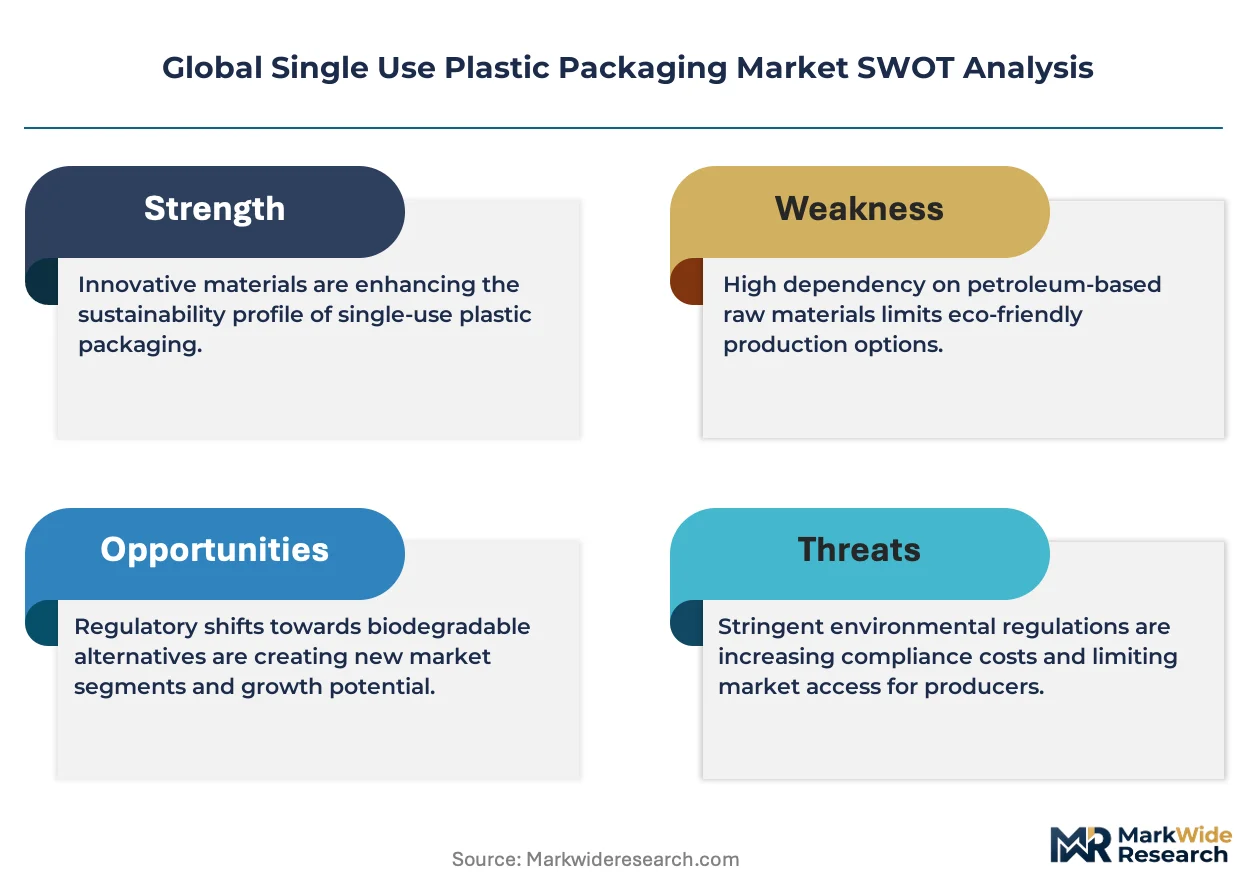
Active barrier coating technologies and digital printing integration are reshaping value capture in flexible formats, while regulatory fragmentation across FDA, REACH, and GB standards forces converters to maintain parallel certification portfolios.
Water-based and solvent-free adhesive lamination is fragmenting conventional solvent-bonded multilayer structures. Premium snack and confectionery brands in Germany and Japan are adopting these systems to eliminate volatile organic compound emissions. The shift is fragmenting incumbent converter margins by requiring capital-intensive coating line replacement while opening qualification windows for equipment specialists.
REACH Annex XVII substance restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorinated coatings from food contact applications by 2026. Paperboard converters serving European quick-service channels are accelerating plasma-deposited silicone oxide barrier trials. Frozen food and microwaveable tray segments face the steepest compliance cliffs, with reformulation costs concentrating among mid-tier suppliers lacking R&D scale.
Consolidated procurement by quick-service restaurant chains and retail private-label programs is compressing supplier switching cycles. Brand owners in the United States and United Kingdom are unbundling packaging specification from equipment supply, creating direct contracting relationships with film extruders. This disintermediation is most visible in fresh produce and bakery categories, where centralized buying desks now mandate recycled content thresholds independent of primary packaging machinery vendors.
Global Single Use Plastic Packaging Market Segmentation
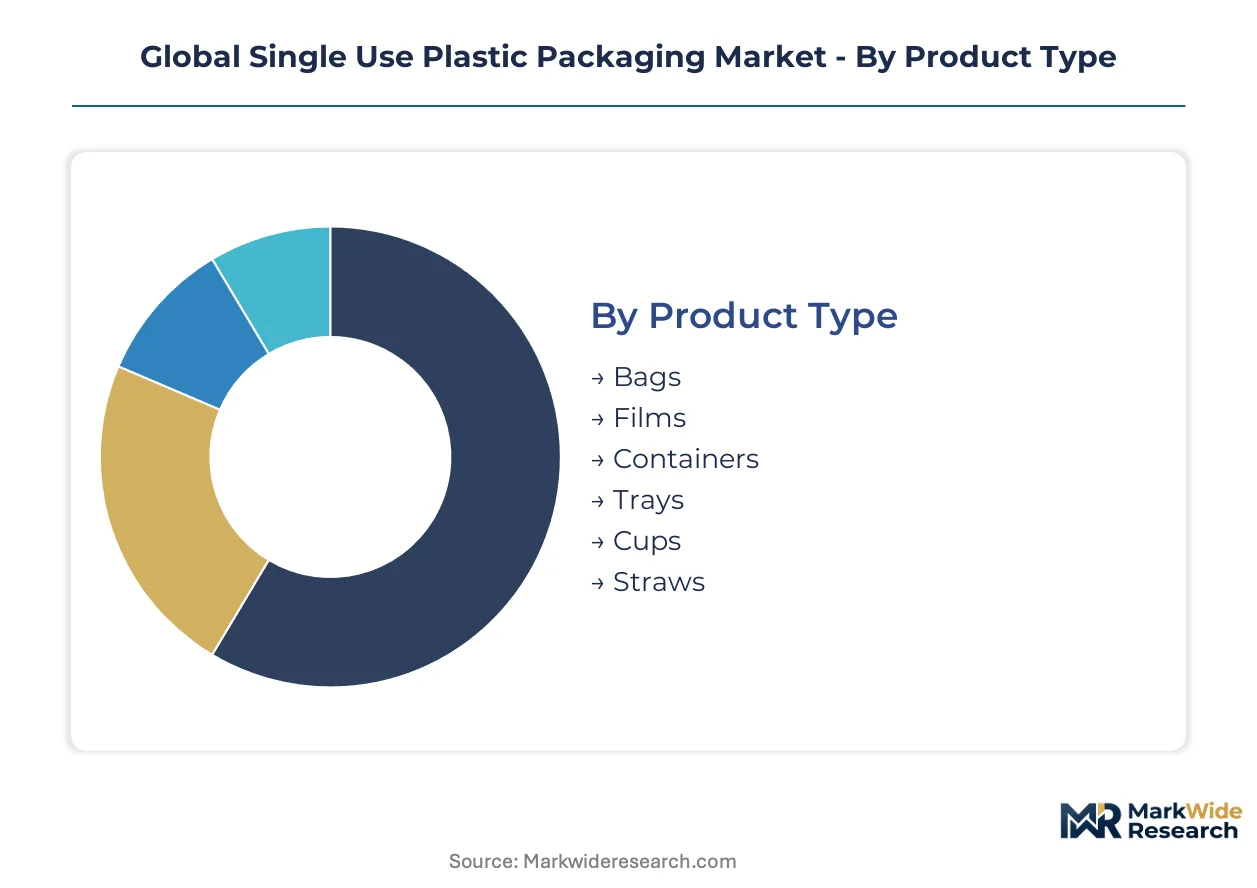
Segmentation in the Global Single Use Plastic Packaging Market reveals how regulatory pressure and channel economics reshape product mix across geographies. Understanding which formats flow through quick-service retail versus institutional procurement exposes where substitution risk and margin defense concentrate.
Product Type:
Channel mix varies sharply: films and bags dominate FMCG distribution networks, while containers and trays anchor food service takeaway operations.
- Films:Multilayer coextrusions of polyethylene terephthalate and ethylene vinyl alcohol deliver oxygen barrier performance below 0.1 cc/m²/day. Modified-atmosphere protein packaging in Germany and Japan drives specification tightening for extended shelf stability. By volume, films lead. By growth pace, trays are expanding most quickly.
- Containers:Thermoformed polypropylene and crystalline polyethylene terephthalate structures with wall thicknesses of 0.3-0.5 millimeters serve ready-to-eat meal applications. Quick-service restaurant chains in India are scaling container procurement as takeaway penetration deepens in tier-2 cities.
- Bags:Low-density polyethylene and linear low-density polyethylene variants handle dry grocery and produce containment through retail distribution.
- Trays:Injection-molded polystyrene and crystalline polyethylene terephthalate formats target frozen food and microwaveable segments facing fiber substitution mandates in France.
- Cups:Expanded polystyrene and polypropylene single-wall structures serve beverage and portion-control food applications.
- Straws:Polypropylene extrusions face structural decline from paper and polylactic acid alternatives in European hospitality channels.
By revenue contribution, films capture the largest share. By substitution vulnerability, straws face the steepest compression.
Application:
Cost tier stratification separates commodity food contact from regulated healthcare segments where sterilization requirements preserve polymer dependence.
- Food Packaging:Flexible films and thermoformed containers preserve perishable shelf stability across retail and food service channels. Quick-service takeaway expansion in Southeast Asia and India concentrates demand for cost-optimized barrier structures.
- Healthcare Packaging:Sterilizable polymer films and rigid trays for pharmaceutical and diagnostic applications face FDA and EMA device packaging mandates. Tyvek and medical-grade polyethylene maintain defensive positioning despite consumer-sector disposables backlash.
- Beverage Packaging:Cups, lids, and straws serve fountain drink and bottled water distribution with thinner-gauge specifications than food contact counterparts.
- Personal Care Packaging:Sachets and tubes for shampoo and lotion samples flow through hotel and airline amenity channels.
- Electronics Packaging:Antistatic films and clamshells protect components through distribution with conductivity-modified polymer grades.
- Industrial Packaging:Heavy-duty liners and drum inserts handle chemical and agricultural bulk containment.
Healthcare commands premium pricing tiers. Food packaging shows the steepest volume acceleration.
End User:
Customer type determines specification authority: multinational food manufacturers centralize procurement while pharmaceutical firms maintain captive packaging engineering.
- Food & Beverage Manufacturers:Consolidated buying desks at global quick-service chains and retail private-label programs now mandate recycled content thresholds independent of machinery vendors.
- Pharmaceutical Firms:Sterilization validation requirements and FDA food contact notification compliance preserve direct converter relationships for barrier film supply.
- Cosmetic Producers:Premium and mass-market beauty brands drive sachet and tube demand through travel retail and sampling programs.
- Electronics Suppliers:Component manufacturers specify antistatic and moisture barrier properties for semiconductor and display shipment.
- Chemical Vendors:Industrial bulk packaging demands chemical resistance and UN certification for hazardous material containment.
- Agricultural Firms:Seed and fertilizer packaging requires UV stability and moisture protection through extended storage cycles.
Pharmaceutical procurement maintains the longest qualification cycles. Food and beverage buying consolidation is compressing supplier switching timelines fastest.
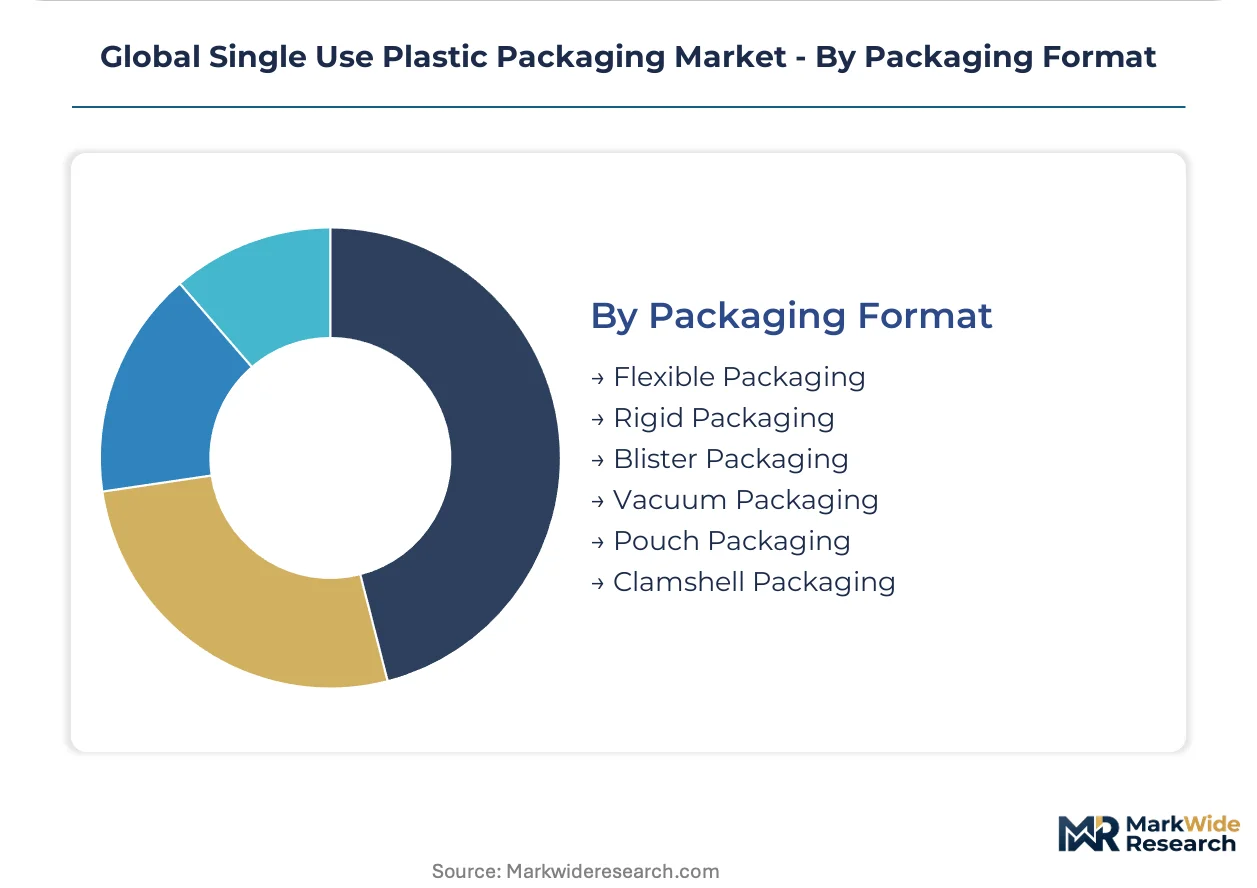
Packaging Format:
Supply concentration clusters around flexible film extrusion in Germany, China, and the US Gulf Coast, while rigid thermoforming distributes more broadly.
- Flexible Packaging:Rollstock films and pre-made pouches integrate active barrier coatings and digital printing for premium snack and confectionery brands in Germany and Japan. Water-based adhesive lamination is displacing solvent-bonded multilayer structures.
- Rigid Packaging:Thermoformed and injection-molded containers, trays, and cups serve food service and retail dairy applications. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorinated coatings by 2026.
- Blister Packaging:Form-fill-seal pharmaceutical and consumer goods formats combine rigid cavity structures with lidding foil.
- Vacuum Packaging:Barrier films with oxygen transmission rates below 1 cc/m²/day extend protein shelf life for export markets.
- Pouch Packaging:Stand-up and flat pouches replace rigid containers in liquid and dry food segments.
- Clamshell Packaging:Two-piece hinged structures protect electronics and produce with visual merchandising functionality.
Flexible formats dominate total output. Rigid packaging faces the most acute fiber substitution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal compliance deadlines and extended producer responsibility frameworks are redirecting investment toward certified alternative materials across major economies. Regional divergence in biodegradability standards and composting infrastructure availability creates uneven competitive terrain for converters.
United States
Quick-service restaurant chains are consolidating procurement for takeaway containers as drive-through penetration deepens in suburban markets. FDA food contact notification requirements preserve polymer dependence in healthcare sterilization applications. The US Gulf Coast petrochemical corridor anchors resin supply concentration, exposing converters to hurricane-related disruption cycles.
Germany
Modified-atmosphere barrier films for premium protein exports drive specification tightening among snack and confectionery brands. REACH Annex XVII substance restrictions on per- and polyfluoroalkyl substances eliminate grease-resistant fluorinated coatings from food contact applications by 2026. The Rhine-Ruhr industrial cluster hosts active barrier coating trials and water-based adhesive lamination pilots.
China
SAMR food contact notification streamlining creates regulatory tailwind for multinational converters establishing distributed certification capabilities. Dual carbon goals and GB standards harmonization pressure domestic suppliers toward mono-material designs. The Yangtze River Delta concentrates flexible film extrusion capacity serving FMCG distribution network expansion.
India
FMCG distribution networks are deepening penetration into tier-2 and tier-3 cities, creating underpenetrated demand for flexible film sachets and pouches. FSSAI compliance frameworks govern food contact applications as urban consumption accelerates. Maharashtra and Gujarat industrial corridors host thermoformed container capacity scaling for quick-service takeaway operations.
Brazil
ISO 18606 certification alignment without corresponding industrial composting infrastructure creates stranded asset risk for biodegradable packaging investments. ANVISA pharmaceutical packaging mandates preserve polymer dependence in sterilizable medical applications. The São Paulo industrial belt concentrates rigid thermoforming capacity serving regional food service channels.
Global Single Use Plastic Packaging Market Competitive Landscape
Player mix skews toward integrated multinational converters with distributed certification capabilities across FDA, REACH, and GB frameworks. Market structure concentrates around three to five global suppliers capable of sustaining parallel compliance portfolios simultaneously. Strategic archetypes include resin-integrated compounders bypassing third-party qualification delays, film extrusion specialists with captive barrier coating infrastructure, and molded fiber-alternative pioneers positioning ahead of European single-use directives. Dominant competitive moves center on mono-material line retrofits for mechanical recycling compatibility and geographic expansion into underpenetrated FMCG distribution networks.
Within the integrated multinational tier, Amcor plc and Berry Global Inc. represent archetypes of compliance-scale converters, while Huhtamaki Oyj occupies a position among fiber-alternative specialists. These entities exemplify how geographic origin and corporate structure map to strategic positioning: the Australian-domiciled limited company, the US-incorporated resin-integrated player, and the Finnish public limited company each anchor distinct competitive vectors without overlapping capability claims.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Novolex |
| Dart Container Corporation |
| Sonoco Products Company |
| Mondi plc |
| DS Smith plc |
| Others |
Supply & Pricing Matrix
Long-term resin offtake agreements with Gulf Coast petrochemical complexes lock in feedstock access and price visibility for converters serving quick-service restaurant chains, insulating tier-one suppliers from polypropylene spot volatility while exposing mid-tier players to hurricane-related disruption cycles.
Pricing Analysis
Certification level (ISO 18606, FDA food contact notification, REACH compliance) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects compliance burden and testing infrastructure investment. Cost compression in economy-tier flexible films is intensifying because Indian FMCG distributors are consolidating procurement around recycled-content thresholds. Quick-service restaurant chains show highest price sensitivity, while pharmaceutical sterilization packaging buyers accept premium positioning.
Supply Chain Analysis
Inventory cycles for ethylene vinyl alcohol barrier resins stretch 8-12 weeks due to limited global production nodes. Supply concentrates in Germany, China, and the US Gulf Coast for flexible film extrusion capacity, while rigid thermoforming distributes more broadly across India and Brazil. Raw material sourcing draws from polypropylene and polystyrene feedstock clusters, with polylactic acid alternatives emerging from Thailand and Nebraska pilot facilities. Single-source vulnerability in modified-atmosphere barrier coextrusion equipment creates qualification bottlenecks. Distribution runs through multinational converter direct contracts and regional distribution partners serving tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against molded fiber alternatives advancing through European food service channels. Incumbents must navigate fiber mandate timelines while preserving polymer-dependent healthcare margins.
For Market Incumbents: Secure ISO 18606 certification ahead of EU Packaging and Packaging Waste Regulation implementation to disqualify non-compliant competitors. Secure captive resin compounding capacity in India and Southeast Asia to bypass third-party qualification delays as FMCG distribution deepens. Molded fiber substitution in French and German hospitality channels threatens food service container margins; mono-material line retrofits for mechanical recycling compatibility defend positioning in retail flexible formats.
For New Entrants and Emerging Players: Regional biodegradability certification gaps in Brazil and Indonesia present white-space opportunities where ISO 18606-aligned suppliers lack local composting infrastructure partnerships. Tier-3 Indian cities remain underpenetrated for flexible film sachets as national brands expand distribution. Plasma-deposited silicone oxide barrier coating services for European paperboard converters facing REACH Annex XVII fluorinated coating bans offer a technical go-to-market angle distinct from commodity extrusion.
For Investors and Strategic Acquirers: Capital is best deployed toward resin-integrated compounders with distributed FDA, REACH, and GB certification capabilities. Long-term viability hinges on mechanical recycling stream compatibility rather than biodegradability certification alone. Acquisition target archetype: mid-tier flexible film extruders with underutilized barrier coating infrastructure in the Yangtze River Delta or Rhine-Ruhr corridor. The signal to watch is quick-service restaurant chain unbundling of packaging specification from equipment supply, which accelerates direct converter contracting and compresses intermediary margins.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material Line Retrofit | Mechanical recycling compatibility simplifies EPR compliance under EU Packaging and Packaging Waste Regulation. |
| Backward Integration into Resin Compounding | Captive polypropylene supply bypasses Gulf Coast disruption exposure and third-party qualification delays. |
| ISO 18606 Certification Investment | Accredited testing infrastructure disqualifies legacy converters from EU quick-service restaurant supply chains. |
| Plasma Barrier Coating Development | Silicone oxide deposition replaces fluorinated coatings eliminated by REACH Annex XVII substance restrictions. |
| India Distribution Network Expansion | Tier-2 and tier-3 city penetration captures FMCG sachet demand as urban consumption accelerates. |
Research Methodology
Operator-level perspectives from flexible film extrusion plant managers, quick-service restaurant procurement directors, pharmaceutical packaging engineers, and EPC contractors anchored the qualitative base. Secondary validation drew from FDA food contact notification databases, ECHA REACH substance restriction filings, SAMR GB standards harmonization notices, and customs records tracking resin trade flows. Bottom-up volume modeling across product types and applications triangulated with top-down macroeconomic drivers.
Sensitivity analysis tested forecast robustness against resin price volatility, regulatory timeline acceleration, and fiber substitution penetration rates. Segmentation dimensions modeled include packaging format (flexible, rigid, blister), application (food, healthcare, beverage), and regional regulatory cluster (EU Green Deal compliance, FDA notification, GB standards). CAGRs were derived from historical volume trajectories adjusted for substitution elasticity and channel penetration rates. Industry-specific inputs incorporated quick-service restaurant outlet expansion data and pharmaceutical sterilization packaging qualification cycles.
Forecasts assume regulatory continuity in EU REACH, FDA food contact, and China GB frameworks; material policy shifts would require re-modeling substitution timelines and certification alignment investments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
United States Plastic Bottles Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Indonesia Plastic Packaging Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Plastic-Based Egg Packaging Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market