
 US Lubricant Contaminated HDPE Container Waste Market | 2026-2036
US Lubricant Contaminated HDPE Container Waste Market Size, Share, and Industry Trends Forecast 2026-2036
US Lubricant Contaminated HDPE Container Waste Market Intelligence
Container reclamation networks are tilting toward regional hub-and-spoke models that consolidate contaminated HDPE from dispersed automotive and industrial generators. Greif, Inc. anchors Gulf Coast collection through its industrial packaging footprint, while Mauser Group B.V. competes via closed-loop reconditioning systems for lubricant drums. Consolidated Container Company specializes in post-consumer resin recovery, extending its position across Midwest manufacturing corridors.
US lubricant contaminated HDPE container waste comprises high-density polyethylene vessels—typically 15–55 gallon drums and 5-gallon pails—retaining residual petroleum-based or synthetic lubricant fractions after primary use, with contamination levels often exceeding 1% by weight that disqualify standard mechanical recycling. These containers require thermal treatment, solvent washing, or energy recovery pathways to recover polymer value or destroy hazardous constituents. Drum formats dominate volume flows due to industrial lubricant consumption patterns, while recycling as a waste management method captures the largest share of value recovery as reprocessors develop advanced decontamination protocols. Automotive industry application represents the fastest-expanding segment as vehicle service intervals generate rising drum retirement rates.
EPA RCRA subtitle C standards govern hazardous waste determination for lubricant residues, while OSHA workplace exposure limits affect container handling protocols, and state environmental agencies in California and Texas impose supplemental manifesting requirements that shape interstate waste movement. The regulatory stack is forcing generators toward certified waste management providers rather than informal disposal channels. Stakeholders must monitor emerging state legislation on post-consumer resin mandates that could redirect contaminated HDPE streams from energy recovery to mechanical recycling investments.
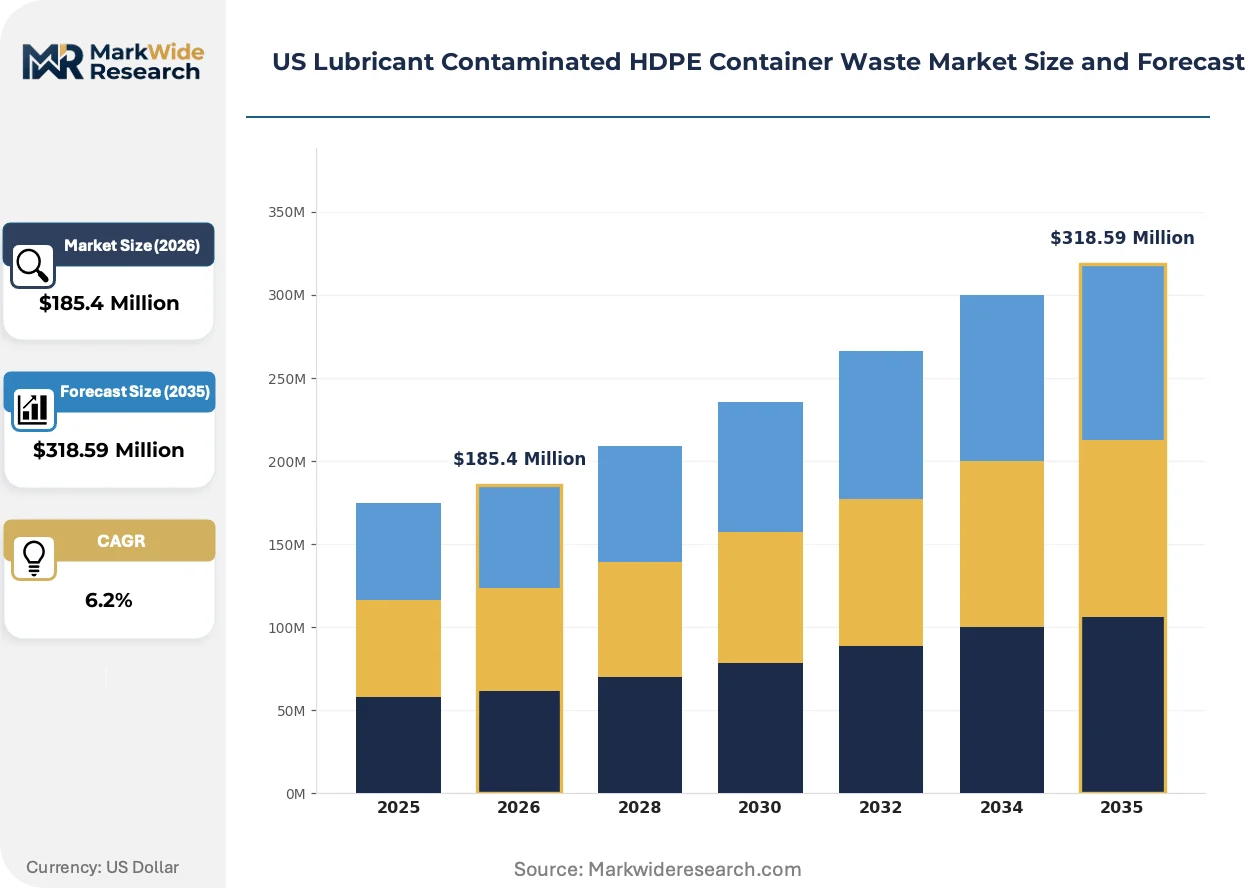
Market Dynamics
State-level extended producer responsibility frameworks are forcing automotive service centers and industrial generators toward certified waste management providers, consolidating collection volumes into regional hub-and-spoke networks anchored by Gulf Coast reprocessing infrastructure.
Growth Catalysts
- Automotive service center expansion:Rising vehicle service intervals generate accelerating drum retirement rates across quick-lube chains and independent repair shops, concentrating contaminated HDPE flows.
- RCRA subtitle C enforcement:EPA hazardous waste determinations for lubricant residues tighten disposal standards and disqualify informal channels, driving formal sector capture.
- Solvent washing technology maturation:Advanced decontamination protocols now recover polymer value from containers exceeding 1% contamination by weight, expanding mechanically recyclable feedstock pools.
Market Restraints
- Energy recovery pathway economics:Cement kiln co-processing and waste-to-energy facilities compete for contaminated HDPE streams, capping mechanical recycling margins when oil prices fluctuate.
- Gulf Coast infrastructure concentration:Reprocessing capacity clusters near Houston and Port Arthur, creating logistics cost penalties for generators in the Midwest and Northeast.
- Residual lubricant characterization complexity:Synthetic and bio-based lubricant fractions require distinct thermal treatment profiles, fragmenting process standardization.
Strategic Opportunities
- Midwest manufacturing corridor penetration:Post-consumer resin recovery investments in Ohio and Michigan could capture dispersed industrial generator volumes currently routed to energy recovery.
- Post-consumer resin mandates:Emerging California and New York legislation may redirect contaminated HDPE from thermal destruction to mechanical recycling through content requirements.
- Closed-loop drum leasing convergence:Integration of IoT tracking with reconditioning systems enables usage-based pricing and asset recovery for lubricant distributors.
Industry Challenges
- Hazardous materials handling certification timelines:OSHA workplace exposure compliance and DOT transport credentials create workforce entry barriers that slow collection network scaling.
- Legacy manifesting system integration:Generator ERP platforms require custom API development to interface with EPA biennial reporting and state supplemental tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Lubricant Contaminated HDPE Container Waste Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $318.59 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Drum, Pail, Bottle, Can Waste Management Method: Recycling, Incineration, Landfill, Treatment End of Life Solution: Refurbishment, Reprocessing, Disposal, Reuse Industry Application: Manufacturing, Automotive, Construction, Agriculture |
| Companies Covered | Consolidated Container Company, Nye Lubricants, Inc., Scholle IPN Corporation, Greif, Inc., Martin Operating Partnership L.P., Mauser Group B.V., Milford Barrel, BWAY Corporation, Rahway Steel Drum Company, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Lubricant Contaminated HDPE Container Waste Market Strategic Shifts & Innovations
Decontamination technology maturation and regulatory data integration are compressing cost structures and traceability gaps across the value chain, reshaping how generators select waste management partners.
Advanced solvent washing systems employing supercritical CO2 extraction are digitizing contamination characterization workflows, enabling real-time residue profiling that matches containers to optimal recovery pathways. Automotive fleet maintenance divisions are piloting these systems at high-volume service centers in Texas. The technology is digitizing drum-sorting decisions that previously relied on visual inspection, compressing processing costs and expanding mechanically recyclable throughput.
EPA's e-Manifest system mandates electronic tracking of hazardous waste shipments, replacing paper documentation that created compliance gaps and enforcement friction. Industrial lubricant distributors must now integrate manifest data into their enterprise systems or face audit exposure. Automotive service center chains operating across state lines face the steepest adaptation costs as they reconcile EPA standards with California and Texas supplemental reporting requirements.
Generator procurement of waste management services is compressing contract cycles from annual to quarterly reviews, with sustainability scorecards displacing price-only selection criteria. Large automotive dealership groups and manufacturing plants now require certified post-consumer resin recovery rates in vendor agreements. This behavioral shift is most pronounced in California, where brand sustainability commitments and state procurement guidelines reinforce preference for mechanical recycling over energy recovery pathways.
US Lubricant Contaminated HDPE Container Waste Market Segmentation
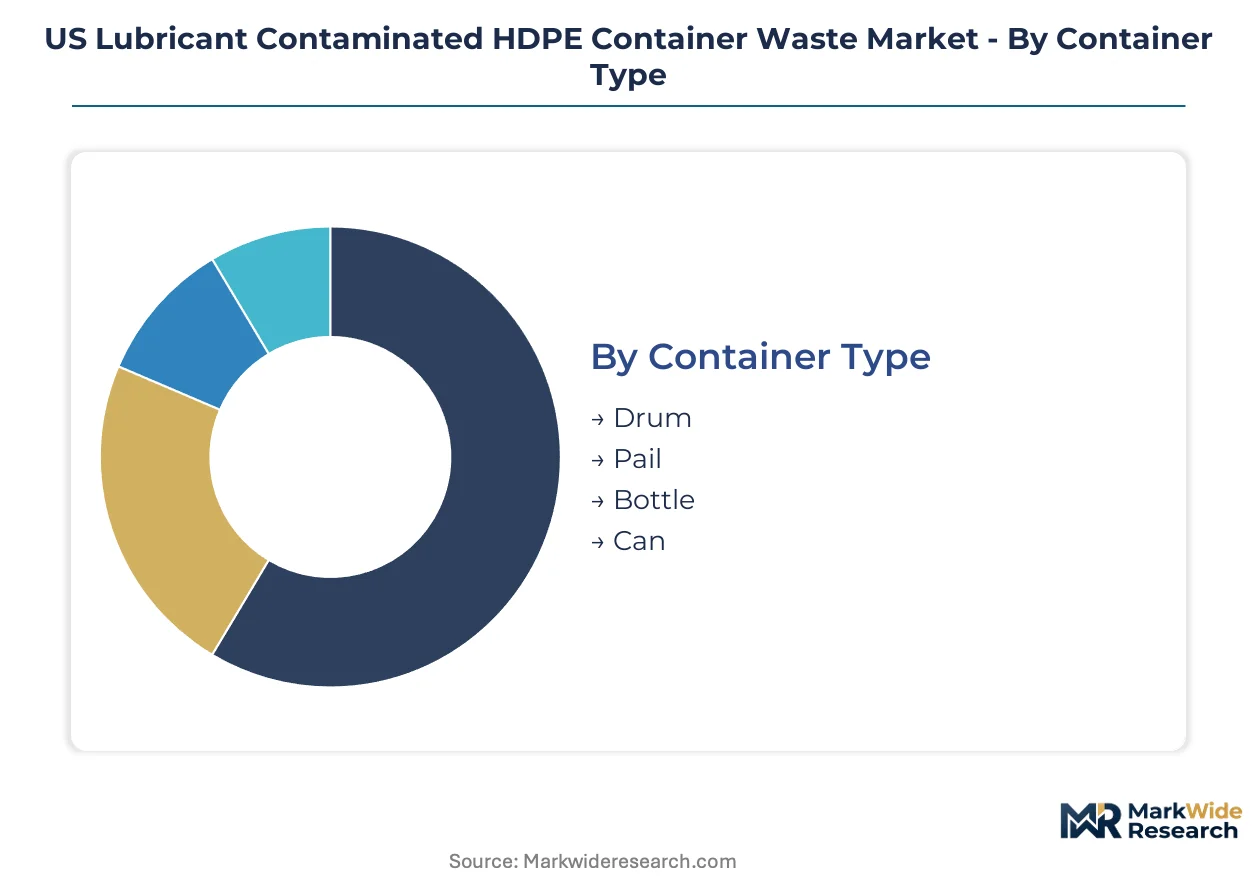
Segmentation in contaminated HDPE container waste reveals distinct velocity profiles across container formats and recovery pathways. Cycle times vary dramatically—automotive service drums retire within months while industrial pails persist for years, reshaping collection logistics and reprocessing investment priorities.
Container Type:
Drum formats exhibit the shortest replacement cycles in high-throughput automotive environments, while smaller containers turn over more slowly in intermittent-use industrial settings.
- Drum:Standard 15–55 gallon cylindrical vessels dominate lubricant bulk distribution to manufacturing and fleet maintenance operations. Gulf Coast automotive service centers generate concentrated retirement volumes as quick-lube chains standardize 55-gallon collection protocols.
- Pail:Five-gallon open-head containers serve machine shop and construction equipment lubrication needs with moderate turnover frequency. Ohio and Michigan manufacturing corridors accumulate pail waste in dispersed patterns that challenge hub-and-spoke collection economics.
- Bottle:One-quart to one-gallon retail formats accompany consumer automotive oil sales with extended residence times in household garages.
- Can:Aerosol and specialty lubricant packaging represents minimal volume contribution with complex multi-material construction barriers to mechanical recycling.
Drum formats anchor the volume base while pail applications gain share at the steepest rate as Midwest manufacturing intensifies used oil collection mandates.
Waste Management Method:
Cost tier differentiation separates capital-intensive thermal treatment from lower-barrier disposal pathways, with regulatory enforcement compressing informal channel viability.
- Recycling:Mechanical reprocessing and solvent washing recover polymer value from decontaminated HDPE feedstock. EPA RCRA subtitle C compliance investments now enable processors to handle containers exceeding 1% residual contamination, expanding addressable feedstock pools for Gulf Coast reprocessors.
- Incineration:Cement kiln co-processing and waste-to-energy facilities destroy hazardous constituents while recovering thermal value. Energy recovery competes aggressively for contaminated streams when oil price volatility elevates alternative fuel economics.
- Landfill:Subtitle C hazardous waste landfill disposal serves containers failing characterization thresholds or lacking transport economics to recovery facilities.
- Treatment:Stabilization and chemical fixation address specific contaminant profiles before final disposal.
Recycling commands premium positioning among sustainability-focused generators while incineration retains volume dominance in price-sensitive segments.
End of Life Solution:
Application maturity varies across refurbishment infrastructure density, with closed-loop systems concentrating in lubricant distributor networks.
- Refurbishment:Reconditioning extends drum service life through cleaning, dent removal, and lining replacement. Mauser Group and Greif operate closed-loop leasing systems that capture automotive service center volumes through usage-based pricing models.
- Reprocessing:Post-consumer resin recovery grinds and pelletizes decontaminated HDPE for secondary manufacturing applications. Consolidated Container Company scales Midwest reprocessing capacity to reduce Gulf Coast logistics penalties.
- Disposal:Terminal destruction pathways serve containers failing recovery economics or regulatory compliance thresholds.
- Reuse:Direct second-use applications without formal reconditioning face declining viability under OSHA workplace exposure and DOT transport regulations.
Refurbishment retains margin leadership in closed-loop contracts while reprocessing expands most quickly under emerging post-consumer resin mandates.
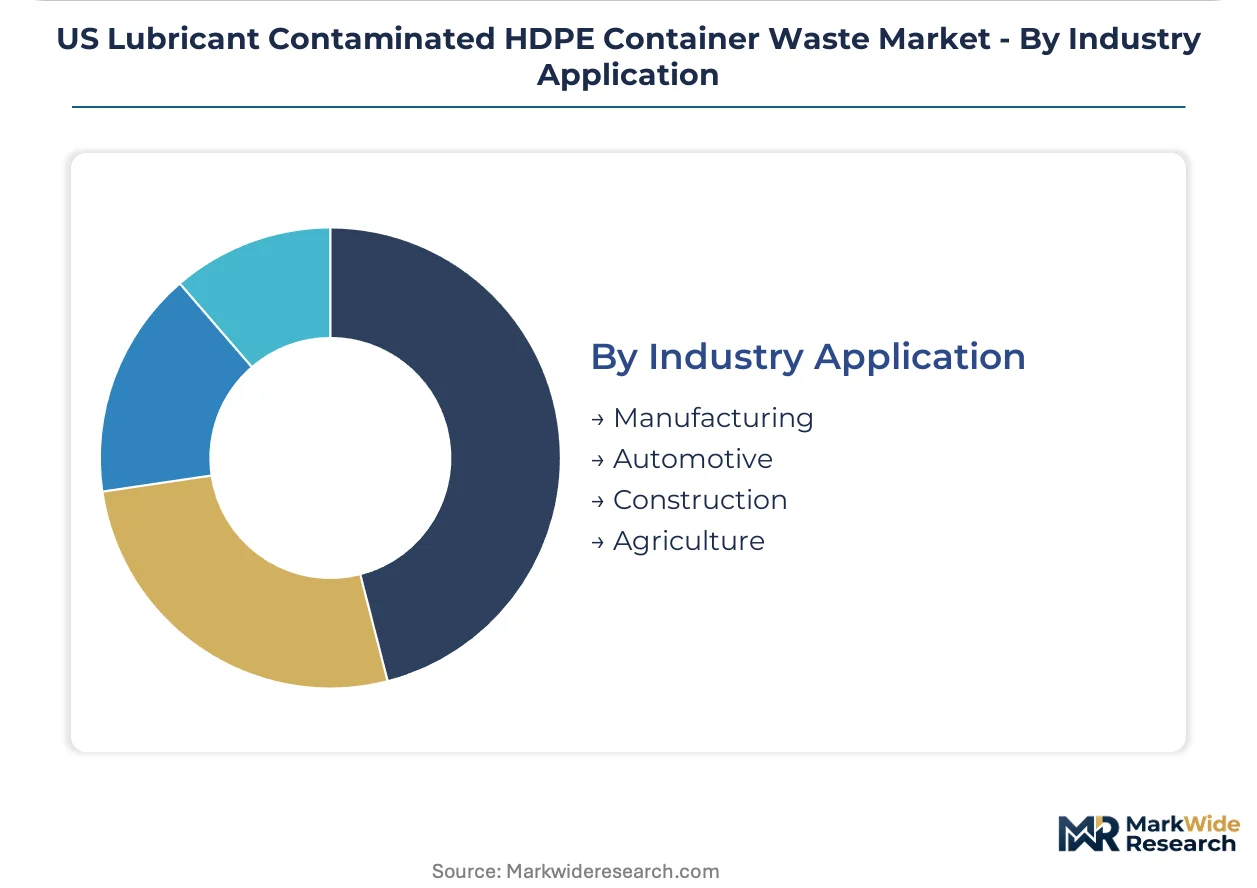
Industry Application:
Customer type concentration determines collection route density, with automotive service networks offering superior logistics efficiency versus dispersed industrial generators.
- Automotive:Vehicle service intervals generate predictable drum retirement across dealership, quick-lube, and independent repair channels. California and Texas quick-lube chains consolidate volumes through national waste management contracts that specify certified recycling rates.
- Manufacturing:Plant-based lubrication systems produce heterogeneous waste streams with variable contamination profiles. Ohio automotive parts manufacturers and Michigan metalworking operations generate pail-dominant waste with intermittent collection scheduling.
- Construction:Mobile equipment lubrication creates geographically dispersed retirement patterns with seasonal volume fluctuation.
- Agriculture:Farm equipment maintenance generates low-density rural waste with challenging transport economics to regional hubs.
Automotive applications anchor the volume base while manufacturing segments gain share at the steepest rate as industrial extended producer responsibility frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel pipeline network and Port Arthur rail intermodal terminals anchor Gulf Coast reprocessing infrastructure, concentrating decontamination capacity within a 200-mile corridor that handles the majority of national contaminated HDPE drum flows.
Gulf Coast
Texas and Louisiana quick-lube chains generate concentrated 55-gallon drum retirement volumes through standardized collection protocols. EPA Region 6 RCRA enforcement mandates electronic manifesting for cross-state waste movement. Houston petrochemical complexes host solvent washing facilities that process containers exceeding 1% residual contamination thresholds.
Midwest
Ohio automotive parts manufacturers and Michigan metalworking operations produce pail-dominant waste streams with intermittent collection scheduling. State environmental agencies in Illinois and Indiana impose supplemental manifesting requirements that shape interstate routing decisions. Consolidated Container Company scales post-consumer resin recovery capacity across Ohio and Michigan to reduce Gulf Coast logistics penalties.
California
Quick-lube chains operating under national waste management contracts specify certified recycling rates above state minimums. CalRecycle extended producer responsibility frameworks tighten disposal standards for automotive service centers. Los Angeles Basin and Central Valley service centers consolidate volumes through hub-and-spoke networks anchored by rail-served reprocessors.
Southeast
Florida and Georgia dealership groups generate predictable drum retirement across high-throughput maintenance bays. State environmental agencies require hazardous waste determination for synthetic lubricant residues before transport authorization. Atlanta distribution corridors channel contaminated containers to Gulf Coast thermal treatment facilities via intermodal rail.
Northeast
New York and New Jersey manufacturing plants produce heterogeneous waste streams with variable contamination profiles. Emerging state legislation on post-consumer resin content mandates redirects streams from energy recovery toward mechanical recycling investments. Port Newark container terminals handle import drum flows that supplement domestic retirement volumes.
US Lubricant Contaminated HDPE Container Waste Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in reconditioning and resin recovery. The vendor base organizes around three functional layers: closed-loop leasing operators, post-consumer resin processors, and hazardous waste logistics providers. Two dominant competitive moves are reshaping positioning: Gulf Coast processors are expanding solvent washing capacity to capture mechanically recyclable feedstock pools, while Midwest operators are building regional grinding and pelletizing infrastructure to reduce transport cost penalties.
Within the closed-loop leasing tier, Greif, Inc. and Mauser Group B.V. occupy positions that exemplify asset-light drum management models, while Consolidated Container Company anchors the post-consumer resin recovery segment with reprocessing investments across Ohio and Michigan manufacturing corridors.
| Leading Market Players |
|---|
| Consolidated Container Company |
| Nye Lubricants, Inc. |
| Scholle IPN Corporation |
| Greif, Inc. |
| Martin Operating Partnership L.P. |
| Mauser Group B.V. |
| Milford Barrel |
| BWAY Corporation |
| Rahway Steel Drum Company, Inc. |
| Others |
Cost & Logistics Intelligence
Houston petrochemical corridor capacity expansions compress regional collection premiums while elevating transport cost penalties for Midwest generators seeking Gulf Coast reprocessing slots. EPA RCRA subtitle C compliance investments now separate certified processors from informal channels, with automotive service center chains absorbing tiered pricing spreads based on manifesting automation and post-consumer resin recovery guarantees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments generator contracts by contamination characterization rigor and recovery pathway certification. Premium tiers command spreads for solvent-washed mechanical recycling with verified post-consumer resin output, while economy tiers route to cement kiln co-processing when oil price volatility elevates alternative fuel economics. Price differentiation hinges on EPA e-Manifest integration depth and state supplemental reporting automation. Cost compression in standard-tier collection is intensifying because quick-lube chains consolidate national volumes through reverse-auction procurement platforms. Independent automotive repair shops exhibit highest price sensitivity; lubricant distributors with closed-loop leasing contracts show least.
Supply Chain Analysis
Extended payment terms from Gulf Coast reprocessors to automotive waste aggregators stretch working capital cycles, with supply-chain finance facilities emerging to bridge manifest-to-settlement gaps. Geographic supply concentration centers on Texas, Louisiana, and Ohio, where reprocessing infrastructure clusters near Houston, Port Arthur, and emerging Midwest grinding capacity. Raw material flows draw from dispersed automotive service centers, manufacturing plant lubrication systems, and construction equipment maintenance yards. Single-source vulnerability concentrates in Houston Ship Channel solvent washing facilities handling containers exceeding 1% residual contamination. Distribution runs through hub-and-spoke networks anchored by rail-served reprocessors, with drayage costs penalizing Northeast and rural agricultural generators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as state-level extended producer responsibility frameworks splinter compliance requirements, creating niche specialization openings for regional processors mastering California manifesting automation or Midwest pail-dominant collection logistics.
For Market Incumbents: Insulate core Gulf Coast positioning through backward integration into solvent washing technology licensing, while capturing Midwest pail volumes before Consolidated Container Company's resin recovery scale advantages harden. Threat substitution looms from energy recovery pathways when oil price spikes elevate cement kiln co-processing economics. Capacity addition in Ohio and Michigan manufacturing corridors represents the priority defensive lever. For New Entrants and Emerging Players: Establish a beachhead in Ohio and Michigan pail-dominant waste streams, where dispersed industrial generator patterns currently route to energy recovery due to Gulf Coast logistics penalties. The most penetrable segment sits in automotive parts manufacturing plants seeking certified post-consumer resin recovery rates for sustainability scorecards. Go-to-market angle: IoT-enabled drum tracking integrated with reconditioning workflows that match Mauser Group's closed-loop pricing models. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity arbitrage play because EPA RCRA enforcement tightening and state post-consumer resin mandates compound compliance moats for integrated processors. Acquisition target archetype: Midwest reprocessors with solvent washing permits and rail siding access. Signal to watch: California and New York post-consumer resin content legislation triggering feedstock competition between mechanical recycling and energy recovery pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Solvent washing investments near Houston capture mechanically recyclable feedstock pools from automotive chains. |
| Backward Integration | Reprocessors acquiring drum collection fleets compress hub-and-spoke logistics costs for Midwest generators. |
| Long-term Supply Agreement | National quick-lube contracts specifying certified recycling rates lock feedstock commitments against energy recovery competition. |
| Joint Venture | Partnerships between Gulf Coast processors and Ohio resin compounders reduce transport penalties for pail-dominant streams. |
| Green Certification Program | Post-consumer resin recovery accreditation aligns vendor selection with California procurement sustainability scorecards. |
Research Approach
A standing panel of waste management operations directors, automotive service center procurement leads, EPA compliance officers, and reprocessing plant managers provided ongoing calibration across quarterly update cycles. Primary interview data triangulated against secondary sources including EPA biennial report filings, state environmental agency manifesting databases, RCRA hazardous waste tracking systems, and customs records for import drum flows. Bottom-up generator volume estimates from quick-lube chains and manufacturing facilities converged with top-down capacity assessments of Gulf Coast and Midwest reprocessing infrastructure.
Scenario-bracketing framed low, base, and high cases across oil price volatility bands and post-consumer resin mandate adoption timelines. Segmentation dimensions modeled encompass container format, waste management method, end-of-life solution, and industry application, with geographic clustering by state regulatory framework intensity. CAGRs derived from installed reprocessing capacity utilization curves and automotive service center drum retirement rate projections. Industry-specific inputs incorporated solvent washing technology maturation curves and EPA e-Manifest adoption penetration rates.
Stress conditions across oil price bands, RCRA enforcement intensity gradients, and post-consumer resin mandate rollout speeds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reprocessing capacity expansion timelines and automotive service interval trends. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
GCC Plastic Packaging Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
Cast Films Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
Saudi Arabia Plastic Packaging Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Global Molded Plastic Packaging Market
Plastic Packaging
Blow Molded Bottles Market