
 Blow Molded Bottles Market | 2026-2036
Blow Molded Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Blow Molded Bottles Market Outlook
Subscription-based packaging-as-a-service contracts is broadening how converters monetize bottle supply beyond unit sales. Berry Global leverages its North American manufacturing footprint to anchor long-term beverage supply agreements. ALPLA specializes in embedded recycling systems that sustain closed-loop resin flows for major brand owners.
Blow molded bottles are hollow thermoplastic containers formed by extruding or injecting a parison into a mold cavity, then inflating it with compressed air to achieve wall thicknesses typically between 0.25 mm and 1.5 mm, serving primarily as liquid storage and dispensing vessels across consumer and industrial supply chains. The petroleum-based segment dominates current volume owing to cost parity and processing consistency, while biodegradable alternatives occupy niche premium positioning where compostability commands shelf-space differentiation. Recycled plastic grades are capturing the fastest expansion trajectory as post-consumer rPET supply chains mature and brand sustainability commitments harden into procurement mandates.
The US FDA and EPA jointly govern food-contact safety and recycled material pathways, while the EU REACH framework and Single-Use Plastics Directive impose material composition thresholds and extended producer obligations that reshape converter investment priorities. China's SAMR enforces national food-contact standards that limit import flexibility for non-compliant resin streams. Stakeholders must monitor how fragmented national recycling infrastructure buildouts alter regional resin cost curves and bottle specification divergence.
Market Dynamics
Lightweight PET container specifications are compressing resin throughput per unit while EU Single-Use Plastics Directive mandates force material transitions toward recycled content, creating simultaneous pull and push forces across converter operations.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled content thresholds are pulling rPET capacity investments from German packaging converters serving branded-goods clients.
- Beverage bottler procurement:Lightweight container specifications are expanding order volumes for reduced-wall-thickness PET designs across carbonated and still water categories.
- Embedded recycling systems:Closed-loop resin flow technologies are sustaining post-consumer feedstock quality for converters with captive collection infrastructure.
Market Restraints
- rPET feedstock cost volatility:Post-consumer bale prices swing with collection infrastructure gaps in fragmented national recycling systems.
- Food-contact regulatory friction:China's SAMR national standards limit import flexibility for non-compliant resin streams, constraining sourcing options.
- Biodegradable substitution ceiling:Compostable alternatives face processing inconsistency and limited industrial composting facility access.
Strategic Opportunities
- Packaging-as-a-service contracts:Subscription monetization models are opening recurring revenue streams beyond unit sales for converters with integrated logistics capabilities.
- REACH framework alignment:EU extended producer responsibility schemes are rewarding converters with verified recycled material traceability systems.
- Pharmaceutical barrier bottles:Oxygen-scavenging multilayer designs are penetrating prescription and over-the-counter drug packaging with stringent stability requirements.
Industry Challenges
- Food-contact safety certification timelines:US FDA and EPA joint oversight of recycled material pathways extends qualification periods for new rPET sources.
- Blow molding technician scarcity:Specialized parison programming and mold-tuning expertise is concentrating among aging workforces without systematic training pipelines.
- Legacy equipment retrofit complexity:Existing extrusion lines require substantial modification to process higher recycled content ratios without quality degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blow Molded Bottles Market |
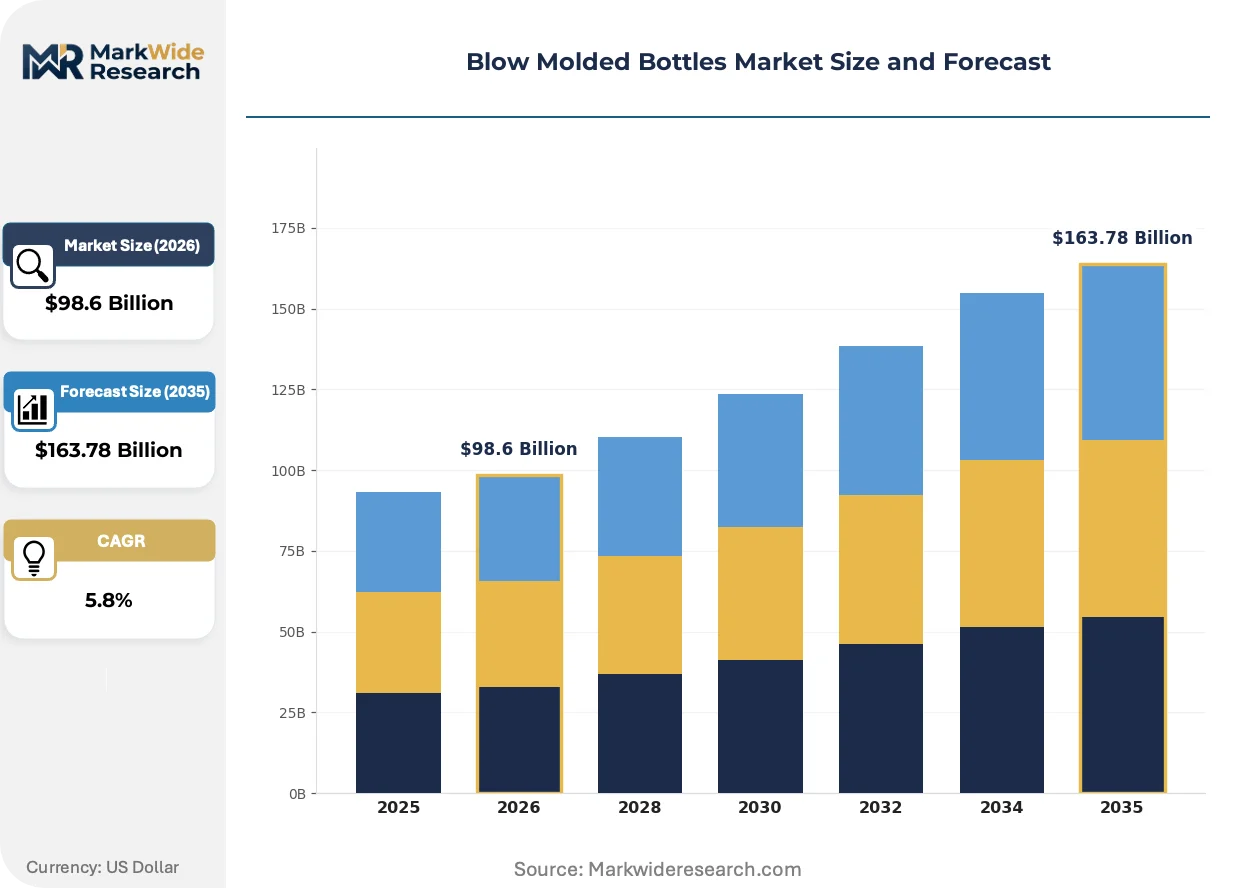
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $163.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Petroleum-Based, Biodegradable, Recycled Plastic, Others End User: Pharmaceuticals, Beverages, Household Products, Personal Care Shape: Cylindrical, Square, Rectangular, Custom Closure Type: Screw Cap, Flip-top, Pump Dispenser, Others |
| Companies Covered | Amcor plc, Berry Global, Graham Packaging, Alpha Packaging, Plastipak Holdings, ALPLA, Comar, Sidel, Altium Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blow Molded Bottles Market Strategic Shifts
Digital manufacturing controls and material traceability systems are converging to enable mass customization at scale, while regulatory pressure on carbon intensity accelerates process electrification across converter floors.
All-electric blow molding machinery is modularizing production floor layouts by eliminating hydraulic fluid systems and reducing energy draw per cavity. Mid-sized beverage converters in North America and Western Europe are adopting these platforms fastest, driven by Scope 3 emissions accounting requirements from multinational brand owners. The technology is modularizing how converters scale capacity—adding discrete machine cells rather than rebuilding centralized hydraulic plants.
EU REACH framework amendments on polymer registration are tightening disclosure requirements for additives and processing aids in food-contact applications. German and French converters face accelerated testing obligations for novel barrier coatings and colorants. Small-to-mid tier suppliers without in-house regulatory affairs functions are outsourcing compliance verification to specialized consultancies, concentrating certification capacity.
Direct-to-brand procurement contracts are compressing distributor roles in bottle supply chains. Large beverage and personal care multinationals are establishing preferred supplier frameworks with tier-one converters, bypassing traditional packaging distributors. This pattern is most visible in Germany and the US, where branded-goods procurement teams have built dedicated packaging category management functions with technical specification authority.
Blow Molded Bottles Market Segmentation
Blow molded bottles serve divergent functional requirements across liquid containment applications, from carbonated beverage pressure resistance to pharmaceutical oxygen barrier needs. Segmentation reveals how material selection, end-use performance standards, and dispensing ergonomics shape converter specialization and procurement patterns.
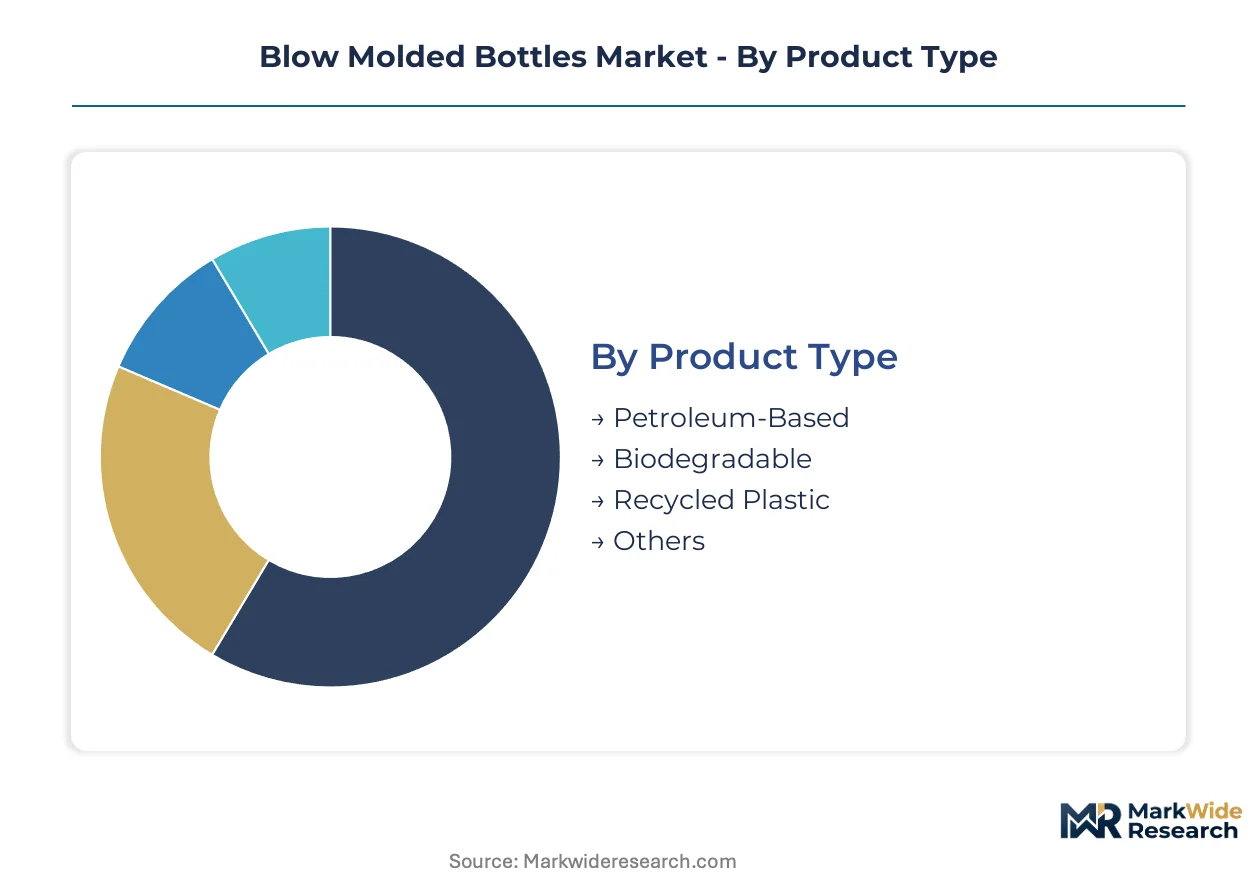
Product Type:
Cost tier separates commodity converters from premium sustainability suppliers in resin sourcing strategies.
- Petroleum-Based:Virgin PET and HDPE formulations deliver consistent melt flow indices and barrier properties for high-speed rotary blow molding lines. Beverage bottlers in Germany and the US specify these grades for carbonated soft drink containers where wall thickness uniformity prevents burst failure under internal pressure.
- Recycled Plastic:Post-consumer rPET flakes undergo super-cleaning and solid-state polymerization to achieve food-contact purity for beverage applications. EU Single-Use Plastics Directive mandates are pulling capacity investments from German packaging converters serving Coca-Cola and PepsiCo supply agreements.
- Biodegradable:PLA and PHA blends target premium personal care segments where industrial composting certification commands shelf-space differentiation.
- Others:Bio-based PET from sugarcane ethanol serves niche carbon-neutral positioning for bottled water brands.
Petroleum-based grades lead volumes today; recycled plastic is gaining share fastest.
End User:
Application-specific performance requirements dictate barrier technology investments and regulatory compliance burdens.
- Beverages:Carbonated and still water categories drive lightweight PET specifications with reduced wall thicknesses, compressing resin throughput per unit while maintaining top-load strength for palletized distribution.
- Pharmaceuticals:Oxygen-scavenging multilayer bottles with EVOH barriers protect prescription drug stability against oxidative degradation. FDA 21 CFR compliance timelines extend qualification periods for new converter entrants.
- Personal Care:Shampoo and conditioner bottles prioritize ergonomic grip geometry and pump dispenser compatibility over barrier performance.
- Household Products:Bleach and cleaning chemical containers require fluorinated HDPE for permeation resistance.
Beverage applications dominate unit volumes; pharmaceutical barrier bottles are expanding most quickly.
Shape:
Volume efficiency in shipping and retail shelf utilization differentiates converter design capabilities.
- Cylindrical:Standard round profiles optimize blow molding material distribution and withstand internal pressure from carbonated beverages.
- Square:Rectangular cross-sections maximize pallet cube utilization for still water distribution, though corner stress concentration requires thicker wall sections.
- Rectangular:Flat-panel designs suit personal care labels requiring 360-degree graphic presentation.
- Custom:Proprietary silhouettes serve brand differentiation for premium spirits and cosmetic positioning.
Cylindrical formats anchor production volumes; square configurations are climbing fastest among water bottlers.
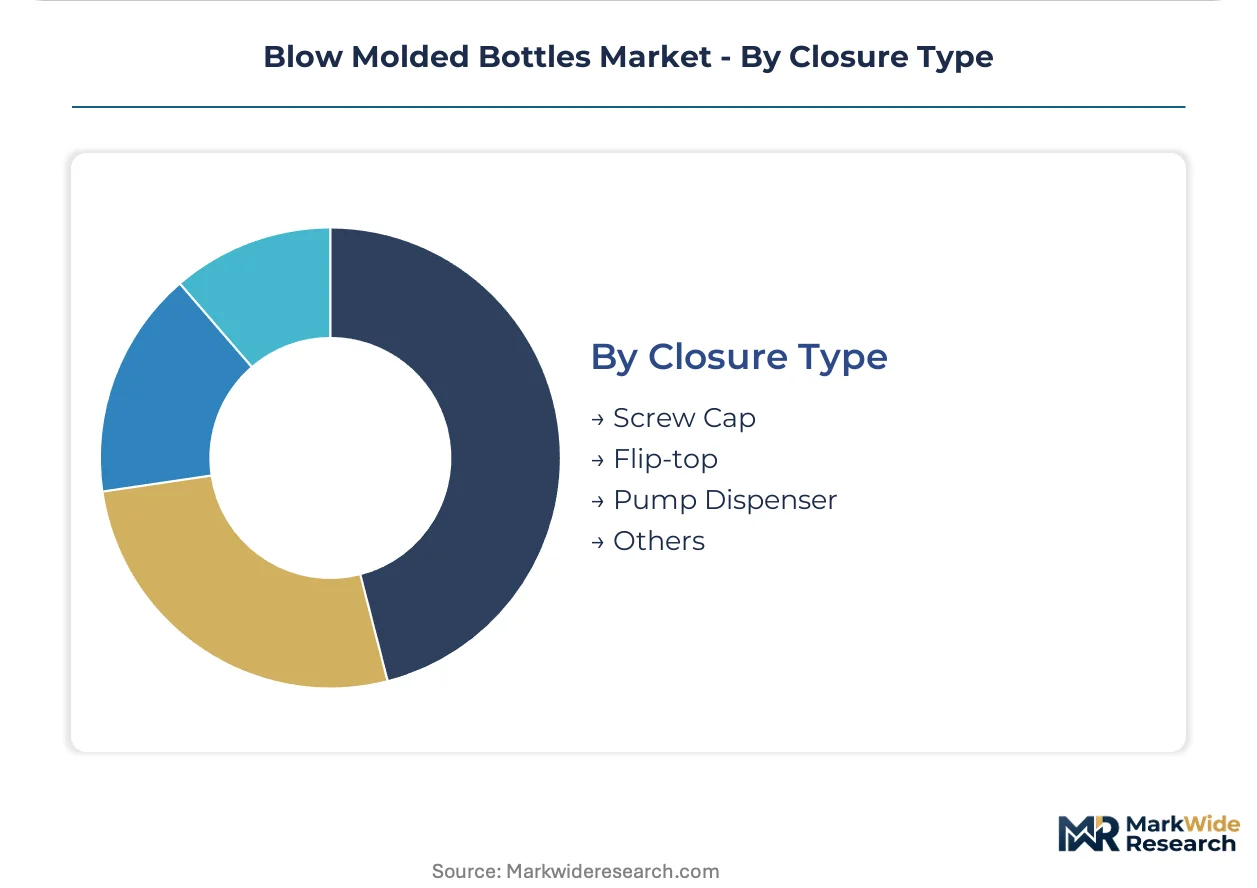
Closure Type:
Customer type separates mass-market convenience from controlled-dispense precision requirements.
- Screw Cap:Standard 28mm PCO finishes dominate beverage applications with tamper-evident band integration for retail security.
- Pump Dispenser:lotion and soap bottles require threaded neck finishes with torque specifications for viscous product evacuation.
- Flip-top:Hinged closures suit on-the-go consumption for sports drink and personal care segments.
- Others:Trigger sprayers and disc-top valves serve household chemical dispensing.
Screw cap attachments lead installed base; pump dispensers are expanding fastest in personal care contract manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest rPET converter capacity in Europe, while the United States leads North American lightweight PET adoption for beverage bottlers.
Germany
Beverage bottlers are scaling orders for reduced-wall-thickness PET containers to meet carbonated drink specifications. The EU Single-Use Plastics Directive mandates recycled content thresholds that reshape converter investment priorities. Packaging clusters in North Rhine-Westphalia are expanding super-cleaning rPET lines to serve Coca-Cola and PepsiCo supply agreements.
United States
Carbonated and still water categories drive procurement of lightweight container designs with compressed resin throughput per unit. The FDA and EPA jointly govern food-contact safety and recycled material pathways, extending qualification timelines for new rPET sources. Midwestern converters in Illinois and Ohio are retrofitting extrusion lines to process higher recycled content ratios.
China
Domestic bottled water brands are specifying bio-based PET from sugarcane ethanol for carbon-neutral positioning. SAMR enforces national food-contact standards that limit import flexibility for non-compliant resin streams. Manufacturing concentration in the Yangtze River Delta is shifting toward embedded recycling systems for closed-loop resin flows.
India
Personal care multinationals are establishing preferred supplier frameworks with tier-one converters for shampoo and conditioner bottle contracts. FSSAI regulations govern food-contact packaging safety for beverage applications. Gujarat-based packaging converters are scaling multilayer barrier technology for pharmaceutical oxygen-scavenging requirements.
Japan
Premium cosmetic brands are commissioning proprietary silhouette designs for shelf-space differentiation. METI guidelines encourage sustainable packaging material transitions across consumer goods supply chains. Kansai region converters near Osaka are specializing in ergonomic grip geometry for pump dispenser compatibility.
Blow Molded Bottles Market Competitive Environment
Top-tier vendors anchor long-term beverage supply agreements, while mid-tier specialists occupy niche barrier technology segments. The vendor base clusters around three strategic archetypes: integrated resin-to-bottle converters with captive recycling infrastructure, regional fabricators serving personal care contract manufacturing, and machinery OEMs licensing all-electric blow molding platforms. Competitive positioning hardens through M&A consolidation of rPET feedstock sources and geographic expansion of preferred supplier frameworks with multinational brand owners.
Within the integrated converter tier, Amcor plc and Berry Global exemplify scale-driven positioning across North American and European manufacturing footprints. ALPLA occupies a distinct position through embedded recycling system specialization that sustains closed-loop resin flows. These three entities represent the dominant competitive archetypes: global supply agreement anchors, regional contract manufacturers, and circular infrastructure operators.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Graham Packaging |
| Alpha Packaging |
| Plastipak Holdings |
| ALPLA |
| Comar |
| Sidel |
| Altium Packaging |
| Others |
Value Chain & Pricing Dynamics
Specialized blow molding technician pools in Germany's North Rhine-Westphalia packaging cluster compress labor-cost differentials between premium rPET-certified converters and commodity virgin-resin suppliers, widening pricing-tier spreads as EU mandates harden procurement specifications.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for food-contact rPET as super-cleaning lines from ALPLA and Berry Global expand output. Three-tier pricing structure across premium certified-rPET, standard virgin-PET, and economy non-food-grade separates converters by FDA and EU REACH compliance depth. Pricing pressure stems from post-consumer bale cost volatility as fragmented national collection infrastructure gaps persist. Beverage bottlers exhibit highest price sensitivity in still water categories, while pharmaceutical barrier bottle buyers prioritize oxygen-scavenging performance over unit cost.
Supply Chain Analysis
EU REACH framework amendments on polymer registration are gating supplier qualification timelines for converters without in-house regulatory affairs functions. Raw material sourcing concentrates in Germany, the United States, and China as dominant resin production and blow molding equipment manufacturing hubs. Post-consumer PET flake supply draws from municipal collection systems in the EU and North America, with quality variability constraining food-contact grade availability. Single-source vulnerability runs through German super-cleaning rPET capacity serving Coca-Cola and PepsiCo supply agreements. Distribution runs through direct-to-brand procurement contracts that compress traditional packaging distributor roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through lightweighting-driven resin throughput reduction per unit, as beverage bottlers specify thinner-wall PET designs that lower material cost while maintaining top-load strength.
For Market Incumbents: To counter rPET feedstock cost volatility, Amcor and Berry Global should deepen backward integration into post-consumer bale sourcing through municipal collection partnerships in Germany and the Midwestern United States. Incumbents must accelerate FDA food-contact safety certification timelines for novel rPET sources to outpace qualification bottlenecks facing mid-tier competitors without dedicated regulatory affairs teams.
For New Entrants and Emerging Players: The EU Single-Use Plastics Directive in Germany opens a window for specialized pharmaceutical barrier bottle converters to capture oxygen-scavenging multilayer demand from prescription drug packagers. New entrants should target India's Gujarat-based pharmaceutical packaging cluster where FSSAI regulations and multilayer barrier technology gaps create white-space for qualified entrants with EVOH coextrusion capabilities.
For Investors and Strategic Acquirers: Beverage multinationals are the most active acquirer in this space, seeking captive rPET capacity to secure Scope 3 emissions accounting compliance. Investors should prioritize mid-tier converters with embedded recycling systems and verified recycled material traceability infrastructure. The signal to watch is EU REACH framework amendment implementation pace, which will concentrate certification capacity among scaled players and accelerate M&A of regulatory-compliant assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Feedstock | Municipal collection partnerships in Germany secure post-consumer bale supply against price volatility. |
| All-Electric Blow Molding Platform Adoption | Sidel and Krones equipment reduces energy draw per cavity for Midwestern beverage converters. |
| Pharmaceutical Barrier Technology Investment | EVOH multilayer qualification opens prescription drug packaging with FDA 21 CFR compliance. |
| Direct-to-Brand Procurement Contracting | Preferred supplier frameworks with PepsiCo and Unilever bypass traditional packaging distributors. |
| EU REACH Compliance Infrastructure Buildout | In-house regulatory affairs functions accelerate polymer registration for German and French converters. |
Study Parameters
Multiple input streams — executive interviews with blow molding plant managers and procurement leads at beverage multinationals, technical discussions with regulatory affairs directors at German packaging converters, and secondary validation against FDA food-contact guidance documents, EU REACH polymer registration databases, and SEC 10-K filings from Amcor and Berry Global — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across primary fieldwork and secondary sources anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include material grade tier, end-use application performance requirements, closure type compatibility, and regional regulatory cluster. CAGRs were derived from trend extrapolation of lightweight PET adoption curves and rPET capacity buildout schedules, with inputs from beverage bottler procurement volume forecasts and pharmaceutical barrier technology penetration assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU Single-Use Plastics Directive enforcement acceleration or sustained post-consumer bale price spikes from collection infrastructure shortfalls. A model refresh is warranted upon material change in FDA food-contact safety certification timelines for novel recycled material sources.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Plastic Vials Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
Recycled Plastic Envelope Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market