
 PET Bottle Market | 2026-2036
PET Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
PET Bottle Market Intelligence
The capital investment gap between integrated recycled PET processing and commodity blow molding is unwinding the traditional competitive landscape. Amcor Plc leverages its global manufacturing footprint to serve multinational beverage clients with standardized packaging. Indorama Ventures Public Company Limited controls a significant portion of the upstream PET resin supply chain, influencing material costs. Plastipak Holdings, Inc. specializes in customized rigid plastic container solutions for diverse end markets.
A PET bottle is a container produced from polyethylene terephthalate via an injection stretch blow molding process. This material provides excellent clarity, chemical resistance, and gas barrier properties, making it ideal for preserving contents. Its primary commercial purpose is the packaging of liquids for the food, beverage, and personal care industries. Carbonated beverage bottles and water bottles constitute the largest product type segments by volume. The increasing focus on circular economy principles elevates the importance of food-grade material, which commands a price premium over industrial-grade resins.
Regulatory frameworks are shaping material choices and product designs across major markets. The European Union's directives on single-use plastics and packaging waste mandate specific levels of recycled content, impacting producers across the continent. In the United States, the FDA sets stringent standards for post-consumer recycled materials intended for food-contact applications. Navigating the divergence between virgin and recycled PET pricing will determine future cost structures and profitability for bottle manufacturers.
Market Dynamics
The push for a circular economy, codified by regulations like the EU Green Deal, is the central force shaping the PET bottle market. This pressure is creating a bifurcation between virgin polymer and recycled content supply chains, impacting investment, pricing, and material innovation.
Growth Catalysts
- Expanding Consumer Markets:Rising disposable incomes and urbanization in high-population countries, particularly China and India, are fueling demand for packaged beverages and personal care products, which are primary end-uses for PET bottles.
- Recycled Content Mandates:Regulatory frameworks, such as the European Union's Single-Use Plastics Directive, require minimum levels of recycled content in beverage bottles, creating a guaranteed demand stream for food-grade recycled PET (rPET).
- Material and Processing Advances:Innovations in lightweighting, which reduces the amount of PET resin per bottle, and the development of enhanced barrier coatings are improving cost-efficiency and expanding applications into oxygen-sensitive product categories.
Market Restraints
- Feedstock Volatility:The price of virgin PET is directly linked to fluctuations in crude oil and paraxylene (PX) markets, creating significant cost instability for converters and bottlers.
- rPET Supply Constraints:A structural shortage of high-quality, food-grade post-consumer recycled PET feedstock acts as a major bottleneck, limiting producers' ability to meet recycled content mandates and brand owner goals.
- Substitution from Alternatives:PET bottles face persistent competition from other packaging materials, including aluminum cans, glass bottles, and flexible pouches, especially in segments like craft beer and premium water.
Strategic Opportunities
- Chemical Recycling Investment:Advanced recycling technologies that break down PET to its molecular building blocks offer a path to produce virgin-quality resin from lower-grade plastic waste, bypassing the limitations of mechanical recycling.
- Non-Food Applications:Expanding use in packaging for household chemicals, personal care items, and pharmaceuticals provides a growth avenue with often less stringent regulatory requirements for recycled content compared to food-contact uses.
- Emerging Market Penetration:Untapped demand in regions like Southeast Asia and Africa presents significant volume growth opportunities as formal retail channels expand and consumer preferences shift toward packaged goods.
Industry Challenges
- Capital Investment Hurdles:The substantial capital expenditure needed to build and certify food-grade rPET processing plants that comply with EFSA or FDA standards presents a significant barrier to entry for new players.
- Regulatory Fragmentation:Manufacturers must navigate a complex and often inconsistent web of national and regional regulations governing plastic waste, recycled content, and food-contact materials, increasing compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Bottle Market |
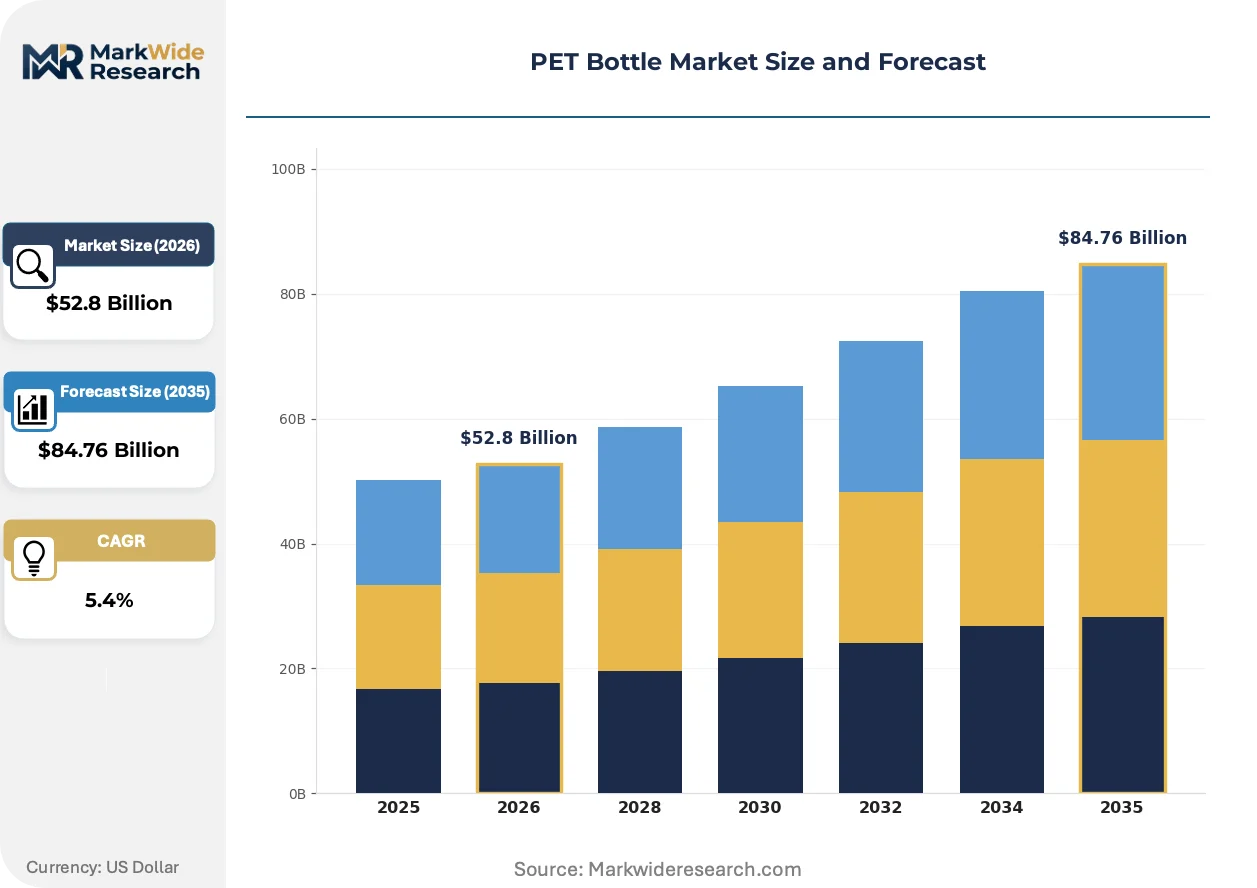
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $84.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated Beverage Bottles, Water Bottles, Juice Containers, Edible Oil Bottles, Cosmetic Bottles Material Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade, Beverage Grade Application: Beverage Packaging, Personal Care Packaging, Household Chemicals, Edible Oil Packaging, Pharmaceutical Packaging End User: Beverage Manufacturers, Personal Care Companies, Chemical Producers, Edible Oil Brands, Pharmaceutical Firms |
| Companies Covered | Berry Global Inc., ALPLA Group, Plastipak Holdings, Inc., Loews Corp, Silgan Containers LLC, Graham Packaging Co Inc., Indorama Ventures Public Company Limited, Krones AG, Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Bottle Market Strategic Shifts & Innovations
Material science innovation is directly responding to regulatory pressures and consumer demands for sustainability. The industry's focus is shifting from optimizing virgin resin performance to mastering the complexities of the recycled material supply chain, fundamentally altering process economics and competitive dynamics.
Advanced Recycling Technologies
Chemical recycling processes like glycolysis break down post-consumer PET waste into its constituent monomers, which can be purified and re-polymerized. Global chemical and packaging companies are actively scaling these technologies to produce virgin-equivalent rPET. This circular PET feedstock is displacing mechanically recycled materials in high-value, food-contact applications where purity and consistent performance are non-negotiable.
Evolving Food-Contact Regulations
The United States FDA's framework for post-consumer recycled plastics requires a Letter of No Objection (LNO) for food-contact use. This process demands that recyclers provide extensive data proving their specific process removes contaminants to a level safe for human consumption. Consequently, bottle producers targeting the US market must partner with or invest in suppliers whose decontamination and processing systems have successfully completed the FDA's rigorous review.
Direct Offtake Agreements for rPET
A significant shift in procurement involves major beverage and consumer packaged goods brands signing long-term offtake agreements directly with rPET producers. This strategy allows brands to secure the volume and quality of recycled material needed to meet sustainability targets, bypassing the price volatility of the open spot market. The practice is most advanced in Europe, where companies are working to comply with EU-mandated recycled content thresholds.
PET Bottle Market Segmentation
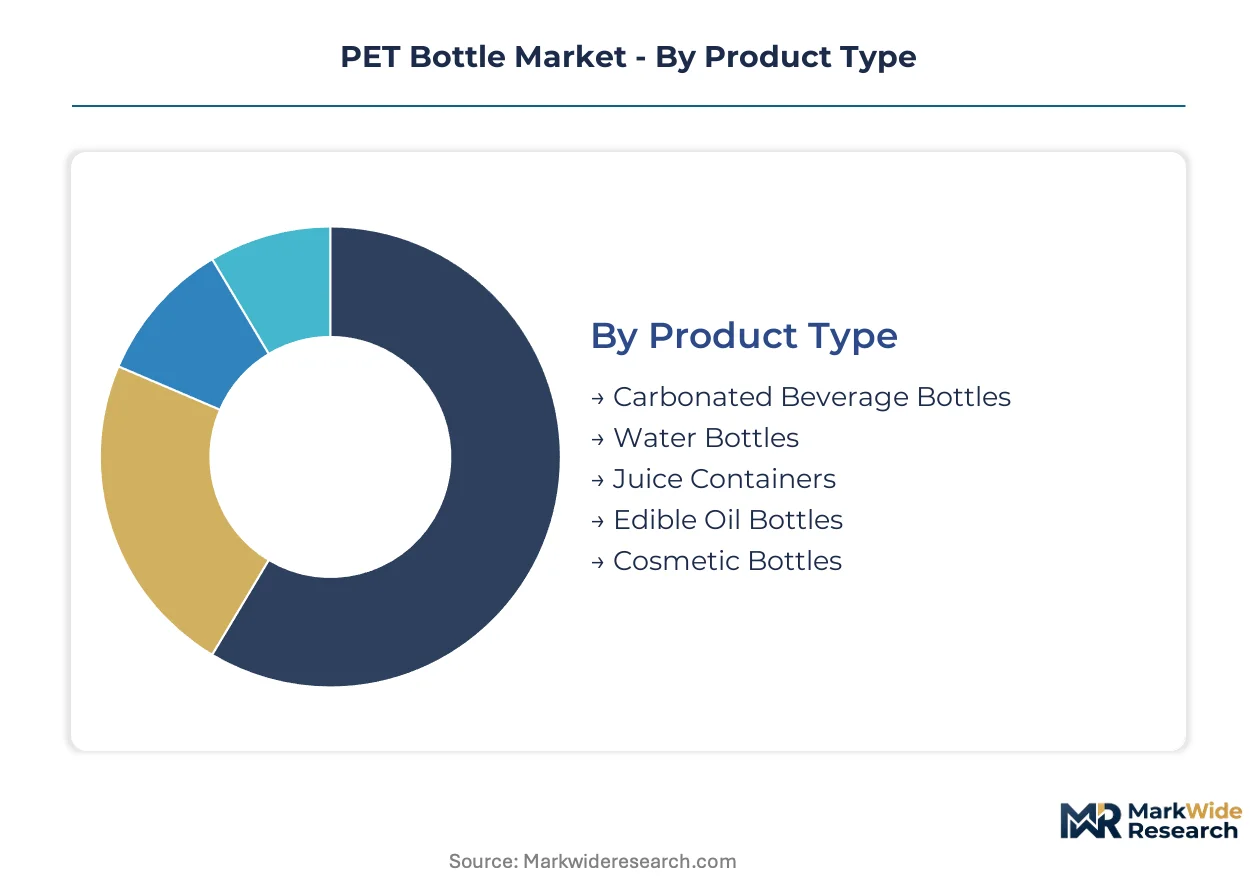
The PET bottle market segmentation reflects the diverse requirements of end-use industries, material specifications, and product designs. Understanding these distinct segments allows manufacturers to tailor production and optimize material sourcing for specific applications, influencing profitability across the value chain.
Product Type:
The diverse product types for PET bottles reflect varying production capacities and distribution networks across different regions.
- Carbonated Beverage Bottles:These containers are engineered with excellent gas barrier properties and structural integrity to withstand internal pressure. Demand concentrates in high-population urban centers such as China and India, driven by expanding consumer goods markets and rising disposable incomes.
- Water Bottles:Designed for lightweighting and clarity, these bottles are suitable for both single-serve and bulk water applications. Global consumption in developed and emerging markets drives volume, though environmental concerns push for increased recycled content mandates in regions like the European Union.
- Juice Containers:PET provides transparency and chemical resistance, making it suitable for various juice formulations and shelf-stable products.
- Edible Oil Bottles:These bottles offer a clear, robust, and safe package for diverse cooking oils, protecting product integrity.
- Cosmetic Bottles:Utilized for personal care products, these bottles offer design flexibility and material compatibility for lotions, shampoos, and soaps.
Water Bottles commands the established base. The steepest expansion runs through Carbonated Beverage Bottles.
Material Grade:
Material grades for PET bottles are differentiated by purity specifications, directly influencing production costs and market pricing.
- Food Grade:This material meets stringent regulatory requirements for direct food contact, ensuring safety and purity for packaged consumables. Demand concentrates in Europe and the United States, driven by FDA and EFSA standards for recycled content in food packaging.
- Industrial Grade:Characterized by lower purity standards, this grade is suitable for non-sensitive applications where cost-efficiency is paramount. Volume demand primarily comes from packaging for household chemicals and general-purpose containers.
- Pharmaceutical Grade:This grade requires high purity and inertness for drug packaging, adhering to pharmacopeial standards and strict quality controls.
- Cosmetic Grade:Offers aesthetic appeal and chemical compatibility, designed for a range of beauty products and personal care formulations.
- Beverage Grade:Optimized for clarity and barrier properties, this grade is specifically designed for liquid refreshment products, including soft drinks and juices.
The supply of Food Grade material is highly concentrated among certified producers. Industrial Grade material faces broader competition.
Application:
PET bottle applications are driven by specific industry requirements, from high-volume consumer goods to specialized medical uses.
- Beverage Packaging:This is the dominant application for PET bottles, encompassing water, carbonated soft drinks, and juices. Global demand from multinational beverage brands drives innovation in lightweighting and recycled content integration.
- Personal Care Packaging:This segment includes bottles for shampoos, conditioners, lotions, and liquid soaps, valuing design flexibility and chemical resistance. Growth in emerging markets like India and Southeast Asia creates new opportunities for packaged personal care products.
- Household Chemicals:This application utilizes PET for cleaners and detergents, offering durability and chemical compatibility for various formulations.
- Edible Oil Packaging:Provides a transparent and robust container for various types of cooking oils, ensuring product protection and extended shelf life.
- Pharmaceutical Packaging:Requires high-purity PET for medicines, adhering to strict regulatory protocols and material safety standards.
Beverage Packaging holds the largest share of PET bottle consumption. Personal Care Packaging is expanding most quickly.
End User:
End-user segments exhibit distinct procurement patterns, often seeking specialized bottle designs and material certifications.
- Beverage Manufacturers:These are large-scale buyers requiring high volumes of standardized and custom PET bottle designs for their extensive product lines. Procurement patterns are shifting towards long-term offtake agreements for rPET to meet sustainability targets.
- Personal Care Companies:These companies seek innovative and aesthetically pleasing PET bottle designs to differentiate products in competitive markets. They prioritize material compatibility and brand-specific customization.
- Chemical Producers:Utilize PET bottles for household and industrial chemical products, focusing on durability, safety, and compatibility with aggressive formulations.
- Edible Oil Brands:Require secure and transparent PET packaging that protects product integrity, prevents oxidation, and extends shelf life.
- Pharmaceutical Firms:Demand highly sterile and compliant PET bottles for various medical and health products, adhering to strict regulatory standards for packaging.
Beverage Manufacturers drive significant volume through the PET bottle value chain. Pharmaceutical Firms demand the highest value-added solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing asymmetry exists between European markets, where stringent recycled content mandates drive up rPET costs, and Asian markets, where virgin PET pricing often remains more competitive. This divergence influences material sourcing and investment decisions.
China
China's demand for PET bottles stems from its vast consumer base and rapid urbanization, particularly for packaged beverages. The country's dual carbon goals increasingly influence packaging material choices and recycling infrastructure development. Production and innovation concentrate within the Yangtze River Delta and Pearl River Delta regions.
India
India's PET bottle consumption is propelled by rising disposable incomes and a burgeoning packaged food and beverage sector. The Bureau of Indian Standards (BIS) sets quality benchmarks for plastic products, guiding domestic production. Major manufacturing clusters in Maharashtra and Gujarat are expanding capacity.
United States
The United States market for PET bottles is driven by its extensive consumer base for beverages and personal care items. The FDA establishes stringent standards for post-consumer recycled materials, influencing rPET supply. Packaging innovation and production facilities concentrate in states like California and across the Northeast Corridor.
Germany
Germany's PET bottle market is shaped by a mature beverage sector and a strong national commitment to circular economy principles. The EU Green Deal and Single-Use Plastics Directive mandate specific recycled content levels, driving material innovation. Production and recycling infrastructure are highly developed in North Rhine-Westphalia and Bavaria.
Japan
Japan exhibits high per capita consumption of packaged beverages, fueling steady demand for PET bottles for water and teas. METI promotes plastic resource circulation through various initiatives, impacting packaging design. Major manufacturing and recycling operations are active in the Kanto and Kansai regions.
PET Bottle Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the PET bottle market. The industry structure shows consolidation among large-scale manufacturers but also fragmentation among regional specialists. Three strategic archetypes emerge: global integrated suppliers, specialized custom molders, and upstream resin producers. Dominant competitive moves involve capacity expansion and strategic partnerships, particularly for securing recycled content.
Global integrated suppliers like Amcor Plc exemplify a strategy focused on leveraging extensive manufacturing footprints to serve multinational beverage clients with standardized packaging solutions. Indorama Ventures Public Company Limited, a Thailand-based entity, occupies a position as a major upstream PET resin producer, influencing material costs and supply chain stability across the value chain. Plastipak Holdings, Inc., a US-based firm, anchors the segment of specialized custom rigid plastic container solutions for diverse end markets, adapting to evolving customer needs. These companies represent distinct approaches to market penetration and value creation within the PET bottle ecosystem.
| Leading Market Players |
|---|
| Berry Global Inc. |
| ALPLA Group |
| Plastipak Holdings, Inc. |
| Loews Corp |
| Silgan Containers LLC |
| Graham Packaging Co Inc. |
| Indorama Ventures Public Company Limited |
| Krones AG |
| Amcor Plc |
Cost & Logistics Intelligence
Recycled content mandates are reshaping the PET bottle market, simultaneously altering material supply chains and influencing pricing economics across major consumption geographies. This dynamic is particularly evident in regions like Europe, where regulatory pressures drive demand for rPET.
Pricing Analysis
Configured-to-order solutions for specialized PET bottle designs command a premium over standardized commodity offerings. The PET bottle market operates on a hybrid pricing model, blending commodity spot pricing for virgin resin with contract-based long-term offtake agreements for rPET. Price differentiation stems from food-grade certification requirements and the volume scale of procurement. Pricing pressure on rPET is increasing due to supply constraints and regulatory mandates, while virgin PET prices remain volatile with crude oil. Industrial grade users exhibit higher price sensitivity compared to large beverage manufacturers securing rPET.
Supply Chain Analysis
The structural shortage of high-quality food-grade post-consumer recycled PET feedstock acts as a chokepoint for circularity initiatives across major markets. Upstream PET resin production largely concentrates in Asian countries like China and India, drawing from paraxylene and crude oil derivatives. Feedstock volatility in crude oil markets presents a significant supply chain risk for virgin PET producers. Distribution runs through global integrated suppliers serving multinational beverage brands and specialized custom molders for regional needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET bottle market presents a service-attach opportunity, as advanced rPET processing and certification services are expanding faster than traditional virgin resin production. This shift reflects the industry's drive towards circularity and regulatory compliance.
For Market Incumbents:Compound existing manufacturing footprints by strategically investing in advanced chemical recycling technologies. Secure long-term offtake agreements for food-grade rPET to mitigate feedstock volatility and meet regulatory mandates, especially in the European Union. This defends against substitution from alternative packaging materials and ensures compliance with evolving standards. Pursue strategic partnerships to expand certified rPET processing capacity in regions like the United States.
For New Entrants and Emerging Players:Lead with specialized solutions for non-food applications, targeting segments like household chemicals and personal care items. These areas often present less stringent regulatory requirements for recycled content compared to food-contact uses. Penetrate emerging markets such as Southeast Asia and Africa by offering cost-efficient and durable packaging solutions. A go-to-market angle focusing on design flexibility and material compatibility for diverse product formulations will capture market share.
For Investors and Strategic Acquirers:The market sits at a transition phase that favors vertically integrated rPET processors and innovators in chemical recycling technologies. Long-term viability remains strong for PET bottles, driven by persistent demand for packaged beverages and the imperative for circularity. Acquisition targets should include firms with established food-grade rPET production or advanced material science capabilities. The signal to watch is the commercial scaling of chemical recycling facilities, indicating a shift in feedstock dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Investment in Chemical Recycling Infrastructure | This advances circularity by producing virgin-equivalent resin from diverse PET waste streams. |
| Long-term rPET Offtake Agreements | Beverage manufacturers secure consistent supply of food-grade recycled content to meet EU mandates. |
| Capacity Expansion for Food-Grade rPET | Producers address the structural shortage of high-quality feedstock required by FDA standards. |
| Development of Enhanced Barrier Coatings | This innovation expands PET bottle applications into oxygen-sensitive product categories, like juices. |
| Penetration of Emerging Markets | Companies capture new volume growth opportunities in regions like Southeast Asia for packaged goods. |
Research Approach
Desk research of regulatory filings, industry association reports, and company annual reports preceded structured interviews with PET bottle manufacturers, rPET processors, brand procurement managers, and packaging designers. This approach combined primary insights with extensive secondary validation. Bottom-up and top-down triangulation methods ensured data consistency and accuracy across all market segments.
Variance decomposition models projected market growth across the analysis window by isolating the impact of key drivers and restraints. The analytical framework segmented the market by product type, material grade, application, end user, and regional production hubs. Compound Annual Growth Rates were derived from historical trends and projected market dynamics, with forecast inputs including virgin PET pricing and rPET supply availability.
Forecasts assume regulatory continuity in regimes like the European Union and the United States; material policy shifts would require re-modeling. These projections reflect current assumptions on feedstock volatility. Practitioners should keep alternative scenarios live as industry conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Water Cooler Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Insulated Cup Sleeves Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Can Sleeves Market