
 Plastic Tubes Market | 2026-2036
Plastic Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Tubes Market Outlook
Polymer compounding expertise is redrawing competitive boundaries as specialized formulation chemists become scarce across mature manufacturing economies. Berry Global Inc. leverages captive resin blending capabilities to secure cost-advantaged multilayer tube supply for North American pharmaceutical clients. Albéa Group anchors its position through dedicated extrusion R&D centers in France and China that sustain premium cosmetic tube innovation.
Plastic tubes are hollow cylindrical extrusions manufactured from thermoplastic resins, typically ranging from 2 mm to 150 mm in diameter, designed to contain, protect, and dispense viscous or semi-liquid products across industrial and consumer applications. The extrusion blow-molding or coextrusion process yields barrier structures with ethylene vinyl alcohol or polyamide interlayers to prevent oxygen and moisture ingress. Flexible tubes dominate unit volume in personal care and pharmaceutical packaging where squeezability and controlled dispensing govern purchase decisions, while medical tubing commands premium pricing due to USP Class VI and ISO 10993 biocompatibility certification burdens that constrain supplier pools. Polyethylene formulations lead material consumption for cost-sensitive mass-market applications, though polypropylene is gaining ground in hot-fill food packaging where dimensional stability above 100°C proves essential.
US FDA enforces 21 CFR 177.1520 compliance for food-contact polyethylene and polypropylene tubes, while EPA regulations on vinyl chloride monomer residuals shape PVC tubing viability in potable water and medical fluid transfer. EU REACH restricts phthalate plasticizers in PVC medical tubing, redirecting formulation investment toward citrate-based alternatives. ISO 9001 and ISO 13485 certification gates are hardening for medical tubing suppliers as OEMs consolidate approved vendor lists. Stakeholders must monitor evolving extended producer responsibility schemes in California and the EU that will internalize post-consumer tube collection costs into supplier economics.
Market Dynamics
Multilayer coextrusion technology is compressing margins for commodity tube suppliers while rewarding compounders with captive barrier resin capabilities. REACH chemical certification deadlines in Europe are forcing cosmetic tube manufacturers to requalify entire material portfolios ahead of 2026 enforcement windows.
Growth Catalysts
- Pharmaceutical serialization mandates:EU Falsified Medicines Directive compliance is requiring tamper-evident tube closures with integrated track-and-trace codes. This specification upgrade is pulling higher-margin multilayer structures into oral care and topical drug packaging.
- India's PLI scheme for packaging:Production-linked incentives for domestic manufacturing are accelerating extrusion capacity additions near Mumbai and Ahmedabad to serve FMCG and generic drug exporters.
- Hot-fill food packaging migration:Polypropylene dimensional stability above 100°C is displacing glass and metal in sauce and condiment tubes, particularly in North American private-label retail channels.
Market Restraints
- Ethylene vinyl alcohol supply concentration:Barrier resin production clusters in Japan and South Korea create vulnerability for European and North American tube laminators seeking EVOH interlayer supply.
- PVC plasticizer substitution costs:EU REACH restrictions on phthalates are forcing medical tubing compounders toward citrate-based alternatives at 15-30% formulation cost premiums.
- Biocompatibility certification burdens:USP Class VI and ISO 10993 testing timelines stretch 18-24 months, constraining supplier pool expansion for fluid transfer and drainage tubing.
Strategic Opportunities
- Post-consumer recycled content mandates:California's extended producer responsibility framework and EU Packaging and Packaging Waste Regulation are creating certified PCR resin demand that integrated compounders can capture.
- Minimally invasive surgical expansion:Catheter and endoscopic tubing demand is outpacing general medical packaging growth, with specialized extrusion cleanrooms commanding 40-60% price premiums over standard pharmaceutical tubes.
- Direct-to-consumer refill systems:Subscription personal care brands are specifying larger-diameter tubes with precision dispensing closures, opening design service revenue streams beyond commodity extrusion.
Industry Challenges
- Polymer formulation chemist scarcity:Specialized expertise in multilayer adhesion promotion and rheology control is retiring across mature manufacturing economies faster than technical universities can replenish pipelines.
- ISO 13485 certification backlog:Medical tubing OEMs are consolidating approved vendor lists, forcing mid-tier extruders through 12-18 month quality system overhauls to maintain contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Tubes Market |
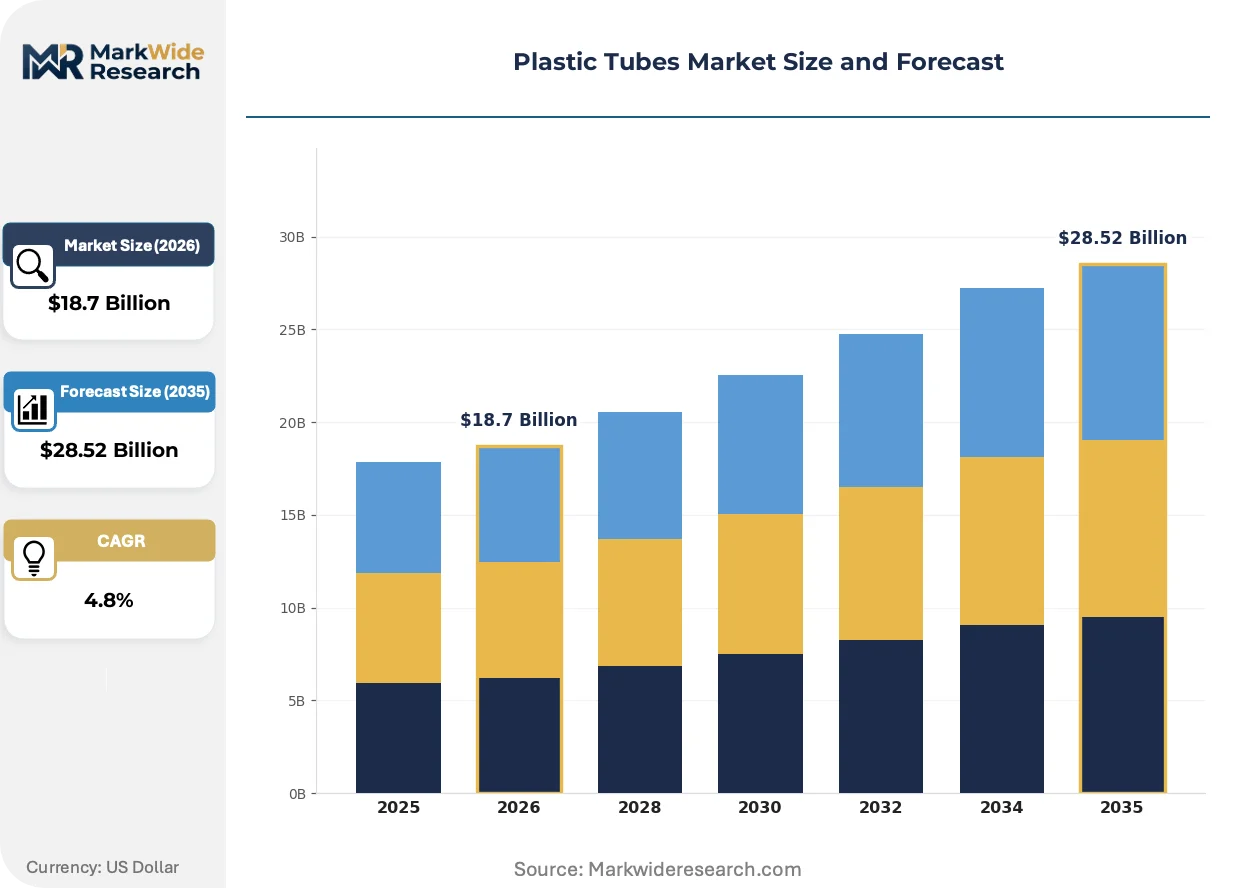
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Tubes, Rigid Tubes, Medical Tubing, Industrial Tubing Material: Polyethylene, Polypropylene, PVC, Nylon End User: Healthcare, Food Packaging, Industrial Supplies, Consumer Goods Application: Fluid Transfer, Packaging Solutions, Construction, Automotive |
| Companies Covered | Berry Global Inc., Albéa Group, EPL Limited, CCL Industries Inc., Huhtamäki Oyj, Amcor plc, LINHARDT GmbH & Co. KG, Hoffmann Neopac AG, ALLTUB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Tubes Market Strategic Shifts
Active and intelligent packaging integration is redefining tube functionality beyond containment, with sensor-enabled closures and oxygen-scavenging layers moving from pilot programs to commercial pharmaceutical contracts.
Digital printing on tube substrates is fragmenting the traditional offset-decorated tube market. Pharmaceutical and cosmetic brands in Germany and France are adopting direct-to-sleeve inkjet systems that enable lot-specific variable data and regional language customization without plate changeover costs. This capability is compressing minimum order quantities and enabling regionalized production footprints that challenge centralized high-volume extrusion economics.
REACH Annex XVII expansion on microplastic restrictions is reshaping formulation strategies for cosmetic rinse-off products. The European Chemicals Agency's 2023-2025 restriction roadmap is forcing tube suppliers to eliminate polyethylene microbeads and certify biodegradability for wash-off formulations. Personal care brands with European distribution are responding by accelerating qualification of bio-based polyhydroxyalkanoate tube structures despite 25-35% material cost premiums.
Consolidated procurement by multinational FMCG conglomerates is compressing supplier margins and technical specification autonomy. Unilever and Procter & Gamble's centralized packaging engineering groups are mandating harmonized tube diameters and closure interfaces across regional manufacturing networks. This standardization is visible most acutely in Southeast Asian contract manufacturing hubs, where local tube converters must retool extrusion lines to match global SKU templates or exit approved supplier rosters.
Plastic Tubes Market Segmentation
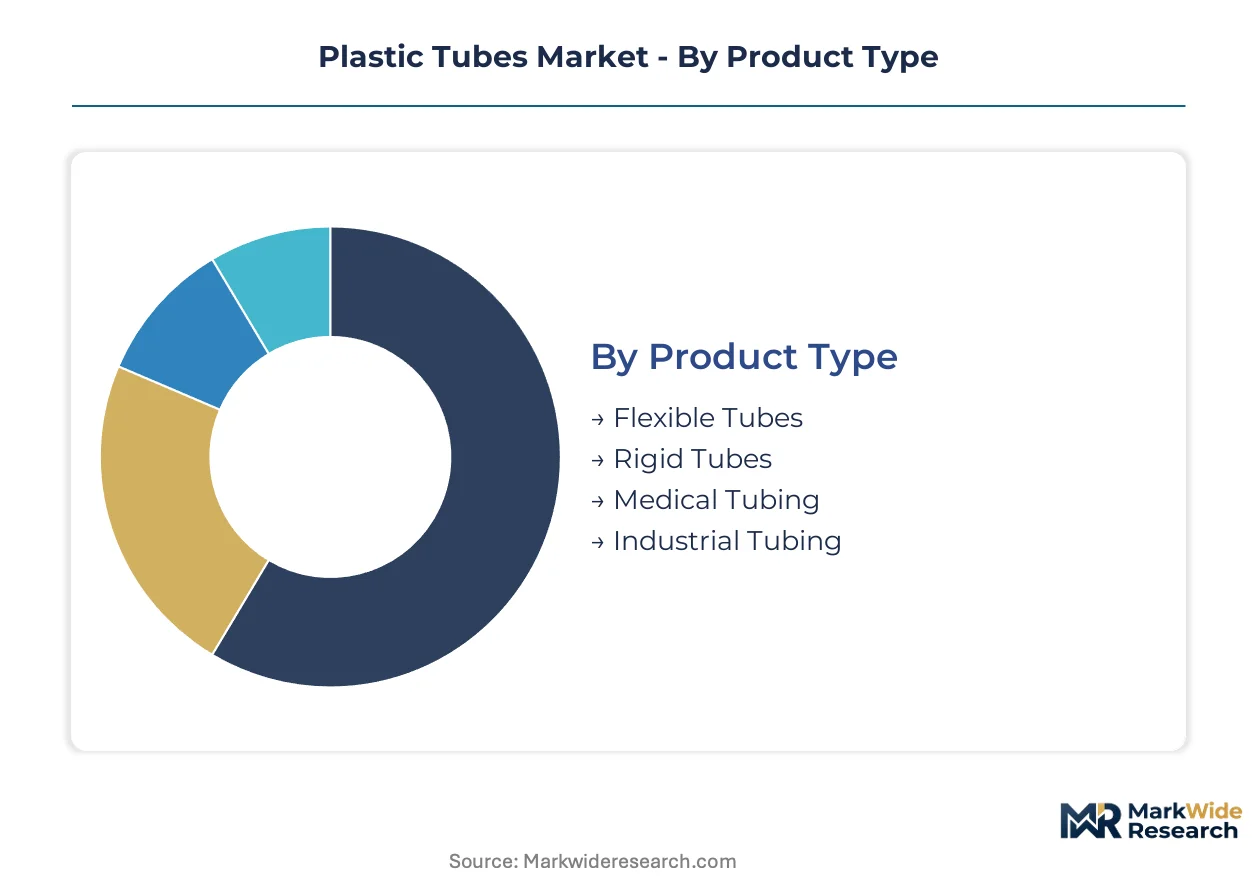
Plastic tube segmentation reveals divergent margin structures across pharmaceutical certification tiers, barrier technology layers, and regional regulatory compliance burdens. Each dimension carries distinct supply chain implications for compounders and converters.
Product Type:
Flexible tubes dominate domestic consumption in personal care and food sectors, while medical tubing exports concentrate in FDA-registered cleanroom facilities serving North American and European OEMs.
- Flexible Tubes:Multilayer coextrusions with EVOH or polyamide barriers prevent oxygen and moisture ingress for pharmaceutical and cosmetic viscous products. Demand concentrates in India's expanding FMCG sector and North American private-label retail channels where squeezability governs purchase decisions.
- Medical Tubing:Extrusions requiring USP Class VI and ISO 10993 biocompatibility certification for fluid transfer, drainage, and catheter applications. European and Japanese OEMs consolidate approved vendor lists, constraining supplier pool expansion amid 18-24 month qualification timelines.
- Rigid Tubes:Structural extrusions for industrial fluid containment with thicker wall specifications.
- Industrial Tubing:General-purpose conduits for pneumatic and hydraulic systems across manufacturing automation.
Flexible tubes command the established base. The steepest expansion runs through medical tubing.
Material:
Cost tier differentiation separates commodity polyethylene formulations from premium barrier compounds and certified biocompatible grades.
- Polyethylene:LDPE and HDPE formulations lead volume consumption for cost-sensitive mass-market tubes. Indian and Southeast Asian converters leverage domestic resin supply for FMCG and generic drug packaging.
- Polypropylene:Homopolymer and random copolymer grades deliver dimensional stability above 100°C for hot-fill sauce and condiment tubes. North American private-label retailers are displacing glass and metal in this temperature-critical segment.
- PVC:Plasticized formulations face REACH phthalate restrictions, redirecting investment toward citrate-based alternatives.
- Nylon:Polyamide grades serve specialized barrier and mechanical strength applications.
Polyethylene anchors current volume. Polypropylene is gaining share fastest in food packaging migration.
End User:
Customer type segmentation exposes divergent procurement patterns between consolidated multinational FMCG engineering groups and fragmented regional healthcare distributors.
- Healthcare:Hospitals, clinics, and home care settings drive demand for sterile fluid transfer and drainage systems. Japanese and German OEMs enforce ISO 13485 certification gates that compress mid-tier supplier margins.
- Consumer Goods:Personal care brands specify multilayer barrier tubes with tamper-evident closures for oral care and topical formulations. Unilever and Procter & Gamble's centralized engineering groups mandate harmonized diameters across Southeast Asian contract manufacturing hubs.
- Food Packaging:Hot-fill and aseptic processing requirements.
- Industrial Supplies:Pneumatic, hydraulic, and process equipment applications.
Consumer goods represents the largest addressable base. Healthcare delivers the steepest margin expansion trajectory.
Application:
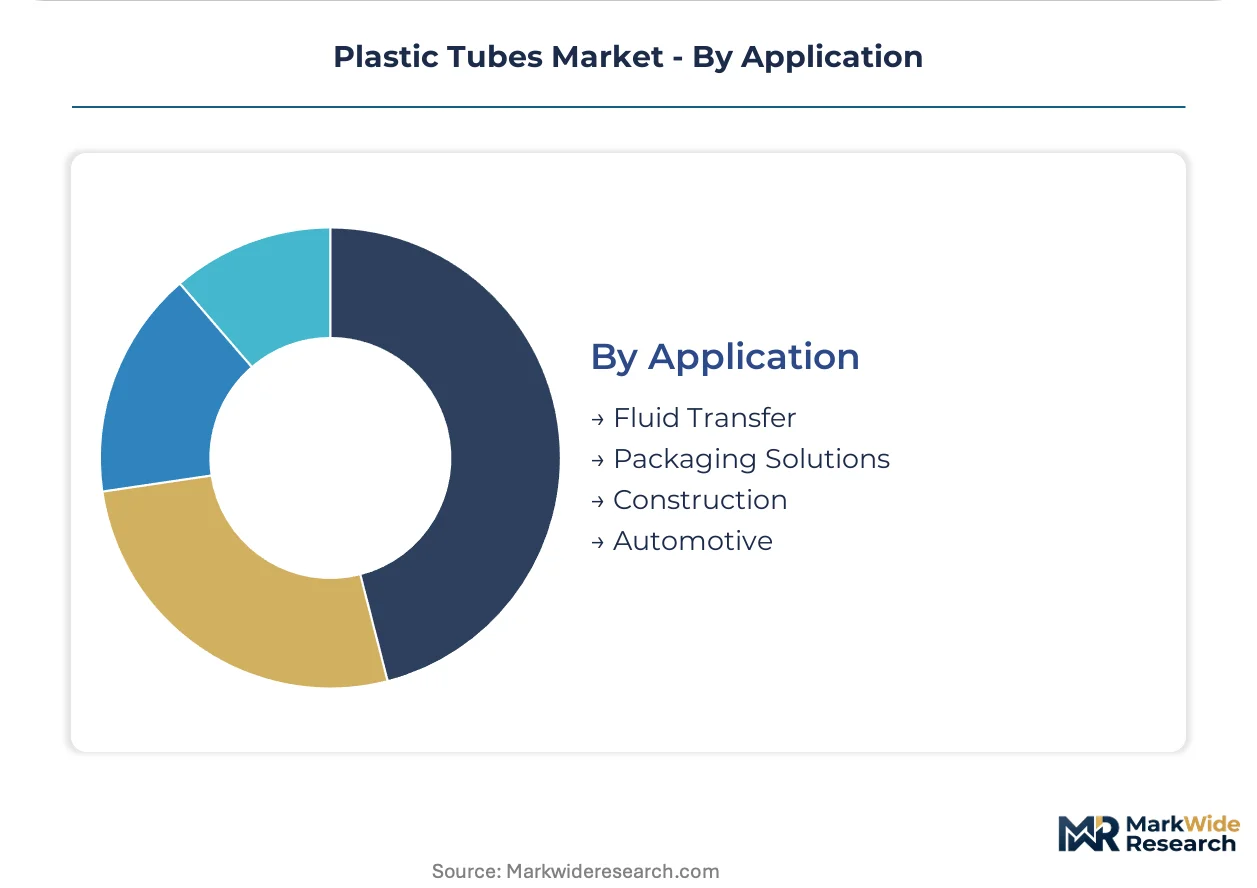
Application segmentation tracks the shift from passive containment toward active functionality in pharmaceutical and intelligent packaging systems.
- Packaging Solutions:Barrier tubes with oxygen-scavenging layers and sensor-enabled closures are moving from pilot programs to commercial pharmaceutical contracts in Germany and France. Direct-to-sleeve digital printing enables lot-specific variable data without plate changeover costs.
- Fluid Transfer:Catheter and endoscopic tubing for minimally invasive surgical procedures commands 40-60% price premiums over standard pharmaceutical tubes in Japanese and North American hospital supply chains.
- Construction:Conduit and protective sleeving for infrastructure.
- Automotive:Fluid routing and pneumatic systems in vehicle assembly.
Packaging solutions holds the volume foundation. Fluid transfer in surgical applications is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR compliance anchors North American pharmaceutical tube demand while EU REACH chemical certification deadlines compress European supplier margins. India's PLI scheme for packaging accelerates extrusion capacity additions near Mumbai and Ahmedabad. Japanese OEMs enforce ISO 13485 certification gates that constrain medical tubing supplier pools.
United States
Private-label retailers displace glass and metal with polypropylene hot-fill tubes for sauces and condiments. FDA enforces 21 CFR 177.1520 compliance for food-contact polyethylene and polypropylene formulations. Midwest extrusion clusters around Chicago and Cincinnati serve North American pharmaceutical and personal care packaging networks.
Germany
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive pull higher-margin multilayer structures into oral care packaging. ECHA REACH Annex XVII expansion on microplastic restrictions forces cosmetic tube suppliers to certify biodegradability for wash-off formulations. Industrial concentrations in North Rhine-Westphalia and Bavaria host digital printing pilot programs for direct-to-sleeve inkjet systems.
India
Domestic FMCG and generic drug packaging sectors concentrate demand for cost-sensitive polyethylene tubes. The PLI scheme for packaging production-linked incentives accelerates extrusion capacity additions near Mumbai and Ahmedabad. Gujarat-based converters leverage domestic resin supply for Southeast Asian export channels.
Japan
Minimally invasive surgical expansion drives catheter and endoscopic tubing demand outpacing general medical packaging growth. METI industrial standards and PMDA pharmaceutical regulations enforce biocompatibility certification timelines stretching 18-24 months. Osaka and Nagoya industrial corridors host specialized extrusion cleanrooms commanding premium pricing over standard pharmaceutical tubes.
China
Albéa Group anchors premium cosmetic tube innovation through dedicated extrusion R&D centers in France and China. NMPA pharmaceutical packaging regulations and MIIT industrial standards shape barrier resin qualification requirements. Yangtze River Delta manufacturing clusters serve both domestic consumption and European cosmetic brand supply chains.
Plastic Tubes Market Competitive Environment
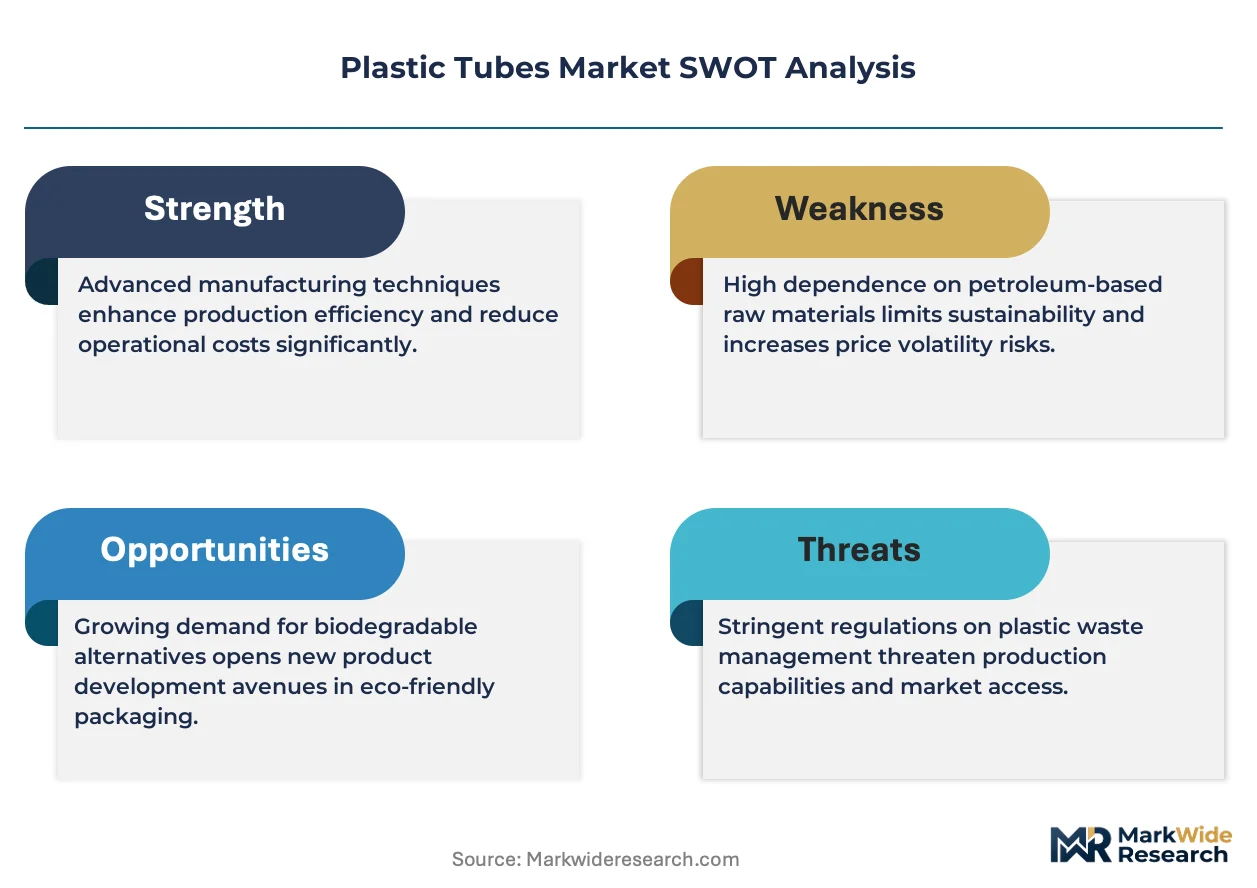
A small set of integrated leaders sits above a broader specialist tier in plastic tube manufacturing. Berry Global Inc. leverages captive resin blending capabilities to secure cost-advantaged multilayer tube supply. Three strategic archetypes dominate: integrated compounders with barrier resin capabilities, premium cosmetic specialists with dedicated R&D centers, and regional converters serving cost-sensitive FMCG volumes. Competitive moves concentrate on multilayer coextrusion technology deployment and REACH chemical certification portfolio requalification ahead of 2026 enforcement windows.
Among integrated North American packaging conglomerates, Berry Global Inc. and Amcor plc exemplify the compounder-converter archetype with upstream resin control. Albéa Group anchors the premium cosmetic specialist tier through France and China-based extrusion R&D centers. EPL Limited represents the emerging market-focused converter archetype serving India's expanding domestic FMCG and generic drug packaging sectors. These three occupy distinct competitive positions without direct segment overlap, reducing price-based rivalry intensity.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Albéa Group |
| EPL Limited |
| CCL Industries Inc. |
| Huhtamäki Oyj |
| Amcor plc |
| LINHARDT GmbH & Co. KG |
| Hoffmann Neopac AG |
| ALLTUB |
| Others |
Value Chain & Pricing Dynamics
Polypropylene's displacement of glass and metal in hot-fill food packaging simultaneously redraws supply geography toward North American private-label retail channels and compresses pricing premiums for temperature-stable barrier formulations. This substitution dynamic funnels procurement power toward consolidated FMCG engineering groups while fragmenting margin structures across converter tiers.
Pricing Analysis
Price spreads between Japanese medical tubing cleanrooms and Indian FMCG commodity converters exceed 40-60% on equivalent diameter specifications. Three-tier pricing structure across premium, standard, and economy levels separates USP Class VI certified medical grades from pharmaceutical barrier tubes and mass-market polyethylene formats. Pricing pressure stems from Unilever and Procter & Gamble's harmonized diameter mandates across Southeast Asian contract manufacturing hubs. Consumer goods procurement teams exhibit highest price sensitivity; Japanese OEMs purchasing catheter tubing show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites resin feedstock flows to Southeast Asian extrusion clusters serving European cosmetic brand supply chains. Manufacturing concentrates in China, India, and Germany for distinct end-use tiers. EVOH barrier resin supply draws from Japanese and South Korean petrochemical complexes. Single-source vulnerability runs through concentrated EVOH interlayer production. Distribution runs through multinational FMCG centralized engineering groups and fragmented regional healthcare distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plastic tubes sit in early-cycle expansion as pharmaceutical serialization mandates and minimally invasive surgical adoption create durable specification upgrades across barrier and biocompatibility tiers.
For Market Incumbents: Shield formulation expertise advantages by accelerating polymer chemist recruitment ahead of retirement-driven scarcity across mature manufacturing economies. Consolidate approved vendor list positions through preemptive ISO 13485 certification investments before OEM consolidation hardens. Backward integration into captive EVOH compounding secures margin defense against resin supply concentration.
For New Entrants and Emerging Players: Lead with post-consumer recycled content certification capabilities to capture California extended producer responsibility and EU Packaging and Packaging Waste Regulation procurement mandates. India's PLI scheme incentives near Mumbai and Ahmedabad offer the most penetrable geography for cost-sensitive polyethylene tube manufacturing. Direct-to-consumer refill system partnerships with subscription personal care brands provide design service revenue beyond commodity extrusion.
For Investors and Strategic Acquirers: REACH Annex XVII microplastic restriction enforcement reshapes the acquisition landscape toward bio-based polyhydroxyalkanoate formulation capabilities. Five-to-ten year viability favors compounders with integrated barrier resin production and established pharmaceutical certification portfolios. Target integrated converters with captive multilayer coextrusion technology. Monitor ECHA biodegradability certification timelines as inflection signal for cosmetic tube supplier restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Capacity Expansion | Captures pharmaceutical serialization mandate demand for tamper-evident barrier structures under EU Falsified Medicines Directive. |
| Backward Integration into EVOH Compounding | Reduces exposure to Japanese and South Korean barrier resin supply concentration for European tube laminators. |
| Post-Consumer Recycled Content Certification | Qualifies suppliers for California extended producer responsibility frameworks and EU Packaging and Packaging Waste Regulation procurement. |
| ISO 13485 Quality System Overhaul | Maintains approved vendor list eligibility as Japanese and German OEMs consolidate medical tubing supplier pools. |
| Bio-Based Polyhydroxyalkanoate Formulation Investment | Positions cosmetic tube suppliers ahead of ECHA REACH Annex XVII microplastic restriction enforcement. |
Study Parameters
A spread of perspectives from extrusion plant managers, pharmaceutical packaging procurement leads, polymer formulation chemists, and cosmetic brand supply chain directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC filings from packaging conglomerates, BIS certification databases, and ECHA REACH substance registration data. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segmentation dimensions modeled include product type, material formulation, end-user industry, and application functionality across the projection horizon. CAGRs derive from regression analysis of historical capacity additions, resin price elasticity coefficients, and regulatory compliance cost trajectories. Forecast inputs incorporate pharmaceutical serialization mandate implementation timelines and minimally invasive surgical procedure growth curves.
The analysis sits within stated boundaries; outcomes outside sustained EVOH supply availability or accelerated REACH enforcement would require recalibration. Forecasts reflect documented assumptions on resin price trajectories and certification timeline stability. Practitioners should keep alternative scenarios live as EU chemical restriction roadmaps and extended producer responsibility scheme implementations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Asia Pacific Single-Use Plastic Packaging Market
Plastic Packaging
US Plastic Packaging Market
Plastic Packaging
Plastic Cutlery Market