
 South Africa Plastic Packaging Market | 2026-2036
South Africa Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Plastic Packaging Market Analytics
Single-source reliance on imported resin is hardening into multi-source procurement with local polymer integration. Nampak Ltd anchors beverage can and rigid plastics output through captive converting lines across KwaZulu-Natal and Gauteng. Mpact Ltd leverages recycled-content leadership to sustain supply contracts with major retail chains. Polyoak Packaging specializes in injection-molded closures and bottles for the dairy and edible oil sectors.
South Africa plastic packaging denotes thermoformed, blow-molded, and extruded polymer structures typically manufactured from polyethylene, polypropylene, or PET resins with wall calibers ranging from 0.15 mm films to 2.5 mm rigid containers, engineered to preserve shelf stability, enable barrier protection, and support automated filling lines across food, beverage, and pharmaceutical supply chains. Films and flexible bags dominate tonnage throughput due to their prevalence in fresh produce and grain packaging, though rigid PET bottles command premium margin pools in beverage applications. Healthcare packaging represents the fastest-expanding application segment as cold-chain pharmaceutical distribution expands domestically.
The Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations that mandate post-consumer collection targets and recycled-content minimums, compelling converters to redesign specifications and secure local recycling feedstock. BIS-equivalent South African Bureau of Standards certification governs food-contact migration limits and pharmaceutical primary packaging integrity. Stakeholders must monitor regulatory enforcement cadence and recycler capacity buildout to calibrate capital allocation between virgin and circular material streams.
Market Dynamics
Extended producer responsibility regulations under the Department of Forestry, Fisheries and the Environment are forcing converters to redesign specifications and secure local recycling feedstock, creating a structural pivot toward circular material streams.
Growth Catalysts
- Regulatory Compliance Mandates:The Department of Forestry, Fisheries and the Environment enforces post-consumer collection targets and recycled-content minimums that compel packaging redesign.
- Cold-Chain Pharmaceutical Distribution:Healthcare packaging represents the fastest-expanding application segment as domestic pharmaceutical logistics infrastructure matures.
- Johannesburg-Pretoria Manufacturing Corridors:Gauteng province concentrates national demand, anchoring converter capacity expansion and supply chain efficiency.
Market Restraints
- Resin Import Dependency:Single-source reliance on imported polymer feedstock exposes converters to currency volatility and shipping disruptions.
- Recycling Infrastructure Gaps:Post-consumer collection systems remain underdeveloped relative to regulatory targets, constraining circular feedstock availability.
- Flexible Film Substitution Pressure:Paper-based alternatives gain traction in fresh produce segments, threatening polyethylene film volumes.
Strategic Opportunities
- KwaZulu-Natal Port Proximity:Coastal logistics positioning enables export-oriented rigid container production for regional African markets.
- Recycled-Content Premium Positioning:Retail chain sustainability mandates create contract premiums for converters with verified circular supply chains.
- Barrier Technology Convergence:Oxygen-scavenging additives combined with multilayer coextrusion unlock extended shelf-life applications in edible oils and dairy.
Industry Challenges
- Polymer Chemist Talent Scarcity:Local universities produce insufficient formulation specialists to support rapid specification redesign cycles.
- Bureau of Standards Certification Timelines:Food-contact migration testing and pharmaceutical primary packaging approval processes extend commercialization schedules.
- Legacy Extrusion Asset Retrofit Costs:Existing blown film lines require substantial capital modification to process high recycled-content feedstock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Plastic Packaging Market |
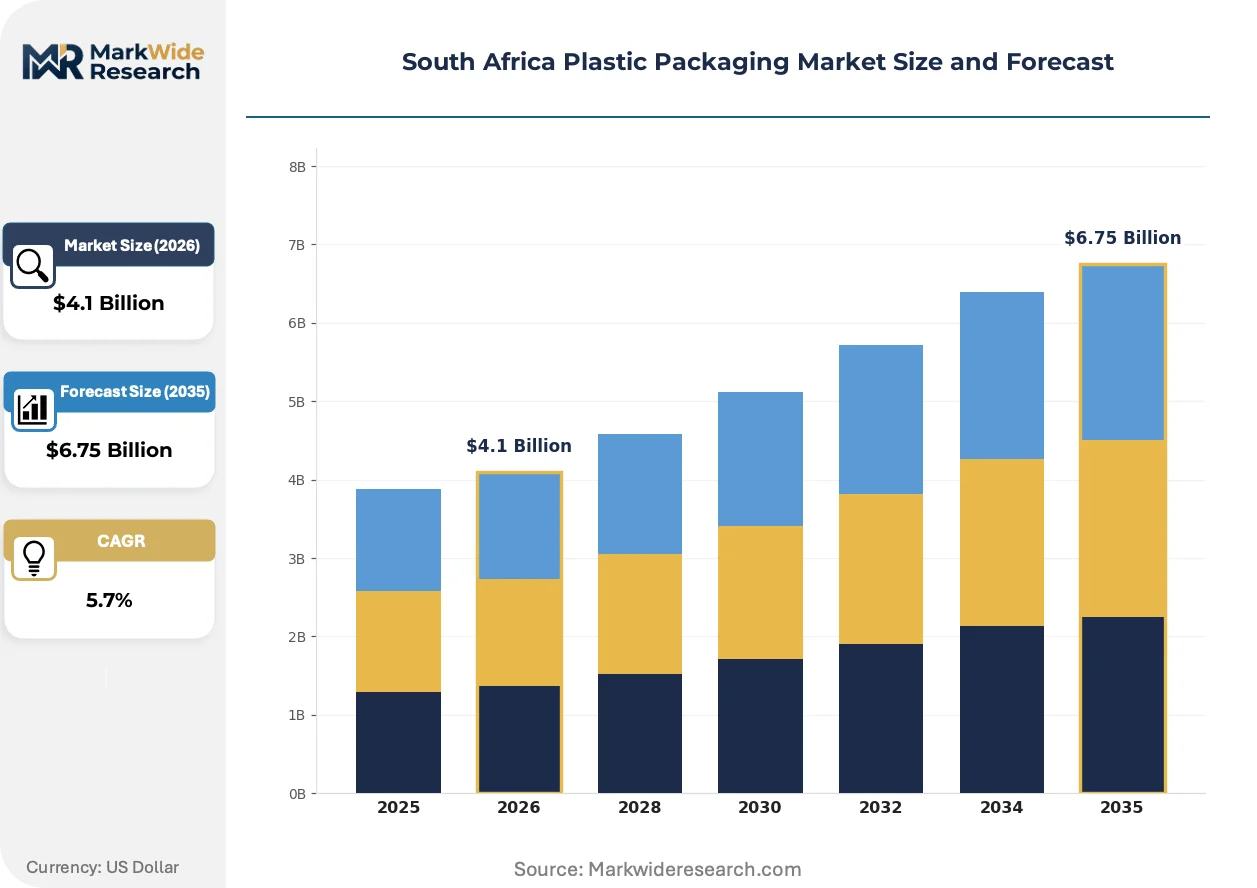
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.75 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Containers, Films, Bottles Material: Polyethylene, Polypropylene, PVC, PET Application: Food Packaging, Beverage Packaging, Healthcare Packaging, Industrial Packaging End User: Retail, Food & Beverage, Pharmaceuticals, Consumer Goods |
| Companies Covered | Nampak Ltd, Mpact Ltd, Amcor plc, Mondi plc, Constantia Flexibles GmbH, RPC Astrapak Ltd, Polyoak Packaging, Safripol, Foster International Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Plastic Packaging Market Evolving Landscape
Material science advances and regulatory pressure are converging to reshape converter strategies across rigid and flexible formats, with circularity and barrier performance emerging as the dominant technical battlegrounds.
Multilayer coextrusion technology is consolidating position in high-barrier dairy and edible oil applications. Major retail chains now specify oxygen transmission rates below 0.5 cc per square meter per day for sensitive products. This technical threshold is compressing the viable supplier base to converters with captive multilayer capacity.
The Department of Forestry, Fisheries and the Environment's extended producer responsibility framework tightens compliance timelines annually. Converters must demonstrate verified post-consumer collection tonnages or face market access restrictions. Flexible bag producers in Gauteng are responding by integrating mechanical recycling partnerships directly into supply agreements.
Buyer consolidation among national retail chains is compressing procurement cycles and unbundling technical service from unit pricing. Category managers now demand lifecycle carbon data and recycled-content certificates as standard bid components. This behavioral shift concentrates contract awards with converters possessing integrated sustainability verification systems.
South Africa Plastic Packaging Market Segmentation
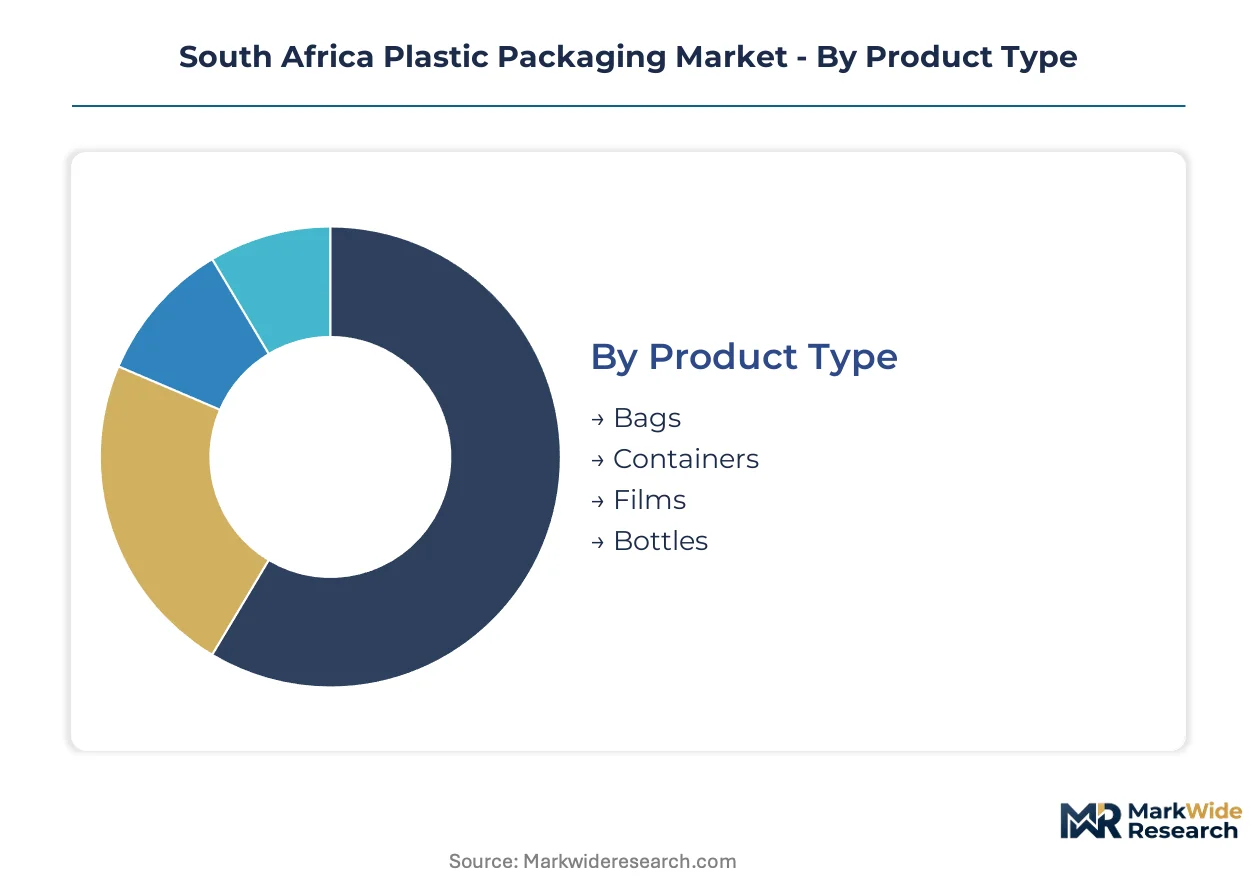
Segmentation reveals how regulatory pressure and supply chain configuration distribute value across South Africa's plastic packaging landscape. Converter specialization patterns align closely with Bureau of Standards certification requirements and extended producer responsibility compliance burdens.
Product Type:
Bureau of Standards food-contact migration testing applies differentially across rigid and flexible formats, with bottles and containers facing the most stringent pharmaceutical-grade protocols.
- Bottles:Blow-molded PET and HDPE structures dominate beverage and personal care applications. Demand concentrates in Gauteng's Johannesburg-Pretoria corridor, where Coca-Cola Beverages South Africa and SAB anchor rigid container procurement. Cold-chain pharmaceutical distribution is accelerating demand for barrier-enhanced PET vials.
- Films:Blown and cast polyethylene structures range from 0.15 mm produce wraps to 0.5 mm industrial liners. Fresh produce packaging in Western Cape agricultural zones drives tonnage, though paper substitution pressure is compressing growth in retail carryout applications.
- Containers:Injection-molded tubs and pails serve dairy, edible oil, and chemical sectors. Multilayer coextrusion capability separates tier-one suppliers from commodity converters in this segment.
- Bags:Flexible polyethylene sacks handle grain, fertilizer, and retail merchandise. Post-consumer collection partnerships are becoming mandatory for contract retention with Shoprite and Pick n Pay.
Films sits at the top of the volume ranking, with bottles climbing the fastest.
Material:
Resin selection determines circularity compliance feasibility and barrier performance ceilings across application segments.
- Polyethylene:LDPE and HDPE grades constitute the tonnage backbone, spanning films, bottles, and injection-molded containers. Recycling infrastructure maturity favors PE in extended producer responsibility schemes, though imported resin dependency exposes converters to rand-dollar volatility.
- PET:Bottle-grade and thermoforming sheet grades command premium positioning in beverage and pharmaceutical primary packaging. Local flake-to-resin recycling capacity is expanding to meet retail chain recycled-content mandates.
- Polypropylene:Homopolymer and copolymer grades serve caps, closures, and thin-wall containers. Higher melt temperatures complicate mechanical recycling integration relative to PE streams.
- PVC:Rigid and flexible formulations persist in pharmaceutical blister packs and construction applications. Regulatory scrutiny on plasticizer migration limits food-contact expansion.
Polyethylene dominates absolute tonnage, while PET gains share fastest on beverage and pharmaceutical demand.
Application:
End-use sector determines the regulatory intensity and certification timeline burden converters must absorb.
- Food Packaging:Spans flexible produce films, rigid dairy containers, and modified-atmosphere meat trays. Retail chain consolidation is compressing supplier counts while elevating lifecycle carbon documentation requirements.
- Beverage Packaging:PET bottles and HDPE closures face the most advanced recycled-content specifications from Coca-Cola and PepsiCo bottling partners. Nampak and Mpact compete on verified circular feedstock access.
- Healthcare Packaging:Cold-chain pharmaceutical distribution is expanding demand for barrier vials, blister foils, and temperature-indicating labels. Bureau of Standards pharmaceutical primary packaging certification timelines extend commercialization cycles.
- Industrial Packaging:Drums, pails, and shrink films serve chemicals, lubricants, and agricultural inputs. Lower regulatory scrutiny permits higher recycled-content ratios than food-contact segments.
Food packaging leads by installed converter capacity, with healthcare packaging expanding most quickly on pharmaceutical logistics investment.
End User:
Customer procurement sophistication varies sharply, with national retail chains imposing sustainability verification systems unavailable to smaller industrial buyers.
- Retail:Shoprite, Pick n Pay, and Woolworths specify recycled-content minimums and post-consumer collection verification. Category managers unbundle technical service from unit pricing, concentrating awards with integrated sustainability systems.
- Food & Beverage:Processors of dairy, edible oils, and beverages demand oxygen transmission rates below 0.5 cc per square meter per day for sensitive products. Multilayer coextrusion capability filters the viable supplier base.
- Pharmaceuticals:Aspen Pharmacare and Adcock Ingram require cold-chain validated primary packaging with batch-level traceability. Certification timelines with the national pharmaceutical regulator extend qualification periods.
- Consumer Goods:Personal care and household product brands prioritize shelf differentiation through decoration and structural design over barrier performance.
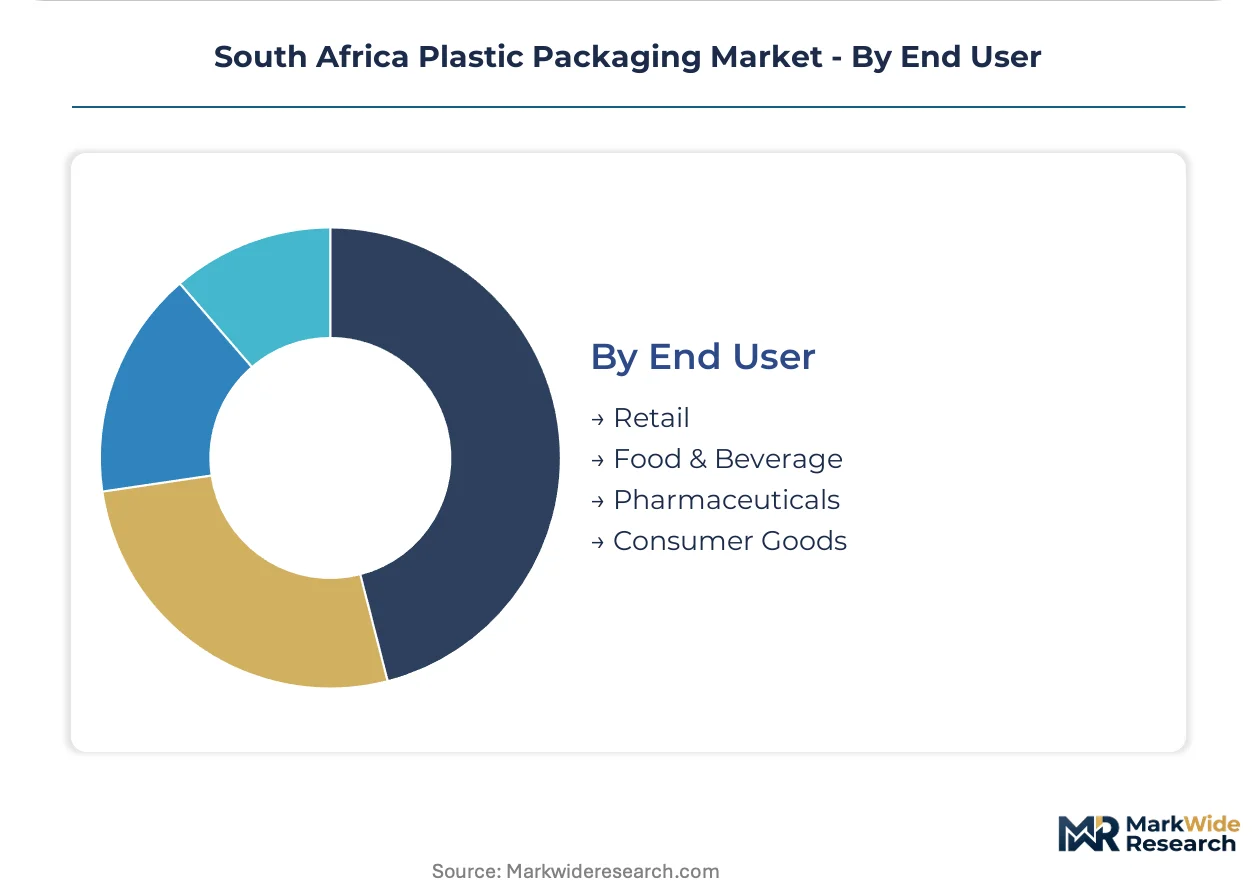
Retail commands the largest procurement volume, with pharmaceuticals showing the steepest expansion trajectory on domestic drug distribution growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing converter capacity across South Africa as extended producer responsibility compliance costs vary by provincial enforcement intensity and recycling infrastructure maturity.
Gauteng Province
The Johannesburg-Pretoria manufacturing corridor concentrates national rigid container demand from Coca-Cola Beverages South Africa and SAB. The Department of Forestry, Fisheries and the Environment enforces collection targets most stringently here, compelling converters to integrate mechanical recycling partnerships. Midrand and Rosslyn industrial zones host the densest extrusion and blow-molding capacity clusters.
Western Cape
Fresh produce packaging dominates tonnage through Stellenbosch and Paarl agricultural processing zones. The provincial environmental affairs department operates pilot deposit-return schemes that test collection models ahead of national rollout. Cape Town port logistics enable flexible film exports to sub-Saharan African markets.
KwaZulu-Natal
Durban's petrochemical proximity and Richards Bay polymer import terminals anchor resin distribution networks. The provincial industrial development corporation incentivizes recycled-content facility investments through tax abatements. Pinetown and New Germany house captive converting lines serving beverage and personal care sectors.
Eastern Cape
Automotive component packaging and agricultural chemical containers drive specialized demand around Gqeberha and East London. The Coega Special Economic Zone offers duty exemptions for packaging machinery imports. Converter presence remains thinner than in Gauteng or KwaZulu-Natal.
South Africa Plastic Packaging Market Competitive Landscape
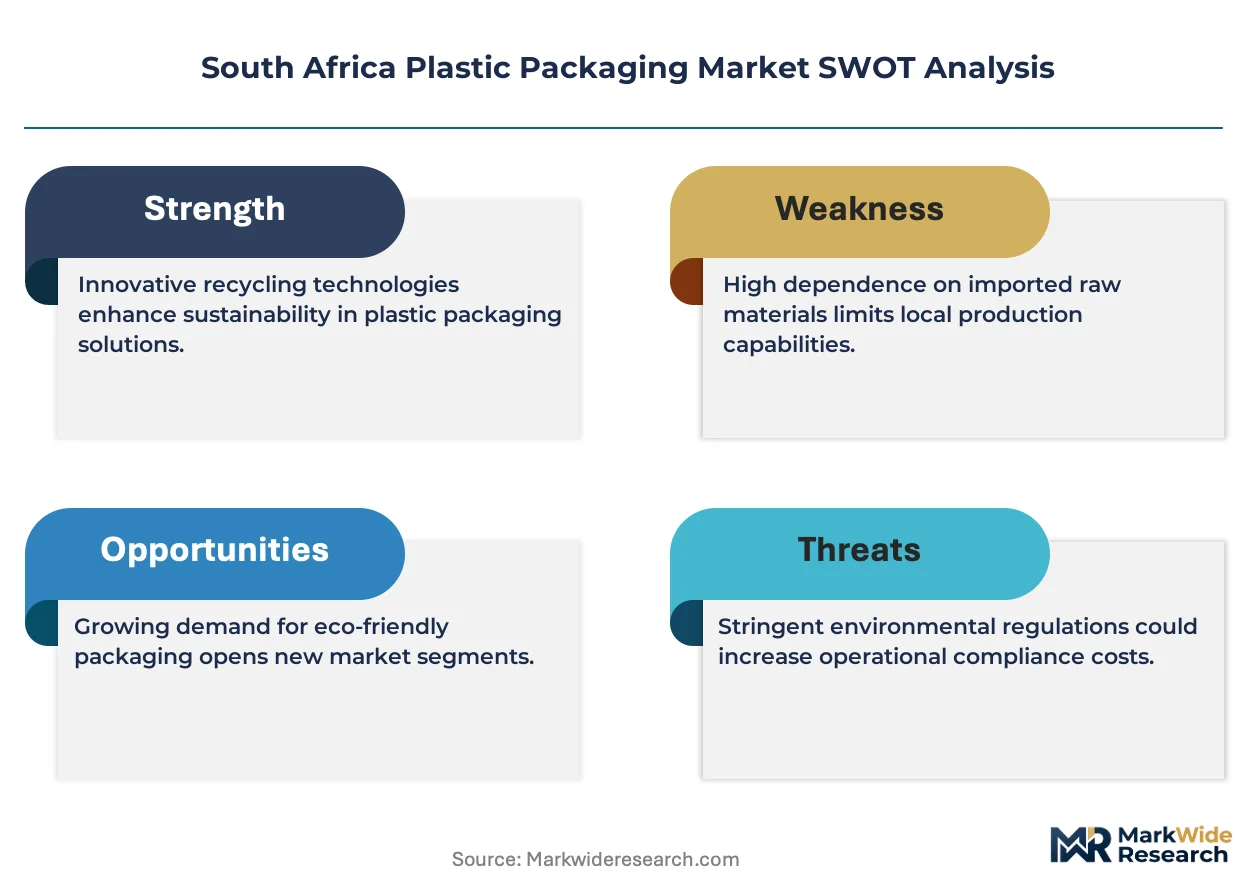
Established producers occupy the standard tier; emerging entrants pursue recycled-content certification and barrier technology specialization. The market structures around three tiers: integrated resin-to-package converters with captive polymer supply, independent converters reliant on merchant resin, and niche specialists in pharmaceutical-grade or food-contact certified formats. Dominant competitive moves include backward integration into recycling feedstock collection and strategic partnerships with retail chains for verified circular supply chains.
Among South Africa-based integrated packaging groups, Nampak Ltd and Mpact Ltd exemplify the resin-to-retail archetype with captive converting infrastructure across multiple provinces. Polyoak Packaging occupies a specialist position within injection-molded closures and dairy sector formats. These three entities represent distinct competitive postures: integrated scale, recycled-content leadership, and application-specific technical depth.
| Leading Market Players |
|---|
| Nampak Ltd |
| Mpact Ltd |
| Amcor plc |
| Mondi plc |
| Constantia Flexibles GmbH |
| RPC Astrapak Ltd |
| Polyoak Packaging |
| Safripol |
| Foster International Packaging |
| Others |
Value Network & Pricing Analysis
Captive resin-to-package integration anchors both supply security and pricing power for South Africa's leading converters, insulating Nampak and Mpact from rand-dollar volatility while compressing margins for merchant-resin-dependent competitors.
Pricing Analysis
Retailer markup compression unbundles technical service from unit pricing across Gauteng procurement corridors. Three-tier pricing structure across premium, standard, and economy levels filters the viable supplier base, with multilayer barrier capability commanding premium positioning in dairy and edible oil segments. Cost compression in standard-grade flexible film is intensifying because paper substitution pressure accelerates in fresh produce applications. Industrial buyers show highest price sensitivity, while pharmaceutical and beverage segments absorb premium tiers for certified barrier performance.
Supply Chain Analysis
Post-consumer collection flows and mechanical recycling partnerships are reshaping feedstock sourcing patterns across the value chain. Raw material sourcing draws from Saudi Arabia, China, and domestic Safripol polymer production, with polyethylene and PET constituting the dominant resin dependencies. Single-source vulnerability concentrates in imported virgin resin channels exposed to shipping disruptions and currency swings. Distribution runs through Johannesburg-Pretoria manufacturing corridors for rigid containers and Cape Town port logistics for flexible film exports to sub-Saharan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in recycled-content premium tiers and barrier technology specialization, with converters capturing value through verified circular supply chains and oxygen-scavenging multilayer specifications.
For Market Incumbents: Anticipate regulatory enforcement cadence from the Department of Forestry, Fisheries and the Environment by accelerating mechanical recycling partnerships ahead of compliance deadlines. Defensive consolidation through backward integration into recycling feedstock collection secures circular material access against emerging entrants with retail chain sustainability mandates. For New Entrants and Emerging Players: The premium-to-economy price-point gap in pharmaceutical-grade barrier packaging offers white-space entry for certified converters. Target cold-chain pharmaceutical distribution with Bureau of Standards-certified PET vials and temperature-indicating label formats, leveraging extended certification timelines as incumbency barriers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap converters with captive multilayer coextrusion capability because retail chain consolidation concentrates procurement with integrated sustainability verification systems. Acquisition target archetypes include mechanical recycling operators and barrier technology specialists. Practitioners should monitor recycler capacity buildout against regulatory collection targets for inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Partnership | Secures verified post-consumer feedstock for extended producer responsibility compliance with Shoprite and Pick n Pay. |
| Multilayer Coextrusion Capacity Addition | Unlocks oxygen transmission rates below 0.5 cc per square meter per day for dairy and edible oil contracts. |
| Bureau of Standards Certification Investment | Accelerates food-contact migration testing and pharmaceutical primary packaging approval timelines. |
| KwaZulu-Natal Port Proximity Expansion | Enables export-oriented rigid container production for regional African beverage markets. |
| Barrier Technology R&D Program | Develops oxygen-scavenging additives for extended shelf-life applications in sensitive product segments. |
Research Methodology
Direct dialogue with polymer chemists, converter plant managers, retail category buyers, and recycling facility operators combined with secondary validation from South African Bureau of Standards certification records, customs trade data, and Department of Forestry, Fisheries and the Environment regulatory filings. Bottom-up and top-down triangulation cross-validates capacity estimates against procurement volume disclosures.
Bottom-up modeling builds from individual converter capacity, resin throughput, and application-specific pricing, while top-down analysis benchmarks against national packaging consumption patterns and retail sales data across the projection horizon. Segmentation dimensions include product type, material grade, application sector, and end-user procurement sophistication. CAGRs derive from regression analysis of historical volume trajectories and regulatory compliance cost absorption rates.
Caveats apply where rand-dollar volatility, recycler capacity shortfalls, or paper substitution acceleration could materially shift the outlook. Practitioners should monitor Department of Forestry, Fisheries and the Environment enforcement cadence and mechanical recycling partnership announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market