
 North America Oxygen Concentrators Market | 2026-2036
North America Oxygen Concentrators Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oxygen Concentrators Market Intelligence
CMS competitive bidding is repositioning the cost-of-entry calculus for oxygen therapy suppliers across the United States. Inogen, Inc. leverages direct-to-consumer channel control to sustain margins amid reimbursement compression. CAIRE Inc. anchors its position through portable system specialization and battery chemistry leadership. Invacare Corporation competes via rehabilitation center relationships and durable medical equipment distribution scale.
An oxygen concentrator is an electrically powered medical device that extracts ambient air, compresses it through molecular sieve beds, and delivers concentrated oxygen at flow rates typically ranging from 0.5 to 10 liters per minute for therapeutic use in patients with chronic respiratory insufficiency. Portable units weighing under ten pounds now dominate ambulatory prescriptions, while stationary systems above twenty pounds retain installed base relevance for nocturnal and high-flow prescriptions. PSA technology leads unit economics and reliability metrics, though membrane systems carve niche positions in travel and military applications where vibration tolerance matters.
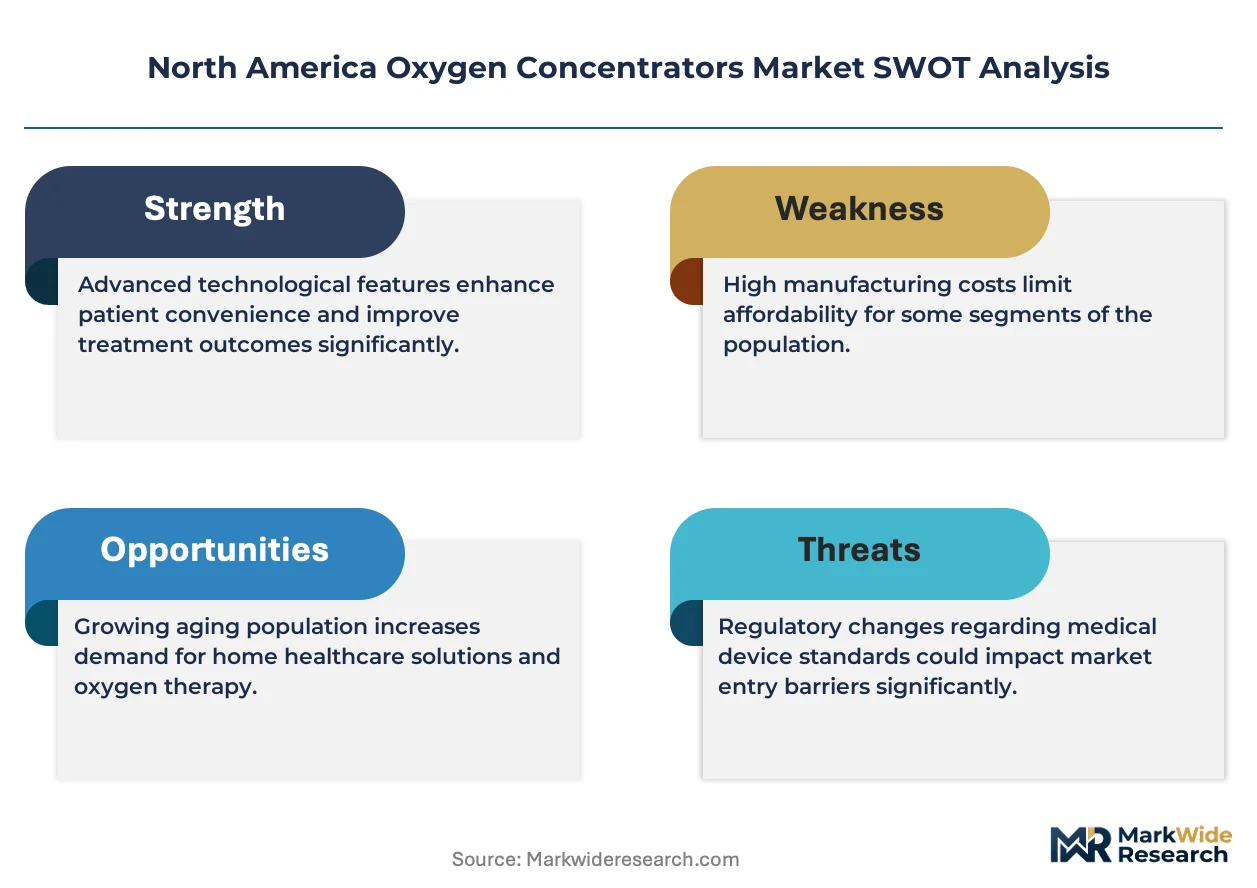
FDA 510(k) clearance requirements and CMS national coverage determinations shape product development timelines and reimbursement access across the United States, while Health Canada medical device licensing governs northern market entry. The EPA Energy Star program and DOE appliance efficiency standards increasingly influence concentrator power consumption specifications and manufacturer R&D allocation. Stakeholders must monitor how pulse-dose algorithm patents, solid-state oxygen separation research, and state-level Medicaid managed care procurement consolidation reshape competitive advantage without warning.
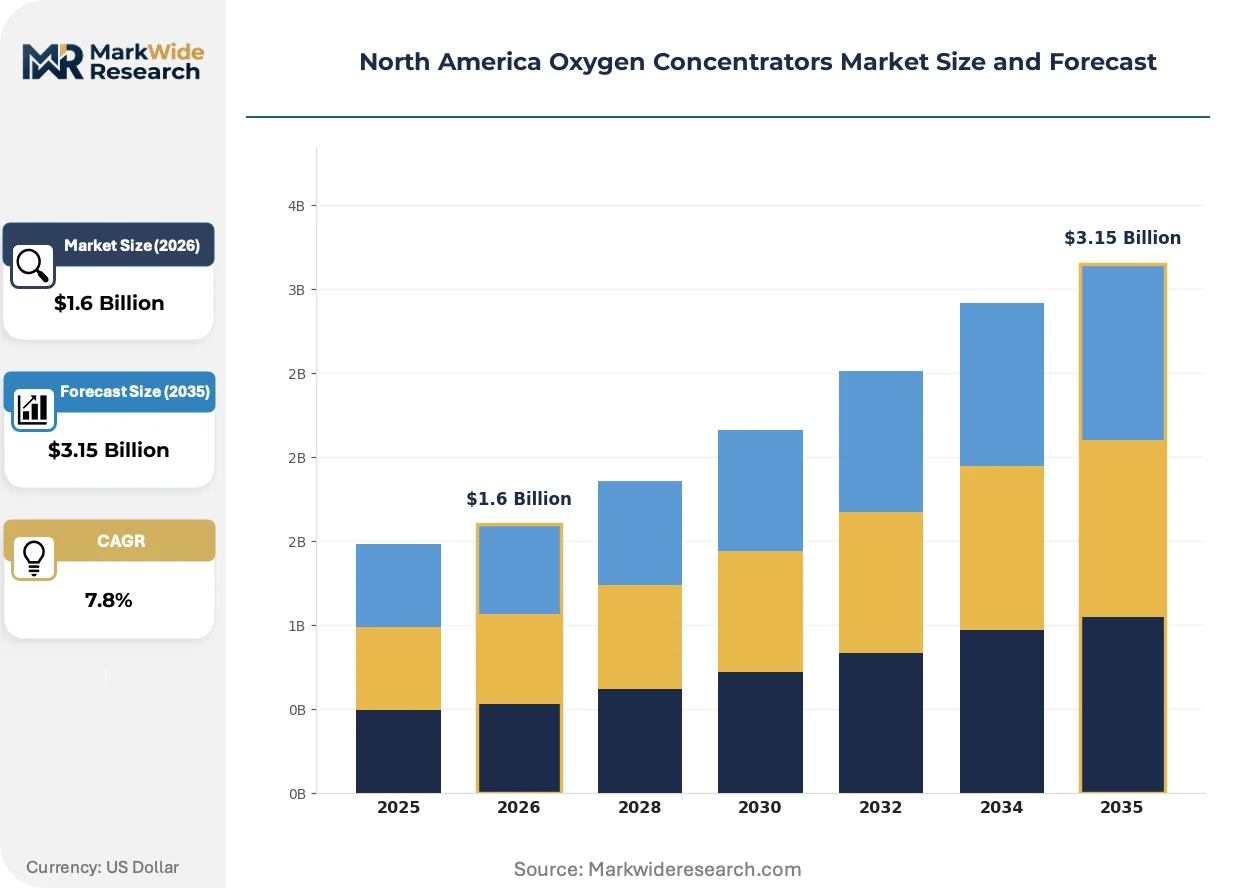
Market Dynamics
Medicare competitive bidding is compressing reimbursement rates for stationary oxygen equipment while simultaneously accelerating portable device procurement through revised durable medical equipment fee schedules.
Growth Catalysts
- CMS Reimbursement Realignment:The Medicare competitive bidding program's expanded coverage for portable oxygen concentrators is redirecting capital toward ambulatory delivery systems across homecare provider networks.
- Pulse-Dose Algorithm Refinement:Advanced oxygen-sensing electronics are extending battery runtime in portable units, enabling longer ambulatory coverage without weight penalties.
- Southeastern Demographic Concentration:Elevated COPD prevalence in Florida, Georgia, and Alabama is sustaining replacement demand cycles above national averages.
Market Restraints
- Molecular Sieve Zeolite Supply:Concentrated sourcing of lithium-exchanged zeolites from limited specialty chemical producers creates input vulnerability for PSA system manufacturers.
- FDA 510(k) Timeline Compression:Extended clearance durations for algorithm-modified pulse-dose devices delay product launches and compress commercialization windows.
- Stationary System Obsolescence Risk:Reimbursement rate reductions for continuous-flow equipment threaten installed base service economics for legacy rental fleets.
Strategic Opportunities
- Medicaid Managed Care Consolidation:State-level procurement aggregation in Texas and California creates volume contracting opportunities for multi-state equipment lessors.
- Solid-State Oxygen Separation Convergence:Electrochemical ceramic membrane integration with portable electronics architectures promises vibration-tolerant alternatives to compressor-based systems.
- Direct-to-Patient Channel Development:E-commerce fulfillment bypassing traditional durable medical equipment distributors captures margin from compressed reimbursement spreads.
Industry Challenges
- Biomedical Technician Certification Bottlenecks:EPA Section 608 refrigerant handling credentials and FDA device servicing qualifications constrain field service capacity expansion.
- Legacy Fleet Integration Complexity:Pulse-dose portable units require protocol retraining for respiratory therapists accustomed to continuous-flow titration practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oxygen Concentrators Market |
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Home-Based, Liquid Oxygen End User: Hospitals, Homecare, Rehabilitation Centers, Long-term Care Facilities Technology: PSA, Membrane, Cryogenic, Vacuum Pressure Swing Adsorption Distribution Channel: Online, Retail, Direct Sales, Third-Party Distributors |
| Companies Covered | Inogen, Inc., CAIRE Inc., Invacare Corporation, DeVilbiss Healthcare, Nidek Medical Products, Inc., O2 Concepts, React Health, GF Health Products, Inc., Direct Supply, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oxygen Concentrators Market Strategic Shifts & Innovations
Product architecture is bifurcating between lightweight ambulatory systems and connected stationary platforms, with software-defined oxygen delivery emerging as the primary competitive differentiator.
Portable concentrator technology is decentralizing oxygen therapy delivery from institutional settings to patient-controlled environments. Homecare providers are adopting sub-five-pound pulse-dose units for 24/7 mobile coverage. This shift is decentralizing service revenue from rental models toward direct equipment ownership and subscription-based remote monitoring.
EPA Energy Star 3.0 specifications for medical device power consumption are forcing compressor motor efficiency upgrades and standby power reductions. Manufacturers must redesign thermal management systems to meet the new thresholds. Stationary concentrator portfolios face the steepest redesign costs, with production lines in Mexico and the United States retooling through 2026.
Buyer contracting is consolidating around outcomes-based equipment performance guarantees rather than per-unit rental rates. Large homecare networks are unbundling device provision from clinical respiratory therapy services. This restructuring is most visible in Medicare Advantage plan territories, where capitated payments incentivize total cost-of-therapy reduction over device utilization maximization.
North America Oxygen Concentrators Market Segmentation
Segmentation in oxygen concentrators reveals divergent engineering priorities across mobility requirements, care settings, and oxygen delivery physics. Each dimension carries distinct reimbursement pathways and regulatory compliance burdens that reshape supplier economics.
Product Type:
Standardization dominates portable and stationary categories, while home-based systems and liquid oxygen demand bespoke installation protocols and clinical integration.
- Portable:Pulse-dose algorithms and lithium-ion battery architectures enable sub-five-pound ambulatory units. Demand concentrates in Medicare Advantage territories across Florida and Texas, where competitive bidding accelerates patient-owned equipment substitution for rental fleets.
- Stationary:Continuous-flow compressors delivering 5-10 LPM anchor nocturnal and high-flow prescriptions. Southeastern United States nursing facilities sustain replacement cycles as legacy rental contracts expire under CMS reimbursement compression.
- Home-Based:Integrated concentrator-ventilator hybrids for complex respiratory failure.
- Liquid Oxygen:Cryogenic reservoir systems for high-flow ambulatory patients requiring extended duration away from power sources.
Leading the category by volume: Portable. Growing fastest: Home-Based.
End User:
Cost tier stratification separates acute institutional procurement from distributed homecare reimbursement models.
- Homecare:Medicare-certified durable medical equipment suppliers deploy pulse-dose portables through competitive bidding territories. CMS fee schedule realignment in southeastern states redirects capital toward patient-owned ambulatory systems.
- Hospitals:Centralized oxygen pipeline systems and bedside concentrators for emergency departments and step-down units. Academic medical centers in California and New York drive specifications for integrated alarm telemetry.
- Rehabilitation Centers:Post-acute respiratory therapy protocols bridging hospital discharge to home oxygen.
- Long-term Care Facilities:Skilled nursing facility concentrator fleets under Medicaid managed care capitation.
Dominating procurement value: Homecare. Expanding most quickly: Rehabilitation Centers.
Technology:
Application physics separate pressure-swing dominance from membrane niche positioning.
- PSA:Zeolite molecular sieve beds compress ambient air through alternating pressure cycles. PSA systems command installed base across United States homecare networks due to reliability metrics and CMS reimbursement familiarity.
- Membrane:Polymer fiber bundles separate oxygen via differential permeation without moving parts. Demand clusters in military and aviation applications where vibration tolerance outweighs efficiency penalties.
- Cryogenic:Liquid oxygen production for centralized supply and high-flow ambulatory reservoirs.
- Vacuum Pressure Swing Adsorption:Modified PSA with vacuum regeneration for enhanced oxygen purity in compact footprints.
Highest volume production: PSA. Steepest expansion trajectory: Vacuum Pressure Swing Adsorption.
Distribution Channel:
Margin structure differentiates direct channel control from third-party distributor dependency.
- Direct Sales:Manufacturer-to-provider contracts bypass distributor markups. Direct channels capture margin compression from Medicare competitive bidding through volume commitments with multi-state homecare networks.
- Third-Party Distributors:Regional durable medical equipment wholesalers manage logistics and field service. Distributor relationships dominate legacy stationary system rentals in rural Medicare jurisdictions.
- Online:E-commerce fulfillment of patient-owned portables with remote clinical onboarding.
- Retail:Pharmacy and medical supply storefronts for cash-pay accessory sales.
Largest transaction volume: Third-Party Distributors. Gaining share fastest: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone 74 in Miami concentrates oxygen concentrator distribution for Caribbean and Latin American re-export, leveraging duty-deferred warehousing and expedited FDA inspection protocols to anchor regional logistics gravity.
United States
CMS competitive bidding and Medicare Advantage capitation drive portable device procurement across Florida, Texas, and California. FDA 510(k) clearance timelines shape product launch cadences for algorithm-modified pulse-dose systems. The southeastern nursing facility corridor from Atlanta to Tampa sustains stationary concentrator replacement cycles as legacy rental contracts expire.
Canada
Health Canada medical device licensing governs market entry for PSA and membrane concentrator technologies. Provincial health authority procurement consolidation in Ontario and British Columbia shifts volume toward multi-year equipment leasing. Calgary and Edmonton clusters concentrate homecare provider networks serving remote northern territories with portable oxygen solutions.
Mexico
COFEPRIS regulatory alignment with FDA standards accelerates cross-border manufacturing integration for compressor assemblies and battery packs. IMSS public health system tenders in Mexico City and Guadalajara drive demand for cost-optimized stationary units. Baja California maquiladora operations supply molecular sieve zeolite components to US-based PSA system assemblers.
North America Oxygen Concentrators Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the North American oxygen concentrator landscape. The vendor base separates into three tiers: multinational medical device conglomerates with rehabilitation equipment portfolios, dedicated respiratory therapy specialists with pulse-dose patent estates, and regional durable medical equipment distributors with service fleet scale. Consolidation pressure intensifies as Medicare reimbursement compression favors volume contracting and direct-to-patient channel control over traditional distributor relationships.
Among US-based specialists, Inogen, Inc. and CAIRE Inc. exemplify the pure-play archetype with concentrated exposure to portable oxygen concentrator technology and ambulatory care reimbursement dynamics. Invacare Corporation represents the diversified conglomerate model with rehabilitation center relationships and durable medical equipment distribution infrastructure spanning multiple therapeutic categories. These three anchors illustrate the strategic bifurcation between focused technology development and broad service network coverage that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Inogen, Inc. |
| CAIRE Inc. |
| Invacare Corporation |
| DeVilbiss Healthcare |
| Nidek Medical Products, Inc. |
| O2 Concepts |
| React Health |
| GF Health Products, Inc. |
| Direct Supply |
| Others |
Cost & Logistics Intelligence
Biomedical technician certification clusters in the southeastern United States widen labor-cost differentials between premium service-contract tiers and economy self-service models, compressing mid-market pricing bands as homecare providers arbitrage field-service availability against reimbursement spreads.
Pricing Analysis
Lead-time premiums for FDA 510(k)-cleared pulse-dose devices command substantial markups over spot inventory of legacy continuous-flow units. Three-tier pricing structure across premium algorithm-enabled, standard PSA-based, and economy refurbished tiers separates reimbursement-eligible prescriptions from cash-pay alternatives. Cost compression in the standard tier intensifies because Medicare competitive bidding squeezes durable medical equipment supplier margins. Medicaid managed care plans exhibit highest price sensitivity; hospital procurement committees demonstrate lowest sensitivity due to bundled payment structures.
Supply Chain Analysis
Direct-to-homecare provider channels handle volume contracting with multi-state networks, while third-party distributors manage rural Medicare jurisdiction logistics. Manufacturing concentrates in Mexico, the United States, and China for compressor assemblies, battery packs, and molecular sieve zeolites respectively. PSA system production draws from lithium-exchanged zeolite feedstock anchored in specialty chemical producers. Single-source vulnerability for zeolite molecular sieves threatens input continuity. Distribution runs through regional durable medical equipment wholesalers with EPA Section 608 certified service fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over pulse-dose algorithm patents and lithium-ion battery pack assembly determines margin capture against reimbursement compression.
For Market Incumbents: Lock in exclusive sourcing agreements with molecular sieve zeolite producers to preempt input cost volatility. Secure backward integration into battery pack assembly through maquiladora operations in Baja California. Consolidate field-service capacity by acquiring EPA-certified biomedical technician networks before competitive bidding territories expand. For New Entrants and Emerging Players: The mid-tier price-point gap between Inogen's premium portables and refurbished economy units opens white-space for algorithm-licensed, white-label manufacturing. Target state-level Medicaid managed care procurement consolidation in Texas and California with direct-to-patient e-commerce fulfillment. Pursue software-defined oxygen delivery as the primary differentiation vector against hardware-locked incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play portable specialists given Medicare Advantage capitation acceleration. Evaluate acquisition targets with pulse-dose patent estates and direct-to-consumer channel infrastructure. Monitor FDA 510(k) clearance timeline compression as the inflection indicator for product launch cadence and commercialization window viability.| Strategic Initiative | Industry Significance |
|---|---|
| Pulse-Dose Algorithm Patent Acquisition | CMS reimbursement alignment favors algorithm-enabled portable systems over continuous-flow legacy equipment. |
| Direct-to-Patient E-Commerce Launch | Medicare competitive bidding compression makes distributor-bypass margin capture essential for homecare providers. |
| Battery Chemistry Vertical Integration | Lithium-ion pack assembly control extends portable runtime without weight penalties in ambulatory prescriptions. |
| EPA Energy Star 3.0 Certification Pathway | Power consumption specifications reshape thermal management R&D allocation for stationary concentrator portfolios. |
| Medicaid Managed Care Volume Contracting | State-level procurement aggregation in Texas and California creates multi-year equipment leasing opportunities. |
Research Approach
FDA 510(k) filings, CMS Medicare reimbursement databases, and Health Canada medical device licensing records formed the secondary backbone for regulatory pathway mapping. Primary interviews with biomedical engineers, homecare procurement directors, GPO contracts managers, and respiratory therapists validated demand assumptions. Bottom-up unit shipment estimates triangulated against top-down reimbursement expenditure analysis.
Historical trendline analysis across installed base replacement cycles, competitive bidding territory expansions, and portable device adoption curves informed projection modeling. Segmentation dimensions included product mobility class, oxygen delivery physics, end-use setting, and distribution channel structure. CAGRs derived from regression analysis against demographic COPD prevalence and reimbursement policy trajectories. Pulse-dose algorithm patent expiration schedules and solid-state oxygen separation research milestones served as technology disruption inputs.
Inputs from FDA premarket notification databases and CMS fee schedule archives were available through the study window; gaps in state-level Medicaid managed care contract terms introduce uncertainty bands around volume forecasting. Forecasts reflect assumptions regarding competitive bidding program continuity and zeolite supply chain stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Urine Collection Devices Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Education Microscope Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Capsule Endoscope Systems Market