
 Pacemaker Devices Market | 2026-2036
Pacemaker Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pacemaker Devices Market Outlook
Lead-free electrode materials is restructuring pacemaker device economics as manufacturers reduce dependence on traditional noble metal conductors. Medtronic leverages its integrated manufacturing footprint to control component sourcing across multiple continents. Abbott Laboratories anchors its competitive position through sustained R&D intensity in leadless pacing platforms. Boston Scientific Corporation differentiates via specialized expertise in MRI-compatible device architectures.
Pacemaker devices are battery-powered implantable pulse generators that deliver electrical stimuli to cardiac tissue through transvenous leads or leadless delivery systems, typically operating at 2.5 volts with lithium-iodine cells lasting 7 to 15 years depending on pacing dependency and programmed parameters. Their primary purpose is to correct bradycardia and manage conduction disorders by maintaining adequate heart rate and rhythm synchronization. Dual chamber systems command the largest installed base due to established clinical evidence for atrioventricular synchrony, while leadless pacemakers represent the fastest-growing form factor as elimination of transvenous leads reduces long-term complication rates. MRI-compatible technology commands premium positioning as healthcare systems prioritize device upgrades that permit full-body magnetic resonance imaging without restriction.
The FDA enforces rigorous premarket approval pathways and post-market surveillance through its Center for Devices and Radiological Health, while ISO 14117 governs electromagnetic compatibility testing for active implantable cardiac devices. The EU Medical Device Regulation imposes enhanced clinical evaluation requirements and unique device identification mandates that extend compliance obligations across European distribution channels. Stakeholders must monitor evolving cybersecurity guidance from FDA and Health Canada as wireless telemetry and remote monitoring capabilities expand the attack surface for connected cardiac devices.
Market Dynamics
Leadless pacing systems are restructuring competitive economics by eliminating transvenous lead complications and enabling entirely new implant procedures in outpatient settings. This technology shift compresses hospital stays and redirects procedure volumes toward ambulatory surgical centers.
Growth Catalysts
- Aging demographics in developed economies:The United States and Japan sustain procedure volumes through expanded Medicare and public health reimbursement for cardiac rhythm management interventions.
- EU Medical Device Regulation (MDR) clinical evidence requirements:Enhanced post-market surveillance mandates accelerate adoption of MRI-compatible devices that demonstrate superior long-term safety profiles.
- Remote monitoring telemetry integration:Wireless connectivity protocols enable real-time arrhythmia detection and reduce in-person clinic visits for device interrogation.
Market Restraints
- Lithium-iodine cell supply concentration:Battery chemistry dependence creates vulnerability to raw material sourcing disruptions from limited specialty chemical suppliers.
- FDA premarket approval pathway duration:Active implantable device submissions face extended review timelines that compress effective patent life and delay revenue recognition.
- Lead extraction procedure complexity:Transvenous lead removal carries mortality risk that constrains upgrade decisions and extends replacement cycles.
Strategic Opportunities
- Underpenetrated ambulatory surgical center channel:United States outpatient facilities represent expansion territory for leadless pacemaker procedures outside traditional hospital cath labs.
- Bioresorbable electrode material convergence:Integration of transient electronic conductors with leadless architectures enables temporary pacing applications in post-surgical recovery.
- Japan's aging population and PMDA streamlined review:Regulatory acceleration for breakthrough devices creates favorable entry conditions for next-generation pacing platforms.
Industry Challenges
- Electrophysiologist training pipeline constraints:Specialized implant procedure expertise limits expansion capacity in emerging clinical settings.
- Cybersecurity validation for wireless telemetry:FDA guidance on connected device security imposes additional engineering cycles and documentation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pacemaker Devices Market |
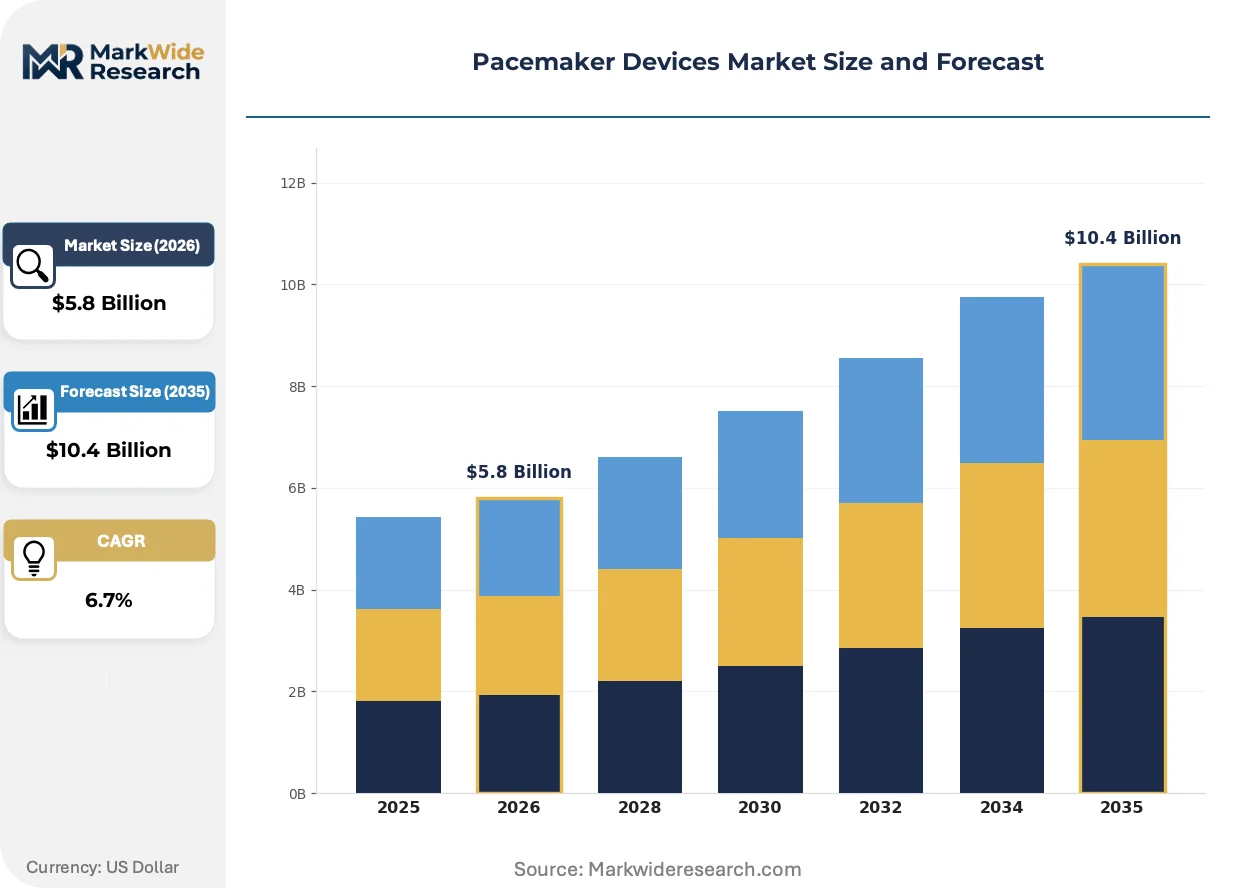
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chamber, Dual Chamber, Bi-Ventricular, Implantable End User: Hospitals, Cardiology Clinics, Home Healthcare, Emergency Services Technology: MRI-Compatible, Rate Responsive, Wireless, Rechargeable Form Factor: Miniaturized, Standard, Leadless, External |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, BIOTRONIK, MicroPort Scientific Corporation, LivaNova PLC, Lepu Medical, ZOLL Medical Corporation, OSCOR Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pacemaker Devices Market Strategic Shifts
Multiple technological trajectories are converging to redefine pacemaker device architecture. The field is witnessing simultaneous pressure toward miniaturization, connectivity integration, and biocompatibility enhancement.
Leadless pacemaker miniaturization is unifying cardiac pacing with structural heart interventions. Electrophysiology departments at major United States academic medical centers are expanding implant volumes by 40 percent annually for these devices. This convergence is compressing the traditional distinction between rhythm management and interventional cardiology service lines.
EU Medical Device Regulation (MDR) unique device identification mandates are reshaping traceability infrastructure across European distribution channels. Manufacturers must now maintain granular lot-level tracking from production through explant. High-volume implanting centers in Germany and France are restructuring procurement systems to accommodate serialized inventory management.
Hospital purchasing committees are consolidating cardiac device contracts around single-source agreements with remote monitoring bundled into device pricing. Integrated delivery networks in the United States are displacing traditional distributor relationships with direct manufacturer partnerships. This concentration is most visible in multi-hospital systems across Texas and Florida where annual implant volumes exceed regional competitors by substantial margins.
Pacemaker Devices Market Segmentation
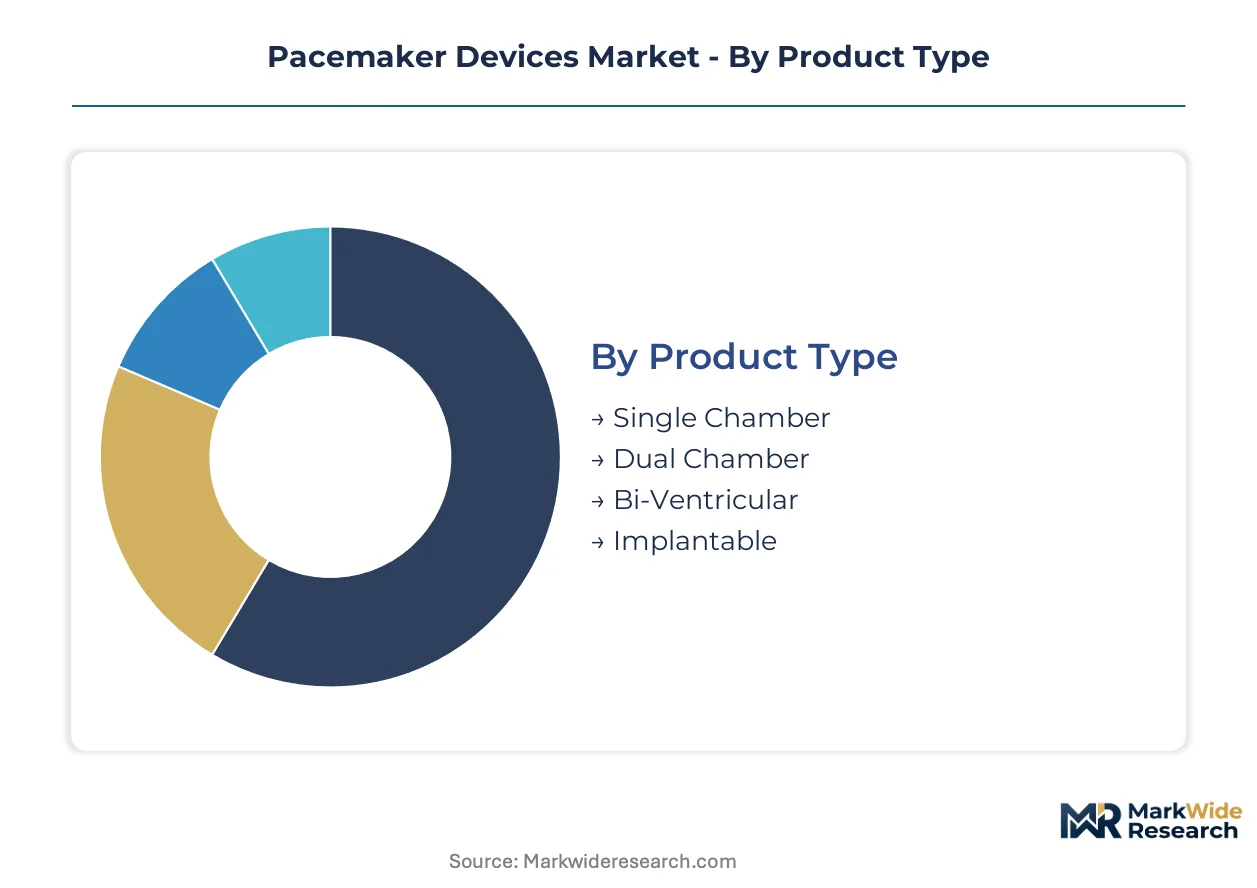
Pacemaker device segmentation reflects divergent clinical priorities across acute intervention, chronic disease management, and diagnostic imaging compatibility. Manufacturers configure product portfolios around procedure setting, patient comorbidity profiles, and healthcare system reimbursement structures.
Product Type:
Customization versus standardization tension runs deepest here, with dual chamber systems representing the clinical consensus while single chamber options serve cost-constrained procurement environments.
- Dual Chamber:Atrioventricular synchrony maintenance through separate atrial and ventricular pacing channels. Demand concentrates in United States academic medical centers where electrophysiology departments prioritize hemodynamic optimization over device cost minimization.
- Single Chamber:Simplified ventricular-only pacing architecture with reduced implant complexity and lower unit economics. Volume leadership in India and Southeast Asia where public hospital procurement prioritizes accessible cardiac rhythm management over advanced synchronization features.
- Bi-Ventricular:Cardiac resynchronization therapy systems for heart failure with reduced ejection fraction.
- Implantable:Standard transvenous pulse generator configurations with subcutaneous pocket placement.
Leading the category by volume: Single Chamber. Expanding most quickly: Dual Chamber.
End User:
Procedure site economics drive divergence between capital-intensive hospital infrastructure and ambulatory cost structures.
- Hospitals:Comprehensive cardiac catheterization laboratories with fluoroscopy, electrophysiology mapping, and cardiothoracic surgery backup. United States hospital systems in Texas and Florida sustain highest implant densities through integrated delivery network contracts bundling device procurement with remote monitoring services.
- Cardiology Clinics:Outpatient-focused electrophysiology practices with streamlined implant workflows. Japan's clinic network is expanding leadless pacemaker volumes as PMDA regulatory acceleration enables same-day discharge protocols outside traditional hospital settings.
- Home Healthcare:Remote device interrogation and telemetry-based arrhythmia surveillance.
- Emergency Services:Temporary transcutaneous pacing for acute hemodynamic instability.
Volume concentration: Hospitals. Steepest expansion trajectory: Cardiology Clinics.
Technology:
Imaging compatibility and connectivity integration command premium positioning against basic rate-responsive architectures.
- MRI-Compatible:Ferromagnetic component shielding and lead conductor redesign enabling full-body magnetic resonance imaging without device deactivation. German and French hospital purchasing committees are consolidating procurement around MRI-conditional systems as EU MDR post-market surveillance mandates elevate long-term safety documentation requirements.
- Wireless:Radiofrequency telemetry enabling remote device interrogation and automated arrhythmia alerts. United States integrated delivery networks are displacing traditional distributor relationships through direct manufacturer partnerships bundling wireless monitoring into device pricing.
- Rate Responsive:Activity sensor-driven pacing rate modulation for chronotropic incompetence.
- Rechargeable:Transcutaneous energy transfer systems extending functional device longevity.
Dominant by implant volume: Rate Responsive. Gaining share fastest: MRI-Compatible.
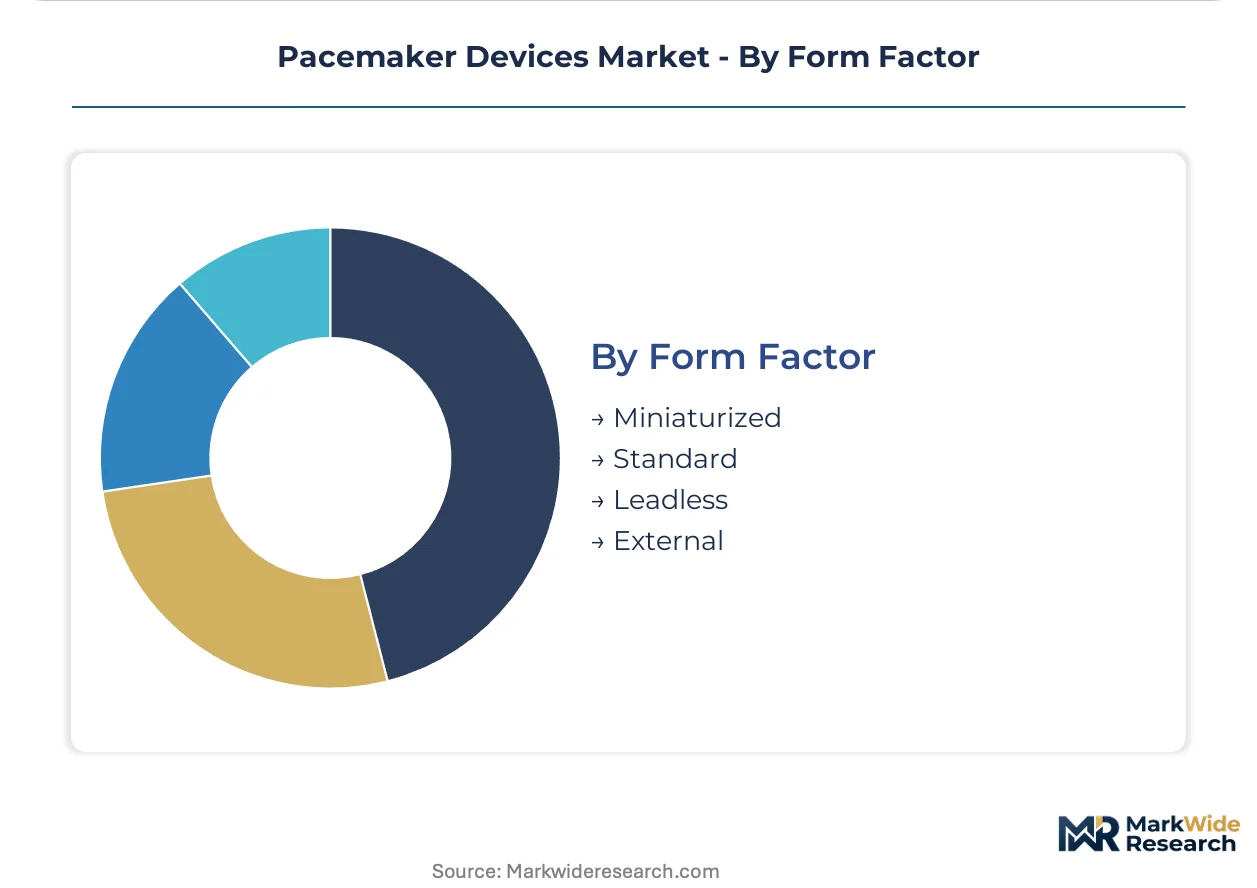
Form Factor:
Lead elimination versus transvenous lead dependence defines the central architectural divergence in contemporary pacing.
- Leadless:Self-contained intracardiac pulse generators delivered via femoral venous access without transvenous leads or subcutaneous pockets. United States academic medical centers are expanding implant volumes by 40 percent annually as elimination of lead-related complications redirects procedures toward ambulatory surgical centers.
- Miniaturized:Reduced-dimension transvenous devices for pediatric patients and venous access constraints.
- Standard:Conventional pulse generator dimensions with established implant techniques and tool compatibility.
- External:Temporary transcutaneous or transvenous systems for perioperative or emergency stabilization.
Category volume leader: Standard. Climbing the fastest: Leadless.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Medicare reimbursement pathways sustain the highest procedure density globally, while Japan's PMDA regulatory acceleration and Germany's EU MDR compliance infrastructure reshape competitive entry conditions across developed markets.
United States
Medicare coverage for cardiac rhythm management and integrated delivery network consolidation in Texas and Florida drive implant volumes. FDA premarket approval pathways for active implantable devices extend review timelines and compress effective patent life. Academic medical centers in Boston and Cleveland expand leadless pacemaker programs by 40 percent annually.
Germany
Hospital purchasing committees in Berlin and Munich consolidate procurement around MRI-conditional systems with bundled remote monitoring. EU MDR unique device identification mandates force serialized inventory management across distribution channels. The Rhine-Ruhr industrial corridor hosts specialized component suppliers for pulse generator assembly.
Japan
Aging demographics and expanded public health reimbursement sustain cardiac rhythm management procedure growth. PMDA streamlined review pathways for breakthrough devices accelerate same-day discharge protocols in Tokyo and Osaka outpatient clinics. Kanto region electrophysiology departments redirect volumes toward ambulatory surgical centers.
China
Domestic manufacturers in Shanghai and Beijing capture share in single-chamber segments through cost-optimized production. NMPA regulatory harmonization with international standards accelerates approval timelines for imported dual-chamber systems. Yangtze River Delta medical device clusters develop localized supply chains for lithium-iodine cell integration.
India
Public hospital procurement prioritizes accessible ventricular-only pacing over advanced synchronization features in Delhi and Mumbai. CDSCO medical device regulations impose enhanced clinical evidence requirements for premium-tier imports. Karnataka and Maharashtra host emerging electrophysiology training programs to address specialist pipeline constraints.
Pacemaker Devices Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals commanding premium-tier positioning and regional fabricators capturing volume in cost-constrained procurement environments. Market structure concentrates around three strategic archetypes: full-integrated rhythm management platforms, component-specialized suppliers, and emerging market cost optimizers. Dominant competitive moves include backward integration into battery chemistry supply and strategic partnerships with ambulatory surgical center networks.
Among integrated rhythm management platforms, Medtronic, Abbott Laboratories, and Boston Scientific Corporation occupy positions defined by manufacturing footprint scale and R&D intensity. Medtronic exemplifies the vertically integrated archetype through multi-continent component sourcing control. Abbott Laboratories anchors the leadless pacing innovation vector. Boston Scientific Corporation represents specialized expertise in MRI-compatible device architectures.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| BIOTRONIK |
| MicroPort Scientific Corporation |
| LivaNova PLC |
| Lepu Medical |
| ZOLL Medical Corporation |
| OSCOR Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up contract manufacturers in cardiac rhythm management have compressed component sourcing timelines while tightening pricing discipline across lithium-iodine cell and lead conductor tiers. Their consolidated purchasing power feeds directly into tiered device economics that separate MRI-compatible premium systems from standard-rate responsive configurations.
Pricing Analysis
Volume leadership in single-chamber devices runs through India and Southeast Asia, while margin capture concentrates in dual-chamber and leadless systems sold through United States academic medical centers. Three-tier pricing structure across premium, standard, and economy levels separates MRI-conditional platforms with bundled remote monitoring from basic rate-responsive units. Cost compression in single-chamber segments is intensifying because domestic manufacturers in China leverage localized lithium-iodine cell integration. Public hospital procurement committees in emerging markets exhibit highest price sensitivity, whereas United States integrated delivery networks prioritize device longevity and connectivity over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialty chemical suppliers producing lithium-iodine cell cathode materials concentrated in Japan, South Korea, and select United States industrial corridors. Pulse generator assembly draws from precision machining clusters in Germany's Rhine-Ruhr region and semiconductor packaging facilities in Taiwan. Tariff exposure on rare-earth magnet components for MRI shielding creates procurement risk for manufacturers without captive magnet supply. Distribution runs through direct manufacturer partnerships with United States hospital systems, displacing traditional distributor relationships in high-volume implant territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pacemaker devices sector sits in a technology-transition phase where leadless pacing platforms are systematically displacing transvenous lead-dependent systems across outpatient settings.
For Market Incumbents: Anticipate accelerated consolidation of hospital purchasing contracts around bundled remote monitoring offerings by securing direct partnerships with ambulatory surgical center networks before competitor lock-in. Defensive patent portfolio expansion in leadless retrieval and battery chemistry should accompany backward integration into lithium-iodine cell production to offset raw material concentration risk from Japanese and South Korean suppliers. For New Entrants and Emerging Players: Rural cardiology clinics in India's Maharashtra and Karnataka states represent an underserved buyer archetype with expanding electrophysiology training pipelines and unmet demand for cost-optimized single-chamber systems. Same-day discharge protocols in Japan's Kanto region outpatient facilities offer a second penetrable entry point through PMDA breakthrough device designation. A go-to-market angle anchored in localized manufacturing partnerships with Yangtze River Delta medical device clusters enables cost structure parity with established domestic producers. For Investors and Strategic Acquirers: Distressed-cycle entries favor component-specialized suppliers with MRI-compatible shielding expertise and captive magnet sourcing in Germany or Taiwan over fully integrated rhythm management platforms facing patent cliff pressure. Long-term viability across the analysis window hinges on exposure to leadless form factor growth and software-enabled remote monitoring revenue streams. The signal to watch is FDA premarket approval timeline compression for active implantable devices, which would extend effective patent life and improve revenue recognition predictability for portfolio companies.| Strategic Initiative | Industry Significance |
|---|---|
| Leadless Platform Miniaturization | Abbott Laboratories' Micra systems enable same-day discharge protocols in United States ambulatory surgical centers. |
| MRI-Conditional Certification Investment | Boston Scientific Corporation's ferromagnetic shielding expertise commands premium positioning in German hospital purchasing committees. |
| Remote Monitoring Software Development | Integrated telemetry platforms reduce in-person clinic visits and create recurring revenue streams for device manufacturers. |
| Backward Integration into Battery Chemistry | Captive lithium-iodine cell production mitigates supply concentration risk from limited specialty chemical suppliers. |
| Reimbursement Strategy Alignment | Medicare coverage pathways for cardiac rhythm management sustain procedure volumes in United States aging demographics. |
Study Parameters
FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, and EU MDR notified body certificates formed the secondary backbone for market sizing and competitive positioning. Primary interviews with electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers validated demand assumptions and procurement workflow insights. Bottom-up implant volume estimates by country and device category were cross-checked against top-down manufacturer revenue disclosures and trade flow data.
Bottom-up modeling anchored volume projections to procedure counts by form factor, technology tier, and end-user setting across the analysis window. Top-down validation drew from disclosed manufacturer revenue ranges and regional regulatory approval trajectories. Segmentation dimensions included product type, technology compatibility, procedure site economics, and geographic reimbursement structure. CAGRs were derived from fitted trend analysis against demographic procedure drivers and technology substitution curves.
Revisions become necessary when FDA premarket review timelines shift materially, lithium-iodine cell supply disruptions emerge, or cybersecurity guidance for wireless telemetry imposes unplanned engineering cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia Pacific Hearing Aids Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Infusion Management Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Japan Hemostats Market
Medical Devices
Airotar Handpiece Market
Medical Devices
Urethral Bulking System Market
Medical Devices
United States Aesthetic Devices Market
Medical Devices
Cardioscope Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Global Gynecological Devices Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Global Lithotripsy Device Market