
 Neurothrombectomy Devices Market | 2026-2036
Neurothrombectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neurothrombectomy Devices Market Intelligence
CE marking under the EU Medical Device Regulation is rotating the competitive landscape toward manufacturers with dedicated neurovascular quality management systems. Stryker leverages its integrated stroke care platform to sustain leadership across aspiration and stent retriever portfolios. Penumbra, Inc. differentiates through specialized aspiration catheter technology that anchors its position in high-volume thrombectomy centers. Medtronic competes with broad navigation system capabilities that extend its reach into combined technique procedures.
Neurothrombectomy devices are catheter-based instruments designed to mechanically extract or aspirate thrombi from cerebral vessels, typically constructed from nitinol alloys and engineered with distal access diameters below 0.05 inches to navigate tortuous intracranial anatomy. Their primary commercial purpose is restoring cerebral blood flow during acute ischemic stroke events where pharmacological thrombolysis remains contraindicated. Stent retriever technology currently occupies the largest installed base among product categories, while aspiration catheter systems represent the fastest-growing segment as operators shift toward direct aspiration first pass techniques. Mechanical thrombectomy technology leads procedure volumes, though combined techniques integrating aspiration with stent retrieval are capturing growing share in complex clot morphologies.
FDA breakthrough device designation and EMA centralized review pathways govern market access timelines for novel neurothrombectomy platforms, with ISO 13485 quality system certification serving as a baseline predicate for both regulatory submissions. These frameworks elevate R&D investment thresholds and favor established manufacturers with dedicated regulatory affairs infrastructure over emerging entrants. Stakeholders must monitor evolving health technology assessment criteria from national payers that increasingly tie reimbursement to demonstrated functional independence outcomes rather than mere recanalization metrics.
Market Dynamics
Direct aspiration first pass techniques are compressing procedure times and displacing standalone stent retriever protocols in comprehensive stroke centers, forcing manufacturers to recalibrate catheter portfolio investments.
Growth Catalysts
- MDR CE marking pathways:The EU Medical Device Regulation creates tiered market access that rewards manufacturers with dedicated neurovascular quality systems, accelerating clearance timelines for compliant firms.
- Comprehensive stroke center networks:Hospital certification programs in the United States and Germany mandate mechanical thrombectomy capability, embedding device procurement into facility infrastructure requirements.
- Nitinol alloy engineering:Advances in shape-memory catheter construction enable sub-0.05-inch distal access diameters that navigate tortuous intracranial anatomy previously unreachable by earlier generation devices.
Market Restraints
- Single-source nitinol supply:Superelastic alloy production concentrates among specialty metallurgical suppliers in Germany and the United States, creating input vulnerability for catheter manufacturers.
- FDA breakthrough designation thresholds:The evidentiary bar for expedited neurovascular device review elevates clinical trial costs beyond emerging manufacturer capitalization.
- Pharmacological thrombolysis:Intravenous tPA protocols retain first-line protocol status in non-comprehensive centers, limiting mechanical thrombectomy to contraindicated patient subsets.
Strategic Opportunities
- Japan stroke center expansion:METI hospital certification programs are extending mechanical thrombectomy infrastructure beyond Tokyo and Osaka into secondary metropolitan regions.
- Combined technique procedures:Aspiration-stent retriever hybrid protocols are capturing complex clot morphologies that resist single-modality extraction, creating dual-product procurement relationships.
- Functional independence reimbursement:Payers in Germany and the United States are migrating from recanalization-based to modified Rankin Scale outcome metrics, rewarding demonstrated patient recovery over procedural technical success.
Industry Challenges
- Neurointerventionalist training pipelines:Fellowship programs produce insufficient operator volume to match comprehensive stroke center expansion timelines, creating procedural bottleneck risk.
- ISO 13485 audit cycles:Quality system recertification demands continuous documentation infrastructure that strains mid-tier manufacturer administrative bandwidth.
- Legacy navigation system integration:New catheter platforms must interface with installed angiography suites from multiple imaging equipment suppliers, complicating technical validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurothrombectomy Devices Market |
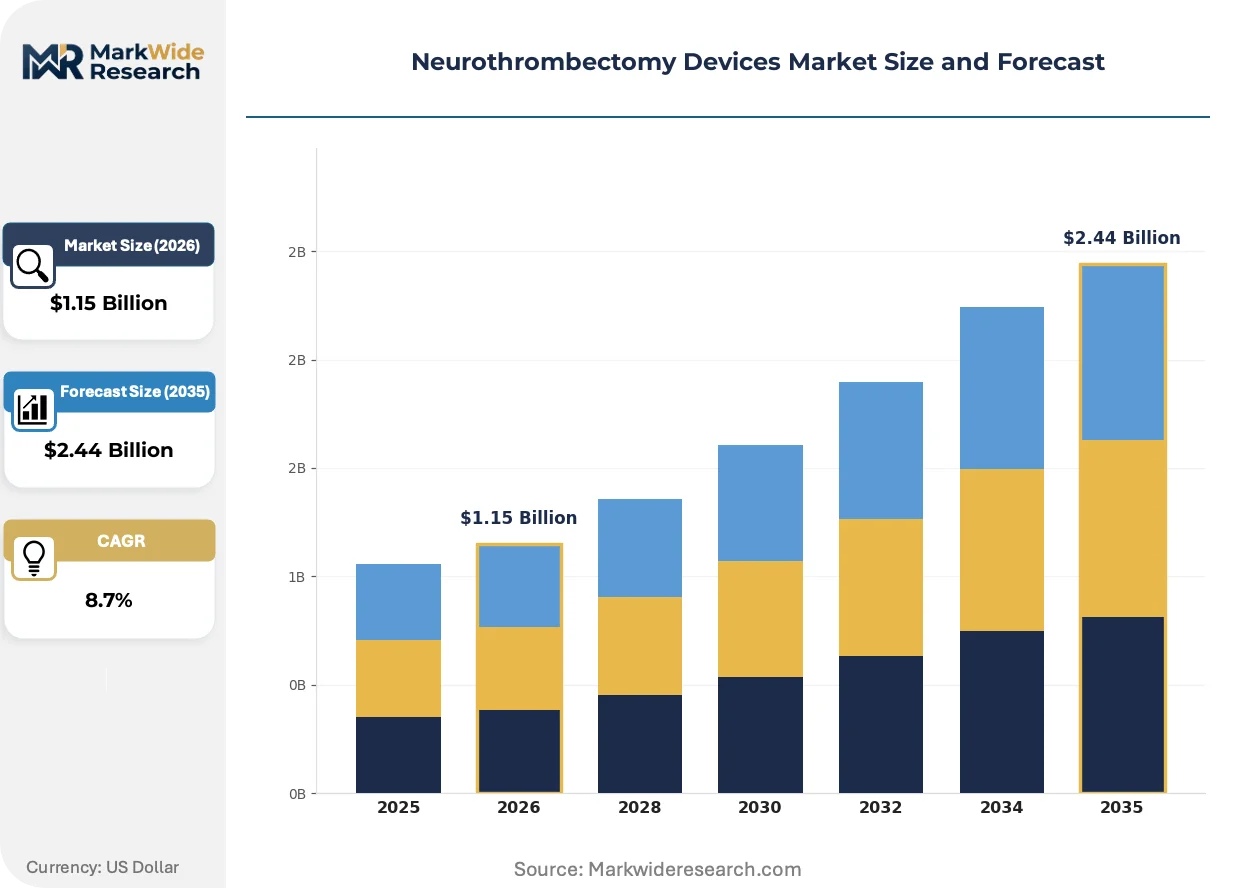
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stent Retriever, Aspiration Catheter, Clot Filter, Delivery System Application: Acute Ischemic Stroke, Intracranial Aneurysm, Vascular Occlusion, Trauma End User: Hospitals, Specialty Clinics, Academic Research Centers, Emergency Departments Technology: Mechanical Thrombectomy, Aspiration Thrombectomy, Combined Techniques, Navigation Systems |
| Companies Covered | Medtronic, Stryker, Penumbra, Inc., Acandis GmbH, Phenox GmbH, Boston Scientific Corporation, Vesalio, MicroVention, Inc., Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurothrombectomy Devices Market Strategic Shifts & Innovations
Operator technique preferences are fragmenting established product hierarchies, with device selection criteria migrating from manufacturer brand loyalty toward procedure-specific performance attributes.
Aspiration catheter technology is bifurcating competitive positioning in the neurothrombectomy market. Large-bore distal access catheters enable direct clot engagement without stent retriever deployment, compressing procedural steps and reducing embolization risk. High-volume thrombectomy centers in the United States and Germany are adopting these systems as default first-line approaches, forcing stent retriever manufacturers to defend installed base through combination protocol bundling.
EU MDR Article 54 expert panel review is extending neurovascular device conformity assessment timelines for novel Class III submissions. The centralized EMA consultation requirement adds 90-180 days to CE marking pathways, compressing European launch windows relative to FDA breakthrough-designated US approvals. Manufacturers are responding with parallel submission strategies that prioritize US commercialization before European regulatory investment.
Hospital procurement committees are unbundling stroke care platform contracts that previously locked catheter supply to integrated navigation system vendors. Standalone aspiration specialists are penetrating comprehensive stroke centers through technology-specific value demonstrations rather than equipment bundling. This pattern concentrates in German hospital groups and US academic medical centers where catheter committee autonomy exceeds system-level standardization mandates.
Neurothrombectomy Devices Market Segmentation
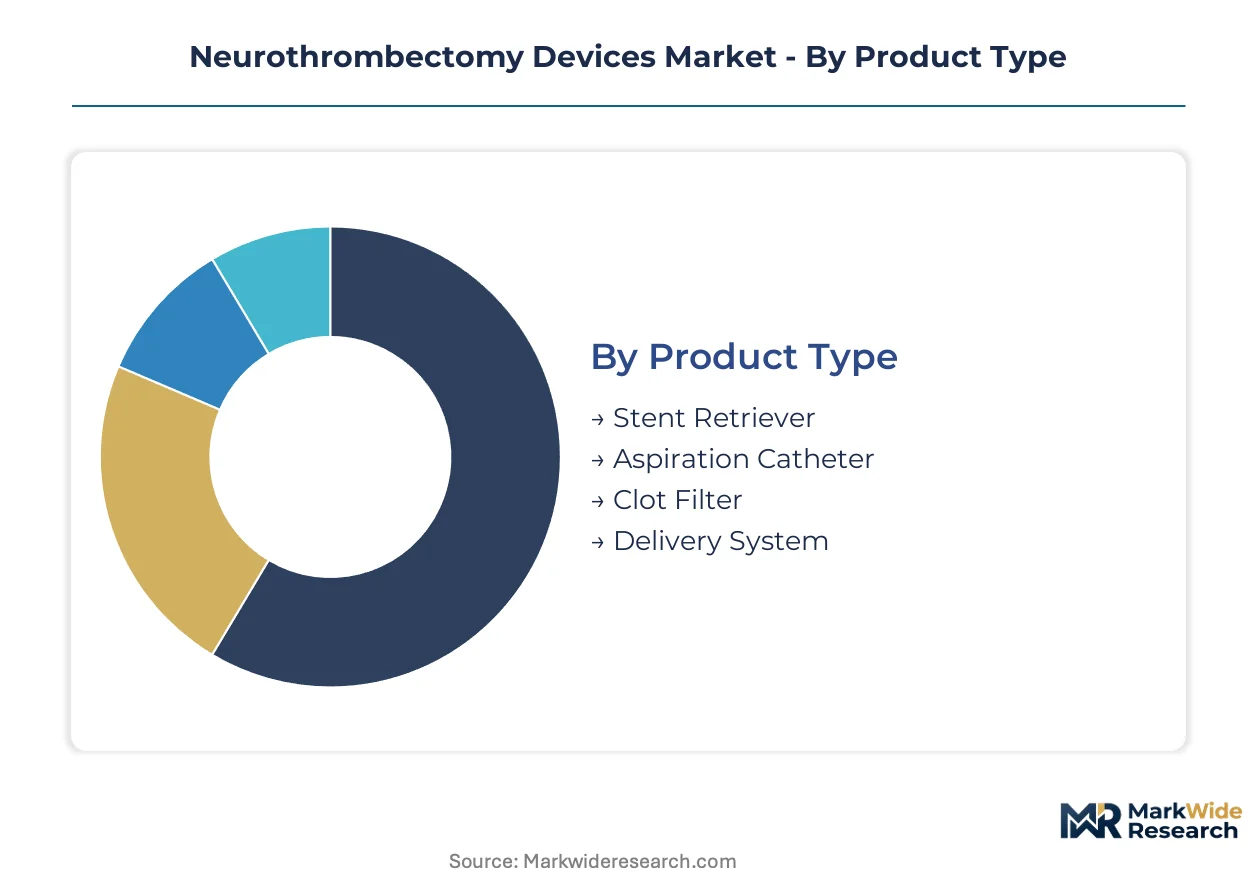
Neurothrombectomy device segmentation reflects divergent regulatory pathways across product categories and end-use settings. FDA breakthrough designation and EU MDR classification tiers create asymmetric commercial timelines that reshape manufacturer portfolio priorities.
Product Type:
FDA Class II versus Class III pathways differentiate clearance complexity across mechanical extraction platforms.
- Stent Retriever:Nitinol mesh constructs deploy across thrombus segments for integrated extraction. Demand concentrates in United States comprehensive stroke centers where reimbursement codes reward mechanical recanalization outcomes.
- Aspiration Catheter:Large-bore distal access systems enable direct clot engagement without stent deployment. German hospital procurement committees favor these systems for compressed procedure times that align with DRG efficiency metrics.
- Clot Filter:Distal embolic protection devices deploy downstream of thrombus during extraction procedures.
- Delivery System:Microcatheter platforms provide navigational access for thrombectomy tools in tortuous anatomy.
Established volume favors stent retriever; emerging adoption favors aspiration catheter.
Application:
Procedure reimbursement intensity varies sharply across clinical indications, with stroke protocols commanding premium device budgets.
- Acute Ischemic Stroke:Mechanical thrombectomy within 24-hour windows dominates commercial procedure volumes. United States comprehensive stroke center certification mandates device availability, embedding procurement into facility infrastructure requirements.
- Intracranial Aneurysm:Flow diversion and coiling adjuncts utilize overlapping catheter platforms. Japanese neurovascular centers concentrate demand for aneurysm-specific device configurations.
- Vascular Occlusion:Chronic total occlusion interventions apply modified thrombectomy techniques.
- Trauma:Emergency vascular repair scenarios require rapid-deployment extraction capabilities.
Reimbursement density peaks with acute ischemic stroke; trauma applications climb fastest as emergency protocols expand.
End User:
Capital equipment integration requirements fragment procurement autonomy across facility types.
- Hospitals:Comprehensive stroke centers anchor device demand through 24/7 intervention capability. German hospital groups negotiate system-level contracts that bundle catheter supply with angiography suite maintenance.
- Specialty Clinics:Outpatient neurovascular centers concentrate elective procedures with lower acuity thresholds. United States ambulatory surgery center expansion creates alternative site demand for streamlined catheter platforms.
- Academic Research Centers:Investigator-initiated trials drive early adoption of novel device iterations.
- Emergency Departments:Pre-hospital stroke networks extend device deployment to initial patient contact points.
Procurement scale concentrates with hospitals; flexibility demands concentrate with specialty clinics.
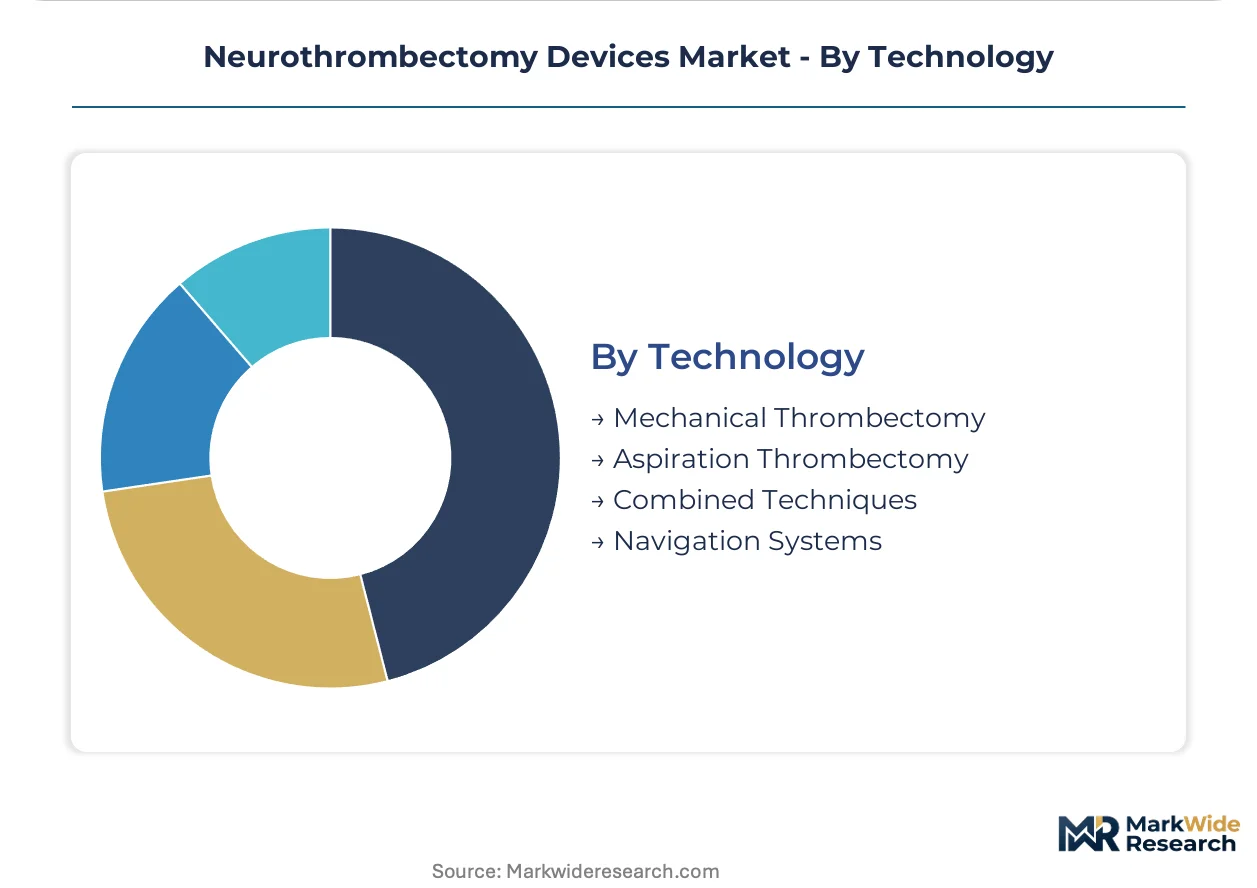
Technology:
Operator training and technique certification create switching costs that lock centers into preferred technical approaches.
- Mechanical Thrombectomy:Stent retriever-based extraction protocols retain the largest installed operator base. United States fellowship programs standardize on mechanical techniques, perpetuating demand for compatible device platforms.
- Aspiration Thrombectomy:Direct aspiration first pass approaches reduce procedural steps and embolization risk. German high-volume centers lead European adoption of aspiration-dominant protocols.
- Combined Techniques:Hybrid aspiration-stent retriever protocols address complex clot morphologies.
- Navigation Systems:Angiography-integrated guidance platforms enable real-time device positioning.
Operator training investment favors mechanical thrombectomy; outcome-based reimbursement favors combined techniques.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Comprehensive stroke center certification programs concentrate device procurement among hospital networks with 24/7 intervention capability. United States, Germany, and Japan anchor commercial demand through advanced reimbursement frameworks and established neurointerventionalist training pipelines.
United States
Comprehensive stroke center certification through The Joint Commission mandates mechanical thrombectomy availability, embedding device procurement into facility infrastructure requirements. FDA breakthrough device designation accelerates clearance timelines for novel catheter platforms. The Cleveland Clinic and Mayo Clinic stroke networks anchor demand in the Midwest, driving adoption of aspiration-first protocols.
Germany
DRG reimbursement codes reward compressed procedure times, favoring aspiration catheter systems that reduce embolization risk. EU MDR CE marking pathways under Article 54 extend conformity assessment timelines for Class III neurovascular submissions. Hospital groups in North Rhine-Westphalia negotiate system-level contracts bundling catheter supply with angiography suite maintenance.
Japan
METI hospital certification programs extend mechanical thrombectomy infrastructure beyond Tokyo and Osaka into secondary metropolitan regions. PMDA review pathways govern market access for novel stent retriever and aspiration platforms. The Nagoya and Fukuoka medical corridors concentrate neurointerventionalist training capacity, anchoring regional device demand.
United Kingdom
NHS England stroke service specifications mandate mechanical thrombectomy availability in hyper-acute stroke units, driving procurement standardization. MHRA conformity assessment procedures align with EU MDR technical documentation requirements. The Greater London and Greater Manchester health economies concentrate procedure volumes, creating clustered demand for compatible catheter platforms.
Switzerland
Swissmedic medical device regulations require quality system certification for neurovascular product registration, elevating compliance thresholds. Cantonal hospital networks in Zurich and Geneva coordinate stroke care regionalization, concentrating device procurement among academic medical centers. Swiss university hospitals anchor demand for combined technique protocols addressing complex clot morphologies.
Neurothrombectomy Devices Market Key Industry Players
Player mix skews toward integrated medical technology conglomerates with dedicated neurovascular divisions. Market structure concentrates among three to five manufacturers with established regulatory affairs infrastructure and comprehensive stroke care platform offerings. Strategic archetypes include integrated stroke platform vendors, specialized aspiration technology developers, and broad navigation system suppliers. Dominant competitive moves center on portfolio diversification into combined technique systems and geographic expansion through distributor partnerships in Asia-Pacific markets.
Among diversified medical technology conglomerates, Medtronic, Stryker, and Penumbra occupy positions spanning the competitive spectrum. Medtronic represents the broad navigation system archetype with angiography-integrated guidance capabilities. Stryker exemplifies the integrated stroke platform model bundling aspiration and stent retriever portfolios. Penumbra anchors the specialized aspiration technology tier with catheter systems engineered for direct first-pass techniques. These three manufacturers collectively illustrate the strategic positioning vectors—platform breadth, navigation integration, and technique specialization—that define competitive differentiation in comprehensive stroke center procurement.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Penumbra, Inc. |
| Acandis GmbH |
| Phenox GmbH |
| Boston Scientific Corporation |
| Vesalio |
| MicroVention, Inc. |
| Terumo Corporation |
| Others |
Cost & Logistics Intelligence
Large-bore aspiration catheter substitution for stent retriever-first protocols is redrawing procurement geography toward German and United States comprehensive stroke centers while compressing price premiums previously attached to integrated platform contracts. This input substitution simultaneously elevates standalone catheter manufacturers' pricing power and erodes bundled-equipment discounts that anchored legacy supply relationships.
Pricing Analysis
Cost-plus contracts with nitinol alloy indexation govern raw material pass-through for catheter manufacturers. Three-tier pricing structure across premium aspiration systems, standard stent retrievers, and economy delivery catheters reflects FDA breakthrough designation tier and ISO 13485 certification status. Cost compression in economy-tier delivery systems is intensifying because hospital procurement committees unbundle stroke platform contracts. Academic medical centers in the United States exhibit lowest price sensitivity due to outcome-based reimbursement alignment; German hospital groups demonstrate highest sensitivity through DRG efficiency mandates.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for nitinol precursor shipments from German specialty metallurgical suppliers underwrites supply security premiums in catheter manufacturing. Production concentrates in Germany, United States, and Japan for superelastic alloy fabrication and final device assembly. Raw material dependencies center on nickel-titanium ingots, platinum-iridium marker bands, and hydrophilic polymer coatings. Single-source vulnerability concentrates in German nitinol suppliers serving multiple catheter OEMs. Distribution runs through hospital GPO contracts in the United States and direct hospital group procurement in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's expansion trajectory outpaces fellowship-trained neurointerventionalist supply, creating acute capability scarcity that constrains procedural volume realization and amplifies operator compensation costs.
For Market Incumbents: Fortify regulatory affairs infrastructure against EU MDR Article 54 extended timelines while deepening backward integration into nitinol alloy supply through captive relationships with German metallurgical specialists. Emerging standalone aspiration specialists threaten integrated platform margins through unbundled procurement penetration in academic medical centers. For New Entrants and Emerging Players: Anchor in Japanese secondary metropolitan stroke centers beyond Tokyo and Osaka where METI certification programs expand mechanical thrombectomy infrastructure with less entrenched incumbent relationships. Combined technique aspiration-stent retriever hybrid protocols offer the most penetrable white space. Pursue investigator-initiated trial partnerships with Nagoya and Fukuoka medical corridor training programs to establish clinical evidence base. For Investors and Strategic Acquirers: The market sits at a technique-transition phase that favors specialized aspiration technology developers over broad navigation system suppliers. Long-term viability across the next decade hinges on demonstrated functional independence outcomes rather than recanalization metrics. Acquisition targets should demonstrate EU MDR compliance infrastructure and established relationships with German hospital procurement committees. The signal to watch is modified Rankin Scale-based reimbursement adoption velocity in United States Medicare Advantage plans.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Expedited review pathways compress time-to-revenue for novel catheter platforms in United States comprehensive stroke centers. |
| EU MDR CE Marking Pathway | Article 54 expert panel compliance differentiates manufacturers for German hospital group procurement decisions. |
| Hospital System Partnership | Direct contracting with Cleveland Clinic and Mayo Clinic stroke networks anchors aspiration-first protocol adoption. |
| Software Companion Development | Angiography-integrated guidance algorithms enhance catheter positioning accuracy for complex intracranial anatomy navigation. |
| Reimbursement Strategy | Modified Rankin Scale outcome demonstration aligns with German DRG and United States Medicare Advantage value-based payment migration. |
Research Approach
Operator-level perspectives from neurointerventionalists, hospital stroke center directors, biomedical engineers, and GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA 510(k) and breakthrough device filings, EMA centralized review documentation, CMS Medicare procedure databases, and comprehensive stroke center certification records. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation across stent retriever, aspiration catheter, and combined technique platforms.
Sensitivity analysis tested forecast robustness across regulatory timeline scenarios, nitinol supply disruption assumptions, and reimbursement metric migration pathways. Segmentation modeling captured product type, application, end user, and technology dimensions alongside operator training pipeline capacity constraints. CAGRs derived from procedure volume growth trajectories and device ASP evolution patterns. Forecast inputs incorporated comprehensive stroke center certification expansion timelines and METI hospital program geographic extension.
Decision-makers should treat outputs as directional under stable EU MDR implementation and unaltered FDA breakthrough designation criteria; material deviation in either regulatory framework would warrant model refresh. Practitioners should keep alternative scenarios live as modified Rankin Scale reimbursement adoption and combined technique protocol penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Vaginal Pessary Market
Medical Devices
Eye Sphere Implants Market
Medical Devices
Clot Management Devices Market
Medical Devices
Global Sperm Separation Devices Market
Medical Devices
Global Pupillometer Market
Medical Devices
Foot and Ankle Allograft Market
Medical Devices
Medical Device Technologies Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Radiotherapy Positioning Devices Market
Medical Devices
US Clear Aligners Market
Medical Devices
Vortex Mixer Market
Medical Devices
Snare Devices Market