
 Global Intraoperative Neuromonitoring (IONM) Market | 2026-2036
Global Intraoperative Neuromonitoring (IONM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intraoperative Neuromonitoring (IONM) Market Foresight
Multi-modality IONM capability is rotating toward premium-tier hospital contracts and complex spine surgery bundles. NuVasive sustains one of the largest outsourced IONM service footprints across US health systems. Medtronic leverages its integrated surgical ecosystem to bundle neuromonitoring hardware with navigation platforms. Natus Medical Incorporated anchors its position through specialized electrodiagnostic equipment that spans intraoperative and diagnostic settings.
Intraoperative neuromonitoring encompasses real-time electrophysiological surveillance of neural pathways during surgical procedures, employing evoked potential recording with microvolt-level signal resolution to detect ischemic or mechanical nerve insult before irreversible damage occurs. Its primary commercial purpose is reducing postoperative neurological deficit rates in high-risk surgeries. Evoked Potential Systems command the dominant product share due to their irreplaceability in multimodal protocols, while Motor Evoked Potentials represent the fastest-growing technology segment as transcranial electrical stimulation protocols expand beyond spine into aortic and intracranial applications. Spine Surgery absorbs the largest application volume, though Brain Tumor Removal generates superior per-procedure service margins because of the neurophysiologist specialization required.
The FDA governs IONM device classification and 510(k) clearance timelines, directly shaping product development cycles and market entry barriers for new hardware entrants. The EU MDR and CE marking requirements impose additional clinical evidence burdens on evoked potential system manufacturers seeking European commercialization. ISO 13485 quality management certification operates as a baseline procurement filter for hospital purchasing committees evaluating vendor qualification. Stakeholders must monitor reimbursement code stability and neurophysiologist labor supply constraints as the primary variables determining service model profitability and geographic expansion feasibility.
Market Dynamics
Hospital systems are consolidating outsourced IONM service contracts to eliminate the fixed cost of in-house neurophysiologist staffing, compressing vendor margins while expanding addressable procedure volumes for specialized monitoring providers.
Growth Catalysts
- Medicare reimbursement stability:United States CMS maintains consistent CPT code coverage for IONM procedures, reducing revenue uncertainty and enabling capital investment in monitoring infrastructure by ASCs and hospital outpatient departments.
- Transcranial MEP protocol expansion:Motor evoked potential stimulation is migrating beyond spine surgery into aortic arch repair and intracranial tumor resection, opening procedural categories previously monitored with somatosensory methods alone.
- FDA Class II guidance acceleration:Streamlined 510(k) pathways for evoked potential systems are compressing time-to-market for hardware iterations, incentivizing manufacturers to refresh product lines more frequently.
Market Restraints
- Neurophysiologist labor scarcity:Board-certified clinical neurophysiologists concentrate in major US metropolitan academic centers, creating recruitment bottlenecks for rural hospital contracts and limiting service expansion velocity.
- EU MDR clinical evidence burden:CE marking requirements for evoked potential systems now demand expanded post-market surveillance data, extending European commercialization timelines and raising compliance costs for hardware entrants.
- Disposable electrode cost volatility:Silver-silver chloride electrode prices fluctuate with precious metal markets, squeezing per-procedure margins for high-volume monitoring service providers.
Strategic Opportunities
- India surgical volume penetration:Private hospital chains in Mumbai, Delhi, and Bangalore are installing IONM capability for complex spine and neurosurgery cases, creating first-mover advantage for outsourced service partnerships.
- Japan super-aging surgical demand:METI incentives for surgical safety technologies align with rising elderly spine surgery volumes, positioning multimodal IONM as a reimbursable risk-mitigation investment.
- AI-assisted signal interpretation:Machine learning artifact rejection algorithms are converging with traditional electrophysiology hardware, enabling lower-skill technicians to operate monitoring equipment under remote neurologist supervision.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for evoked potential device manufacturers average 12-18 months, delaying product launches and freezing R&D capital in compliance preparation.
- Legacy EMR integration complexity:IONM data streams require HL7 FHIR mapping to hospital electronic medical record systems, with incompatible vendor architectures forcing expensive custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intraoperative Neuromonitoring (IONM) Market |
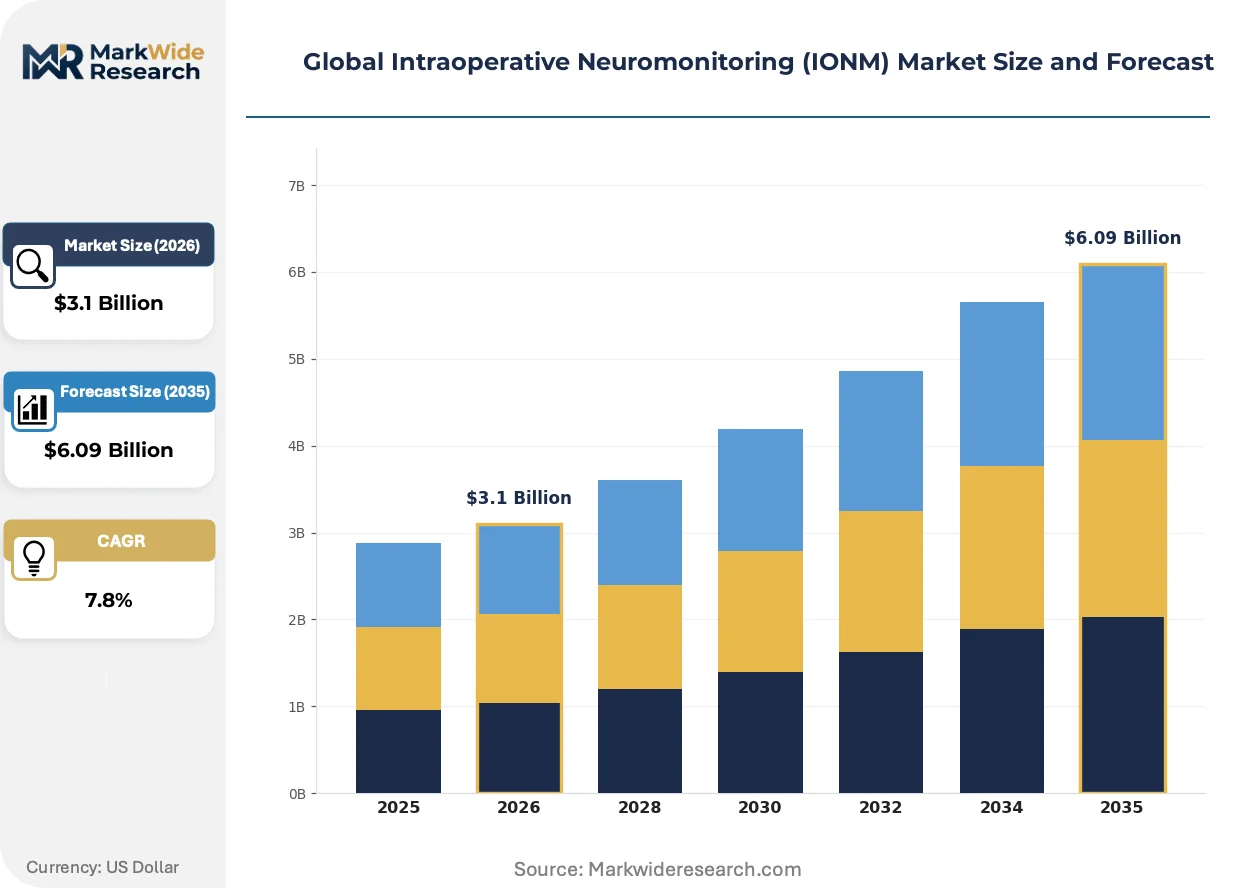
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromyography Devices, Electroencephalography Instruments, Evoked Potential Systems, Peripheral Nerve Stimulators Technology: Somatosensory Evoked Potentials, Motor Evoked Potentials, Brainstem Auditory Evoked Potentials, Visual Evoked Potentials Application: Spine Surgery, Brain Tumor Removal, Cardiovascular Procedures, Thyroidectomy End User: Hospitals, Ambulatory Surgical Centers, Neurosurgical Clinics, Specialty Diagnostic Centers |
| Companies Covered | NuVasive, Cadwell Industries, Medtronic, inomed Medizintechnik GmbH, SpecialtyCare, Natus Medical Incorporated, Accurate Monitoring, Neuromonitoring Technologies, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intraoperative Neuromonitoring (IONM) Market Shifts & Advancements
Real-time signal processing architectures and remote monitoring delivery models are restructuring how surgical teams access neuromonitoring expertise, collapsing geographic constraints on specialist availability.
Wireless electrode arrays with integrated amplification are supplanting tethered cable bundles in complex spine and cranial procedures. Pediatric and scoliosis surgery centers in the United States are piloting these systems to reduce setup time and infection risk from cable contamination. The technology is compressing the minimum staff footprint required per procedure, enabling single-technician monitoring protocols that alter service cost structures.
EU MDR Article 10 clinical evaluation requirements are mandating prospective safety data collection for evoked potential systems, forcing manufacturers to sponsor multicenter registry studies before CE marking renewal. European notified bodies are prioritizing software-as-medical-device submissions, creating backlog delays for traditional hardware-only 510(k) equivalents. German and French hospital purchasing committees are now requiring MDR compliance documentation as a mandatory procurement filter.
Academic medical centers are unbundling IONM service contracts from implant vendor bundles, issuing standalone RFPs for monitoring-only provision. This pattern is visible across Texas, California, and New York health systems seeking direct control over neurophysiologist credentialing standards. The shift is elevating pure-play monitoring specialists over integrated device-and-service conglomerates in competitive evaluations.
Global Intraoperative Neuromonitoring (IONM) Market Segmentation
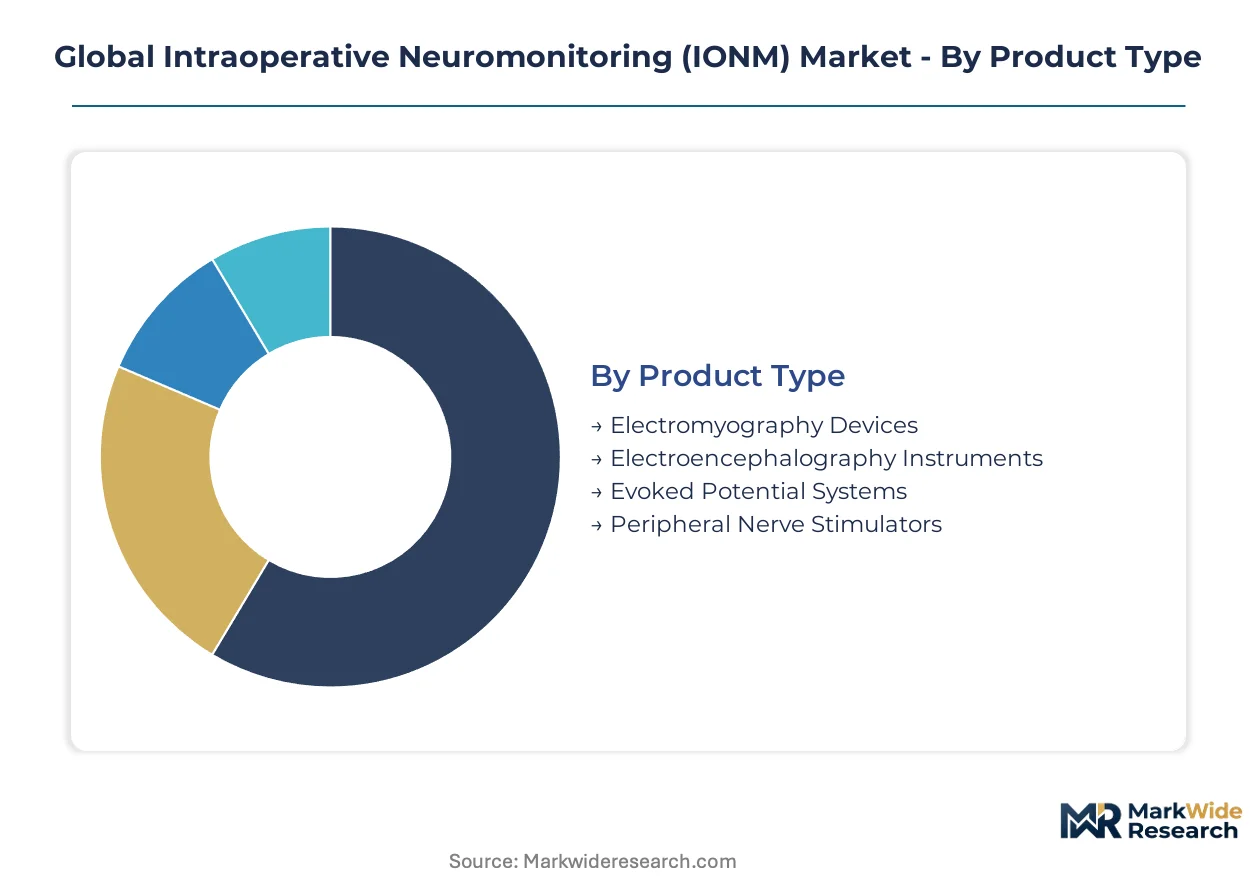
IONM market segmentation reveals distinct procurement and deployment patterns across hardware categories and service delivery models. Hospital purchasing committees evaluate segments through divergent lenses: capital equipment decisions favor integrated platform vendors, while outsourced service contracts prioritize neurophysiologist credentialing density and geographic coverage.
Product Type:
Evoked Potential Systems and electromyography hardware flow through integrated surgical device vendors, while electroencephalography instruments concentrate in specialized electrodiagnostic distributors serving hospital neurophysiology departments.
- Evoked Potential Systems:These platforms integrate multimodal signal acquisition with microvolt-level resolution for real-time neural pathway surveillance. United States hospital systems and ambulatory surgical centers in Texas, California, and New York are consolidating procurement around FDA 510(k)-cleared systems that bundle somatosensory and motor evoked potential capabilities, driven by Medicare reimbursement stability for multimodal monitoring protocols.
- Electromyography Devices:Surface and needle electrode configurations enable direct muscle response recording during peripheral nerve proximity procedures. Demand concentrates in orthopedic spine units and neurosurgical suites across German university hospitals and Japanese metropolitan medical centers, where ISO 13485-certified device procurement filters favor established electrodiagnostic manufacturers with MDR compliance documentation.
- Electroencephalography Instruments:Continuous cortical activity monitoring systems for intracranial procedures.
- Peripheral Nerve Stimulators:Handheld and integrated stimulation units for nerve localization and integrity testing.
By volume, Evoked Potential Systems lead hospital capital budgets. By growth pace, Electromyography Devices are expanding most quickly through ambulatory surgical center penetration.
Technology:
Technology selection follows surgical complexity tiers: high-acuity intracranial and aortic procedures demand motor evoked potential protocols, while standard spine surveillance relies on somatosensory methods.
- Motor Evoked Potentials:Transcranial electrical stimulation protocols generate descending motor pathway signals with train-of-four monitoring capability. United States academic medical centers and aortic surgery programs at Cleveland Clinic and Mayo Clinic are expanding MEP utilization beyond spine into arch repair and intracranial tumor resection, propelled by superior sensitivity to anterior spinal artery ischemia compared to somatosensory methods.
- Somatosensory Evoked Potentials:Peripheral nerve stimulation with cortical recording remains the backbone of posterior column monitoring in deformity correction and degenerative spine procedures. Volume concentrates in high-throughput spine centers across India—Mumbai, Delhi, and Bangalore private hospital chains—and United States Medicare-certified ambulatory surgery centers, where reimbursement code stability supports standardized SSEP protocol deployment.
- Brainstem Auditory Evoked Potentials:Cranial nerve VIII monitoring during cerebellopontine angle and brainstem procedures.
- Visual Evoked Potentials:Optic pathway surveillance for suprasellar and orbital apex surgeries.
Somatosensory Evoked Potentials command the largest procedure volume. Motor Evoked Potentials are gaining share fastest through transcranial protocol expansion into vascular and oncologic applications.
Application:
Application segmentation maps directly to reimbursement tier and service margin structure: spine procedures drive volume, while intracranial applications command premium neurophysiologist specialization fees.
- Spine Surgery:Deformity correction, degenerative disease, and trauma procedures constitute the dominant IONM utilization category. United States hospital outpatient departments and German orthopedic spine centers deploy multimodal monitoring for scoliosis, spondylolisthesis, and revision fusion cases, with Medicare and German statutory health insurance maintaining consistent procedure code coverage that reduces revenue uncertainty for monitoring service providers.
- Brain Tumor Removal:Resection of supratentorial and infratentorial lesions requires continuous cortical and subcortical mapping. Academic medical centers in Boston, Baltimore, and Zurich concentrate demand here, where direct motor cortex stimulation and subcortical tract identification justify higher per-procedure neurophysiologist staffing ratios and specialized training credentials.
- Cardiovascular Procedures:Aortic arch and thoracoabdominal aneurysm repair with segmental artery sacrifice.
- Thyroidectomy:Recurrent laryngeal nerve monitoring during anterior neck surgery.
Spine Surgery absorbs the greatest absolute procedure count. Brain Tumor Removal delivers the steepest expansion trajectory through unbundled academic center contracting.
End User:
End user channel structure is bifurcating: hospital systems consolidate outsourced IONM contracts to eliminate fixed neurophysiologist costs, while ambulatory surgical centers invest in capital-light remote monitoring partnerships.
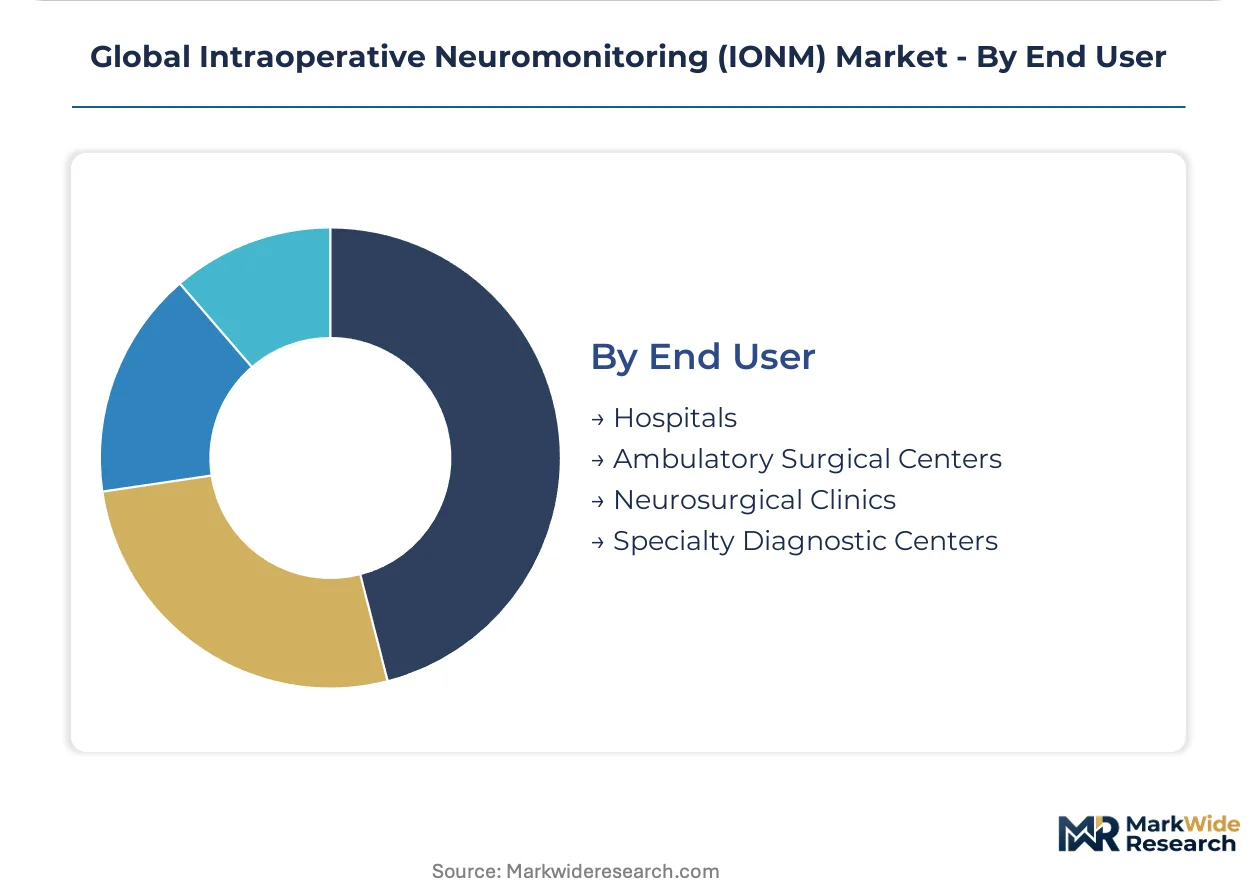
- Hospitals:Tertiary and community hospital systems represent the core revenue channel for both device manufacturers and outsourced service providers. United States health systems in Texas, California, and New York are issuing standalone RFPs for monitoring-only provision, elevating pure-play specialists over integrated device-service conglomerates in competitive evaluations.
- Ambulatory Surgical Centers:Freestanding outpatient facilities performing spine and ENT procedures are adopting remote neuromonitoring delivery models. ASCs in Florida, Arizona, and North Carolina are contracting with centralized neurophysiologist hubs that supervise local technicians via encrypted video and signal streaming, compressing specialist labor costs while maintaining procedural coverage.
- Neurosurgical Clinics:Specialized outpatient surgical facilities with integrated imaging and monitoring capability.
- Specialty Diagnostic Centers:Electrodiagnostic laboratories with intraoperative service extension.
Hospitals retain the dominant procurement volume. Ambulatory Surgical Centers are climbing the fastest as Medicare site-of-service differentials incentivize outpatient migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturers cluster manufacturing and service operations in the United States, Germany, and Japan where neurosurgical procedure volumes and regulatory infrastructure align. Emerging private hospital networks in India and Brazil are installing IONM capability for complex spine cases, creating new demand nodes outside traditional North American and European centers.
United States
Cleveland Clinic and Mayo Clinic anchor MEP protocol expansion into aortic arch repair, driving technology migration beyond spine applications. FDA Class II guidance streamlines 510(k) clearance timelines for evoked potential system iterations. Texas, California, and New York health systems unbundle monitoring contracts from implant vendor bundles, elevating pure-play service specialists in competitive RFPs.
Germany
University hospitals in Munich and Berlin concentrate electromyography device demand for orthopedic spine units. EU MDR Article 10 mandates prospective safety data collection for evoked potential systems, extending CE marking renewal timelines. German statutory health insurance maintains consistent procedure code coverage, reducing revenue uncertainty for monitoring service providers operating across Baden-Württemberg and North Rhine-Westphalia.
Japan
METI incentives for surgical safety technologies align with rising elderly spine surgery volumes in Tokyo and Osaka metropolitan areas. PMDA regulatory frameworks govern evoked potential system commercialization, with local manufacturers prioritizing domestic hospital procurement relationships. Kanto and Kansai regions concentrate multimodal IONM adoption as super-aging demographics elevate risk-mitigation investments.
India
Private hospital chains in Mumbai, Delhi, and Bangalore install IONM capability for complex spine and neurosurgery cases. CDSCO medical device registration requirements shape hardware import pathways for international manufacturers. CDSCO compliance documentation operates as a mandatory procurement filter for hospital purchasing committees evaluating vendor qualification.
Brazil
São Paulo and Rio de Janeiro surgical centers expand outsourced neuromonitoring partnerships to address neurophysiologist specialization gaps. ANVISA medical device regulations govern evoked potential system commercialization, with notified body backlogs extending market entry timelines. Southeastern state hospital networks concentrate demand as private insurance reimbursement stabilizes for high-risk procedure monitoring.
Global Intraoperative Neuromonitoring (IONM) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the IONM ecosystem. Integrated surgical device conglomerates bundle neuromonitoring hardware with navigation platforms, while pure-play monitoring specialists compete on neurophysiologist credentialing density and geographic coverage. The market structure bifurcates between capital equipment vendors serving hospital purchasing committees and outsourced service providers eliminating fixed staffing costs for health systems. Dominant competitive moves include standalone RFP pursuit for monitoring-only contracts and remote delivery model expansion into ambulatory surgical centers.
Among integrated device-and-service conglomerates, Medtronic and NuVasive occupy positions spanning hardware manufacturing and outsourced service provision. Natus Medical Incorporated anchors the specialized electrodiagnostic equipment tier, with product lines spanning intraoperative and diagnostic settings. Cadwell Industries represents the independent electrophysiology hardware archetype, competing on FDA 510(k) clearance velocity and ISO 13485 quality certification maintenance.
| Leading Market Players |
|---|
| NuVasive |
| Cadwell Industries |
| Medtronic |
| inomed Medizintechnik GmbH |
| SpecialtyCare |
| Natus Medical Incorporated |
| Accurate Monitoring |
| Neuromonitoring Technologies |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Wireless electrode arrays replacing tethered cable bundles in US pediatric spine centers simultaneously shift component sourcing from domestic cable manufacturers to Taiwanese semiconductor foundries and compress per-procedure pricing economics through reduced setup labor.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across evoked potential systems, separating premium multimodal platforms with MEP capability from standard SSEP-only configurations. Price differentiation rests on ISO 13485 certification grade and after-sales service bundling, with academic medical centers showing lowest sensitivity due to grant-funded procurement while ambulatory surgical centers face acute pressure from Medicare site-of-service differentials. Cost compression in standard-tier hardware is intensifying because silver-silver chloride electrode volatility squeezes disposable margins.
Supply Chain Analysis
Germany and the United States anchor precision amplifier manufacturing for evoked potential systems, while Japan and South Korea supply microelectrode sensor arrays. Raw material flows draw from Malaysian rubber substrates, Chinese rare-earth magnet components for transcranial stimulators, and Indian software engineering for signal processing algorithms. Single-source vulnerability concentrates in high-resolution analog-to-digital converter chips. Distribution runs through specialized surgical device distributors serving hospital purchasing committees and direct OEM partnerships with integrated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IONM market functions as a service-attach opportunity where outsourced neuromonitoring contracts expand faster than capital equipment sales, with recurring neurophysiologist staffing fees now exceeding hardware depreciation curves in hospital total cost of ownership models.
For Market Incumbents: Compound credentialing density in neurophysiologist labor pools to defend against AI-assisted remote monitoring entrants eroding technician-supervised service margins. Deepen backward integration into disposable electrode manufacturing to offset silver price volatility squeezing per-procedure profitability. Prioritize ISO 13485 certification maintenance as European hospital procurement filters harden under MDR Article 10 requirements. For New Entrants and Emerging Players: Differentiate on AI-assisted signal interpretation protocols that enable lower-skill technician deployment under remote neurologist supervision. Target India's private hospital chains in Mumbai and Bangalore where complex spine surgical volumes outpace local neurophysiologist supply. Pursue software-as-medical-device regulatory pathways ahead of hardware-only submissions to exploit European notified body prioritization patterns. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors pure-play monitoring specialists with unbundled contract momentum over integrated device-service conglomerates losing standalone RFP evaluations. Acquisition targets should display dense neurophysiologist geographic coverage and established remote delivery infrastructure. Watch for FDA guidance acceleration on Class II evoked potential systems as the inflection signal compressing hardware refresh cycles and elevating R&D capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined Class II pathways compress time-to-market for evoked potential system iterations. |
| Remote Monitoring Platform Development | Encrypted video streaming enables centralized neurophysiologist hubs supervising ASC technicians. |
| Neurophysiologist Credentialing Network Expansion | Board-certified specialist density determines competitive positioning in hospital RFP evaluations. |
| AI Signal Interpretation Integration | Machine learning artifact rejection algorithms reduce minimum staff footprint per procedure. |
| EU MDR Compliance Documentation Investment | Prospective safety data collection satisfies German and French hospital procurement filters. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committee members and secondary validation through FDA 510(k) filings anchors the qualitative findings. Conversations with clinical neurophysiologists, biomedical engineers, GPO contracts managers, and outsourced IONM service executives informed service model profitability assessments. Secondary sources encompass CMS Medicare reimbursement databases, EU MDR notified body submission records, and hospital procurement RFP documentation. Bottom-up procedure volume estimates and top-down equipment shipment data triangulate market sizing.
Sensitivity analysis across neurophysiologist labor supply scenarios and reimbursement code stability assumptions shapes the analytical framework over the projection horizon. Segmentation dimensions span product type, technology protocol, surgical application, and end-user channel structure. CAGRs derive from procedure volume trajectories weighted by per-case service fees and capital equipment replacement cycles. Forecast inputs incorporate Medicare site-of-service differential impacts and EU MDR compliance timeline extensions.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement stability or accelerated neurophysiologist training pipeline expansion would require recalibration. Forecasts reflect assumptions regarding regulatory clearance velocity and precious metal commodity price bands. Recalibration cycles align with material shifts in FDA guidance updates and European notified body prioritization patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Electrophysiology Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Vascular Boot Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Spinal Cord Stimulators Market
Medical Devices
Medical Smart Wearable Devices Market
Medical Devices
Spinal Trauma Devices Market