
 Oxygen Concentrators Market | 2026-2036
Oxygen Concentrators Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Concentrators Market Intelligence
Aftermarket service and consumable revenue is reshaping the traditional device-sales model for oxygen concentrators. This shift favors companies with strong direct-to-consumer channels and service networks. Koninklijke Philips leverages its extensive healthcare ecosystem to bundle services with its devices. Inogen, Inc. specializes in direct-to-consumer sales of portable units, while CAIRE Inc. sustains a broad portfolio across both portable and stationary systems.
An oxygen concentrator is a medical device that selectively removes nitrogen from ambient air to provide an oxygen-enriched gas stream. These devices typically operate using Pressure Swing Adsorption (PSA) technology, employing a zeolite sieve to achieve oxygen purities of up to 95%. The market's product landscape is bifurcating between portable oxygen concentrators for mobile patients and stationary units for home healthcare. Demand for managing Chronic Obstructive Pulmonary Disease continues to dominate application segments, driving sales in home healthcare provider and long-term care facility end-user channels.
Product approval and market access are governed by stringent medical device regulations. These include premarket clearance from the US FDA, conformity assessments for CE marking under Europe's Medical Device Regulation (MDR), and approval from China's NMPA. Future competitive advantage will depend on successfully navigating varied reimbursement policies and demonstrating superior clinical outcomes for conditions beyond COPD, such as sleep apnea therapy.
Market Dynamics
The market's central dynamic is the product bifurcation between stationary systems for home use and portable units for patient mobility. This split is driven by patient demand for greater independence and technological advancements that enable smaller, more efficient devices.
Growth Catalysts
- Aging Demographics:The rising prevalence of Chronic Obstructive Pulmonary Disease (COPD) among aging populations, particularly in developed nations like Japan and the United States, directly stimulates demand for long-term oxygen therapy in homecare settings.
- Technological Miniaturization:Advances in Pressure Swing Adsorption (PSA) technology and more efficient zeolite sieve materials are enabling the production of lighter, smaller portable oxygen concentrators with extended battery life, expanding the addressable market to mobile patients.
- Home Healthcare Expansion:Favorable reimbursement policies for home medical equipment in countries like the United States are encouraging a shift in patient care from hospitals to home settings, making oxygen concentrators a cost-effective solution for providers.
Market Restraints
- High Upfront Cost:The significant initial purchase price of portable oxygen concentrators remains a barrier to adoption for many patients, especially in markets without comprehensive insurance coverage or reimbursement schemes.
- Regulatory Compliance Burden:Navigating the stringent and divergent regulatory requirements of bodies like the US FDA and Europe's Medical Device Regulation (MDR) for market approval creates long lead times and high compliance costs.
- Competition from Alternatives:In certain price-sensitive segments and developing regions, traditional compressed oxygen cylinders and liquid oxygen systems remain a viable, lower-cost substitute, limiting concentrator penetration.
Strategic Opportunities
- Emerging Market Penetration:Large, developing economies offer significant growth potential as healthcare infrastructure improves and disposable incomes rise, creating new demand for both stationary and portable oxygen therapy solutions.
- Expanded Clinical Applications:Demonstrating clinical efficacy for conditions beyond COPD, such as sleep apnea and certain cardiac conditions, opens new therapeutic areas and patient populations for oxygen concentrator technology.
- Integration with Digital Health:Incorporating connectivity features that link concentrators to remote patient monitoring platforms allows for better management of chronic respiratory diseases, creating value-added service opportunities for manufacturers.
Industry Challenges
- Service Network Management:For companies pursuing direct-to-consumer models, establishing and maintaining a responsive global network for device service, repair, and consumable replacement presents a significant logistical and operational challenge.
- Battery Technology Limitations:The performance of portable units depends on battery life, and current lithium-ion battery technology limits duration and increases device weight, posing a hurdle to achieving true all-day mobility for users.
- Reimbursement Variability:Inconsistent reimbursement codes and payment levels across different countries and private payers create complexity and uncertainty for manufacturers, impacting market access and profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Concentrators Market |
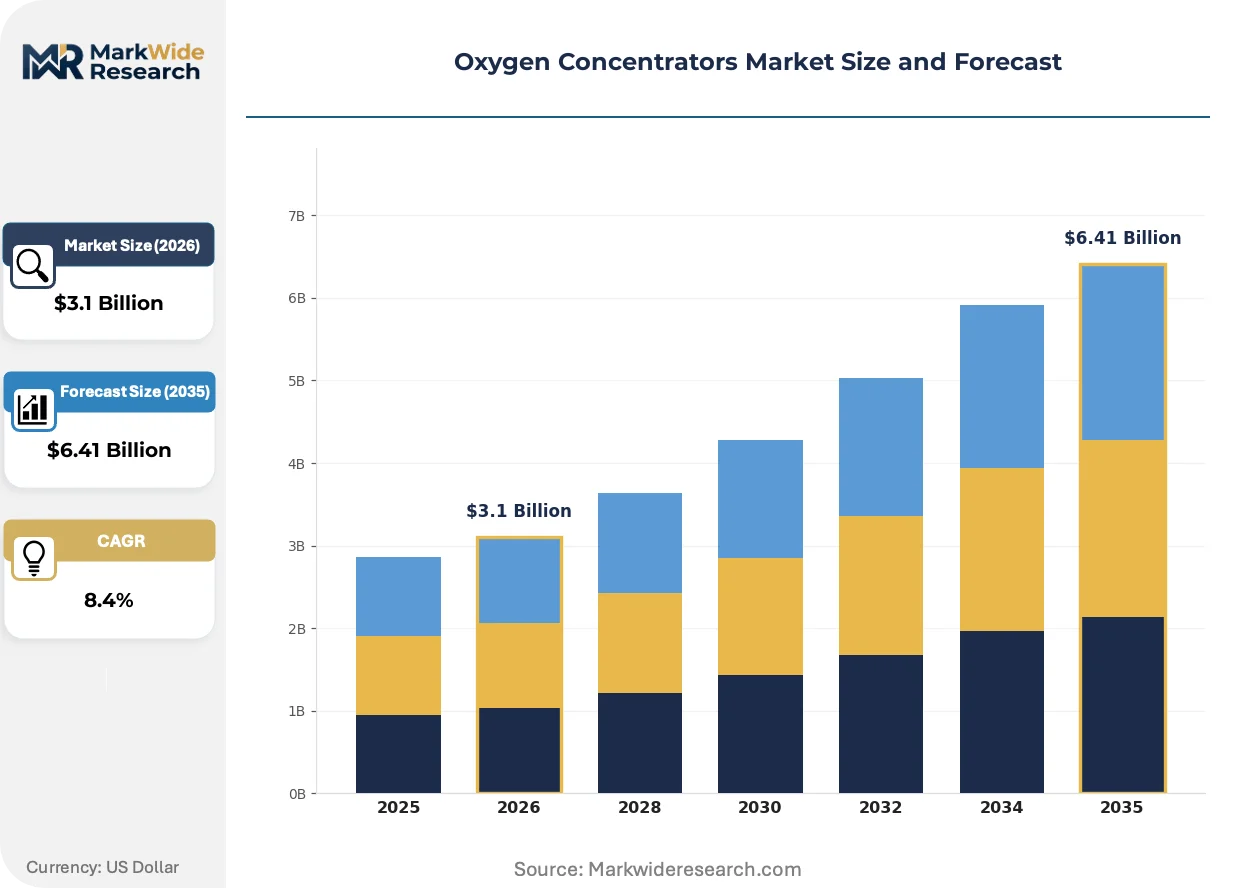
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Oxygen Concentrators, Stationary Oxygen Concentrators, Hybrid Oxygen Concentrators, Mini Oxygen Concentrators Technology: Pressure Swing Adsorption, Membrane Separation, Cryogenic Distillation, Vacuum Swing Adsorption Application: Chronic Obstructive Pulmonary Disease, Pneumonia Treatment, Sleep Apnea Therapy, Cystic Fibrosis End User: Home Healthcare Providers, Ambulatory Care Centers, Long-Term Care Facilities, Respiratory Clinics |
| Companies Covered | Koninklijke Philips, Inogen, Inc., CAIRE Inc., Drive DeVilbiss Healthcare, Invacare Corporation, Jiangsu Yuyue Medical Equipment & Supply Co., Ltd., Chart Industries, Inc., Nidek Medical Products, Inc., ResMed Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Concentrators Market Strategic Shifts & Innovations
The evolution of oxygen concentrators is defined by a push towards greater patient autonomy and integration into connected care ecosystems. This transition transforms the device from a standalone medical apparatus into a component of a managed, long-term therapeutic service.
Pressure Swing Adsorption (PSA) technology uses zeolite molecular sieves to separate nitrogen from ambient air, producing concentrated oxygen. Home healthcare patients and long-term care facilities are rapidly adopting devices built on this principle. The market's product architecture is migrating from bulky, power-intensive stationary units to lightweight, battery-operated portable systems that support an active lifestyle.
Europe's Medical Device Regulation (MDR) has introduced more rigorous requirements for clinical evidence and post-market surveillance. This regulation forces manufacturers to generate more extensive data to prove safety and performance throughout a device's lifecycle. Portable oxygen concentrator manufacturers are particularly affected, facing higher costs and longer timelines to secure or maintain CE marking for market access.
A notable behavioral shift involves the move from one-time capital equipment sales to recurring revenue models, including rentals and service bundles. This change is disrupting the business of traditional durable medical equipment (DME) providers, who face new competition from manufacturers selling directly to consumers. This model is most advanced in the United States market, where it aligns with home healthcare provider reimbursement structures.
Oxygen Concentrators Market Segmentation
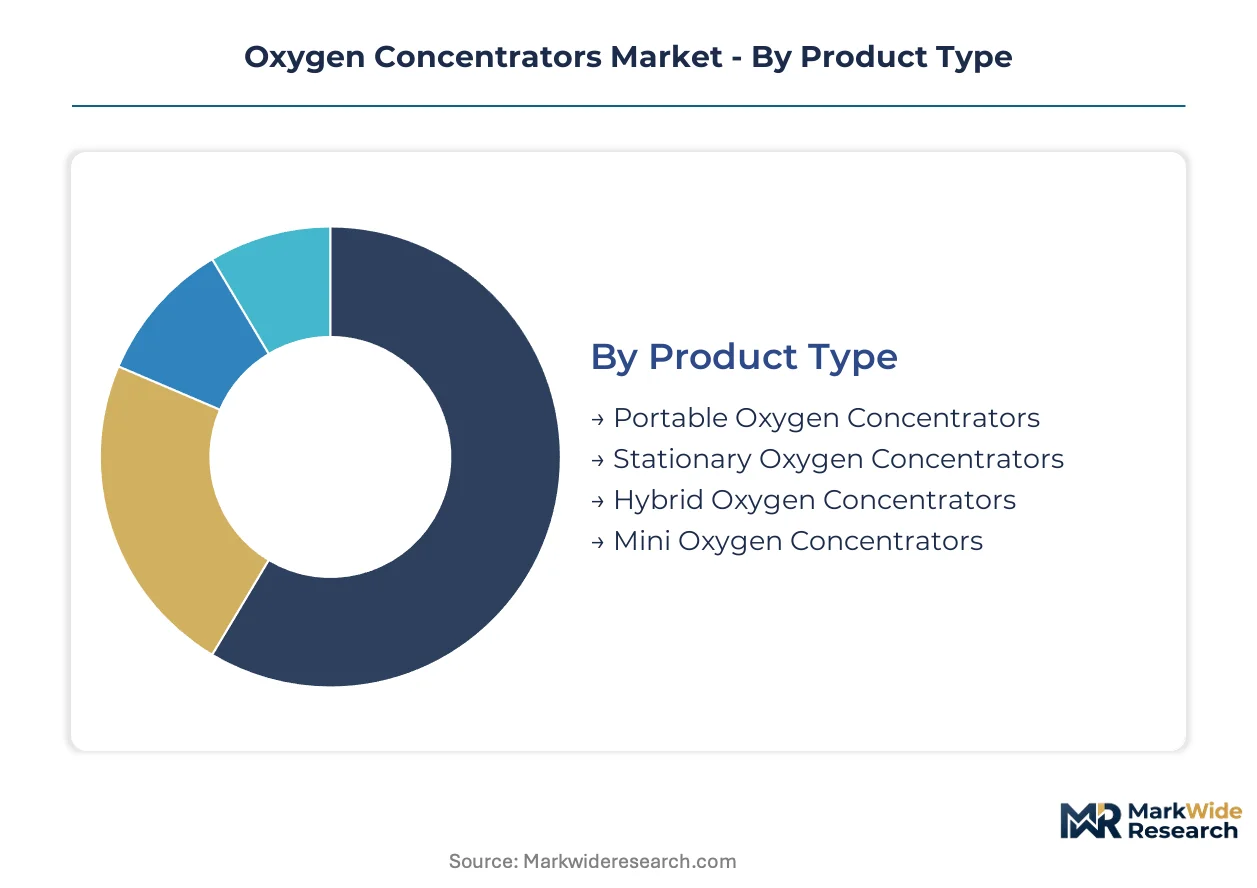
The oxygen concentrators market segments across distinct product types, underlying technologies, clinical applications, and diverse end-user channels. Understanding these classifications reveals the specific demands influencing device design, distribution strategies, and regulatory pathways. This detailed segmentation highlights areas of established market strength and identifies emerging growth opportunities for manufacturers.
Product Type:
The market's product architecture is bifurcated by patient mobility requirements, spanning devices for continuous home use and portable solutions for active individuals.
- Portable Oxygen Concentrators:These lightweight, battery-operated devices provide oxygen on demand, enabling patients to maintain an active lifestyle outside their homes. Demand concentrates in developed nations like the United States, driven by an aging population seeking greater independence.
- Stationary Oxygen Concentrators:Larger, more powerful units deliver a continuous flow of oxygen for patients requiring long-term therapy within a fixed setting, typically a home or long-term care facility. These systems are foundational for managing chronic respiratory conditions, particularly in home healthcare.
- Hybrid Oxygen Concentrators:These devices offer flexibility, combining features of both portable and stationary units for varied patient needs.
- Mini Oxygen Concentrators:Characterized by ultra-compact size and reduced weight, these concentrators prioritize discretion for patients with less intensive oxygen requirements.
Stationary Oxygen Concentrators commands the established base. The steepest expansion runs through Portable Oxygen Concentrators.
Technology:
Technological differentiation drives the efficiency and performance of oxygen concentrators, with various methods employed for gas separation.
- Pressure Swing Adsorption:This dominant technology uses zeolite molecular sieves to selectively adsorb nitrogen from ambient air, producing high-purity oxygen. Its advancements enable smaller, more efficient portable units, particularly for home healthcare applications.
- Vacuum Swing Adsorption:A variant of PSA, this technology operates at lower pressures, potentially offering improved energy efficiency and reduced device size. It is gaining adoption in compact portable systems, enhancing patient mobility.
- Membrane Separation:This method employs selective membranes to separate oxygen from other atmospheric gases, offering continuous flow with simpler mechanical components.
- Cryogenic Distillation:This traditional, large-scale method cools air to liquefy and separate components, yielding high-purity oxygen for industrial production.
Pressure Swing Adsorption holds the foundational position, while Vacuum Swing Adsorption technology is gaining traction.
Application:
Clinical conditions dictate the specific therapeutic requirements and device configurations, influencing demand across various patient populations.
- Chronic Obstructive Pulmonary Disease:This condition represents the largest application segment, driving significant demand for long-term oxygen therapy, especially in developed nations with aging populations. Devices are designed to provide consistent, reliable oxygen delivery for daily management.
- Sleep Apnea Therapy:Oxygen concentrators can supplement CPAP machines for patients experiencing hypoxemia during sleep, offering a potential growth area beyond traditional respiratory diseases. Clinical evidence for this combined therapy is expanding, creating new market opportunities.
- Pneumonia Treatment:Oxygen therapy supports patients recovering from severe pneumonia by improving oxygen saturation. Short-term use in hospital and home settings is common.
- Cystic Fibrosis:Patients with advanced cystic fibrosis often require supplemental oxygen to manage lung damage and improve quality of life. Concentrators provide continuous support.
Chronic Obstructive Pulmonary Disease therapy remains the primary application. Sleep Apnea Therapy presents a significant area for future expansion.
End User:
The end-user landscape reflects the diverse healthcare settings and provider types that utilize oxygen concentrators for patient care.
- Home Healthcare Providers:These entities manage long-term oxygen therapy for patients in their residences, favoring compact and user-friendly concentrators. Favorable reimbursement policies in countries like the United States encourage this care shift.
- Long-Term Care Facilities:Nursing homes and assisted living centers use stationary concentrators for residents requiring continuous oxygen support over extended periods. These facilities demand reliable, low-maintenance systems for their patient populations.
- Ambulatory Care Centers:Outpatient clinics and day surgery centers utilize concentrators for short-term oxygen administration during procedures or patient recovery. Portability is key.
- Respiratory Clinics:Specialized clinics diagnose and treat respiratory conditions, employing concentrators for patient assessments and therapy initiation. Precise delivery is crucial.
Home Healthcare Providers drive the largest segment. Long-Term Care Facilities are expanding their adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption patterns for oxygen concentrators vary significantly across global regions. Developed nations prioritize portable units for active lifestyles, while emerging markets often focus on foundational stationary systems. This differential reflects diverse healthcare infrastructures and patient mobility needs, shaping regional demand profiles.
United States
Aging demographics and favorable reimbursement policies for home healthcare drive robust demand for oxygen concentrators. Premarket clearance from the US FDA ensures device safety and efficacy, directly influencing market access. Major medical device hubs like Minneapolis-St. Paul foster continuous innovation in portable oxygen concentrator design and functionality.
Japan
A rapidly aging population and high prevalence of Chronic Obstructive Pulmonary Disease create strong demand for long-term oxygen therapy solutions. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees product approvals, maintaining stringent quality standards for medical devices. Tokyo's advanced healthcare technology sector focuses on miniaturization and extended battery life for portable units.
Germany
The country's robust healthcare system and increasing home care adoption support both stationary and portable concentrator use. CE marking under Europe's Medical Device Regulation (MDR) mandates rigorous clinical evidence and post-market surveillance for market entry. The "Medical Valley" in Erlangen drives research and development for advanced respiratory care devices.
China
Improving healthcare infrastructure and rising disposable incomes are expanding access to oxygen therapy for chronic conditions. China's NMPA approval process guides market entry for both domestic and international medical device manufacturers. Shenzhen's medical equipment manufacturing base is scaling up production of cost-effective oxygen concentrator solutions for a large patient base.
Oxygen Concentrators Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic market structure. The oxygen concentrators market exhibits a tiered competitive landscape, with established medical device giants alongside specialized portable unit manufacturers. Strategic archetypes include diversified healthcare conglomerates, focused direct-to-consumer specialists, and broad-portfolio providers. Key competitive moves involve portfolio diversification into services and strategic partnerships for market access.
Within the specialized portable unit segment, Inogen, Inc. exemplifies a direct-to-consumer sales model, focusing on patient mobility solutions. Koninklijke Philips, a diversified healthcare technology company, leverages its extensive ecosystem to bundle services with its oxygen concentrator devices. CAIRE Inc. operates with a broad portfolio, covering both portable and stationary systems, catering to a wider range of end-user needs. These players represent different approaches to market penetration and value capture within the oxygen concentrator industry.
| Leading Market Players |
|---|
| Koninklijke Philips |
| Inogen, Inc. |
| CAIRE Inc. |
| Drive DeVilbiss Healthcare |
| Invacare Corporation |
| Jiangsu Yuyue Medical Equipment & Supply Co., Ltd. |
| Chart Industries, Inc. |
| Nidek Medical Products, Inc. |
| ResMed Inc. |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes, vital for delivering oxygen concentrators from Asian manufacturing hubs, directly influence regional pricing and supply chain concentration. Their cost dynamics impact the final differentiation of portable versus stationary units.
Pricing Analysis
Contract-based long-term offtake agreements define the predominant pricing model for oxygen concentrators with institutional buyers. Price differentiation stems from device quality grade, specifically oxygen purity, and comprehensive CE marking and US FDA certifications. Pricing pressure stems from increased competition from Asian manufacturers. Home healthcare providers exhibit the highest price sensitivity due to fixed reimbursement rates.
Supply Chain Analysis
Zeolite molecular sieves, essential for oxygen separation, form the upstream feedstock for concentrator manufacturing. Geographic supply concentrates in China for both components and device assembly, alongside specialized material suppliers in Europe. Single-source vulnerability for advanced microprocessors presents a structural risk. Downstream distribution runs through direct-to-consumer channels and business-to-business sales to long-term care facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oxygen concentrators market operates with a defensive moat, primarily due to regulatory entrenchment from stringent medical device approvals. This structural advantage limits rapid market entry and ensures product quality.
For Market Incumbents:Entrench existing market positions by diversifying portfolios into comprehensive service bundles, moving beyond device sales. Strategic partnerships with large home healthcare networks can counter reimbursement variability. Investment in R&D for next-generation battery technology provides a crucial lever against competitive threats from alternative oxygen delivery systems. Focus on advanced US FDA and Europe MDR certifications.
For New Entrants and Emerging Players:Emerging market penetration in Southeast Asia, characterized by improving healthcare infrastructure, represents a penetrable entry point. Target cost-effective, durable stationary units for public health systems and basic portable models for a growing middle class. Local manufacturing partnerships offer a viable go-to-market angle. Rural clinics in countries like India and Vietnam present significant white space.
For Investors and Strategic Acquirers:Specialized portable unit manufacturers with established direct-to-consumer channels represent an attractive acquisition target archetype. The long-term viability of this market is anchored by sustained demand from aging demographics and the rising prevalence of chronic respiratory diseases over the next decade. Increased M&A activity involving digital health integration firms signals a key inflection point for future value creation. Evaluate companies with strong intellectual property in miniaturization.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA/CE Marking Pathway Acceleration | Streamlines market access for new and updated device models in key developed regions. |
| Remote Patient Monitoring Integration | Enhances patient adherence and clinical outcomes through connected care ecosystems. |
| Localized Manufacturing Expansion | Reduces supply chain risks and improves responsiveness to regional demand shifts. |
| Service Bundle Development | Shifts revenue models from one-time sales to recurring, value-added subscriptions. |
| Battery Technology R&D Investment | Extends portable unit mobility and addresses a critical patient pain point. |
Research Approach
Operator-level perspectives from home healthcare administrators, respiratory therapists, medical device engineers, and procurement managers anchored the qualitative base of this analysis. Primary interviews combined with secondary validation from US FDA filings, Europe MDR guidance documents, and NMPA approval databases informed initial hypotheses. This approach integrated both bottom-up market sizing with top-down validation.
Scenario-bracketing framed the quantitative forecasts over the projection horizon, considering optimistic and conservative outlooks. Segmentation dimensions modeled included product type, technology, application, end-user channel, and regional regulatory compliance. Compound Annual Growth Rates were derived through regression analysis of historical trends and projected market drivers. COPD prevalence rates and aging population statistics served as key industry-specific forecast inputs.
Practitioners should monitor shifts in reimbursement policies, new medical device regulations, and breakthroughs in alternative therapies for early signals indicating potential forecast revisions. Forecasts reflect assumptions regarding technological evolution and healthcare expenditure trends. Cross-checking against World Health Organization disease burden reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Annuloplasty System Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Global Structural Heart Devices Market
Medical Devices
Cervical Spacer Systems Market
Medical Devices
Spinal Implant Market
Medical Devices
Medical Smart Glasses Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Refurbished Medical Devices Market
Medical Devices
Bowel Irrigation System Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Lung Preservation Systems Market
Medical Devices
Micro Balloon Catheter Market