
 China Medical Imaging Market | 2026-2036
China Medical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Medical Imaging Market Insights
The China medical imaging equipment landscape is shifting between premium imported systems and domestically manufactured alternatives. Siemens Healthineers leverages its established service infrastructure to sustain installed-base loyalty among top-tier hospitals. United Imaging Healthcare anchors its position through in-house production of core components and aggressive pricing on 3.0T MRI systems. Mindray competes on portable ultrasound and digital X-ray platforms designed for county-level hospital networks.
Medical imaging encompasses the generation of visual representations of internal body structures for clinical diagnosis and treatment planning, utilizing ionizing radiation, magnetic fields, or acoustic waves with spatial resolutions ranging from sub-millimeter CT slices to whole-body MRI fields. CT scan platforms command the largest revenue share due to their ubiquity in emergency and trauma workflows, while MRI systems capture premium margins in neurology and musculoskeletal applications. Digital imaging technology is displacing analog architectures across all product categories, though hybrid systems retain relevance in cost-sensitive installations where infrastructure constraints limit full digital conversion.
NMPA device registration requirements and updated GB standards for electromagnetic compatibility and radiation exposure govern product market access, with provincial health commissions layering tender specifications that favor domestic suppliers in certain equipment categories. The dual carbon goals framework from MEE is beginning to influence hospital procurement criteria, adding energy efficiency metrics to imaging system evaluations. Stakeholders must monitor how provincial centralized procurement programs rebalance price competition against clinical performance specifications in subsequent bidding rounds.
Market Dynamics
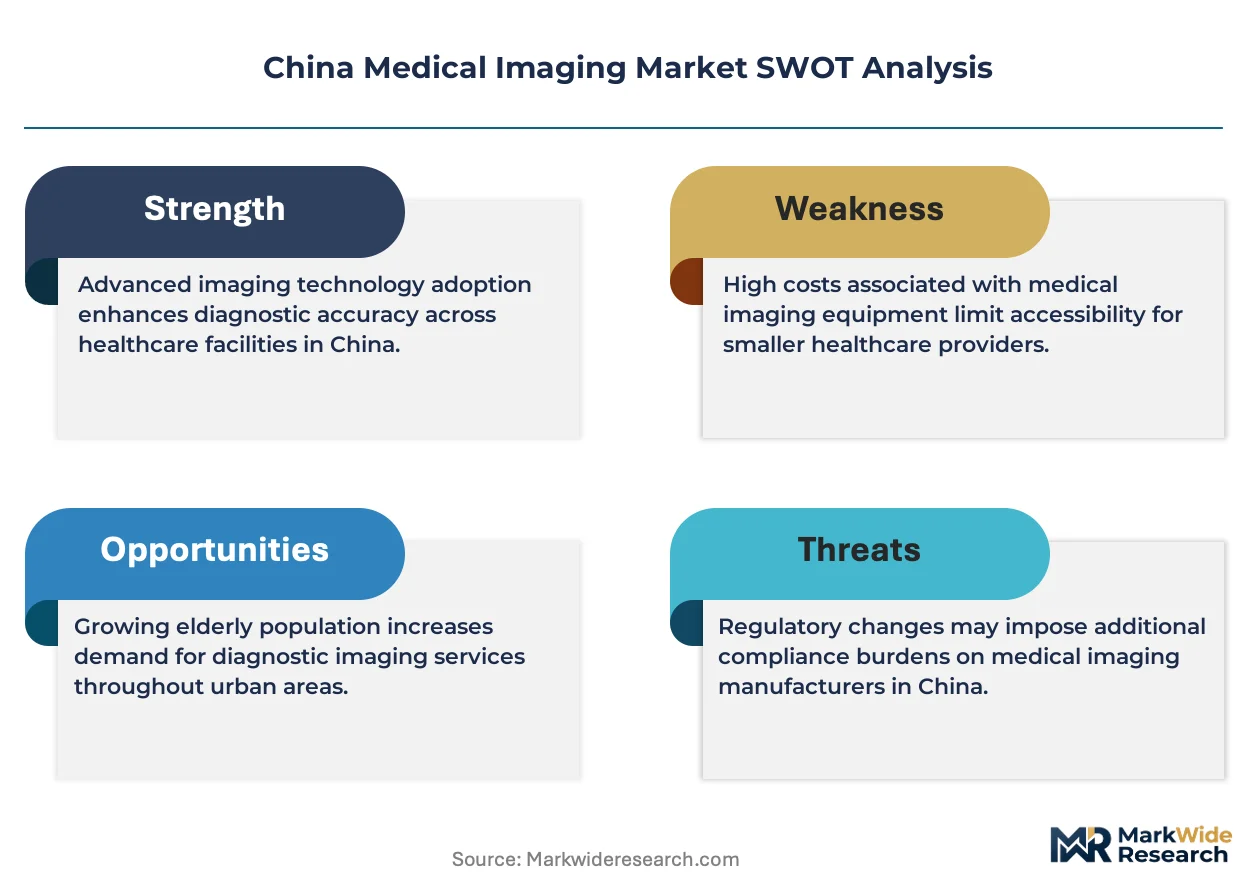
Provincial centralized procurement programs are compressing margins across CT and MRI categories while simultaneously accelerating domestic manufacturer certification timelines under NMPA's streamlined pathways.
Growth Catalysts
- Dual Carbon Goals Framework:MEE mandates are embedding energy efficiency metrics into hospital tender evaluations, favoring next-generation systems with lower helium consumption and reduced power draw.
- County-Level Hospital Networks:Healthcare infrastructure expansion into tier-three and county facilities is generating volume demand for digital X-ray and portable ultrasound platforms.
- Spectral CT Technology:Material decomposition capabilities for iodine quantification and virtual monoenergetic imaging are commanding priority capital allocation in oncology departments.
Market Restraints
- Superconducting Wire Concentration:Niobium-titanium and niobium-tin supply chains concentrate among Japanese and European specialty metal suppliers, exposing domestic MRI manufacturers to input cost volatility.
- Class III Device Approval Friction:NMPA clinical trial requirements for novel imaging agents and AI-integrated diagnostic software extend certification timelines beyond 18 months for foreign applicants.
- Helium Supply Vulnerability:Cryogenic cooling dependency for superconducting magnets ties system availability to Qatar and Algeria LNG byproduct extraction, with spot price spikes pressuring total cost of ownership.
Strategic Opportunities
- Western Province Penetration:Sichuan, Shaanxi, and Xinjiang healthcare commissions are expanding imaging infrastructure budgets with explicit domestic preference clauses in equipment tenders.
- AI-Assisted Diagnostic Workflows:Integration of deep learning reconstruction algorithms with existing CT and MRI hardware is creating software monetization layers without full system replacement.
- Mobile Imaging Fleet Deployment:Containerized MRI and CT units are penetrating rural screening programs and emergency response networks where fixed installation remains impractical.
Industry Challenges
- Clinical Application Specialist Shortage:Radiologists with dual competency in imaging physics and AI algorithm validation remain scarce, constraining deployment of advanced reconstruction protocols.
- Legacy PACS Integration Complexity:Hospital information system heterogeneity forces customized middleware development for each installation, extending deployment cycles and service costs.
- Interoperability Standard Fragmentation:DICOM-RT and HL7 FHIR implementation gaps between domestic and imported systems complicate multi-vendor enterprise imaging strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Medical Imaging Market |
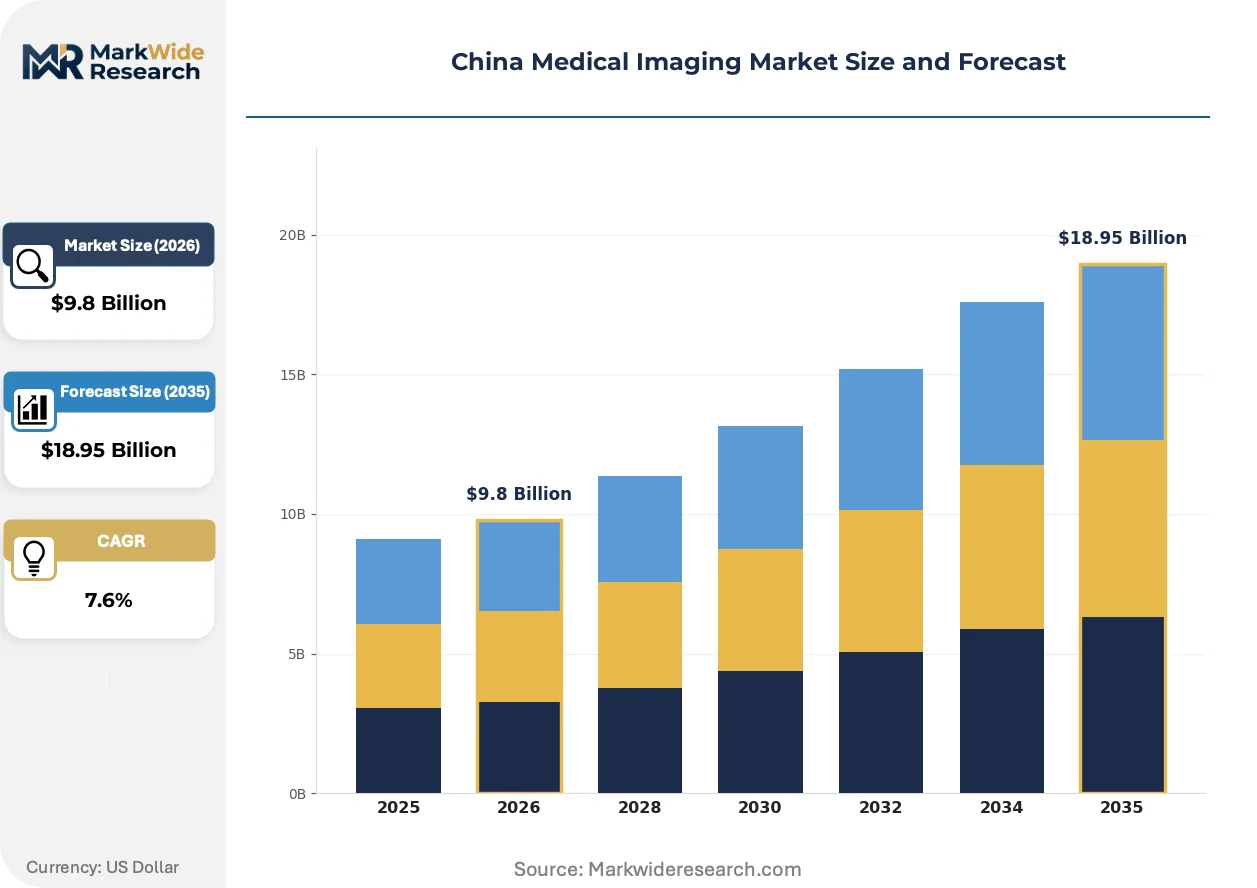
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, Ultrasound, MRI, CT Scan End User: Hospitals, Clinics, Diagnostic Centers, Research Facilities Technology: Digital Imaging, Analog Imaging, Hybrid Systems, 3D Imaging Application: Cardiology, Oncology, Neurology, Orthopedics |
| Companies Covered | Siemens Healthineers, Koninklijke Philips, Mindray, Wandong Medical, Canon, United Imaging Healthcare, GE Healthcare, SonoScape, Neusoft Medical Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Medical Imaging Market Trends and Innovations
Digital detector technology and computational imaging algorithms are compressing hardware differentiation while elevating software and service capabilities as primary competitive battlegrounds.
Photon-counting CT detector architecture is consolidating technical leadership among early movers by replacing energy-integrating scintillators with direct-conversion semiconductors. Tier-one hospitals in Beijing and Shanghai are prioritizing procurement of cadmium-zinc-telluride-based systems for cardiac and pediatric applications. This transition is consolidating vendor relationships around those with captive detector fabrication capabilities or exclusive supply agreements.
NMPA's updated GB standards for electromagnetic compatibility and radiation exposure are tightening device registration requirements for imported systems. The regulatory friction is compressing effective market access timelines and elevating compliance costs for manufacturers without established Shanghai or Beijing regulatory affairs infrastructure. Domestic suppliers with embedded certification expertise are capturing accelerated approval pathways.
Hospital procurement committees are unbundling equipment acquisition from long-term service contracts, compressing vendor lock-in and elevating third-party maintenance providers. County-level facilities in Guangdong and Jiangsu are piloting performance-based service agreements with independent imaging engineers. This disintermediation is most visible in ultrasound and digital radiography categories where technical complexity permits non-OEM service delivery.
China Medical Imaging Market Segmentation
China's medical imaging market segments along clinical workflow intensity, procurement budget tiers, and infrastructure maturity. Procurement committees evaluate systems against NMPA certification status, dual carbon compliance metrics, and integration complexity with legacy hospital information systems.
Product Type:
Customization intensity varies from standardized portable units to fully configured multi-modality suites requiring site-specific architectural planning.
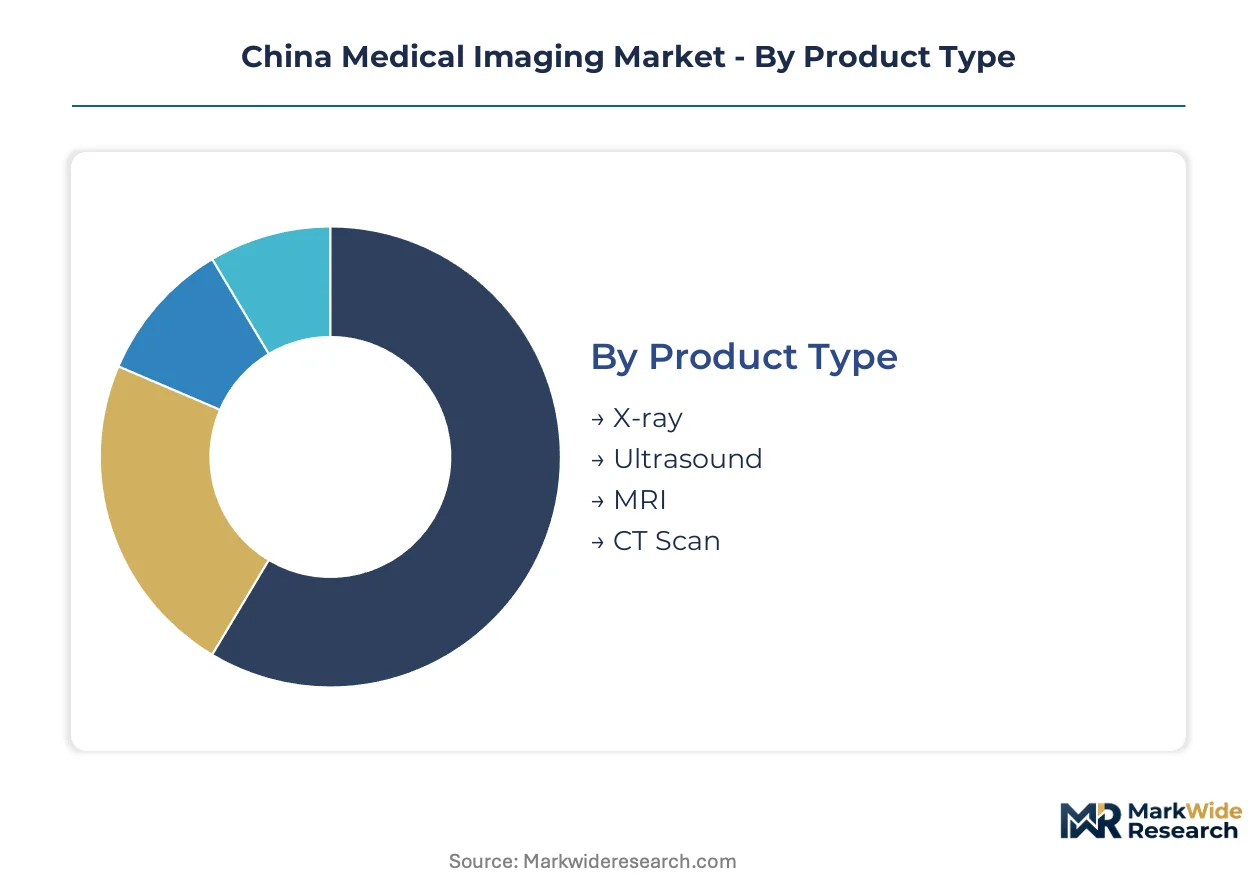
- CT Scan:Energy-integrating and photon-counting detector architectures dominate emergency department and trauma workflow deployments. Beijing and Shanghai tier-one hospitals prioritize spectral CT systems for iodine quantification and virtual monoenergetic imaging in oncology departments. Most installed capacity flows through CT Scan. Expansion is steepest in MRI.
- MRI:Superconducting 1.5T and 3.0T systems with niobium-titanium magnet windings generate premium margins in neurology and musculoskeletal applications. County-level hospital networks in Sichuan and Shaanxi are expanding 1.5T procurement under provincial centralized purchasing programs with explicit domestic preference clauses.
- X-ray:Digital radiography panels with cesium iodide scintillators are displacing computed radiography in county hospital upgrades.
- Ultrasound:Portable cart-based systems with shear wave elastography capabilities address point-of-care diagnostics in tier-three facilities.
CT Scan absorbs the largest capital allocation share. MRI commands the steepest expansion trajectory.
End User:
Procurement authority concentrates with facility tier, determining access to centralized provincial tender programs versus independent acquisition protocols.
- Hospitals:Tier-one public institutions in Beijing and Shanghai deploy high-field MRI and spectral CT through multi-year capital budgets. NMPA Class III device approval timelines and MEE dual carbon energy efficiency metrics shape vendor selection committees. Volume concentrates with Hospitals. Procurement velocity is climbing fastest in Diagnostic Centers.
- Diagnostic Centers:Independent imaging chains in Guangdong and Jiangsu unbundle equipment acquisition from service contracts, piloting performance-based agreements with third-party maintenance providers. These facilities prioritize throughput-optimized CT platforms and digital X-ray systems for high-volume screening workflows.
- Clinics:County-level primary care points favor portable ultrasound and compact digital radiography units.
- Research Facilities:Academic medical centers in Xi'an and Chengdu deploy preclinical imaging systems for translational oncology studies.
Hospital procurement committees control the dominant installed base. Diagnostic center expansion is gaining share fastest.
Technology:
Architecture migration patterns reflect infrastructure constraints, capital availability, and interoperability requirements with legacy PACS installations.
- Digital Imaging:Direct-conversion flat-panel detectors and solid-state ultrasound transducers eliminate chemical processing and film archival costs. Digital detector technology is compressing hardware differentiation while elevating software reconstruction algorithms as competitive differentiators across Beijing and Shanghai installations.
- Hybrid Systems:Analog-digital transitional architectures retain relevance in cost-sensitive county hospital networks where infrastructure constraints limit full digital conversion. These configurations balance upfront capital constraints against incremental upgrade pathways.
- 3D Imaging:Cone-beam CT and volumetric ultrasound reconstruction enable surgical planning and interventional guidance.
- Analog Imaging:Film-screen radiography persists in remote western province facilities with unreliable power infrastructure.
Digital imaging platforms anchor current procurement volumes. 3D imaging integration is expanding most quickly in surgical planning workflows.
Application:
Clinical priority determines capital allocation sequencing, with precision diagnostics commanding budget priority over screening workflows.
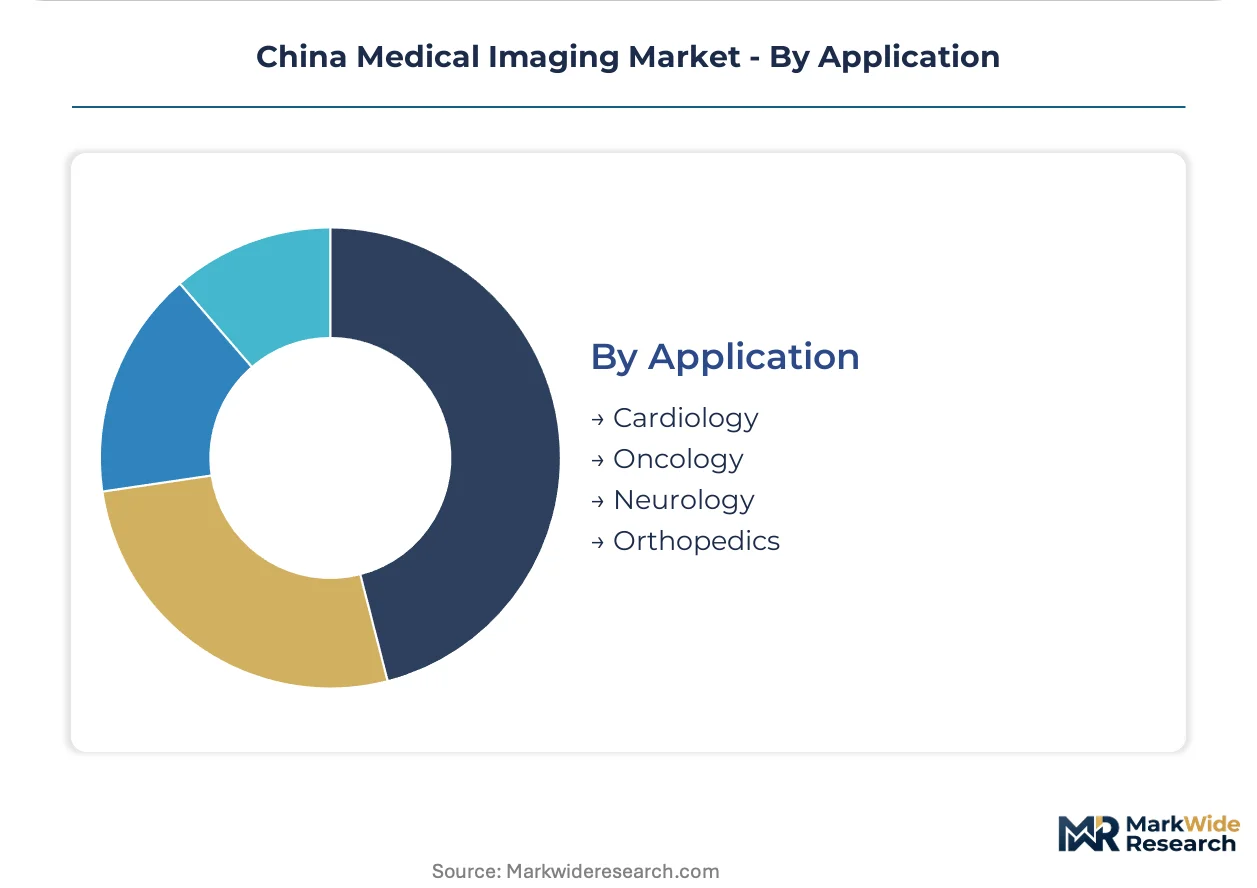
- Oncology:Spectral CT material decomposition and PET-CT fusion imaging support staging and treatment response assessment. Oncology departments in tier-one hospitals prioritize procurement of systems with AI-assisted lesion detection and radiomics quantification capabilities.
- Neurology:Functional MRI and diffusion tensor imaging protocols require high-field 3.0T systems with advanced gradient coil performance. Neurology applications capture premium system margins due to clinical complexity and reimbursement rates.
- Cardiology:Cardiac CT angiography and stress echocardiography drive demand for temporal resolution optimization.
- Orthopedics:Weight-bearing CT and dedicated extremity MRI address musculoskeletal trauma and joint replacement planning.
Oncology absorbs the largest specialized imaging capital allocation. Neurology system deployment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiologists with dual competency in imaging physics and AI algorithm validation concentrate in Beijing and Shanghai, anchoring the national market's technical leadership while county-level networks expand procurement velocity across western provinces.
Beijing-Tianjin-Hebei
Academic medical centers drive demand for high-field MRI and spectral CT systems with AI-assisted diagnostic capabilities. NMPA streamlined Class III device approval pathways accelerate certification timelines for domestic manufacturers establishing regulatory affairs infrastructure. Peking Union Medical College Hospital and Beijing Tiantan Hospital anchor procurement of premium imaging platforms for neurology and oncology workflows.
Yangtze River Delta
Shanghai's tier-one public hospitals prioritize photon-counting CT and 3.0T MRI systems with advanced gradient coil performance. Provincial health commissions layer tender specifications favoring domestic suppliers under centralized procurement programs. Ruijin Hospital and Huashan Hospital concentrate spectral CT deployments for iodine quantification in oncology departments.
Pearl River Delta
Independent diagnostic imaging chains in Guangdong unbundle equipment acquisition from long-term service contracts. MEE dual carbon goals embed energy efficiency metrics into hospital tender evaluations. Guangzhou and Shenzhen facilities pilot performance-based agreements with third-party maintenance providers for digital X-ray and portable ultrasound platforms.
Sichuan-Chongqing
County-level hospital networks expand 1.5T MRI procurement under provincial centralized purchasing with explicit domestic preference clauses. Healthcare infrastructure budgets prioritize digital radiography panels displacing computed radiography. West China Hospital in Chengdu anchors high-field system deployment for translational oncology studies.
Shandong Peninsula
Manufacturing clusters for core imaging components concentrate in Jinan and Qingdao with in-house production of digital detector assemblies. Provincial tenders favor systems with reduced helium consumption and lower power draw under energy efficiency mandates. Shandong University-affiliated hospitals drive adoption of portable ultrasound with shear wave elastography for tier-three facility networks.
China Medical Imaging Market Competitive Landscape
Top-tier vendors anchor Beijing and Shanghai tier-one hospitals, while domestic manufacturers capture county-level networks through aggressive pricing on standardized platforms. The market structures around three tiers: multinational incumbents with established service infrastructure, integrated domestic champions with captive component production, and specialized regional suppliers. Strategic moves concentrate on backward integration into superconducting magnet supply chains and AI software licensing partnerships for diagnostic algorithm integration.
Among multinational incumbents, Siemens Healthineers and GE Healthcare occupy positions sustained by installed-base loyalty and regulatory affairs infrastructure. Within the domestic integrated tier, United Imaging Healthcare exemplifies vertical control through in-house production of core components. Mindray represents the portable modality specialist archetype targeting county-level hospital networks with cart-based ultrasound and digital X-ray platforms.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Koninklijke Philips |
| Mindray |
| Wandong Medical |
| Canon |
| United Imaging Healthcare |
| GE Healthcare |
| SonoScape |
| Neusoft Medical Systems |
| Others |
Pricing and Supply Chain Analysis
Photon-counting CT detector architecture is compressing hardware differentiation and simultaneously consolidating supply concentration among vendors with captive cadmium-zinc-telluride fabrication capabilities or exclusive semiconductor foundry agreements. This technological inflection simultaneously elevates upfront system costs while embedding energy efficiency gains that reshape total cost-of-ownership calculations for hospital procurement committees evaluating NMPA Class III device certifications.
Pricing Analysis
The bundled-versus-unbunded service split is fragmenting vendor lock-in across county-level hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates spectral CT systems with AI reconstruction from conventional energy-integrating platforms and refurbished analog-digital hybrid configurations. Price differentiation rests on NMPA certification grade and after-sales service bundling. Cost compression in mid-tier MRI is intensifying because provincial centralized procurement programs compress vendor margins. County-level facilities exhibit highest price sensitivity; tier-one Beijing and Shanghai academic centers prioritize clinical performance over acquisition cost.
Supply Chain Analysis
NMPA domestic-content preference clauses in provincial tenders are reshaping sourcing patterns toward in-house production of digital detector assemblies and gradient coil windings. Superconducting niobium-titanium wire draws from Japanese and European specialty metal suppliers; cryogenic helium feeds from Qatar and Algeria LNG byproduct extraction; rare-earth magnet materials source from domestic Chinese mining operations. Single-source vulnerability in superconducting wire exposes domestic MRI manufacturers to input cost volatility. Distribution runs through provincial health commission tender platforms with explicit technical specification layering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China medical imaging market reads as a late-cycle quality story where hospital procurement committees are reallocating capital toward photon-counting CT and high-field MRI systems with AI-integrated diagnostic capabilities despite compressed reimbursement environments.
For Market Incumbents: Extend service infrastructure depth into western province county networks before domestic manufacturers cement installed-base relationships. Siemens Healthineers and GE Healthcare should accelerate regulatory affairs staffing in Beijing to compress NMPA Class III approval timelines for AI-integrated software modules. Backward integration into superconducting magnet supply chains offers margin defense against niobium-titanium price volatility.
For New Entrants and Emerging Players: Begin with portable ultrasound and digital X-ray platforms targeting Sichuan and Shaanxi county-level hospital networks where provincial tenders embed explicit domestic preference clauses. The most penetrable white space sits in third-party maintenance services for unbundled equipment contracts in Guangdong independent diagnostic chains. A performance-based service agreement go-to-market model disintermediates OEM lock-in without requiring full system manufacturing capability.
For Investors and Strategic Acquirers: Valuations sit cheapest among domestic component specialists with captive digital detector fabrication and established NMPA certification infrastructure. Long-term viability over a multi-year window hinges on software monetization layers for AI-assisted reconstruction algorithms rather than hardware replacement cycles. The signal to watch is provincial centralized procurement program expansion into spectral CT categories, which would validate domestic manufacturer technical maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Device Certification | Accelerated approval timelines for domestic manufacturers compress foreign competitor market access under updated GB standards. |
| Helium Conservation Technology Investment | Reduced cryogenic consumption aligns with MEE dual carbon mandates and lowers total cost of ownership for superconducting MRI. |
| AI Software Companion Development | Deep learning reconstruction algorithms create recurring revenue streams without requiring full hardware replacement cycles. |
| Provincial Hospital System Partnership | Preferred vendor status in Beijing and Shanghai tier-one academic centers anchors premium product adoption. |
| Third-Party Maintenance Service Launch | Independent service provision exploits unbundling trends in Guangdong diagnostic center procurement patterns. |
Research Methodology
Direct dialogue with hospital procurement committee members, biomedical engineers, GPO contracts managers, and NMPA regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from NMPA device registration databases, provincial health commission tender announcements, hospital procurement records, and MEE dual carbon policy documentation. Bottom-up equipment installation tracking and top-down healthcare infrastructure budget analysis were triangulated to cross-validate market sizing.
Segment-level projections across product type, end user, technology, and application dimensions were generated through the analytical framework. CAGRs were derived from weighted average of historical procurement velocity and modeled policy impact coefficients. Key forecast inputs included provincial centralized procurement program expansion schedules and NMPA streamlined pathway certification throughput rates.
Several conditions sit outside the modeled scope, including unannounced MEE regulatory amendments, superconducting wire supply disruptions, and geopolitical friction affecting helium export logistics. Forecasts reflect documented assumptions regarding NMPA approval timeline stability and provincial budget execution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
Europe Diagnostic Imaging Equipment Market
Medical Imaging
Middle East and Africa Clinical Trial Imaging Market
Medical Imaging
Global Image Guided Therapy System Market
Medical Imaging
Pediatric Imaging Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
India Computed Tomography Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
US Teleradiology Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
Cranial Doppler Market