
 Europe Speech Therapy Market | 2026-2036
Europe Speech Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Speech Therapy Market Insights
Subscription-based leasing of speech therapy software platforms is reconfiguring how independent clinics and regional health networks access digital tools without capital expenditure. Benchmark Therapies leverages cloud-delivered assessment modules to extend its footprint across NHS-contracted services in England. Smart Speech Therapy anchors its competitive position through specialized fluency disorder content that dominates Scandinavian public procurement channels. London Speech Therapy sustains premium positioning by controlling in-person referral networks while layering hybrid teletherapy options for post-operative voice rehabilitation.
Speech therapy encompasses clinical assessment, diagnostic intervention, and rehabilitative treatment of communication and swallowing disorders using standardized protocols, acoustic analysis software, and biofeedback devices. The discipline applies frequency modulation algorithms, aerodynamic measurement systems, and laryngoscopic visualization to restore functional speech patterns in patients with neurological, structural, or developmental impairments. Software segments lead value generation where artificial intelligence-powered articulation scoring commands recurring licensing fees from institutional buyers. Teletherapy delivery mode captures the fastest expansion trajectory as reimbursement parity laws in France and Germany validate remote clinical encounters. Pediatric patient end users concentrate volume demand through school-based early intervention mandates across EU member states.
EMA oversight of software-based medical devices and the EU Medical Device Regulation establish conformity requirements for speech therapy platforms seeking CE marking and market access across the European Economic Area. GDPR compliance shapes how patient voice recordings and biometric speech data traverse cloud infrastructure serving cross-border teletherapy sessions. France's ANSM and Germany's BfArM enforce divergent pre-market review timelines that fragment go-to-market speed for platform developers. Stakeholders must monitor evolving national reimbursement catalogues that determine whether digital speech therapy tools qualify for statutory health insurance coverage.
Market Dynamics
EU Medical Device Regulation enforcement is fragmenting platform certification timelines across the European Economic Area, forcing developers to navigate divergent national pre-market review pathways while pediatric teletherapy demand accelerates through school-based early intervention mandates.
Growth Catalysts
- Reimbursement parity frameworks:France and Germany now validate remote clinical encounters through statutory health insurance coverage, removing payment barriers for teletherapy delivery.
- Pediatric early intervention mandates:School-based screening programs across EU member states concentrate volume demand among children with developmental speech disorders.
- Cloud-delivered assessment modules:Independent clinics access artificial intelligence-powered articulation scoring without capital expenditure through subscription licensing models.
Market Restraints
- CE marking timeline fragmentation:France's ANSM and Germany's BfArM enforce divergent pre-market review durations that delay platform launches by quarters.
- GDPR compliance overhead:Patient voice recordings and biometric speech data require specialized cloud infrastructure for cross-border teletherapy sessions.
- Specialist workforce scarcity:Licensed speech-language pathologists concentrate in urban centers, leaving rural regions underserved despite platform availability.
Strategic Opportunities
- Scandinavian public procurement channels:Specialized fluency disorder content commands premium positioning in Norway, Sweden, and Denmark where national health systems prioritize evidence-based digital tools.
- Post-operative voice rehabilitation:Hybrid teletherapy options capture oncology and otolaryngology referral networks previously served only through in-person delivery.
- EU AI Act alignment:Speech therapy platforms that proactively embed algorithmic transparency documentation gain accelerated conformity assessment pathways.
Industry Challenges
- Legacy EMR integration complexity:Regional health networks in England and Germany require custom API development to synchronize teletherapy platforms with existing patient record systems.
- Multilingual content localization:Platform developers must rebuild articulation scoring algorithms for phonemic inventories across Romance, Germanic, and Slavic language families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Speech Therapy Market |
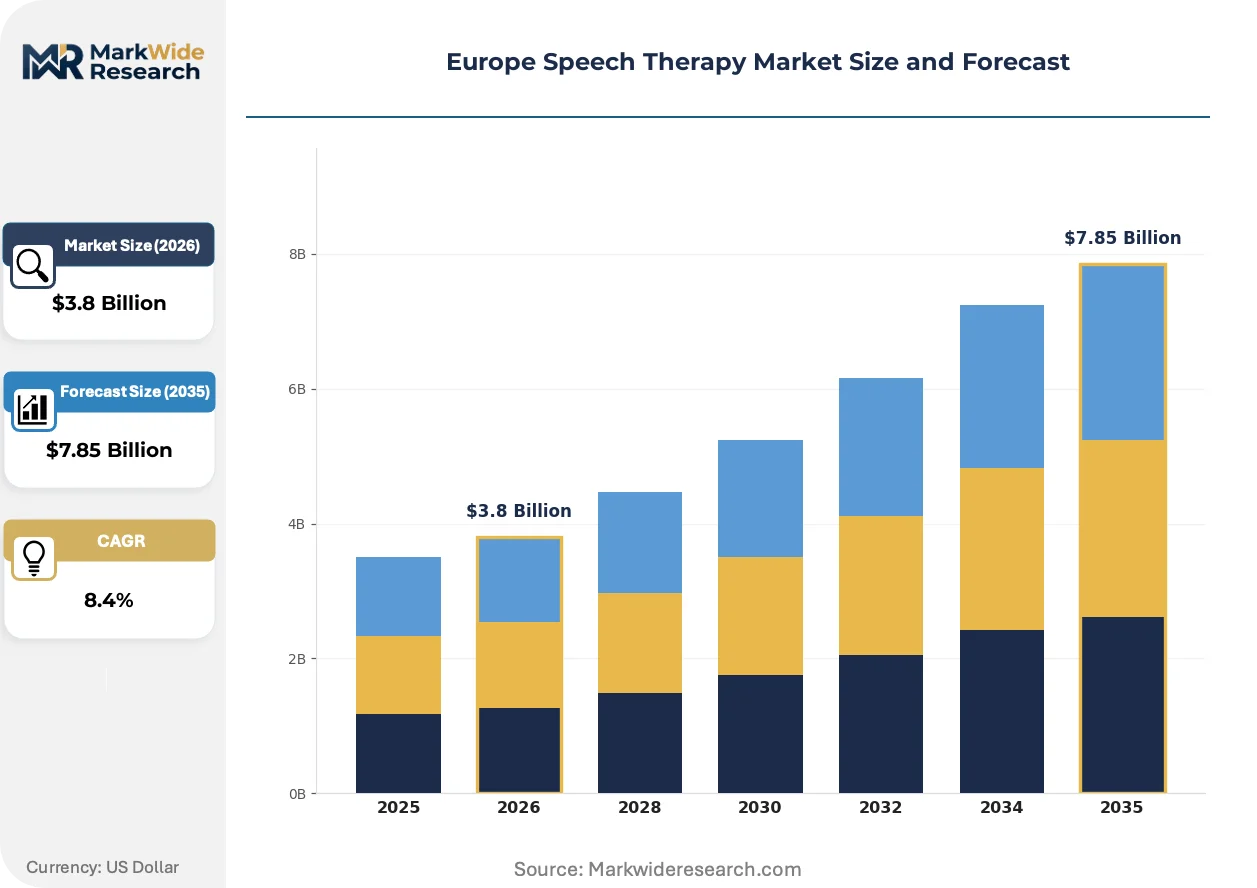
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Devices, Apps, Resources End User: Pediatric Patients, Adults, Clinicians, Educators Delivery Mode: In-Person, Teletherapy, Hybrid, Self-Directed Application: Articulation Disorders, Fluency Disorders, Voice Disorders, Language Disorders |
| Companies Covered | Benchmark Therapies, Smart Speech Therapy, London Speech Therapy, Speech Pathology Australia, Glenda Browne Speech Pathology, Speech Therapy Services London Ltd., Therapy Solutions, Sonova Holding AG, Speech Plus, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Speech Therapy Market Trends and Innovations
Speech therapy delivery is compressing the boundary between synchronous telehealth sessions and asynchronous AI-guided practice, with reimbursement policy and platform certification evolving in parallel.
Frequency modulation algorithms paired with aerodynamic measurement systems are hybridizing traditional in-clinic biofeedback with home-based sensor arrays. Pediatric clinics in the Netherlands and Belgium are adopting these hybrid systems fastest, drawn by reduced appointment frequency requirements. The technology is hybridizing clinical labor models by enabling therapists to oversee multiple patients simultaneously through automated progress monitoring dashboards.
EU Medical Device Regulation software-as-medical-device classifications are tightening documentation requirements for speech therapy platforms seeking CE marking. Developers must now submit clinical performance studies demonstrating equivalence to established diagnostic protocols. Platforms targeting neurological rehabilitation indications face the steepest compliance burdens, with several vendors withdrawing from the stroke recovery segment rather than absorbing validation costs.
Institutional buyers are consolidating vendor relationships around platforms offering bundled assessment and treatment content rather than purchasing point solutions. NHS-contracted services in England now require single-platform coverage across articulation, fluency, and voice disorder domains. France's regional health agencies are following this pattern, with three-quarters of new tenders specifying integrated content libraries over specialized tools.
Europe Speech Therapy Market Segmentation
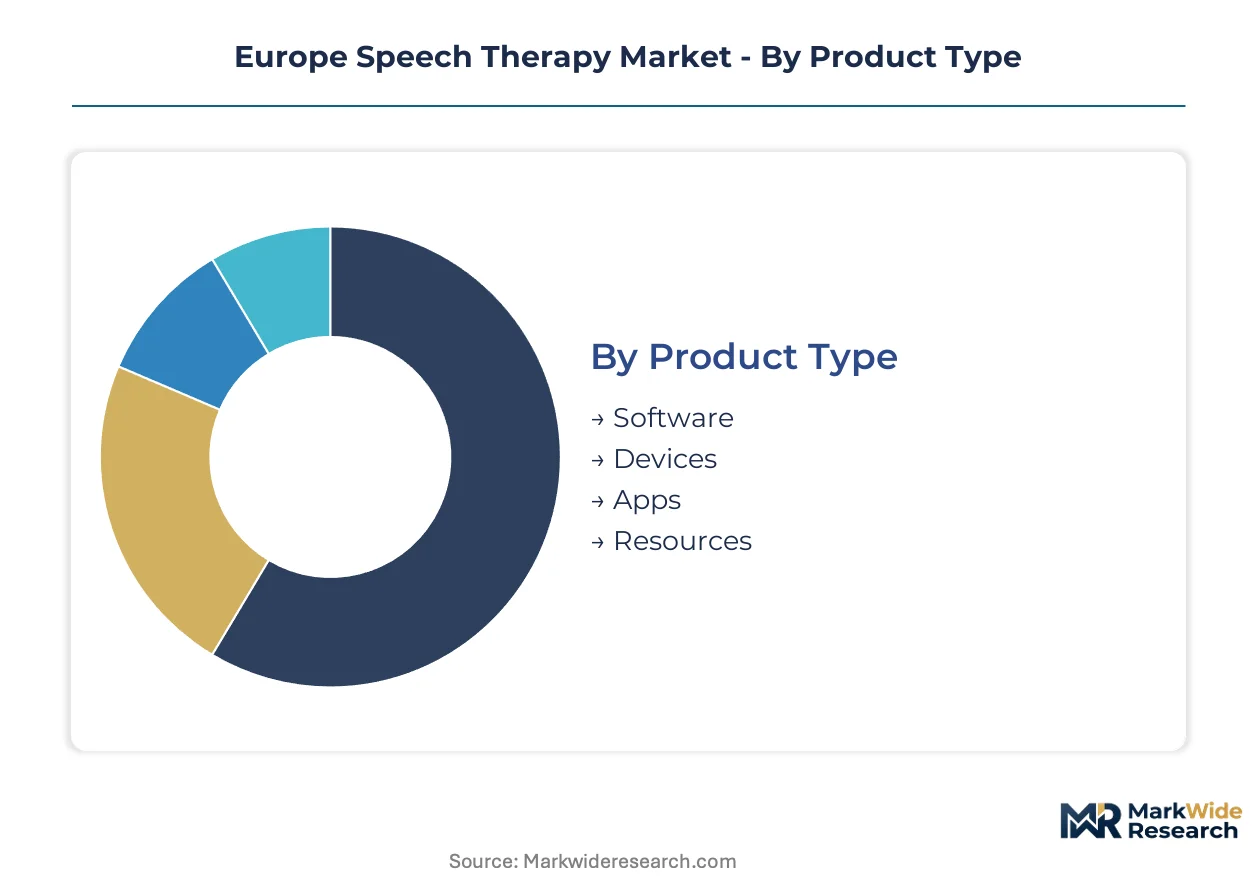
Speech therapy platforms fragment across four intersecting dimensions that determine procurement cycles and reimbursement eligibility. Product type governs capital intensity and regulatory pathway complexity. End user concentration shapes feature prioritization and pricing architecture.
Product Type:
Software platforms turn over fastest through subscription renewal cycles, while hardware devices persist for years under capital amortization schedules.
- Software:Cloud-delivered assessment modules with AI-powered articulation scoring command recurring licensing fees from NHS-contracted services in England. German statutory health insurers now reimburse these tools under digital health application frameworks, accelerating procurement velocity.
- Devices:Aerodynamic measurement systems and laryngoscopic visualization hardware require CE marking under EU Medical Device Regulation and face extended validation timelines before French ANSM or German BfArM approval.
- Apps:Consumer-facing mobile applications targeting home practice compliance operate outside reimbursement frameworks and rely on direct-to-clinic sales.
- Resources:Printable materials and standardized protocol manuals carry minimal regulatory burden but generate thin margins in competitive tender environments.
Software dominates installed base. Devices is where expansion concentrates as hybrid care models proliferate.
End User:
Pediatric concentration drives volume through school-based mandates, while clinician-facing tools command premium pricing through workflow integration requirements.
- Pediatric Patients:Early intervention mandates across EU member states concentrate demand for gamified practice modules and parent engagement dashboards. Netherlands and Belgium clinics adopt these fastest under reduced appointment frequency protocols.
- Adults:Post-operative voice rehabilitation and neurological recovery indications require specialized biofeedback integration that extends sales cycles.
- Clinicians:Practice management platforms with EMR synchronization capture institutional procurement in England and Germany despite custom API development costs.
- Educators:School-based screening tools face budget constraints but benefit from bulk purchasing agreements through regional education authorities.
Pediatric Patients anchors volume demand. Clinicians is where margin expansion concentrates through workflow lock-in.
Delivery Mode:
Reimbursement parity laws in France and Germany validate remote encounters, compressing teletherapy adoption cycles relative to traditional in-person models.
- In-Person:Traditional clinic-based delivery retains dominance for initial diagnostic assessments and complex neurological rehabilitation requiring hands-on biofeedback.
- Teletherapy:Synchronous remote sessions gain statutory health insurance coverage in France and Germany, removing payment barriers that previously constrained adoption.
- Hybrid:Blended models combining periodic in-clinic assessment with home-based sensor arrays enable therapist oversight of multiple patients through automated monitoring dashboards.
- Self-Directed:Asynchronous AI-guided practice modules operate outside reimbursement frameworks and compete on subscription pricing.
In-Person dominates current service delivery. Teletherapy is climbing the fastest as regulatory frameworks align.
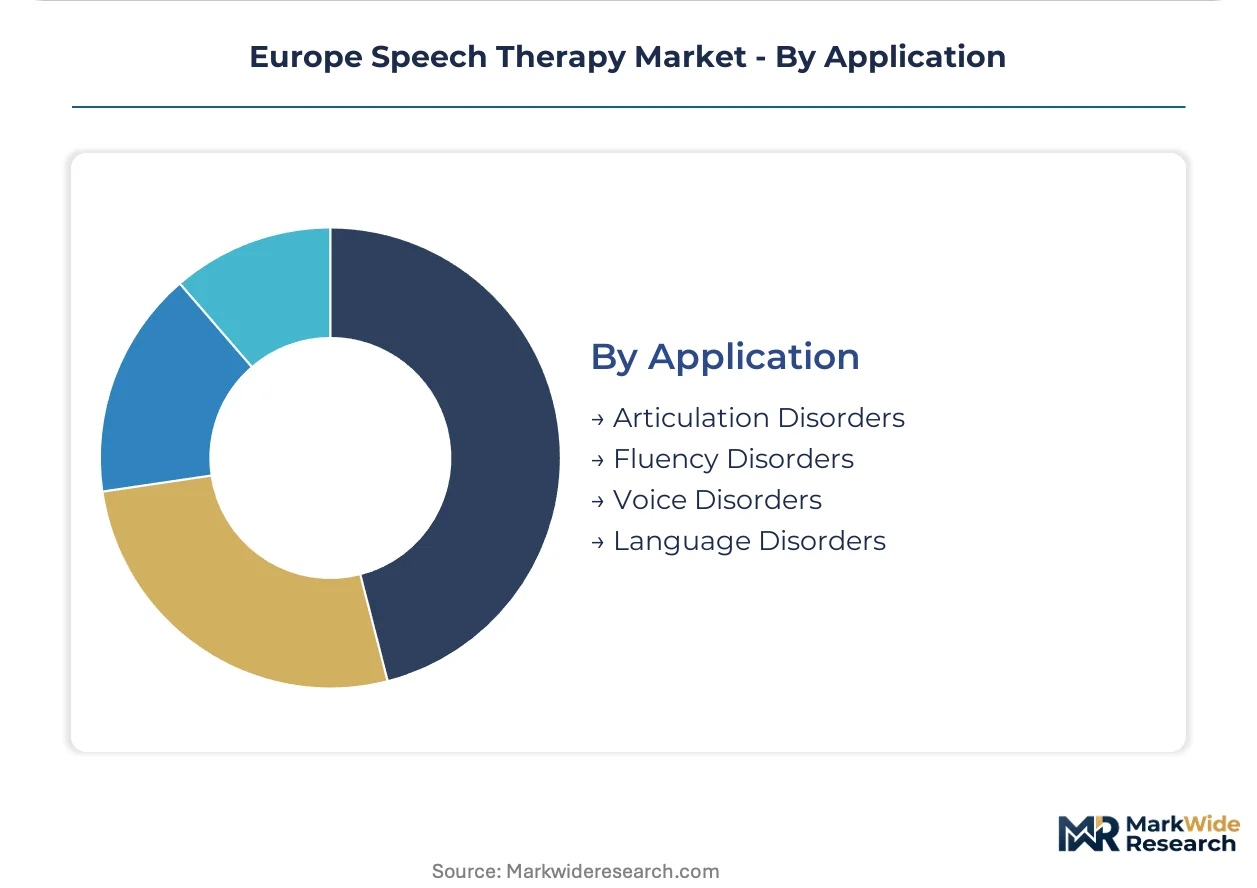
Application:
Articulation and language disorder tools benefit from standardized protocols that accelerate content development, while voice disorder applications require specialized acoustic engineering that extends R&D timelines.
- Articulation Disorders:Phoneme-specific scoring algorithms with multilingual localization requirements target school-based early intervention programs across Romance and Germanic language zones.
- Fluency Disorders:Specialized content for stuttering intervention commands premium positioning in Scandinavian public procurement channels where Norway, Sweden, and Denmark prioritize evidence-based digital tools.
- Voice Disorders:Post-operative rehabilitation platforms integrate with oncology and otolaryngology referral networks previously served only through in-person delivery.
- Language Disorders:Aphasia and cognitive-communication applications face steepest EU MDR compliance burdens, with several vendors withdrawing from stroke recovery segments rather than absorbing validation costs.
Articulation Disorders dominates content library breadth. Fluency Disorders is gaining share fastest through specialized procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional procurement in the Europe Speech Therapy Market concentrates around national health reimbursement frameworks, with statutory insurers in Germany and France validating digital therapeutic platforms while NHS-contracted services in England drive bundled content requirements.
Germany
German statutory health insurers now reimburse cloud-delivered speech assessment tools under digital health application frameworks, accelerating procurement velocity for AI-powered articulation platforms. BfArM enforces extended pre-market review timelines that delay CE-marked platform launches by multiple quarters. Berlin and Munich host the densest concentration of pediatric teletherapy adopters, where regional health networks prioritize EMR-integrated practice management systems.
France
France's regional health agencies are consolidating vendor relationships around single-platform solutions covering articulation, fluency, and voice disorder domains. ANSM maintains divergent review pathways from German regulators, fragmenting go-to-market speed for developers seeking EEA-wide deployment. The Paris metropolitan area anchors demand for hybrid teletherapy models serving post-operative voice rehabilitation through oncology referral networks.
United Kingdom
NHS-contracted services in England now mandate bundled assessment and treatment content, rejecting point solutions in favor of integrated platform coverage. London Speech Therapy controls premium positioning through in-person referral network dominance while layering remote options. The Greater London and Southeast clusters concentrate the highest density of school-based early intervention mandates driving pediatric software adoption.
Netherlands
Dutch pediatric clinics adopt hybrid biofeedback systems fastest under reduced appointment frequency protocols enabled by home-based sensor arrays. GDPR compliance requirements shape how patient voice recordings traverse cloud infrastructure serving cross-border teletherapy sessions. Amsterdam and Rotterdam health networks lead implementation of automated progress monitoring dashboards allowing simultaneous therapist oversight of multiple patients.
Sweden
Swedish public procurement channels prioritize evidence-based digital tools for fluency disorder intervention, commanding premium positioning for specialized content providers. National health system tender specifications emphasize algorithmic transparency documentation aligned with emerging EU AI Act requirements. Stockholm's regional health authority drives standardization of multilingual articulation scoring across Scandinavian phonemic inventories.
Europe Speech Therapy Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the Europe Speech Therapy Market, with institutional procurement consolidation favoring platforms offering bundled content libraries over narrow point solutions. The vendor base stratifies between NHS-integrated service providers, Nordic public procurement specialists, and cloud-native software platforms. Three archetypes dominate: referral-network controllers, reimbursement-optimized platform vendors, and hardware-software hybrid integrators. Competitive moves center on single-platform bundling strategies and EMR synchronization capabilities that lock in institutional buyers.
Among UK-based service providers, London Speech Therapy and Benchmark Therapies exemplify the referral-network controller archetype, with the former anchoring premium hybrid delivery models and the latter leveraging cloud-delivered assessment modules across NHS-contracted services. Smart Speech Therapy represents the Nordic specialization vector, occupying a position defined by fluency disorder content dominance in Scandinavian public procurement channels.
| Leading Market Players |
|---|
| Benchmark Therapies |
| Smart Speech Therapy |
| London Speech Therapy |
| Speech Pathology Australia |
| Glenda Browne Speech Pathology |
| Speech Therapy Services London Ltd. |
| Therapy Solutions |
| Sonova Holding AG |
| Speech Plus |
| Others |
Pricing and Supply Chain Analysis
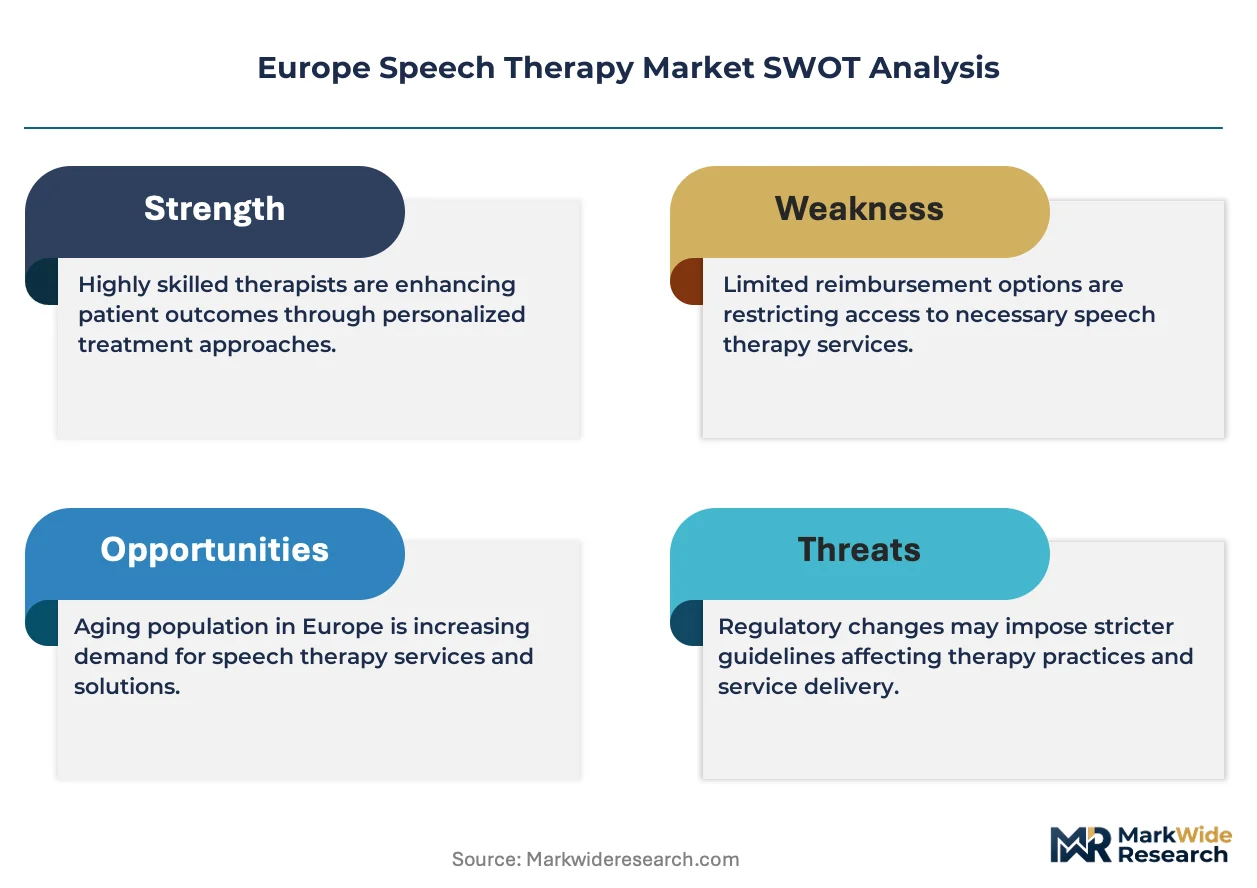
Regulatory chokepoint fragmentation across French ANSM and German BfArM review pathways compresses pricing power for platform developers while simultaneously forcing supply chain restructuring toward dual-country validation infrastructure. This divergence widens tier spreads between CE-marked premium platforms and non-reimbursed economy alternatives.
Pricing Analysis
Cost-plus contracts with German statutory health insurers index subscription fees to digital health application framework approval status, creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on EMR integration depth and BfArM pre-market review completion. Pricing pressure stems from NHS England's bundled content mandates squeezing point-solution margins. Pediatric clinic networks exhibit highest price sensitivity; oncology referral networks tolerate premium positioning.
Supply Chain Analysis
Supplier-financing through extended payment terms dominates cloud infrastructure procurement for teletherapy platforms serving cross-border sessions. Component sourcing concentrates in Ireland, Netherlands, and Germany for GDPR-compliant data centers. Raw material dependencies span acoustic sensors from Switzerland, server hardware from Taiwan, and encryption modules from South Korea. Single-source vulnerability sits with laryngoscopic visualization hardware facing EU MDR re-certification delays. Distribution runs through NHS procurement frameworks and Scandinavian public tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Speech Therapy Market functions as a service-attach opportunity where AI-powered articulation scoring subscriptions expand faster than hardware device sales, with recurring licensing fees from institutional buyers outpacing capital equipment amortization schedules.
For Market Incumbents: Build workflow integration moats by embedding practice management platforms into NHS-contracted service EMR systems. Deepen API synchronization capabilities to lock in English and German regional health networks. Counter emerging cloud-native entrants through exclusive content partnerships with Scandinavian fluency disorder specialists. Invest in BfArM fast-track certification infrastructure to compress review timelines versus fragmented competitors.
For New Entrants and Emerging Players: Pursue white-space penetration in Dutch-Belgian hybrid biofeedback systems where reduced appointment frequency protocols accelerate adoption. Target post-operative voice rehabilitation segments in French oncology referral networks previously served only through in-person delivery. Anchor go-to-market through algorithmic transparency documentation aligned with emerging EU AI Act requirements, accelerating conformity assessment pathways.
For Investors and Strategic Acquirers: The market sits at a reimbursement-alignment phase that favors platform vendors with statutory health insurance coverage validation over hardware-dependent specialists. Long-term viability favors acquisition targets combining bundled content libraries with EMR integration capabilities. Monitor French regional health agency tender specifications as the inflection signal; consolidation toward single-platform mandates will accelerate vendor roll-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Optimization | Dual-track ANSM and BfArM submissions compress EEA-wide launch timelines by quarters. |
| EMR Integration Partnership | NHS-contracted services mandate API synchronization, locking in institutional procurement cycles. |
| Scandinavian Fluency Specialization | Public procurement channels in Norway, Sweden, and Denmark prioritize evidence-based digital tools. |
| Reimbursement Strategy Alignment | German DiGA framework and French statutory coverage validate remote clinical encounter billing. |
| EU AI Act Documentation | Algorithmic transparency embedding accelerates conformity assessment for neurological rehabilitation platforms. |
Research Methodology
A standing panel of speech-language pathologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers provided ongoing calibration across the study. Primary interviews combined with secondary validation from EMA software-as-medical-device guidance documents, NHS procurement databases, BfArM approval registries, and ANSM conformity assessment records. Bottom-up teletherapy platform deployment counts triangulated against top-down statutory health insurance reimbursement data.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling delivery mode segmentation alongside product type, end user concentration, and application indication dimensions. CAGRs derived from institutional procurement velocity indices and pediatric early intervention mandate expansion rates. Forecast inputs incorporated reimbursement parity law adoption timelines and EU MDR software classification enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in European healthcare expenditure growth or GDPR enforcement stringency would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and cloud infrastructure cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
ENT Devices Market
ENT
Surgical ENT Devices Market
ENT
Global ENT Workstations Market
ENT
Head and Neck Squamous Cell Carcinoma Market
ENT
Global Pediatric Hearing Aids Market
ENT
Laryngeal Papillomatosis Treatment Market
ENT
ENT Disorder Treatment Market
ENT
North America Hearing Aid Market
ENT
Hearing Implants Market
ENT
ENT Laser Devices Market
ENT
Audiology Devices Market
ENT
Custom Hearing Aids Market
ENT
Global Acute Otitis Media Treatment Market
ENT
Global Sinusitis Treatment Market
ENT
Interventional ENT Devices Market
ENT
Europe Hearing Aids Market