
 Buccal Drug Delivery System Market | 2026-2036
Buccal Drug Delivery System Market Size, Share, and Industry Trends Forecast 2026-2036
Buccal Drug Delivery System Market Outlook
Project finance partnerships between contract development organizations and specialty pharmaceutical firms are reshaping competitive entry in buccal drug delivery. Catalent leverages its integrated formulation and manufacturing network to anchor large-scale film production for partners. Teva Pharmaceutical Industries Ltd sustains competitive positioning through specialized expertise in complex generic buccal tablets. Indivior PLC dominates the addiction-treatment buccal segment with established regulatory dossiers and prescriber relationships.
Buccal drug delivery systems administer therapeutic agents via the oral mucosa, utilizing bioadhesive polymers that achieve plasma concentrations within minutes through the highly vascularized buccal epithelium. These systems bypass hepatic first-pass metabolism, enabling improved bioavailability for drugs with low oral absorption or high presystemic clearance. Films lead the product type landscape due to patient acceptability and dose precision, while nanoparticle formulations represent the fastest-expanding formulation category as manufacturers target enhanced permeation of macromolecular therapies. Home care channels are gaining share as self-administered buccal products reduce clinic dependency for chronic conditions.
FDA bioequivalence requirements for buccal generics and EMA's MDR frameworks for drug-device combination products shape development pathways and market access timelines. ISO 10993 biocompatibility standards govern adhesive and excipient selection, creating compliance thresholds that favor established polymer suppliers. Stakeholders must monitor evolving pharmacopeial standards for mucoadhesive performance testing, as harmonization between USP and EP methods will determine which formulation platforms achieve multi-jurisdiction approval efficiency.
Market Dynamics
Bioadhesive polymer science is compressing formulation development timelines while FDA fast-track designations for buccal products are accelerating clinical validation pathways. These dual forces are reshaping competitive entry requirements and manufacturing scale-up economics.
Growth Catalysts
- EMA MDR Frameworks:Drug-device combination product classifications in Europe are creating harmonized approval pathways that reduce multi-jurisdiction filing costs for buccal film manufacturers.
- Carbomer-Polycarbophil Blends:Advanced polymer matrices are extending mucosal retention times from minutes to hours, enabling sustained-release formulations for chronic pain management.
- Oncology Clinic Expansion:Cancer treatment centers are adopting buccal formulations for breakthrough pain episodes, bypassing gastrointestinal complications in chemotherapy patients.
Market Restraints
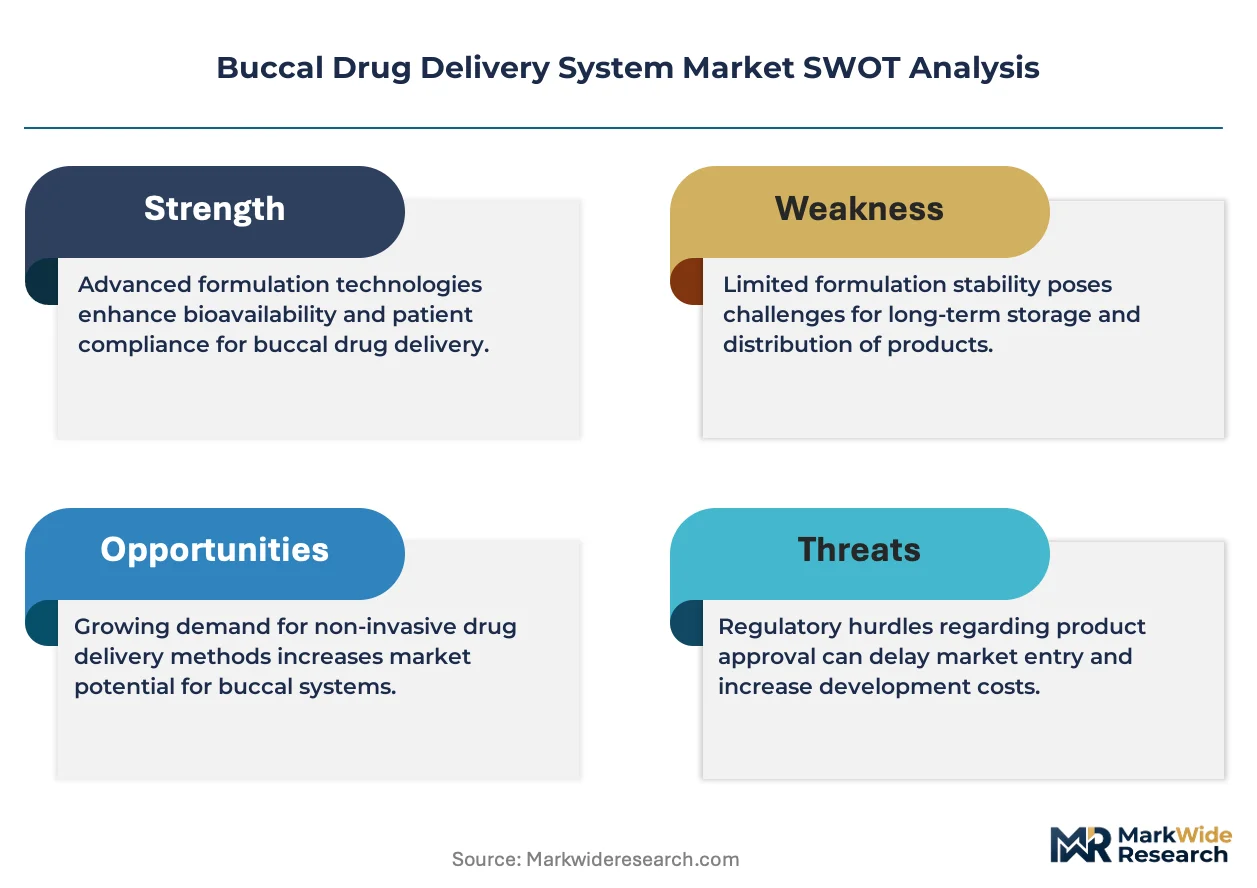
- API Cost Volatility:Specialized bioadhesive excipients and high-purity active pharmaceutical ingredients face supply concentration among German and Swiss chemical suppliers.
- ISO 10993 Compliance Burden:Biocompatibility testing standards for mucoadhesive polymers add 18-24 months to product development timelines for novel formulations.
- Oral Transmucosal Sprays:Alternative non-invasive delivery systems compete for the same prescriber relationships and pharmacy shelf space in acute pain management.
Strategic Opportunities
- Home Care Channel Expansion:Self-administered buccal products for addiction treatment and hormone replacement are reducing clinic dependency for chronic condition management.
- PLI Scheme Incentives:India's production-linked incentive programs for active pharmaceutical ingredients are attracting contract manufacturing investment for export-oriented buccal film production.
- Nanoparticle-Bioadhesive Convergence:Hybrid formulations combining nanostructured carriers with mucoadhesive matrices are opening macromolecular therapy applications previously limited to injection.
Industry Challenges
- Formulation Scientist Scarcity:The intersection of polymer chemistry, pharmaceutical science, and mucosal biology requires specialized expertise concentrated among academic centers in Massachusetts and Basel.
- USP-EP Harmonization Delays:Divergent pharmacopeial standards for mucoadhesive performance testing force redundant validation studies for products seeking simultaneous US and European approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buccal Drug Delivery System Market |
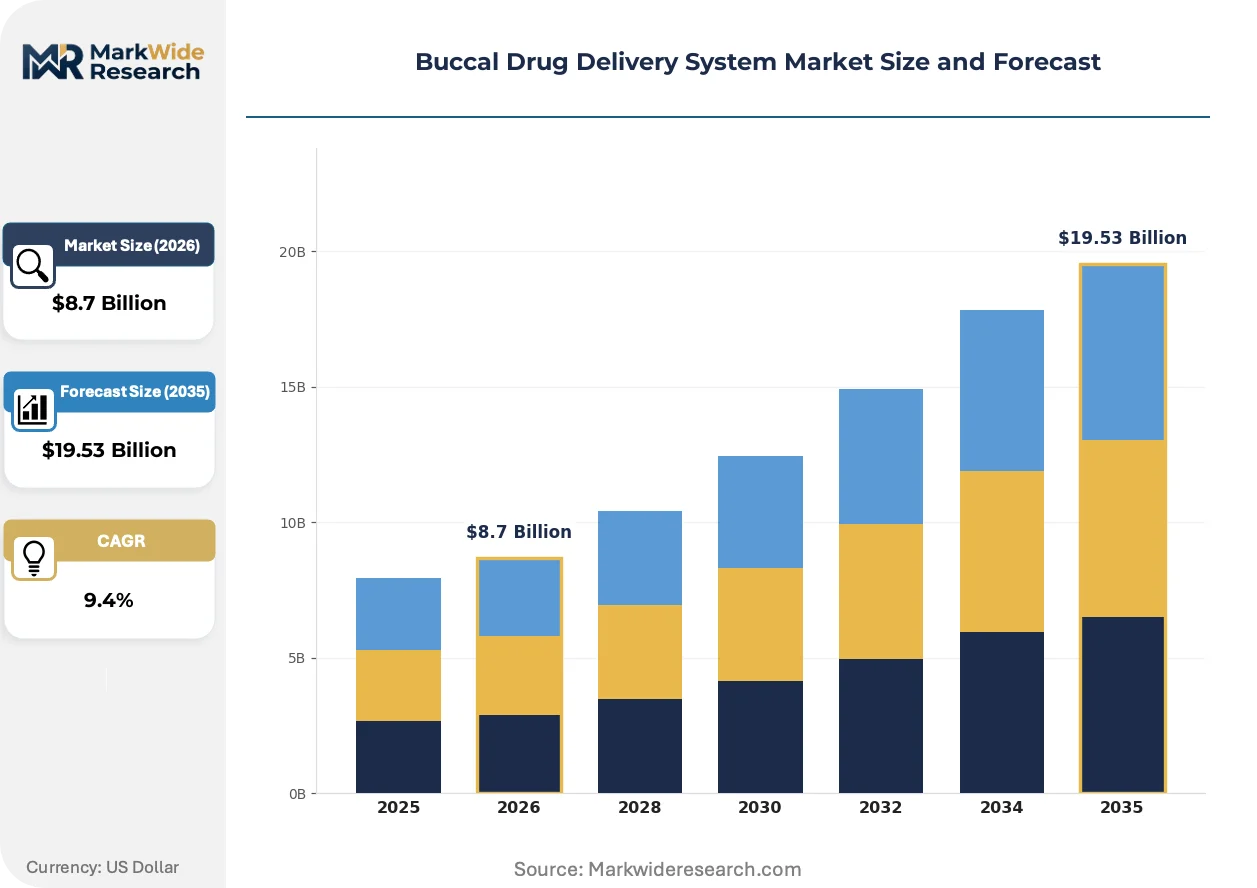
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Films, Gels, Sprays End User: Hospitals, Clinics, Home Care, Pharmacies Formulation Type: Solid, Liquid, Semi-solid, Nanoparticles Delivery Method: Passive Diffusion, Microneedles, Iontophoresis, Electroporation |
| Companies Covered | Generex Biotechnology Corporation, Catalent, Inc., Teva Pharmaceutical Industries Ltd, Indivior PLC, Endo, Inc., GSK plc, ARx, LLC., Collegium Pharmaceutical, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buccal Drug Delivery System Market Strategic Shifts
Digital formulation platforms and real-time release testing are compressing development cycles while regulatory science advances are clarifying bioequivalence boundaries for complex buccal generics.
Electrospun nanofiber matrices are enabling ultra-rapid drug dissolution through high surface-area polymer architectures. Pain management clinics in the United States are piloting these systems for fentanyl alternatives requiring sub-minute onset. This fabrication approach is virtualizing traditional solvent-casting production lines, reducing facility capital requirements by eliminating bulk drying equipment.
FDA bioequivalence guidance for locally-acting buccal products is tightening statistical requirements for comparative clinical endpoint studies. Generic manufacturers must now demonstrate equivalent mucosal residence time distributions, not just plasma pharmacokinetics. Complex generic specialists are responding by investing in biorelevant dissolution apparatus that simulates buccal hydrodynamics.
Hospital procurement consortia are consolidating supplier relationships for controlled-substance buccal formulations, favoring manufacturers with integrated DEA vault-to-pharmacy distribution networks. Specialty distributors with cold-chain capabilities are displacing traditional wholesale channels for temperature-sensitive peptide buccal films. This concentration is most visible in the Veterans Affairs health system and integrated delivery networks across the southeastern United States.
Buccal Drug Delivery System Market Segmentation
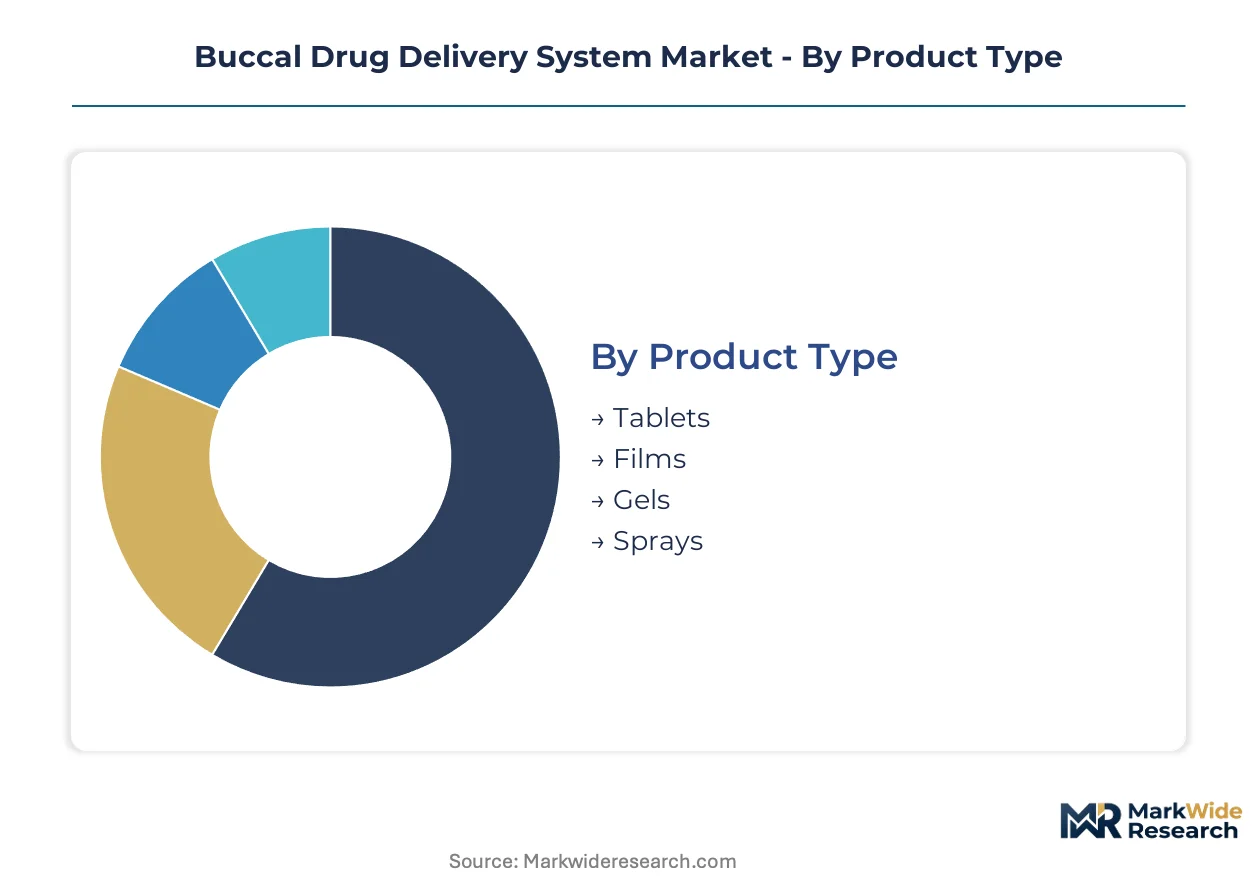
Buccal drug delivery systems fragment across four critical dimensions that determine manufacturing scale, regulatory pathway, and commercial strategy. Each category carries distinct margin profiles and technical barriers that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across formats, with films requiring formulation troubleshooting support and tablets demanding batch-specific stability monitoring.
- Films:Thin polymeric matrices dissolve within minutes through buccal hydration, enabling precise dose titration. Oncology clinics in the United States favor these for breakthrough pain management due to rapid onset and minimal patient training requirements.
- Tablets:Compressed bioadhesive formulations achieve hours-long mucosal retention through carbomer-polycarbophil matrices. Addiction treatment centers specify these for buprenorphine delivery where extended release reduces dosing frequency.
- Gels:Viscous semi-solid preparations suit pediatric and geriatric populations with swallowing difficulties.
- Sprays:Metered-dose aqueous systems compete in acute pain episodes where immediate absorption trumps duration.
Films hold the largest share; momentum sits with tablets as chronic disease applications expand.
End User:
Customer concentration patterns split between institutional procurement and retail pharmacy channels with divergent pricing power.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements for controlled-substance buccal formulations, with DEA vault-to-pharmacy distribution capabilities determining vendor selection.
- Home Care:Self-administered hormone replacement and addiction therapy products bypass clinical infrastructure, with patient adherence monitoring shifting to digital platforms.
- Clinics:Pain management and oncology centers drive adoption of rapid-onset formulations for episodic care.
- Pharmacies:Retail chains stock standard tablet formats while specialty distributors handle cold-chain peptide films.
Hospitals dominate volume procurement; home care channels are climbing the fastest as chronic disease management decentralizes.
Formulation Type:
Technical maturity gradients separate established solid formats from emerging nanoparticle architectures with unproven scale-up economics.
- Nanoparticles:Lipid or polymeric carriers below 200 nanometers penetrate buccal epithelium through paracellular pathways, opening macromolecular therapies previously limited to injection. Massachusetts and Basel academic centers concentrate formulation expertise for these hybrid systems.
- Solid:Conventional compressed tablets and lyophilized wafers anchor generic substitution strategies with established bioequivalence pathways.
- Liquid:Aqueous solutions and suspensions suit immediate-release applications with simpler manufacturing requirements.
- Semi-solid:Hydrogel and ointment bases provide topical buccal action with localized rather than systemic delivery.
Solid formulations retain the largest installed base; nanoparticles show steepest expansion trajectory as permeation science advances.
Delivery Method:
Passive systems dominate commercial deployment while active enhancement technologies remain confined to clinical development.
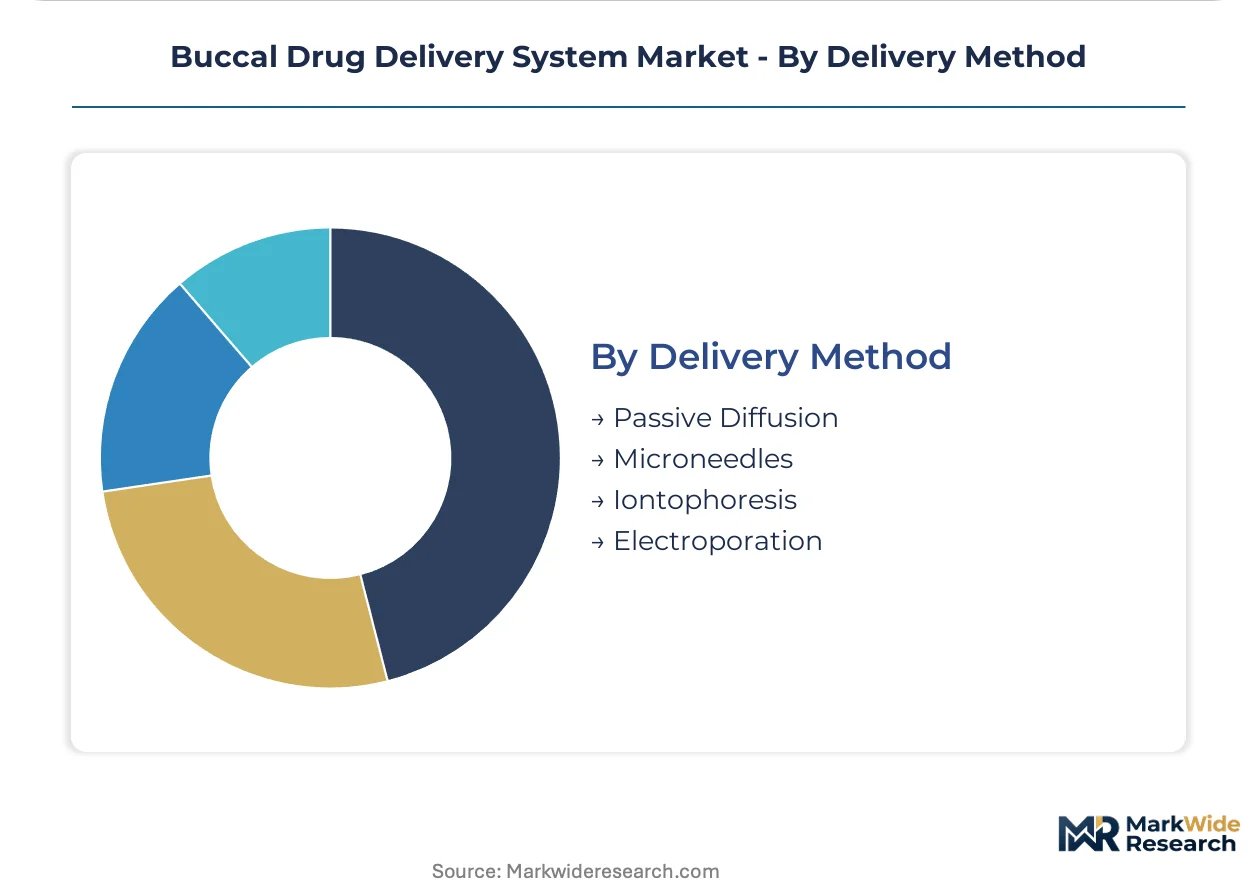
- Passive Diffusion:Concentration gradients drive drug absorption across buccal mucosa without external energy input, minimizing device complexity and regulatory burden for chronic therapies.
- Microneedles:Dissolving or hydrogel-forming microprojections breach stratum corneum barriers for macromolecular delivery, with Swiss and German suppliers controlling precision manufacturing equipment.
- Iontophoresis:Electric current-enhanced transport accelerates ionized drug penetration, limited by patient discomfort and device cost.
- Electroporation:Pulsed electrical fields transiently permeabilize cell membranes, remaining experimental for buccal applications due to tissue irritation concerns.
Passive diffusion commands the largest share; microneedles are gaining share fastest as device miniaturization progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia and oncology clinic networks concentrate demand in health systems with integrated pharmacy distribution. FDA fast-track designations attract formulation investment toward markets with accelerated approval pathways. Manufacturing scale-up economics favor regions with established bioadhesive polymer supply chains and contract development infrastructure.
United States
Veterans Affairs health systems and southeastern integrated delivery networks drive volume procurement for controlled-substance buccal formulations. FDA bioequivalence guidance for locally-acting products tightens statistical requirements for comparative clinical endpoint studies. Greater Boston and Massachusetts academic centers concentrate formulation expertise for nanoparticle-bioadhesive hybrid systems.
Germany
Specialized chemical suppliers in the Rhine-Ruhr region anchor high-purity bioadhesive excipient production for European manufacturers. EMA MDR frameworks for drug-device combination products create harmonized approval pathways that reduce multi-jurisdiction filing costs. Basel-adjacent polymer science clusters supply carbomer and polycarbophil blends extending mucosal retention times.
India
Production-linked incentive schemes for active pharmaceutical ingredients attract contract manufacturing investment for export-oriented buccal film production. CDSCO regulatory pathways align with international standards for generic buccal tablet approvals. Gujarat and Maharashtra pharmaceutical manufacturing corridors scale solvent-casting and lyophilization capacity for film and wafer formats.
Switzerland
Swissmedic oversight of complex drug-device combinations positions the country as a regulatory reference for European market access. Precision manufacturing equipment suppliers in the German-speaking cantons control microneedle fabrication technology for active enhancement delivery methods. Basel polymer chemistry institutes train formulation scientists at the intersection of mucosal biology and pharmaceutical science.
Japan
PMDA review pathways for novel dosage forms accommodate buccal delivery innovations with established biopharmaceutical classification. METI industrial policy supports domestic manufacturing of high-value pharmaceutical excipients. Kanto region contract development organizations integrate film production with packaging for regional Asian markets.
Buccal Drug Delivery System Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent margin structures. The vendor base organizes around three strategic archetypes: integrated contract development and manufacturing organizations with formulation-to-distribution networks; complex generic specialists with regulatory dossier expertise; and addiction-treatment focused firms with prescriber relationship depth. Competitive moves concentrate on strategic partnerships anchoring manufacturing scale-up and portfolio diversification into nanoparticle-bioadhesive convergence formats.
Within the integrated services tier, Catalent, Inc. exemplifies channel control through captive formulation and manufacturing networks. Teva Pharmaceutical Industries Ltd represents complex generic specialists sustaining positioning through specialized expertise. Indivior PLC anchors the addiction-treatment segment with established regulatory dossiers and prescriber relationships. These three firms occupy positions reflecting distinct competitive vectors: scale infrastructure, regulatory complexity navigation, and therapeutic vertical depth.
| Leading Market Players |
|---|
| Generex Biotechnology Corporation |
| Catalent, Inc. |
| Teva Pharmaceutical Industries Ltd |
| Indivior PLC |
| Endo, Inc. |
| GSK plc |
| ARx, LLC. |
| Collegium Pharmaceutical |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp pharmaceutical freight corridors transmit cost volatility from German and Swiss excipient suppliers directly into tiered pricing structures for bioadhesive polymer formulations, compressing margins for contract manufacturers while enabling premium capture by integrated CDMOs with captive supply chains.
Pricing Analysis
Cost-plus contracts indexed to carbomer and polycarbophil raw material baskets dominate procurement between specialty chemical suppliers and film manufacturers. Pricing stratifies across premium, standard, and economy tiers based on ISO 10993 certification status and mucosal retention performance specifications. Cost compression in standard-grade tablets is intensifying because Indian API producers are expanding solvent-casting capacity under PLI incentives. Hospital procurement consortia exhibit lowest price sensitivity due to DEA vault-to-pharmacy distribution requirements, while retail pharmacy channels face acute pressure from generic substitution mandates.
Supply Chain Analysis
Upstream feedstock concentration in German and Swiss chemical corridors anchors high-purity bioadhesive excipient production for European and North American manufacturers. Carbomer resins, polycarbophil powders, and pharmaceutical-grade solvents constitute critical input dependencies. Single-source vulnerability persists for precision microneedle fabrication equipment controlled by German-speaking Swiss suppliers. Distribution runs through specialty distributors with cold-chain capabilities for peptide films, displacing traditional wholesale channels in hospital and home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buccal drug delivery is exiting a development-cycle trough as FDA fast-track designations and EMA MDR harmonization compress approval timelines, positioning the sector for cyclical capacity expansion.
For Market Incumbents: Entrench formulation-to-distribution networks by securing DEA vault-to-pharmacy capabilities for controlled-substance buccal tablets, insulating against price erosion from Indian contract manufacturers. Deepen backward integration into carbomer-polycarbophil blending operations to offset API cost volatility from Rhine-Ruhr suppliers. For New Entrants and Emerging Players: Build out nanoparticle-bioadhesive hybrid capabilities targeting macromolecular therapies previously limited to injection, exploiting formulation scientist scarcity concentrated in Massachusetts and Basel academic clusters. Target home care channels for addiction treatment and hormone replacement products where prescriber relationship barriers are lowest. For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical parents divesting non-core addiction-treatment or pain management buccal portfolios; these assets carry underutilized regulatory dossiers and established prescriber networks. Monitor FDA bioequivalence guidance revisions for locally-acting products as the inflection signal determining generic substitution economics. Cross-checking against hospital procurement consortium contract award patterns is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Integrated CDMOs anchor large-scale film production for partners seeking FDA fast-track pathways. |
| Regulatory Approval Pathway | EMA MDR harmonization reduces multi-jurisdiction filing costs for drug-device combination products. |
| Backward Integration | Captive carbomer-polycarbophil blending insulates margins from German and Swiss excipient price volatility. |
| Pipeline Diversification | Nanoparticle-bioadhesive convergence opens macromolecular therapies previously limited to injection. |
| Hospital System Partnership | DEA vault-to-pharmacy distribution capabilities secure preferred vendor status in Veterans Affairs procurement. |
Study Parameters
A spread of perspectives from formulation scientists, regulatory affairs leads, hospital procurement managers, and specialty pharmaceutical executives converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and ISO 10993 biocompatibility testing protocols. Bottom-up capacity assessments for solvent-casting and lyophilization facilities triangulated against top-down demand modeling from oncology and pain management clinic expansion trends.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, end user, formulation technology, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating bioadhesive polymer science advancement rates and clinical validation timeline compression. Forecast inputs included FDA fast-track designation velocity and EMA MDR implementation pace.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Indian contract manufacturers or Swiss precision equipment suppliers would shift outcomes. Cross-checking against hospital procurement consortium contract award patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Manifolds Market
Medical Devices
Wireless Handheld Ultrasound Devices Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Global Medical Composite Market
Medical Devices
Ear Tube Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Artificial Cartilage Implant Market
Medical Devices
Asia-Pacific Viscosupplementation Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Arthroscopy Market