
 Global Brachytherapy Devices Market | 2026-2036
Global Brachytherapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Brachytherapy Devices Market Foresight
North American radiopharmaceutical suppliers is broadening isotope sourcing for sealed-source brachytherapy. Varian Medical Systems leverages integrated software-hardware ecosystems to anchor its position in remote afterloading. Elekta AB sustains technology leadership through dedicated R&D intensity in pulse-dose rate systems. Eckert & Ziegler dominates European isotope production for low-dose rate seeds, controlling a critical upstream node.
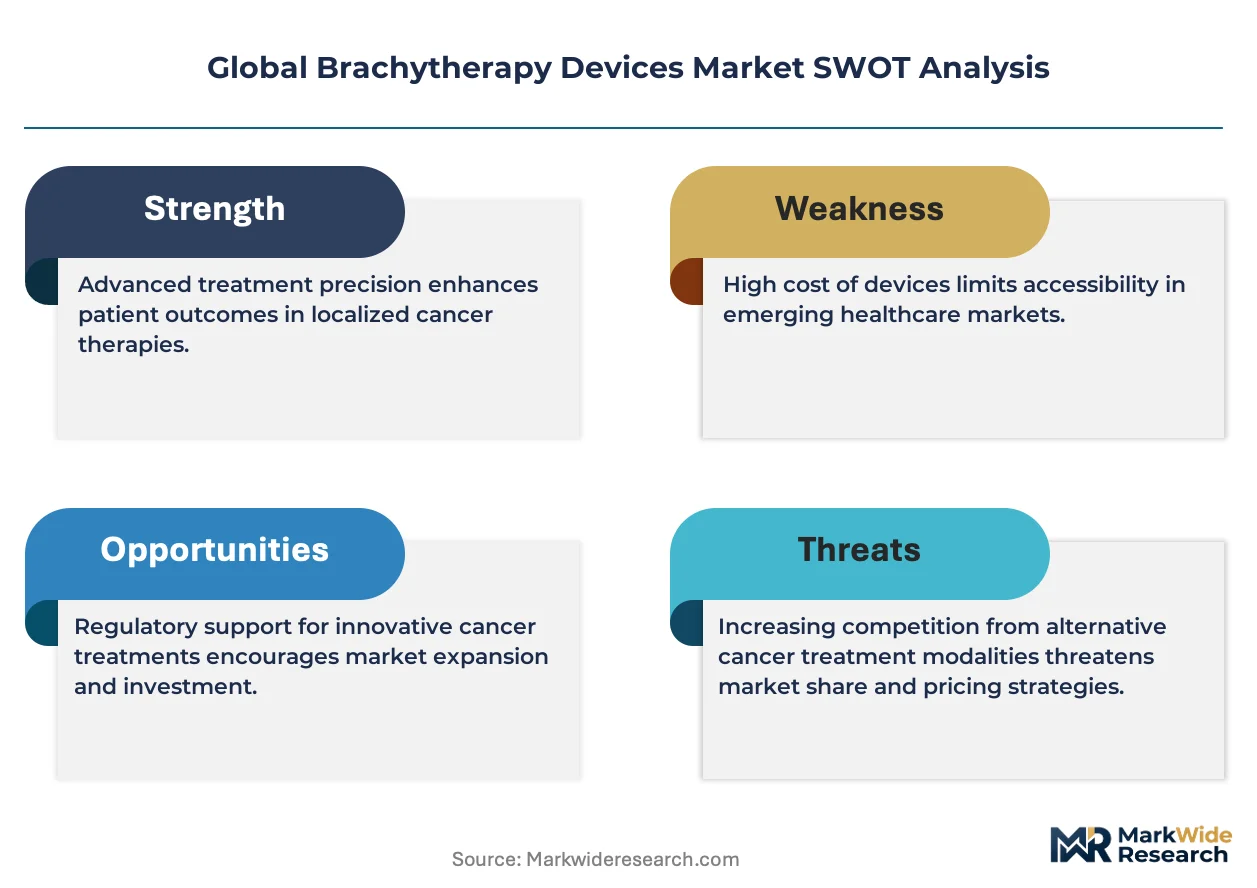
Brachytherapy devices deliver radioactive sources directly into or adjacent to tumor tissue using catheters, applicators, or implanted seeds, with dose rates typically measured in Grays per hour and source strengths calibrated to individual treatment plans. These systems enable conformal dose escalation to cancerous tissue while minimizing exposure to surrounding healthy organs. High-dose rate afterloaders command the largest installed base among product types due to shorter procedure times and outpatient compatibility. Imaging-guided brachytherapy represents the fastest-growing technology segment as clinicians integrate real-time MRI and CT feedback into treatment delivery. Prostate cancer applications generate the deepest margin pools, though gynecological tumor treatments are gaining protocol adoption in European cancer treatment centers.
FDA 510(k) pathways and EMA MDR conformity assessments shape device commercialization timelines, while ISO 13485 quality management standards govern manufacturing consistency across all major supply regions. NMPA registration requirements in China create a separate regulatory track that influences prioritization decisions for multinational device portfolios. Stakeholders must monitor isotope supply chain resilience and reimbursement code stability as dual determinants of regional expansion feasibility.
Market Dynamics
Imaging-guided afterloading systems are compressing treatment planning cycles from days to hours, forcing capital equipment refresh decisions across oncology departments in Germany, Japan, and the United States.
Growth Catalysts
- Reimbursement code stability:Centers for Medicare & Medicaid Services maintenance of dedicated brachytherapy procedure codes sustains hospital capital allocation toward afterloader installations.
- Japan's aging demographic:Prostate and gynecological cancer incidence rates among men over 70 and women over 65 expand eligible patient pools for curative-intent brachytherapy protocols.
- Pulse-dose rate optimization:Refined source stepping algorithms enable dose painting that matches tumor heterogeneity, elevating clinical confidence in complex anatomical sites.
Market Restraints
- Iridium-192 supply concentration:Production of high-dose rate source material clusters at fewer than six nuclear reactors worldwide, creating single-point vulnerability for afterloader-dependent centers.
- External beam substitution:Stereotactic body radiation therapy systems capture prostate cases previously routed to permanent seed implants, compressing low-dose rate procedure volumes.
- EMA MDR transition friction:Extended conformity assessment timelines for class IIb and III devices delay next-generation applicator launches in European cancer treatment centers.
Strategic Opportunities
- India's underserved tier-2 cities:Hyderabad, Ahmedabad, and Pune lack dedicated brachytherapy units despite rising cancer incidence, creating first-mover installation potential.
- MRI-linac convergence:Real-time magnetic resonance guidance during high-dose rate delivery enables adaptive gating that external beam systems cannot replicate.
- Japan METI medical device export incentives:Subsidized regulatory consulting accelerates PMDA-to-FDA parallel filing strategies for domestic afterloader manufacturers.
Industry Challenges
- Medical physicist scarcity:Treatment planning system operation and source calibration require board-certified specialists; training pipeline gaps in the United States and Germany extend staff recruitment cycles.
- Legacy afterloader integration:Hybrid workflows combining 1990s-installed remote afterloaders with contemporary imaging suites demand custom interface development that stretches IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Brachytherapy Devices Market |
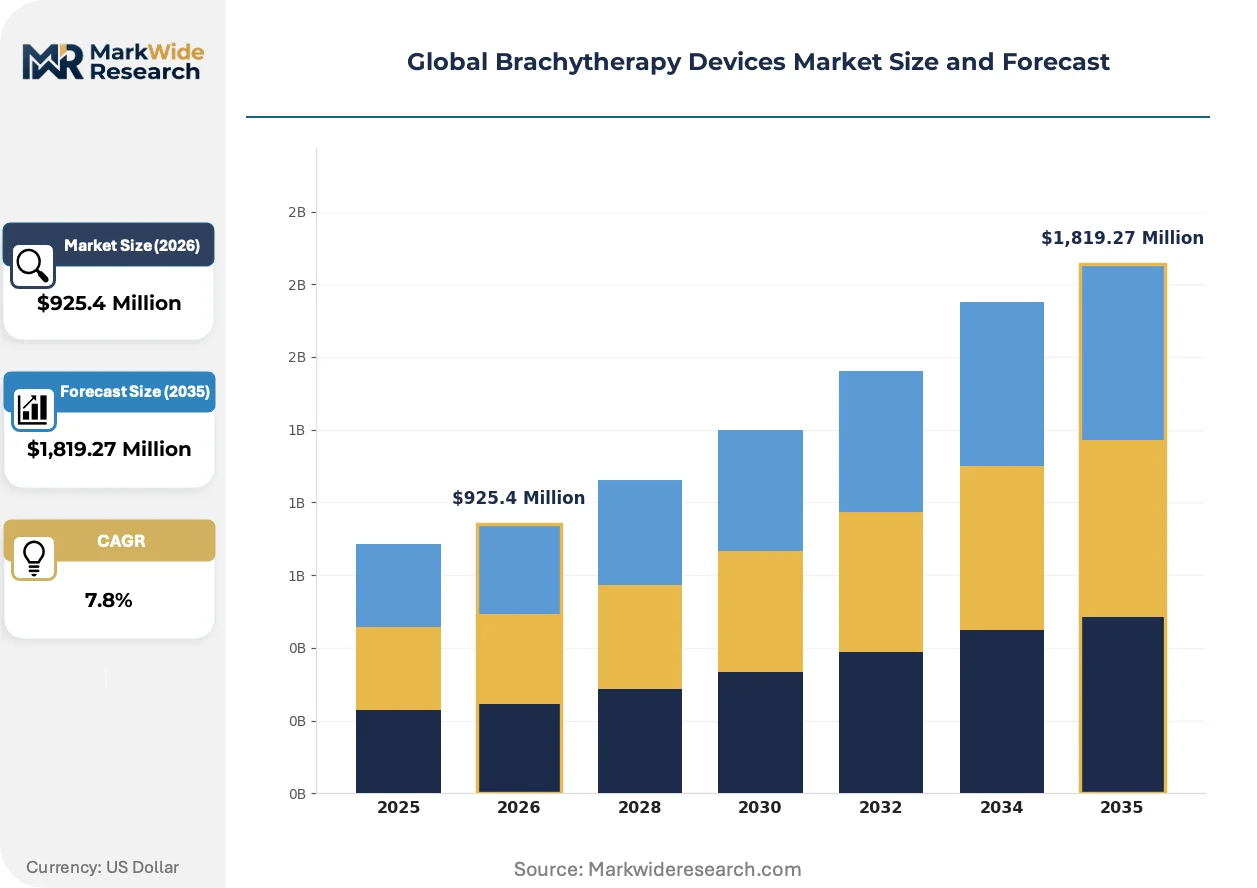
| Market Size in 2026 | $925.4 Million |
| Market Size in 2035 | $1,819.27 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Dose Rate Devices, Low-Dose Rate Devices, Pulse-Dose Rate Devices, Afterloaders Application: Prostate Cancer, Gynecological Tumors, Breast Cancer, Head & Neck Tumors End User: Cancer Treatment Centers, Radiation Oncology Clinics, Specialized Surgical Units, Research Institutes Technology: Remote Afterloading, Manual Afterloading, Imaging-Guided Brachytherapy, Electronic Brachytherapy |
| Companies Covered | Varian Medical Systems, Elekta AB, Eckert & Ziegler, Becton, Dickinson and Company, IsoRay, Theragenics Corporation, CIVCO Medical Solutions, Carl Zeiss, Ion Beam Applications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Brachytherapy Devices Market Shifts & Advancements
Automation of source positioning and real-time dosimetry verification is collapsing the latency between imaging acquisition and treatment delivery, compressing patient throughput timelines in high-volume centers.
Robotic catheter steering is automating needle insertion trajectories for interstitial prostate brachytherapy, reducing operator-dependent variability. Urology departments at academic medical centers in the United States are piloting these systems to standardize seed placement accuracy. This capability is automating the shift from freehand to image-registered implant techniques, raising the floor for community hospital program viability.
EMA MDR Article 10 technical documentation requirements are forcing manufacturers to commission extended clinical follow-up studies for predicate device equivalency claims. Smaller European applicator specialists face capital constraints for post-market surveillance infrastructure. High-dose rate afterloader segments with legacy 510(k) clearances are most affected, prompting portfolio rationalization toward MDR-ready platforms.
Service unbundling is separating afterloader hardware procurement from source supply and maintenance contracts. Hospital procurement departments in Germany and Japan are negotiating multi-vendor source agreements to decouple capital expenditure from recurring isotope costs. This pattern is most visible in prostate cancer service lines where procedure volume predictability enables consumption-based sourcing models.
Global Brachytherapy Devices Market Segmentation
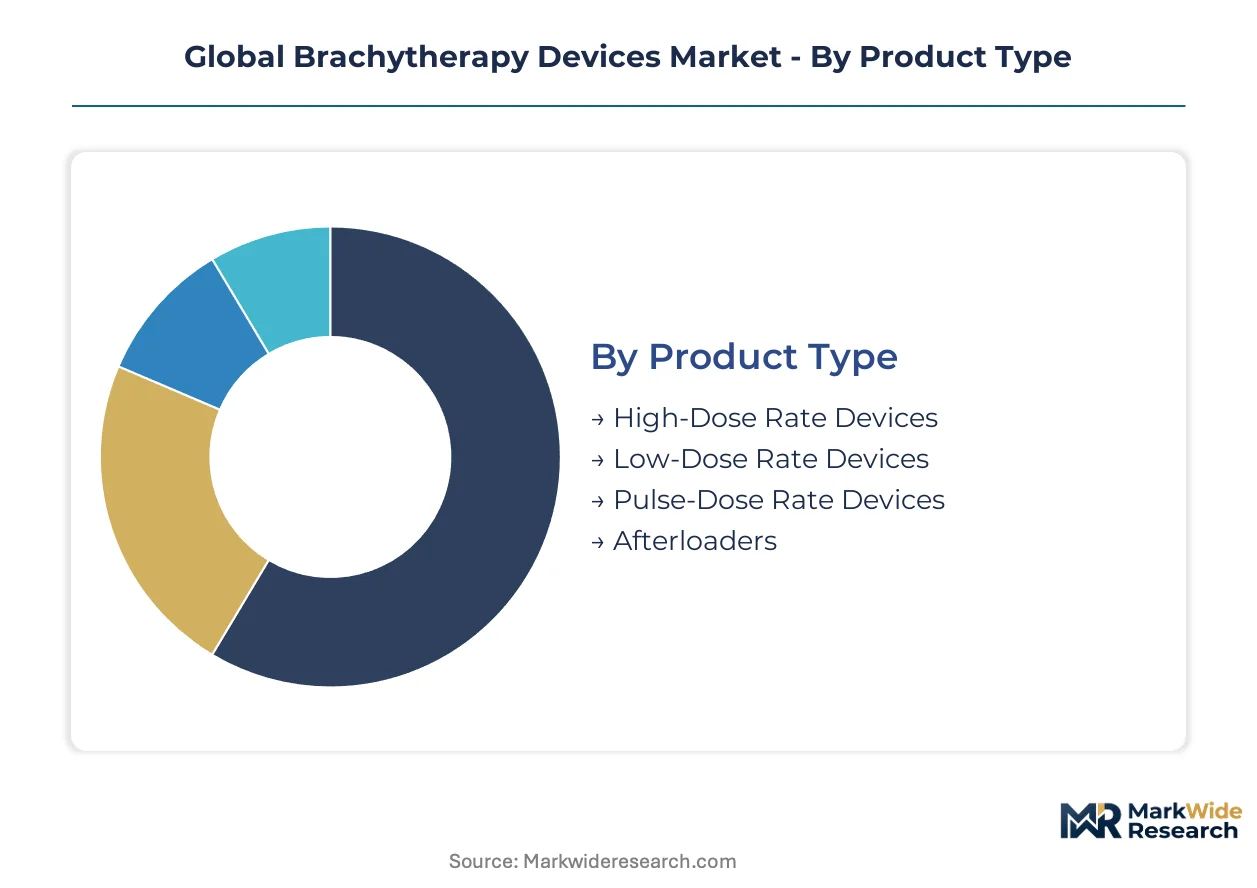
Segmentation in brachytherapy devices reveals distinct capital deployment patterns across hardware categories, clinical applications, and technology tiers. Each dimension carries implications for reimbursement coding, physicist staffing requirements, and facility infrastructure investments.
Product Type:
Capital-intensity varies sharply across product categories, with remote afterloader systems demanding multimillion-dollar infrastructure commitments while seed-based platforms require lower fixed investment but higher recurring isotope expenditure.
- High-Dose Rate Devices:These systems employ Iridium-192 sources delivered through remote afterloaders, enabling outpatient treatment completion in minutes rather than days. German and Japanese cancer treatment centers prioritize these installations for throughput efficiency, though reactor-dependent isotope supply chains constrain expansion in regions lacking radiopharmaceutical infrastructure.
- Low-Dose Rate Devices:Permanent seed implants using Iodine-125 or Palladium-103 deliver continuous radiation over weeks, suited for prostate cancer protocols with established reimbursement in the United States. Community urology practices in Texas and Florida favor this modality for its lower facility overhead compared to fractionated external beam alternatives.
- Pulse-Dose Rate Devices:Hybrid systems blending HDR precision with LDR biological effectiveness, gaining traction in European gynecological protocols where pulse algorithms optimize dose conformity.
- Afterloaders:The mechanical backbone of remote brachytherapy, encompassing source drive mechanisms, shielding assemblies, and treatment planning interfaces; hardware refresh cycles typically span 10-15 years.
High-Dose Rate Devices absorb the bulk of installed capacity; Imaging-Guided Brachytherapy (within Technology) is expanding most quickly.
Application:
Procedure volume distribution across cancer types determines service line prioritization for capital equipment procurement, with prostate and gynecological applications commanding distinct reimbursement and staffing models.
- Prostate Cancer:Dominant application by procedure count, encompassing both permanent seed implants and temporary high-dose rate boost protocols. United States urology departments maintain dedicated brachytherapy suites, while European centers increasingly favor HDR monotherapy for intermediate-risk patients to preserve erectile function outcomes.
- Gynecological Tumors:Cervical and endometrial cancers require intracavitary and interstitial applicator configurations, with pulse-dose rate optimization improving local control in locally advanced disease. French and Italian cancer treatment centers report rising utilization for elderly patients ineligible for radical surgery.
- Breast Cancer:Accelerated partial breast irradiation via interstitial or intracavitary delivery targets lumpectomy cavities, competing with intraoperative radiation therapy for selected early-stage cases.
- Head & Neck Tumors:Interstitial implants address recurrent disease in previously irradiated fields, requiring specialized expertise in airway management during source placement.
Prostate Cancer generates the deepest procedure volume pools; Gynecological Tumors is climbing the fastest as pulse-dose protocols gain protocol adoption.
End User:
Customer-type segmentation reflects divergent procurement authority structures, with hospital-based oncology departments operating under capital budget constraints distinct from independent clinic financing models.
- Cancer Treatment Centers:Integrated academic and community hospital systems with dedicated radiation oncology departments, controlling the majority of afterloader installations in Germany, Japan, and the United States. These facilities negotiate multi-source supply agreements and employ board-certified medical physicists for treatment planning.
- Radiation Oncology Clinics:Freestanding centers focused exclusively on radiation therapy delivery, prevalent in United States metropolitan markets where certificate-of-need regulations permit independent operation.
- Specialized Surgical Units:Gynecologic oncology and urology departments performing intraoperative or perioperative seed placement, often in hybrid operating suite configurations.
- Research Institutes:Academic medical centers conducting clinical trials for novel isotopes, applicator designs, and imaging integration protocols.
Cancer Treatment Centers command the dominant installed base; Radiation Oncology Clinics is gaining share fastest where regulatory frameworks permit independent facility development.
Technology:
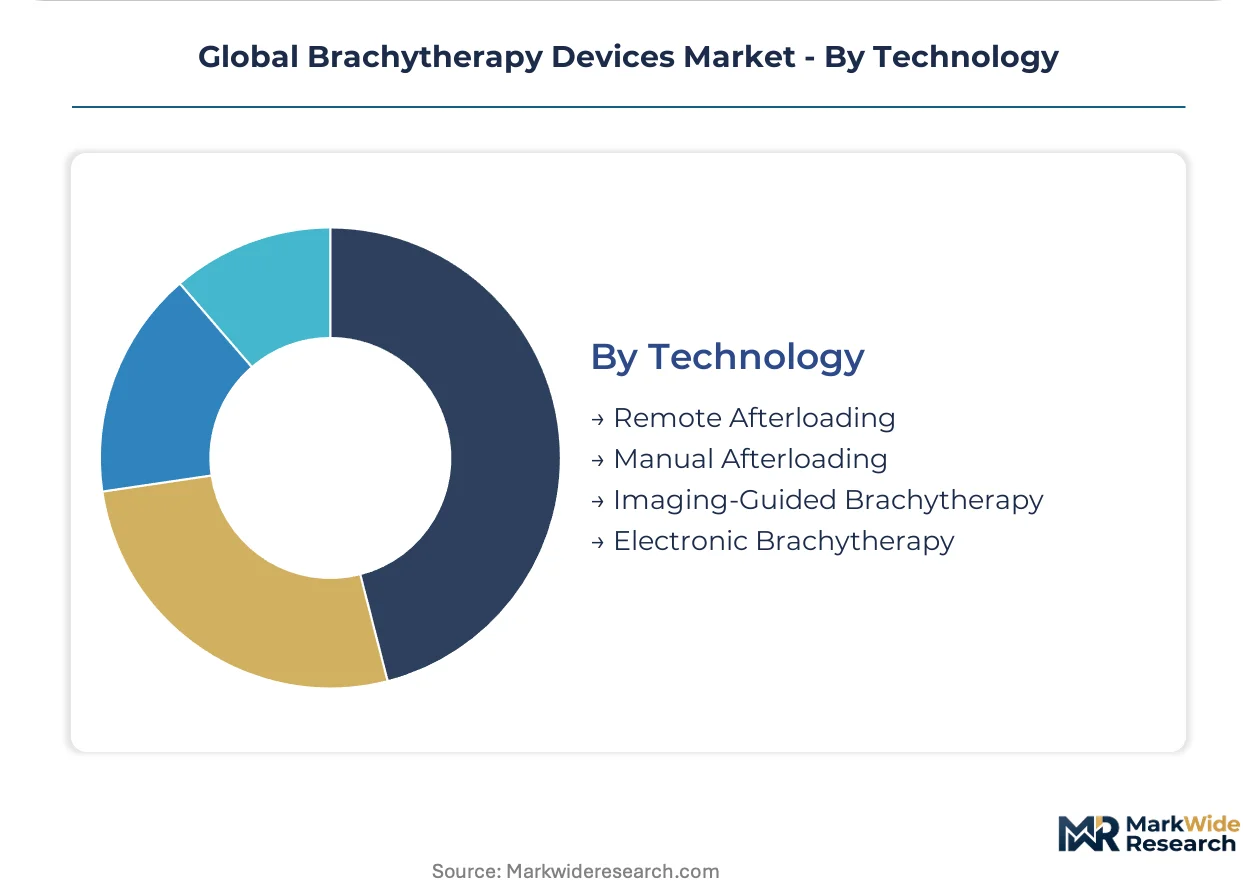
Technology tier differentiation centers on automation depth and imaging integration, with capital allocation decisions increasingly favoring real-time guidance capabilities over conventional source delivery mechanisms.
- Imaging-Guided Brachytherapy:MRI and CT-integrated delivery enables adaptive planning with tumor visualization during source positioning, collapsing treatment planning cycles from days to hours. United States academic medical centers in Boston and Houston pioneer these workflows for complex gynecological and prostate cases.
- Remote Afterloading:Automated source positioning eliminates staff radiation exposure, representing the standard-of-care for high-dose rate delivery in Japan and Western Europe.
- Manual Afterloading:Direct source handling by trained personnel persists in low-resource settings and specific LDR seed implant techniques, though declining as safety regulations tighten.
- Electronic Brachytherapy:X-ray-based surface and intraoperative delivery without radioactive isotopes, appealing to ambulatory surgery centers seeking to circumvent radiopharmaceutical supply chain dependencies.
Remote Afterloading retains the largest installed footprint; Imaging-Guided Brachytherapy is accelerating most rapidly as real-time MRI integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iridium-192 production clusters at fewer than six nuclear reactors worldwide, with Belgian, Dutch, and South African facilities supplying European and Asian afterloader networks.
United States
Prostate cancer incidence among men over 70 and stable CMS reimbursement codes sustain afterloader procurement at academic medical centers. FDA 510(k) pathways compress time-to-market for imaging-integrated systems. Texas and Florida urology practices favor permanent seed implants for lower facility overhead compared to fractionated alternatives.
Germany
Pulse-dose rate optimization for gynecological tumors elevates clinical confidence in complex anatomical sites. EMA MDR conformity assessments extend timelines for class IIb device launches. Bavarian cancer treatment centers report rising utilization of adaptive brachytherapy protocols for elderly patients ineligible for radical surgery.
Japan
Aging demographics expand eligible patient pools for curative-intent protocols among women over 65 with endometrial cancer. METI medical device export incentives subsidize PMDA-to-FDA parallel filing strategies. Tokyo and Osaka metropolitan areas concentrate the majority of high-dose rate installations.
India
Hyderabad, Ahmedabad, and Pune lack dedicated brachytherapy units despite rising cancer incidence, creating first-mover installation potential. CDSCO registration requirements create a separate regulatory track influencing multinational portfolio prioritization. Maharashtra and Gujarat radiation oncology departments negotiate multi-vendor source agreements to decouple capital expenditure from recurring isotope costs.
China
NMPA registration requirements for class III medical devices shape commercialization timelines distinct from FDA and EMA pathways. Yangtze River Delta cancer treatment centers pilot MRI-linac convergence for real-time magnetic resonance guidance. Shanghai and Beijing academic medical centers drive adoption of robotic catheter steering systems.
Global Brachytherapy Devices Market Competitive Landscape
Global majors compete with regional champions across integrated software-hardware ecosystems and isotope supply chains. The vendor base organizes around three tiers: full-platform radiation oncology conglomerates, specialized sealed-source producers, and regional applicator fabricators. Dominant competitive moves include strategic partnerships for imaging integration and backward integration into isotope production to secure supply chain resilience.
Within the full-platform tier, Varian Medical Systems and Elekta AB exemplify vertically integrated positioning spanning afterloader hardware, treatment planning software, and service networks. Eckert & Ziegler anchors the sealed-source specialist archetype with European production infrastructure for low-dose rate seeds. These three entities collectively represent the upstream-through-downstream spectrum that defines competitive positioning in imaging-guided delivery systems.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| Eckert & Ziegler |
| Becton, Dickinson and Company |
| IsoRay |
| Theragenics Corporation |
| CIVCO Medical Solutions |
| Carl Zeiss |
| Ion Beam Applications |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up applicator specialists in Germany and the United States enforce pricing discipline through bundled service contracts that tether hardware procurement to exclusive isotope supply agreements, compressing margin flexibility for hospitals seeking multi-vendor sourcing flexibility.
Pricing Analysis
Warranty and preventive maintenance bundling distinguishes premium afterloader contracts from unbundled capital-only transactions favored by cost-conscious community hospitals. Three-tier pricing structure across premium, standard, and economy levels reflects source activity calibration precision, software integration depth, and ISO 13485 certification tier. Pricing pressure stems from service unbundling trends in German and Japanese procurement departments negotiating consumption-based isotope sourcing. Community urology practices in Texas and Florida exhibit highest price sensitivity, while academic medical centers prioritize imaging integration over capital cost minimization.
Supply Chain Analysis
Freight costs for Iridium-192 source transport from Belgian and Dutch reactor facilities to Asian afterloader networks impose working capital burdens that favor regional radiopharmaceutical distributors with licensed logistics infrastructure. Production of high-dose rate source material clusters in Belgium, the Netherlands, and South Africa, drawing from uranium enrichment byproducts and specialized reactor irradiation cycles. The supply chain rests on single-source vulnerability for reactor-dependent isotope production, with fewer than six facilities worldwide supplying global afterloader networks. Distribution runs through authorized radiopharmaceutical distributors holding nuclear materials licenses in destination markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Imaging-guided brachytherapy systems are displacing conventional remote afterloading installations across major cancer treatment centers, compressing refresh cycles for legacy hardware installed during the 1990s and early 2000s.
For Market Incumbents: Extend software-hardware ecosystem lock-in by integrating real-time MRI guidance modules with existing afterloader installed bases, countering substitution threat from external beam stereotactic systems. Prioritize backward integration into sealed-source production through partnerships with European reactor operators, securing isotope supply resilience against single-point production failures. For New Entrants and Emerging Players: Enter via tier-2 Indian cities including Hyderabad, Ahmedabad, and Pune where dedicated brachytherapy unit penetration remains minimal despite rising prostate and gynecological cancer incidence. Target first-mover installation contracts with radiation oncology departments in Maharashtra and Gujarat, leveraging multi-vendor source supply agreements as differentiated procurement flexibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor European applicator specialists facing EMA MDR Article 10 compliance cost burdens in Germany and France, where extended clinical follow-up study requirements strain capital reserves. Monitor PMDA-to-FDA parallel filing completion rates among Japanese domestic manufacturers as inflection indicator for export-oriented platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS maintenance of dedicated brachytherapy procedure codes sustains hospital capital allocation toward afterloader installations. |
| CE Marking Pathway | EMA MDR conformity assessments for class IIb devices shape commercialization timelines for next-generation applicator launches. |
| Hospital System Partnership | Academic medical center alliances in Boston and Houston accelerate imaging-guided protocol adoption for complex gynecological cases. |
| Software Companion Development | Treatment planning system integration with real-time MRI feedback collapses planning cycles from days to hours. |
| FDA Submission | 510(k) pathways for imaging-integrated systems compress time-to-market for robotic catheter steering platforms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with radiation oncology department heads, medical physicists, hospital procurement managers, and GPO contracts specialists. FDA 510(k) databases, EMA MDR technical documentation, CMS Medicare reimbursement schedules, and nuclear regulatory commission source shipment records provided validation layers. Bottom-up procedure volume modeling across prostate, gynecological, breast, and head and neck cancer indications triangulated against top-down capital equipment shipment data.
Data-stream reconciliation across isotope production volumes, afterloader installation records, and procedure reimbursement claims generated consistent market sizing across the projection horizon. Segmentation dimensions modeled encompass product type, application, end user, and technology tier, with geographic regulatory cluster and reimbursement framework as cross-cutting variables. CAGRs derived from weighted average of historical capital expenditure patterns and protocol adoption curves, incorporating medical physicist staffing constraints and isotope supply chain resilience as industry-specific forecast inputs.
Revisions become necessary when reactor facility outages, reimbursement code restructuring, or MDR conformity assessment timeline extensions materialize beyond baseline assumptions. Forecasts reflect documented assumptions regarding isotope supply concentration and physicist training pipeline capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Ingestible Thermometers Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Global Suture Anchor Devices Market