
 Medical Devices Clinical Trials Market | 2026-2036
Medical Devices Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Devices Clinical Trials Market Insights
Bioresorbable polymers are replacing permanent metal alloys in coronary stent platforms, which is rebalancing cost structures across pivotal trial budgets. Medtronic leverages its integrated trial-services unit to compress study timelines for neuromodulation devices. Boston Scientific specializes in structural heart trials, anchoring its cardiovascular portfolio against interventional rivals.
Medical devices clinical trials constitute regulated investigations that evaluate safety and efficacy of instruments, diagnostic tools, surgical devices, and monitoring equipment through structured human-subject protocols governed by Good Clinical Practice standards, with primary purpose of generating premarket submission data for regulatory clearance and subsequent reimbursement coding. Imaging systems occupy the largest technology segment due to capital intensity and longitudinal follow-up requirements, while wearable devices represent the fastest-expanding category as remote patient monitoring protocols reduce site-visit burdens. Contract research organizations command significant margin pools by integrating site networks with regulatory consulting across Phase II and Phase III studies.
FDA's premarket approval and 510(k) pathways, alongside EMA's Medical Device Regulation and ISO 14155 clinical investigation standards, collectively elevate protocol design costs while compressing timelines for first-in-human through pivotal studies. These frameworks force sponsors to front-load quality management systems and statistical rigor, reshaping vendor selection criteria for contract research partners. Stakeholders must monitor evolving equivalence standards for breakthrough device designation as regulators tighten evidentiary thresholds for novel therapeutic indications.
Market Dynamics
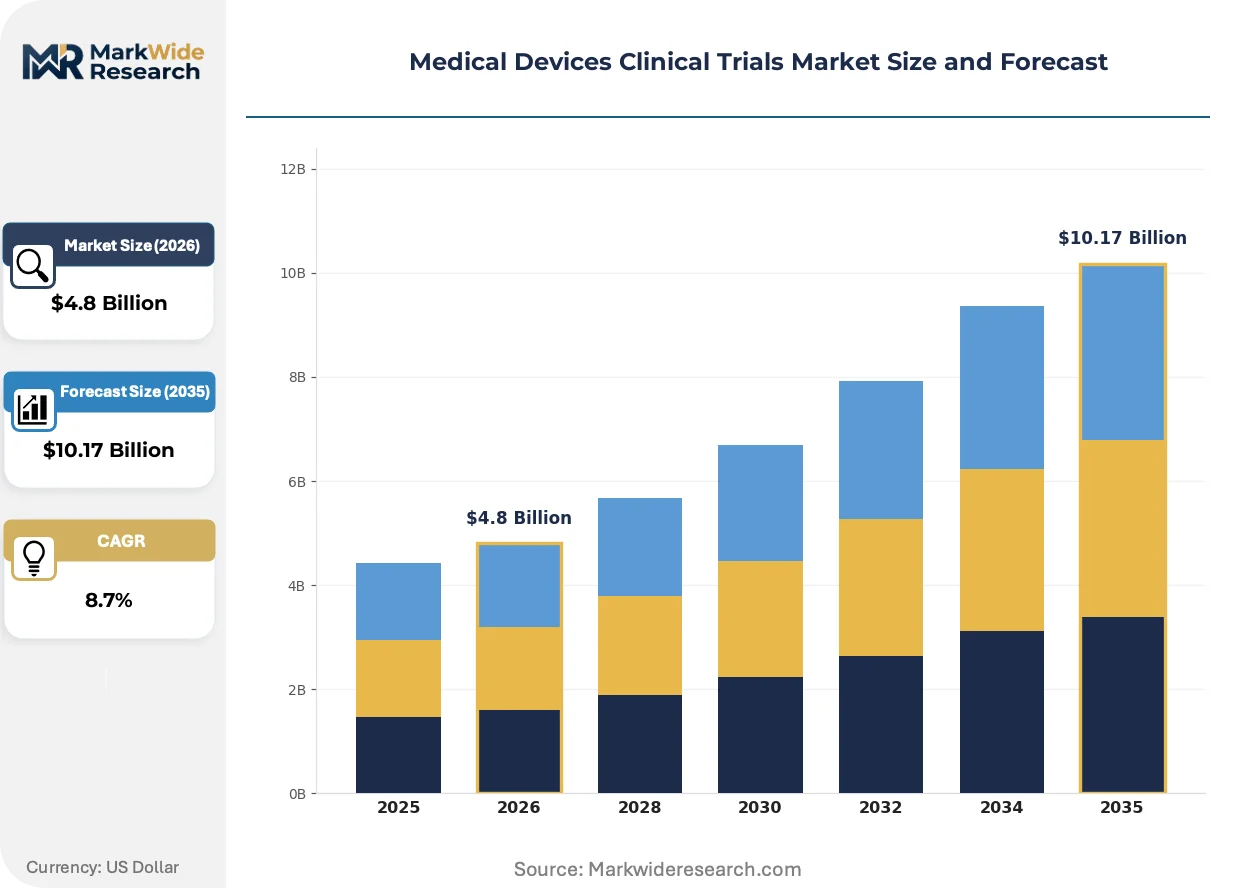
Decentralized trial platforms are compressing site activation timelines while FDA's premarket approval pathway revisions force sponsors to front-load quality management investments. This dual pressure is restructuring vendor selection criteria and trial budget allocation across cardiovascular and neuromodulation portfolios.
Growth Catalysts
- Decentralized Technologies:Remote patient monitoring protocols reduce site-visit burdens for wearable device trials, accelerating enrollment velocity across chronic disease indications.
- Asia-Pacific Regulatory Expansion:CDSCO streamlined medical device approval pathways in India, concentrating trial activity around Hyderabad and Bengaluru corridors.
- Bioresorbable Material Substitution:Polymers replacing permanent metal alloys in coronary stent platforms create new pivotal trial categories with differentiated endpoints.
Market Restraints
- Protocol Design Cost Escalation:ISO 14155 clinical investigation standards and EMA's Medical Device Regulation elevate documentation requirements, stretching sponsor budgets.
- Specialized Site Concentration:Imaging systems trials depend on capital-intensive longitudinal follow-up facilities concentrated in established metropolitan research clusters.
- Equivalence Standard Tightening:Regulators are elevating evidentiary thresholds for breakthrough device designation, extending time-to-submission for novel therapeutic indications.
Strategic Opportunities
- Underpenetrated South Asian Markets:India's medical device corridor offers untapped site network capacity for cardiovascular implant manufacturers expanding trial portfolios.
- Technology Convergence:Integration of artificial intelligence into imaging endpoint adjudication is unifying data collection and analysis workflows, reducing manual review overhead.
- Regulatory Tailwind:FDA's breakthrough device designation program creates accelerated review pathways for devices addressing unmet neurological and cardiovascular needs.
Industry Challenges
- Biostatistics Talent Scarcity:Complex adaptive trial designs for medical devices require specialized statistical expertise that outpaces current workforce supply.
- Legacy System Integration:Electronic data capture platforms must interface with hospital information systems that lack standardized interoperability protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Devices Clinical Trials Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Diagnostic Tools, Surgical Devices, Monitoring Equipment End User: Hospitals, Research Institutions, Clinics, Contract Research Organizations Technology: Robotic Surgery, Imaging Systems, Wearable Devices, Telemedicine Solutions Clinical Phase: Phase I, Phase II, Phase III, Post-Marketing Surveillance |
| Companies Covered | Abbott, Medtronic, Siemens Healthineers AG, Fresenius Medical Care AG, GE Healthcare, Koninklijke Philips N.V., Danaher Corporation, Boston Scientific Corporation, Baxter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Devices Clinical Trials Market Trends and Innovations
Clinical trial execution is pivoting from site-centric to patient-centric models, with technology platforms enabling remote participation and real-time data streams. This transformation is compressing traditional timelines while introducing new validation requirements for digital endpoints.
Synthetic control arms leveraging historical trial data are unifying comparator group construction with regulatory acceptance frameworks. Cardiovascular device sponsors are adopting these methodologies for rare indication trials where recruitment bottlenecks persist. The approach is unifying statistical rigor with ethical constraints on placebo exposure, reshaping budget allocation toward data infrastructure.
EMA's Medical Device Regulation implementation is forcing sponsors to restructure technical documentation and post-market surveillance systems. The framework mandates clinical evidence proportionate to device risk classification, elevating quality management system investments. High-risk implant manufacturers are responding by embedding regulatory strategists into protocol design teams earlier in development cycles.
Contract research organizations are unbundling traditional full-service models into modular offerings targeting specific trial phases. Sponsors now procure site activation, regulatory consulting, and data management as separate workstreams rather than integrated packages. This pattern is most visible in the United States, where mid-cap device companies prioritize vendor flexibility over relationship consolidation.
Medical Devices Clinical Trials Market Segmentation
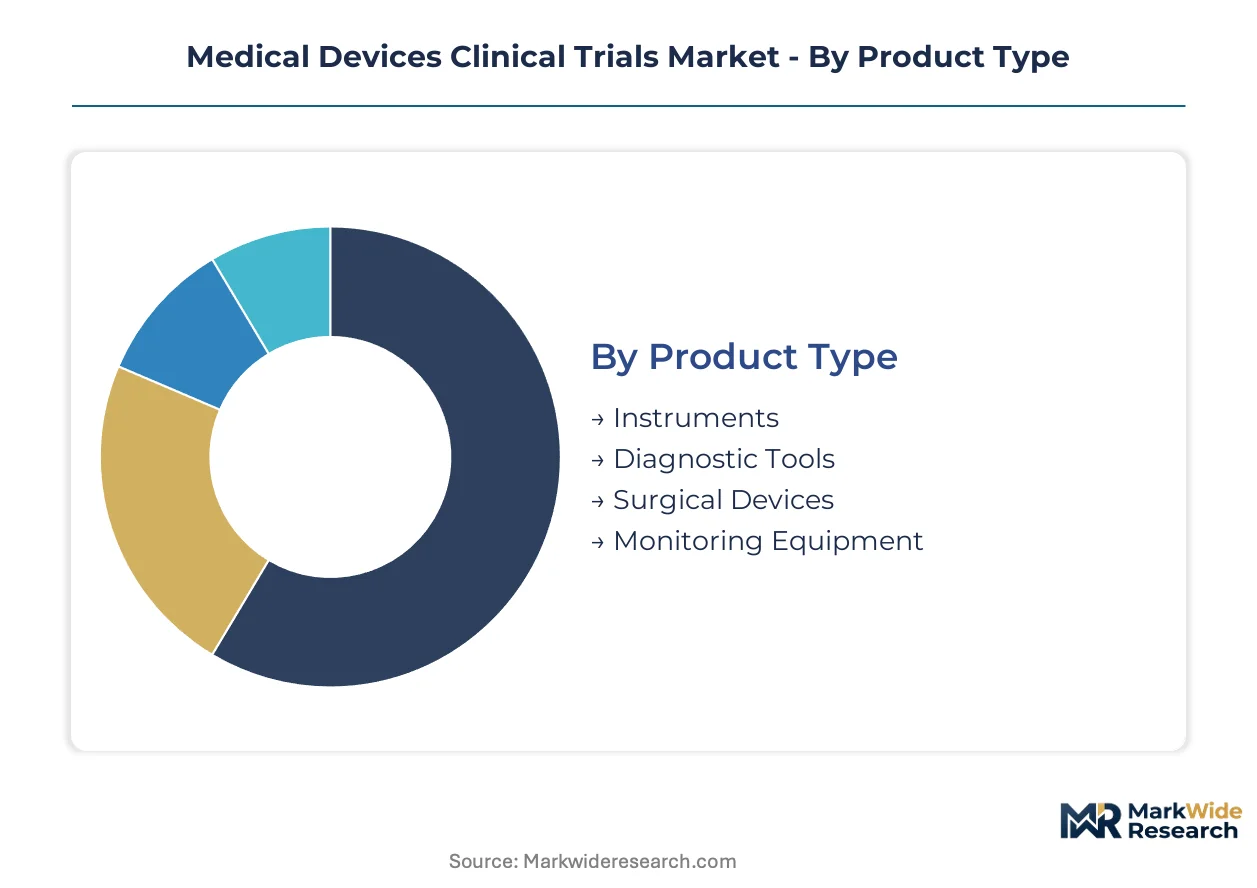
Segmentation in medical devices clinical trials reveals distinct capital requirements, regulatory pathways, and site infrastructure needs across product categories. Trial sponsors allocate budgets differentially based on longitudinal follow-up demands and endpoint adjudication complexity inherent to each segment.
Product Type:
Capital intensity varies sharply across device categories, with implantable systems demanding specialized surgical suites and extended safety monitoring compared to external instruments.
- Instruments:Handheld and powered surgical tools requiring biocompatibility validation and sterilization efficacy documentation. Demand concentrates in orthopedic and general surgery portfolios where FDA 510(k) pathways dominate, though equivalence standard tightening is extending documentation timelines.
- Diagnostic Tools:In vitro diagnostic platforms and point-of-care testing systems requiring analytical and clinical validation studies. Reimbursement coding pressures in the United States and Germany are forcing sponsors to front-load health economic evidence generation alongside safety data.
- Surgical Devices:Capital equipment including energy-based systems and minimally invasive platforms. Site activation depends on OR scheduling access and surgeon training certification programs.
- Monitoring Equipment:Patient monitoring systems for acute and ambulatory settings. Post-market surveillance obligations under EMA MDR are reshaping lifecycle management investments.
Most installed capacity flows through Diagnostic Tools. Expansion is steepest in Monitoring Equipment.
End User:
Site selection criteria diverge based on patient volume, regulatory inspection history, and existing quality management infrastructure.
- Hospitals:Academic medical centers and community hospital systems with established institutional review boards and clinical trial offices. India’s Hyderabad and Bengaluru corridors are attracting cardiovascular implant trials through CDSCO streamlined pathways and available principal investigator capacity.
- Research Institutions:Dedicated clinical research facilities and university-affiliated trial units. First-in-human studies concentrate here due to emergency response capabilities and intensive monitoring infrastructure.
- Clinics:Outpatient specialty practices and ambulatory surgery centers. Decentralized trial technologies are expanding site eligibility beyond traditional hospital networks.
- Contract Research Organizations:Full-service and niche CROs providing integrated site management, regulatory consulting, and biostatistics. Modular procurement patterns are unbundling traditional service packages into phase-specific engagements.
Hospital networks anchor current trial volume. CROs are gaining share fastest through sponsor outsourcing trends.
Technology:
Endpoint validation requirements and data infrastructure investments separate high-complexity from commoditized trial categories.
- Imaging Systems:MRI, CT, ultrasound, and nuclear medicine platforms requiring phantom studies, reader variability assessment, and longitudinal diagnostic accuracy trials. Capital intensity and specialized imaging core lab dependencies concentrate activity in established metropolitan research clusters.
- Wearable Devices:Continuous glucose monitors, cardiac event recorders, and activity trackers leveraging remote patient monitoring protocols. FDA breakthrough device designation applications are accelerating for neurological and cardiovascular indications where site-visit burden reduction proves clinically meaningful.
- Robotic Surgery:Computer-assisted surgical platforms requiring simulator validation and learning curve documentation. Proctoring requirements and device-specific training programs extend site activation timelines.
- Telemedicine Solutions:Remote diagnostic and therapeutic delivery systems. Digital endpoint validation frameworks remain underdeveloped, creating regulatory submission uncertainty.
Imaging Systems command the largest trial budgets. Wearable Devices are climbing the fastest on decentralized protocol adoption.
Clinical Phase:
Regulatory risk and statistical complexity escalate through the development lifecycle, reshaping vendor selection and quality system investments.
- Phase I:First-in-human and early feasibility studies assessing initial safety profiles. Research institutions with emergency response capabilities dominate site selection.
- Phase II:Pilot efficacy studies with refined endpoints and expanded enrollment. CROs capture significant margin pools through integrated site network and regulatory consulting bundles.
- Phase III:Pivotal trials generating premarket submission datasets. ISO 14155 compliance and statistical rigor requirements force sponsors to front-load quality management investments.
- Post-Marketing Surveillance:Registry studies and mandated follow-up under EMA MDR and FDA conditions of approval. Real-world evidence generation is reshaping budget allocation toward data infrastructure.
Phase III studies absorb the largest absolute spending. Post-Marketing Surveillance is expanding most quickly on regulatory mandate intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad and Bengaluru anchor trial activity concentration as cardiovascular implant manufacturers expand Asia-Pacific regulatory portfolios. The United States retains pivotal trial volume leadership through FDA premarket approval pathway dominance. European site networks absorb MDR compliance investments while India captures decentralized protocol migration.
United States
FDA premarket approval pathway revisions and breakthrough device designation programs accelerate neuromodulation and structural heart trial timelines. Academic medical centers in Boston, Minneapolis, and Irvine concentrate Phase III cardiovascular studies. Medtronic and Boston Scientific leverage integrated trial-services capabilities to compress site activation schedules.
Germany
EMA Medical Device Regulation implementation elevates technical documentation and post-market surveillance investments for high-risk implant manufacturers. ISO 14155 clinical investigation standards reshape quality management system procurement across Bavaria and Baden-Württemberg research clusters. Siemens Healthineers anchors imaging systems trial infrastructure from Erlangen.
India
CDSCO streamlined approval pathways concentrate cardiovascular implant trials around Hyderabad and Bengaluru medical device corridors. Remote patient monitoring protocol adoption accelerates wearable device enrollment velocity across chronic disease indications. Contract research organizations expand site network capacity to capture sponsor outsourcing from Western markets.
Japan
PMDA regulatory harmonization efforts with FDA and EMA reduce duplicate clinical evidence generation for multinational sponsors. Tokyo and Osaka metropolitan research clusters concentrate imaging systems and robotic surgery trials requiring longitudinal follow-up facilities. METI medical device innovation programs support first-in-human study infrastructure.
Switzerland
Swissmedic alignment with EMA MDR frameworks positions Basel and Zurich as high-value sites for European pivotal studies. Precision manufacturing heritage supports orthopedic and cardiovascular implant trial execution with specialized surgical suite requirements. Roche and Novartis affiliate networks provide investigator access across contiguous EU markets.
Medical Devices Clinical Trials Market Competitive Landscape
Global majors compete with regional champions across site network coverage and regulatory consulting depth. The vendor base separates into three tiers: integrated full-service CROs, device-specialized mid-caps, and modular boutique providers. Consolidation pressure concentrates among mid-cap players seeking geographic scale. Dominant competitive moves include strategic partnerships with academic medical centers and technology licensing for decentralized trial platforms.
Within the integrated device manufacturer tier, Medtronic and Boston Scientific exemplify vertical trial-services capabilities that compress study timelines. Abbott occupies a position bridging diagnostic and interventional portfolios across cardiovascular and neuromodulation indications. Siemens Healthineers anchors imaging systems trial infrastructure through specialized core lab dependencies. These three entities represent distinct archetypes: full-service integration, therapeutic specialization, and capital equipment concentration.
| Leading Market Players |
|---|
| Abbott |
| Medtronic |
| Siemens Healthineers AG |
| Fresenius Medical Care AG |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Danaher Corporation |
| Boston Scientific Corporation |
| Baxter |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up contract research organizations have consolidated site networks across the United States and Western Europe, concentrating vendor bargaining power while compressing sponsor procurement flexibility. This ownership pattern tightens pricing discipline for Phase III cardiovascular and neuromodulation trials as sponsors face fewer alternative providers for integrated regulatory consulting bundles.
Pricing Analysis
Input-cost pass-through from biostatistics talent scarcity and ISO 14155 compliance investments is intensifying project-based pricing pressure across pivotal trial tiers. Three-tier pricing structure across premium, standard, and economy levels separates full-service CROs with embedded regulatory strategists from modular boutiques and offshore site management providers. Certification level differentiation—FDA breakthrough device designation support versus standard 510(k) pathway execution—commands tier premiums. Pricing pressure stems from sponsor procurement teams unbundling traditional service packages into phase-specific engagements. Mid-cap device companies in the United States exhibit highest price sensitivity, while multinational cardiovascular implant manufacturers prioritize timeline compression over unit cost.
Supply Chain Analysis
Direct-to-sponsor channels handle enterprise trial demand while subcontractor networks feed modular procurement patterns. Clinical site infrastructure concentrates in the United States, Germany, and India, with Hyderabad and Bengaluru corridors capturing decentralized protocol migration. Raw material dependencies include bioresorbable polymer feedstocks, imaging phantom manufacturing, and specialized surgical suite equipment. Single-source vulnerability runs through centralized imaging core labs for longitudinal diagnostic accuracy trials. Distribution runs through CRO-managed site activation pipelines rather than direct hospital contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medical devices clinical trials rests on sponsor procurement shifts toward outcome-based engagement models and premium-tier regulatory consulting. Bioresorbable material substitution and decentralized technology adoption are compressing site-visit burdens while elevating data infrastructure investments.
For Market Incumbents: Anchor cardiovascular trial portfolios through backward integration into site network ownership, particularly across India's CDSCO-streamlined corridors. Consolidate regulatory consulting capabilities to defend against modular boutique entrants unbundling Phase II and III services. Capacity addition in Hyderabad and Bengaluru captures sponsor outsourcing from Western markets facing EMA MDR compliance cost escalation. For New Entrants and Emerging Players: AI-enabled imaging endpoint adjudication platforms offer a technology-first wedge into the highest-margin trial phase. Target post-marketing surveillance registries under EMA MDR mandates, where incumbent CROs lack specialized real-world evidence infrastructure. Go-to-market through modular data management contracts rather than full-service site activation bundles. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap device-specialized CROs with concentrated Asia-Pacific site networks. Long-term viability favors targets integrating decentralized trial platforms with existing regulatory consulting depth. Watch FDA breakthrough device designation application velocity as inflection indicator for neuromodulation and structural heart trial demand.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pathway | Accelerates premarket review timelines for cardiovascular and neurological indications addressing unmet clinical need. |
| CDSCO Regulatory Harmonization Investment | Positions Indian site networks to capture sponsor trial migration from EMA MDR compliance cost centers. |
| Decentralized Trial Platform Integration | Unifies remote patient monitoring protocols with electronic data capture for wearable device enrollment velocity. |
| Bioresorbable Polymer Supply Agreement | Secures coronary stent platform feedstocks for next-generation pivotal trial categories with differentiated endpoints. |
| Hospital System Partnership Expansion | Locks in OR scheduling access and principal investigator capacity for robotic surgery and structural heart trials. |
Research Methodology
Coverage spans the United States, Germany, India, Japan, and Switzerland, with primary inputs from each regional cluster. The analysis combines structured interviews with clinical trial operations directors, regulatory affairs leads at cardiovascular implant manufacturers, hospital purchasing committee members, and CRO procurement executives. Secondary validation draws from FDA PMA and 510(k) filings, CDSCO approval pathway documentation, ClinicalTrials.gov registry data, and EMA MDR technical documentation requirements. Bottom-up site capacity modeling and top-down sponsor spending triangulation anchor demand estimation.
Rate-of-change decomposition separates volume effects from value migration across the projection horizon. The analytical framework models segmentation across product type, end user, technology, and clinical phase dimensions, with additional granularity in regulatory pathway clustering. CAGRs derive from sponsor budget allocation surveys and site activation timeline compression trends. Forecast inputs include decentralized technology adoption curves and CDSCO approval pathway efficiency metrics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA equivalence standard tightening and EMA MDR enforcement intensity. Forecasts reflect assumptions regarding sponsor outsourcing propensity and Asia-Pacific regulatory harmonization velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
PET Injectors Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
India Diabetes Devices Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Critical Care Devices Market
Medical Devices
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Netherlands Aesthetic Devices Market