
 Japan Contraceptive Devices Market | 2026-2036
Japan Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Contraceptive Devices Market Foresight
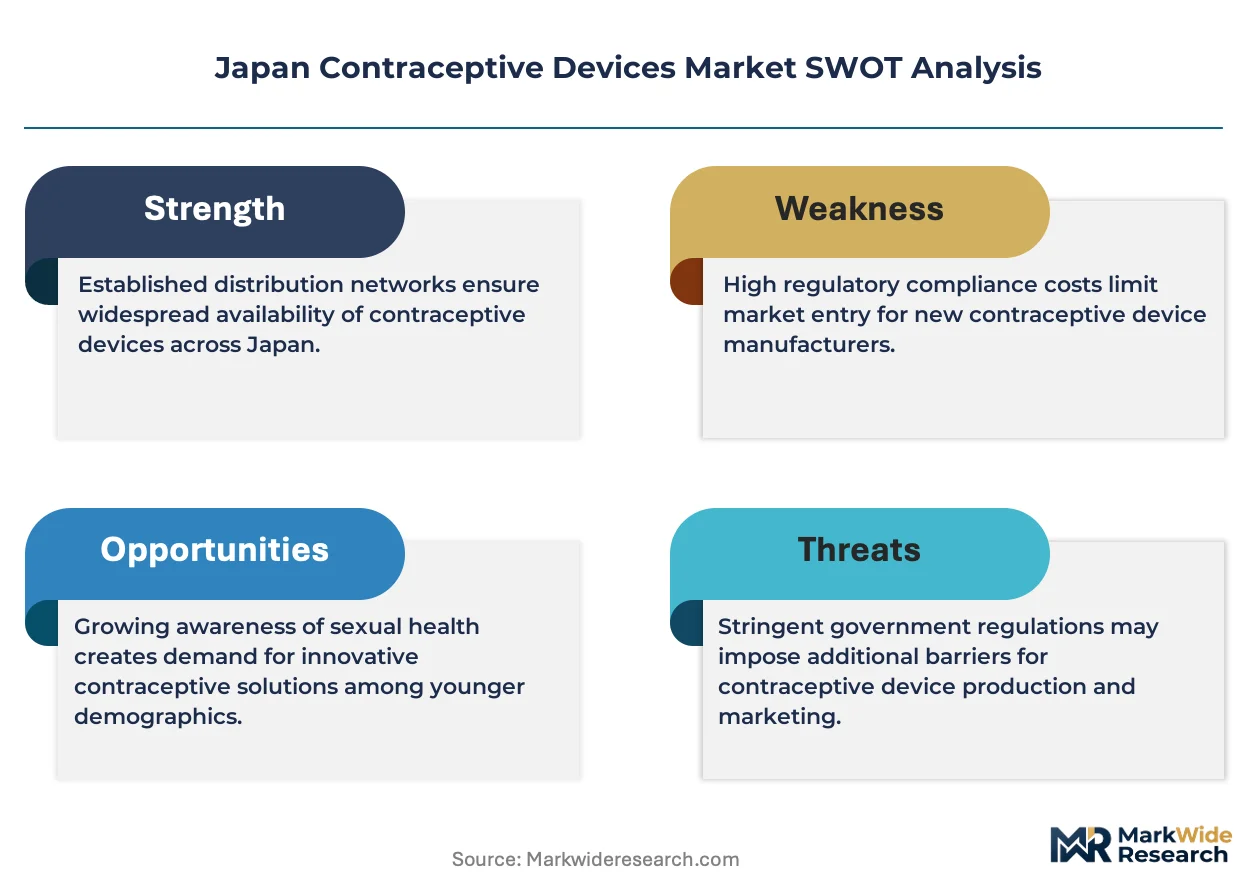
Japan's Pharmaceutical and Medical Device Act is broadening the cost-of-entry calculus for contraceptive device manufacturers seeking market authorization. Okamoto Industries leverages its domestic manufacturing scale to sustain competitive positioning in condom production. Bayer AG anchors its presence through specialized hormonal intrauterine device portfolios tailored to Japanese clinical preferences. Cooper Surgical Inc. differentiates via advanced intrauterine device designs that navigate stringent domestic quality benchmarks.
Contraceptive devices encompass physical and pharmaceutical barriers, intrauterine systems, and subdermal implants engineered from medical-grade silicone, copper alloys, or synthetic hormones to prevent conception through spermicidal, ovulatory suppression, or implantation-inhibition mechanisms. These products serve clinical and consumer channels requiring sterile, biocompatible construction validated to ISO 10993 standards. Condoms occupy the largest volume position across product type segments, while intrauterine devices command premium margin pools due to extended duration of efficacy and higher clinical involvement. Online retail distribution channels are expanding fastest among distribution channel segments, though drugstores retain dominant foot traffic for emergency contraception purchases.
PMDA oversight governs premarket approval pathways, while METI coordinates industrial standards for domestic manufacturing compliance. Japan's national health insurance reimbursement framework shapes patient out-of-pocket costs and provider device selection patterns. Stakeholders must monitor evolving MHLW contraception coverage policies and shifting consumer channel preferences to align portfolio investments with structural demand trajectories.
Market Dynamics
Japan's Ministry of Health, Labour and Welfare reimbursement recalibration is compressing provider margins while accelerating patient cost-sharing burdens, forcing device manufacturers to rebalance premium positioning against volume accessibility in metropolitan clinical networks.
Growth Catalysts
- Reimbursement guideline modernization:MHLW updated intrauterine device coverage criteria, expanding eligible patient pools and reducing out-of-pocket barriers for long-acting reversible contraceptives in Tokyo and Osaka prefectures.
- Copper alloy innovation:Advanced copper intrauterine device formulations with extended efficacy duration are capturing clinical preference over traditional barrier methods among gynecological specialists.
- Metropolitan demand concentration:Young adult populations aged 20-34 in Tokyo, Osaka, and Yokohama are driving replacement cycles for disposable barrier products through higher clinical consultation rates.
Market Restraints
- Domestic manufacturing concentration:Medical-grade silicone supply chains cluster in Kansai region facilities, creating vulnerability to localized production disruptions or material qualification delays.
- PMDA approval timeline friction:Pharmaceutical and Medical Device Act premarket pathways extend commercialization cycles for novel hormonal delivery systems, compressing effective patent windows.
- Copper price volatility:Intrauterine device producers face margin pressure from fluctuating copper alloy input costs, particularly affecting copper-dominant product portfolios.
Strategic Opportunities
- Hokkaido and Kyushu underpenetration:Regional prefectures outside major metropolitan corridors present whitespace for clinic network expansion and telehealth-enabled prescription services.
- Online pharmacy channel emergence:E-commerce platforms with pharmacist consultation integration are capturing emergency contraception demand previously routed through physical drugstore networks.
- Subdermal implant technology convergence:Combination of biodegradable polymer matrices with localized hormone release mechanisms offers pathway to differentiate from incumbent intrauterine systems.
Industry Challenges
- ISO 10993 biocompatibility certification complexity:Extended toxicological testing timelines for novel silicone formulations delay product launches and strain regulatory affairs staffing.
- Legacy clinic inventory system integration:Long-acting device implantation workflows require reconfiguration of hospital information systems and supply chain management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Contraceptive Devices Market |
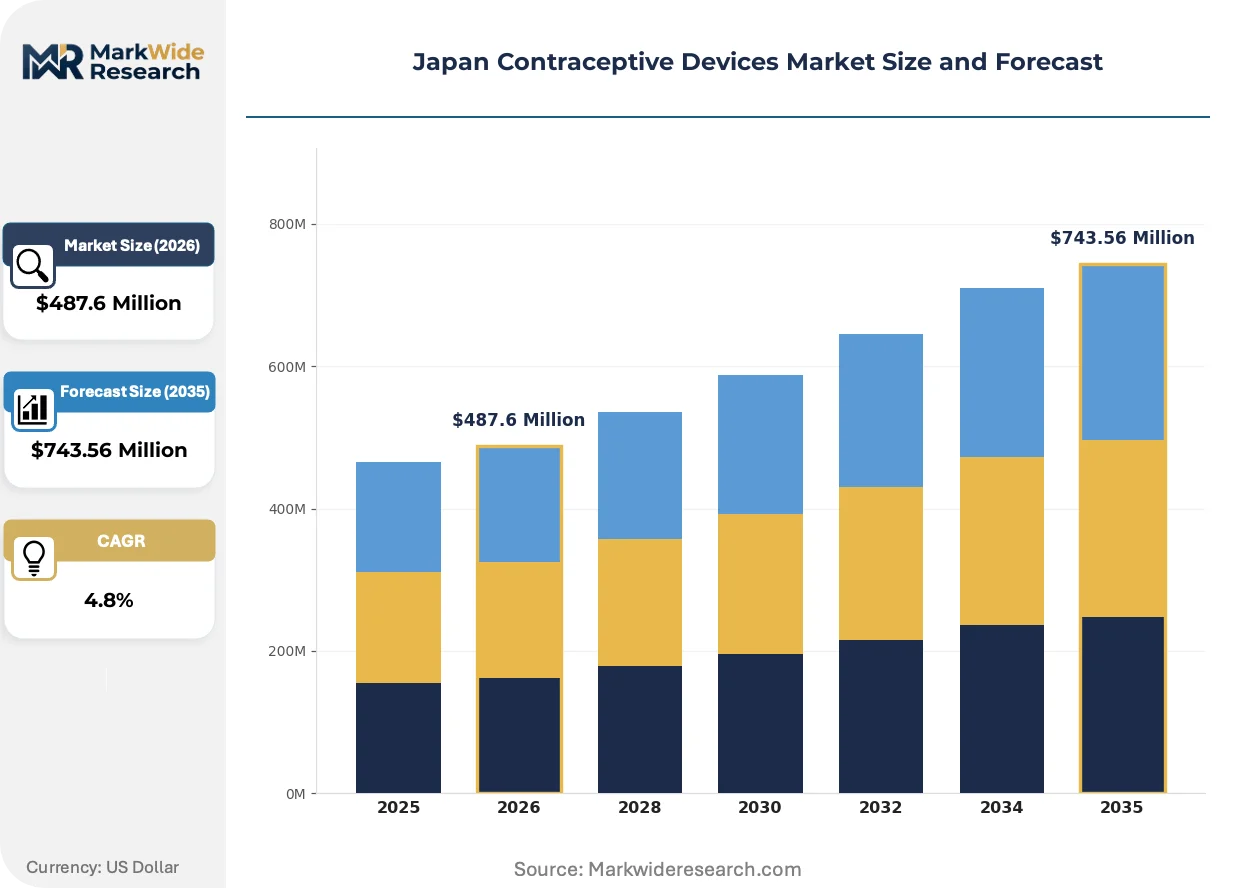
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condoms, Intrauterine Devices, Contraceptive Implants, Diaphragms End User: Individuals, Hospitals, Clinics, Pharmacies Distribution Channel: Online Retail, Specialty Stores, Drugstores, Supermarkets Age Group: Teens, Young Adults, Adults, Elderly |
| Companies Covered | Okamoto Industries, Cooper Surgical Inc., Bayer AG, Merck & Co., Inc, Abbvie Inc, Reckitt Benckiser, Pfizer Inc., Teva Pharmaceutical Industries Ltd, Fujifilm Healthcare Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Contraceptive Devices Market Shifts & Advancements
Digital health infrastructure and materials science advances are converging to reshape patient access pathways and product differentiation in Japan's contraceptive device sector.
Hormonal intrauterine systems with localized progesterone release mechanisms are overtaking traditional copper-based alternatives in gynecological practice preference. Women's health clinics in Tokyo and Osaka are adopting these devices at accelerated rates for patients seeking menstrual symptom management alongside contraception. This technology is overtaking legacy copper portfolios by commanding premium reimbursement positioning and extending patient retention within clinical networks.
METI coordination of industrial standards for medical device manufacturing is tightening domestic production compliance requirements. The Ministry of Economy, Trade and Industry's updated quality benchmarks are forcing manufacturers to revalidate existing product lines against revised JIS specifications. Hormonal device producers with established domestic manufacturing footprints are responding fastest to these certification transitions.
Direct-to-consumer telehealth platforms with integrated pharmacist consultation are fragmenting traditional clinic-dependent prescription pathways. Young adult patients in metropolitan prefectures are bypassing in-person consultations for initial barrier method purchases, though long-acting device insertion still requires clinical infrastructure. This channel rotation is most pronounced in Tokyo and Osaka, where smartphone penetration and digital health literacy rates exceed national averages.
Japan Contraceptive Devices Market Segmentation
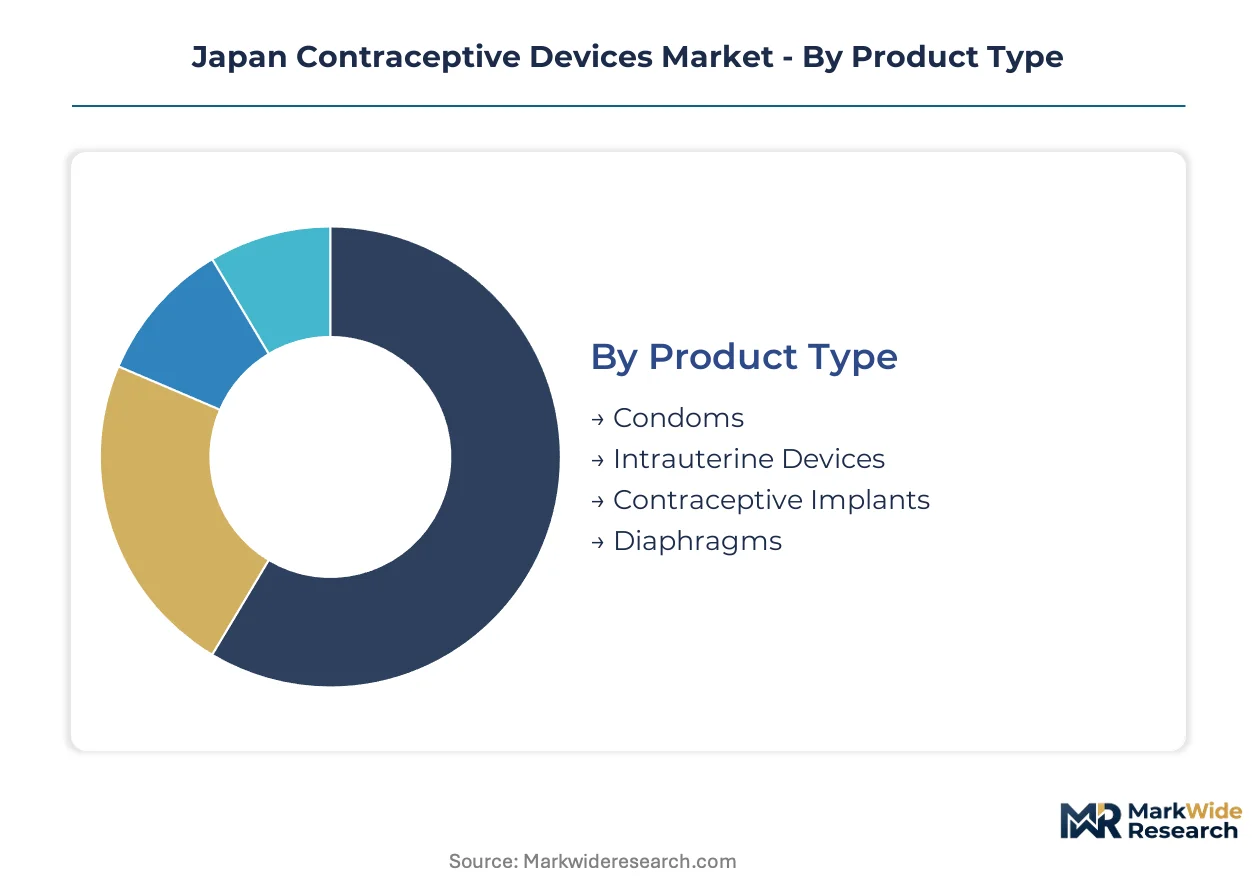
Japan's contraceptive device market fragments across four distinct axes that shape procurement patterns and reimbursement pathways. Product type determines clinical involvement depth and pricing tiers, while distribution channel preferences diverge sharply between emergency and planned contraception use cases.
Product Type:
Material composition and duration of efficacy separate segments across clinical and consumer channels.
- Condoms:Latex and polyurethane barrier products dominate volume throughput across Tokyo and Osaka retail networks. Polyisoprene variants are gaining traction among latex-sensitive users in metropolitan prefectures, with Okamoto Industries leveraging domestic manufacturing scale to maintain shelf presence.
- Intrauterine Devices:Copper alloy and hormonal delivery systems command premium positioning through extended efficacy duration and higher clinical reimbursement rates. MHLW updated coverage criteria are expanding eligible patient pools for these long-acting reversible contraceptives in women's health clinics.
- Contraceptive Implants:Subdermal progesterone-releasing rods require specialized insertion training and carry PMDA approval timeline friction for novel formulations.
- Diaphragms:Silicone cervical barriers occupy niche positioning with limited domestic manufacturing capacity and minimal reimbursement coverage.
Condoms lead on scale; intrauterine devices lead on momentum through reimbursement expansion and clinical preference shifts.
End User:
Procurement authority and prescription requirements create distinct access pathways across the patient journey.
- Individuals:Direct purchases concentrate in Tokyo and Osaka drugstore and online channels for barrier methods, with telehealth platforms fragmenting traditional clinic-dependent pathways for initial consultations.
- Hospitals:Academic medical centers in metropolitan prefectures anchor insertion volumes for long-acting devices, requiring reconfiguration of hospital information systems to manage implantation workflows.
- Clinics:Women's health clinics in Tokyo and Osaka are expanding access to intrauterine systems and capturing replacement cycles through specialized gynecological services.
- Pharmacies:Community drugstores retain dominant foot traffic for emergency contraception, though online pharmacy channel emergence is capturing demand previously routed through physical networks.
Individuals drive volume accessibility; clinics capture margin expansion through device insertion services.
Distribution Channel:
Channel selection correlates with urgency of need and required clinical consultation depth.
- Online Retail:E-commerce platforms with pharmacist consultation integration are climbing the fastest among all channels, particularly for barrier method replenishment and emergency contraception in smartphone-dense metropolitan prefectures.
- Specialty Stores:Dedicated family planning retailers maintain curated assortments with higher service intensity, concentrated in Tokyo and Osaka urban cores.
- Drugstores:Matsumoto Kiyoshi and other major chains sustain dominant foot traffic for over-the-counter barrier purchases and emergency hormonal products.
- Supermarkets:Mass merchandisers carry limited SKUs focused on value-tier condom assortments with minimal clinical consultation integration.
Drugstores anchor current volume; online retail shows steepest expansion trajectory through telehealth integration.
Age Group:
Life stage determines method preference, clinical engagement frequency, and reimbursement eligibility.
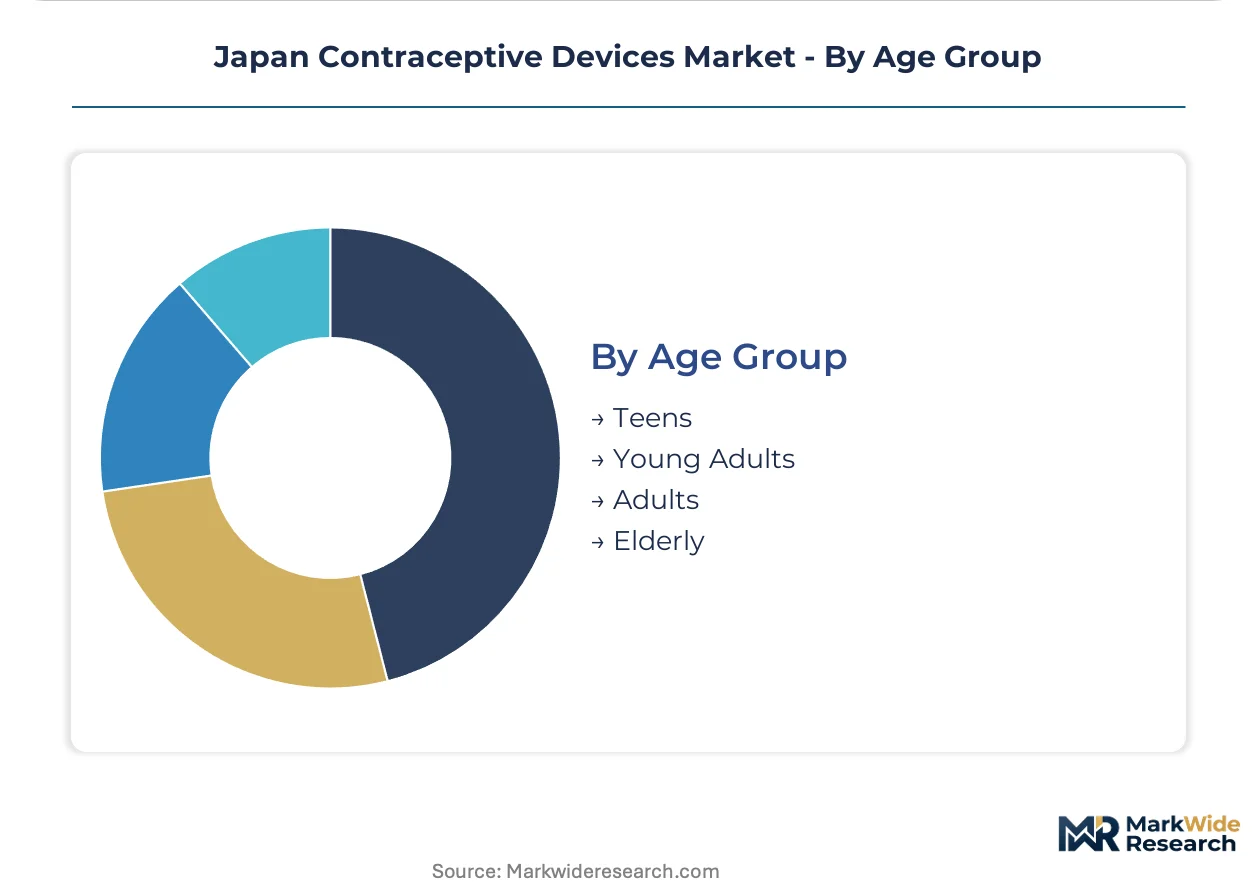
- Young Adults:The 20-34 demographic drives replacement cycles for disposable barrier products and initiates long-acting device adoption through higher consultation rates in metropolitan clinics.
- Adults:The 35-49 segment sustains intrauterine device retention and explores permanent solutions, with demand concentrating in prefectures with established women's health infrastructure.
- Teens:Access restrictions and consent requirements limit direct procurement, with demand channeled through parental involvement or clinic referrals in Tokyo and Osaka.
- Elderly:Post-reproductive health maintenance drives minimal device demand, with occasional diagnostic device use for menstrual disorder management.
Young adults concentrate near-term demand; adults sustain premium method retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized gynecological practitioners cluster in Tokyo and Osaka, anchoring Japan's contraceptive device demand concentration and shaping regional access patterns across the archipelago.
Kanto/Tokyo
Women's health clinics in Tokyo Prefecture drive intrauterine device insertion volumes through expanded MHLW reimbursement eligibility. PMDA oversight governs premarket approvals for hormonal delivery systems entering this metropolitan corridor. Shibuya and Shinjuku medical districts concentrate specialized gynecological services that capture young adult demand aged 20-34.
Kansai/Osaka
Osaka Prefecture mirrors Tokyo's clinical infrastructure density with comparable long-acting reversible contraceptive adoption rates. METI coordinates industrial standards compliance for domestic manufacturers operating in this region. Medical-grade silicone supply chains cluster in Kansai facilities, creating localized production advantages for barrier method producers.
Chubu/Nagoya
Nagoya's healthcare networks sustain moderate device demand through established hospital gynecology departments. JIS standards enforcement by METI affects regional manufacturing qualification timelines. Aichi Prefecture maintains secondary metropolitan demand for condom products through retail pharmacy networks.
Kyushu
Fukuoka and surrounding prefectures present underpenetrated whitespace for clinic network expansion beyond established metropolitan corridors. National health insurance reimbursement frameworks extend to this region with reduced specialist density. Telehealth-enabled prescription services are emerging to bridge geographic access gaps for barrier method procurement.
Hokkaido
Sapporo anchors northern Japan's limited contraceptive device demand through centralized hospital systems. Cold chain logistics constraints affect hormonal product distribution to outlying municipalities. Regional health authorities coordinate with MHLW on coverage policy implementation across dispersed populations.
Japan Contraceptive Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's contraceptive device sector, creating a tiered competitive structure shaped by regulatory compliance depth and manufacturing scale. Pharmaceutical multinationals anchor hormonal intrauterine system supply through specialized device portfolios. Domestic manufacturers defend barrier method positions through captive production infrastructure. Strategic moves concentrate on reimbursement positioning alignment and digital channel integration rather than capacity expansion.
Within the diversified pharmaceutical tier, Bayer AG and Merck & Co., Inc occupy positions exemplifying multinational device portfolio strategies. Among domestic specialists, Okamoto Industries represents scale-driven barrier method production anchored in regional manufacturing clusters. Cooper Surgical Inc sits within the focused medical device archetype, navigating PMDA pathways through specialized gynecological product positioning.
| Leading Market Players |
|---|
| Okamoto Industries |
| Cooper Surgical Inc. |
| Bayer AG |
| Merck & Co., Inc |
| Abbvie Inc |
| Reckitt Benckiser |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd |
| Fujifilm Healthcare Corporation |
| Others |
Supply & Pricing Matrix
Medical-grade silicone feedstock from Kansai region refineries flows through three distinct pricing tiers before reaching Tokyo and Osaka end-users. Copper alloy spot volatility for intrauterine device cores compresses margins at the premium tier while polyurethane barrier inputs sustain volume accessibility at economy positioning.
Pricing Analysis
Bundled insertion services command premium positioning against unbundled device-only procurement across women's health clinics. Three-tier pricing structure across premium, standard, and economy levels separates hormonal intrauterine systems with MHLW reimbursement eligibility from copper alternatives and disposable barrier products. Pricing pressure stems from PMDA approval timeline friction extending commercialization cycles for novel delivery systems. Young adult individual purchasers in metropolitan prefectures exhibit highest price sensitivity for barrier replenishment, while hospital purchasing committees demonstrate lowest sensitivity for long-acting device contracts.
Supply Chain Analysis
Direct-to-clinic channels handle specialized device demand while drugstore distribution runs through Matsumoto Kiyoshi and comparable retail networks for barrier products. Domestic manufacturing concentrates in Japan's Kansai and Kanto industrial corridors, with secondary sourcing from South Korea and Taiwan for specialized polymer inputs. Raw material dependencies center on medical-grade silicone, copper alloys, and synthetic hormone compounds. Single-source vulnerability exists for PMDA-certified silicone formulation facilities. Distribution stratifies across clinical procurement platforms, retail pharmacy networks, and emergent telehealth-integrated e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's contraceptive device market functions as a stable compounder anchored by MHLW reimbursement expansion for long-acting reversible contraceptives. Structural demand from young adult demographic concentration in metropolitan prefectures sustains replacement cycles and clinical service revenue.
For Market Incumbents: Acquire telehealth platform capabilities to capture channel migration from physical clinic dependence. Incumbent device manufacturers face displacement risk from direct-to-consumer pharmacy entrants; defensive positioning requires backward integration into digital consultation infrastructure and captive supply of MHLW-preferred hormonal formulations. For New Entrants and Emerging Players: Rural clinic networks in Hokkaido and Kyushu represent underserved buyer archetypes with reimbursement access but limited specialist density. White-space penetration targets telehealth-enabled prescription services for barrier products and subdermal implant insertion partnerships with regional hospitals. Go-to-market execution should prioritize PMDA regulatory affairs staffing ahead of product registration. For Investors and Strategic Acquirers: Consolidation pressure builds where reimbursement complexity creates compliance scale advantages for diversified device portfolios. Long-term viability favors manufacturers with domestic manufacturing footprints and established MHLW coverage positioning. Acquisition target archetype: mid-cap specialists with PMDA-approved hormonal delivery systems and underutilized Kansai production capacity. Signal to monitor: METI industrial standard updates accelerating certification cost burdens for subscale competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | MHLW coverage expansion for hormonal intrauterine devices reshapes provider prescribing patterns in Tokyo and Osaka. |
| PMDA Submission Pathway | Premarket approval timelines determine effective commercialization windows for novel subdermal implant formulations. |
| Hospital System Partnership | Academic medical centers in metropolitan prefectures anchor insertion volumes for long-acting reversible contraceptives. |
| Telehealth Platform Integration | Digital consultation infrastructure captures young adult demand migrating from physical clinic dependence. |
| Backward Integration | Captive medical-grade silicone supply from Kansai facilities insulates against raw material qualification delays. |
Research Methodology
Coverage spans Japan's Kanto, Kansai, Chubu, Kyushu, and Hokkaido regions, with primary inputs from each prefecture's healthcare infrastructure. Interviews with gynecological specialists, hospital purchasing committee members, MHLW reimbursement policy officers, and pharmaceutical device regulatory consultants combined with secondary validation from PMDA approval databases, METI industrial standard filings, and national health insurance claims data. Bottom-up demand modeling triangulated against top-down market sizing across product type and distribution channel segments.
Rate-of-change decomposition isolates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end user procurement authority, distribution channel, and age group life-stage preferences. CAGRs derived from trend extrapolation of historical reimbursement policy shifts and demographic cohort analysis. Forecast inputs incorporate MHLW coverage eligibility trajectories and METI manufacturing compliance cost projections.
Inputs from PMDA regulatory filings and MHLW reimbursement bulletins were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around clinic channel volume estimates. Forecasts reflect assumptions regarding reimbursement policy continuity and copper alloy input cost stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Enteral Stents Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
North America Electrophysiology Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Suction Catheters Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
External Defibrillator Market
Medical Devices
Biological Microscope Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Allografts Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Posture Correction Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market