
 Sweden Respiratory Devices Market | 2026-2036
Sweden Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Respiratory Devices Market Analytics
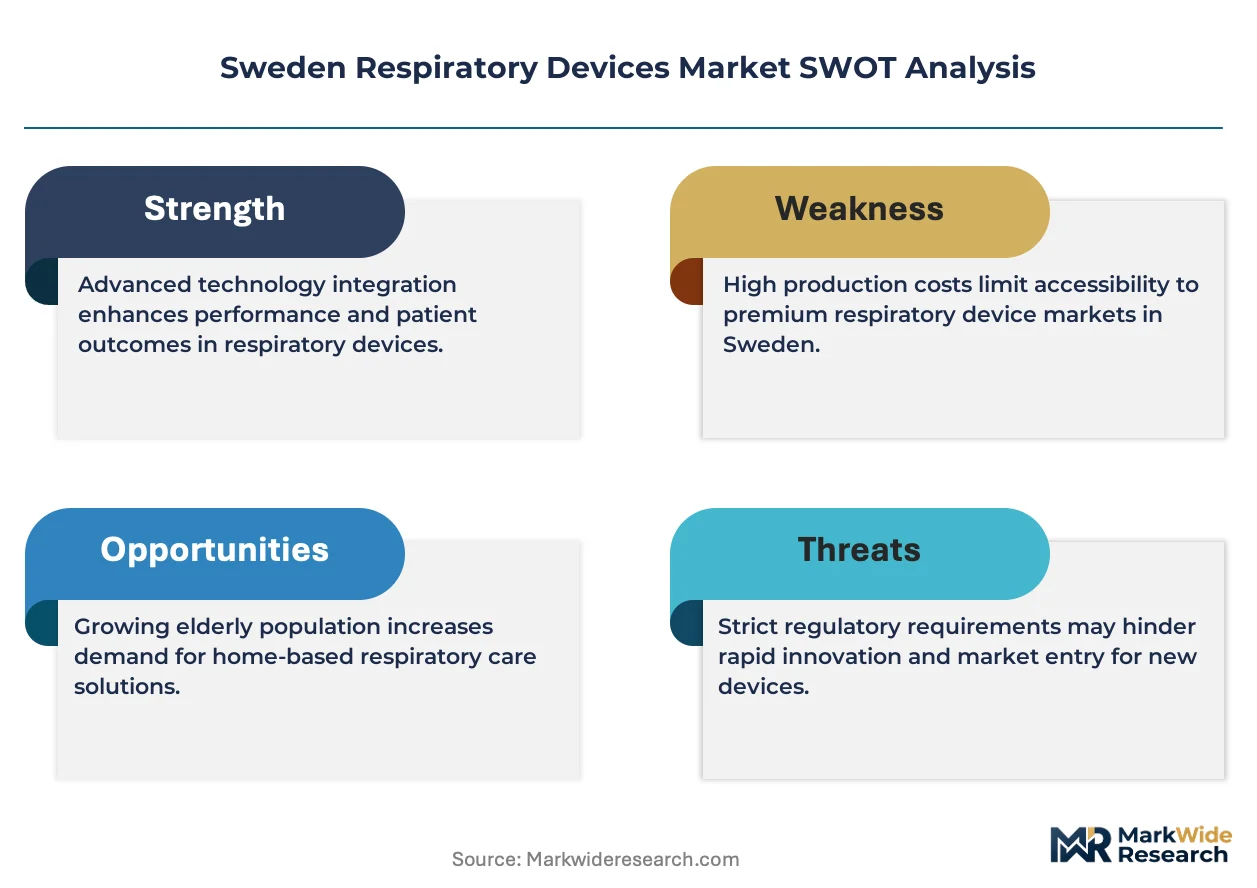
CE marking under the EU Medical Devices Regulation is collapsing the supplier base for high-risk respiratory equipment in Sweden. Dragerwerk AG leverages its intensive care ventilation portfolio to sustain dominance across Swedish regional hospitals. Fisher & Paykel Healthcare Ltd differentiates through humidification systems that integrate with existing ventilator platforms. Medtronic PLC anchors its position via deep distribution relationships with the seven Swedish regional health authorities.
Respiratory devices encompass mechanical apparatus designed to assist, control, or supplement pulmonary ventilation through positive or negative pressure delivery, typically operating at flow rates between 10 and 120 liters per minute depending on clinical indication. These systems serve acute and chronic patient populations requiring airway support, oxygen enrichment, or aerosolized pharmaceutical delivery in clinical and domiciliary settings. Ventilators command the highest capital allocation within Swedish hospital procurement budgets, while CPAP devices generate recurring revenue streams through mask and tubing replacement cycles in homecare settings. Digital Monitoring technology is expanding fastest as Swedish providers integrate remote patient oversight into post-discharge protocols for COPD and sleep apnea cohorts.
The Swedish Medical Products Agency (Läkemedelsverket) enforces MDR compliance timelines that determine market access for Class IIa and above respiratory devices, while the Swedish Work Environment Authority (Arbetsmiljöverket) mandates occupational exposure limits that drive industrial respiratory protection demand. ISO 80601-2-80 standards for sleep apnea breathing equipment further constrain product design parameters for manufacturers targeting Swedish reimbursement pathways. Stakeholders must track regional procurement consolidation under the National Board of Health and Welfare's standardization directives, as these frameworks increasingly bundle device acquisition with long-term service obligations.
Market Dynamics
The Medical Devices Regulation transition is compressing the supplier base for high-risk respiratory equipment in Sweden, forcing manufacturers to consolidate certification resources or exit the market entirely. This structural pressure reshapes competitive positioning across ventilator and CPAP segments.
Growth Catalysts
- Regional hospital procurement consolidation:The National Board of Health and Welfare's standardization directives bundle device acquisition with long-term service obligations, creating multi-year revenue visibility for compliant suppliers.
- ISO 80601-2-80 compliance pathways:Swedish reimbursement frameworks reward manufacturers meeting sleep apnea breathing equipment standards, accelerating product development cycles for homecare-focused devices.
- Gothenburg medical technology corridor expansion:Clustering of R&D facilities and clinical trial sites draws venture funding toward respiratory innovation, shortening time-to-market for novel humidification and monitoring technologies.
Market Restraints
- MDR certification bottlenecks:Notified body capacity constraints in Europe extend approval timelines for Class IIa and above devices, freezing new entrants from Swedish market access for 18-36 months.
- Semiconductor supply concentration:Ventilator control systems depend on specialized chip fabrication concentrated in East Asian foundries, exposing Swedish hospitals to allocation risk during demand surges.
- CPAP mask silicone dependency:Medical-grade elastomer supply tightens periodically, compressing margins on consumables that generate recurring revenue for homecare providers.
Strategic Opportunities
- Digital Monitoring integration:Remote patient oversight platforms for COPD and sleep apnea cohorts remain underpenetrated in Norrland's dispersed populations, creating first-mover advantages for cloud-connected device vendors.
- Arbetsmiljöverket industrial mandates:Occupational exposure limit enforcement drives replacement cycles for workplace respiratory protection equipment, opening parallel revenue streams beyond clinical applications.
- AI-enabled diagnostic convergence:Machine learning algorithms layered atop ventilator waveform data enable predictive intervention protocols, differentiating premium equipment tiers in Stockholm's university hospital clusters.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in pneumatic system design and regulatory documentation concentrates in Stockholm and Gothenburg, constraining scaling for manufacturers in secondary cities.
- Legacy device interoperability:Swedish regional health authorities operate heterogeneous ventilator fleets accumulated over decades, complicating centralized data aggregation and remote monitoring deployment.
- CE marking transition timelines:Manufacturers face compressed windows to recertify legacy products under MDR requirements, forcing portfolio rationalization decisions that eliminate marginal SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Respiratory Devices Market |
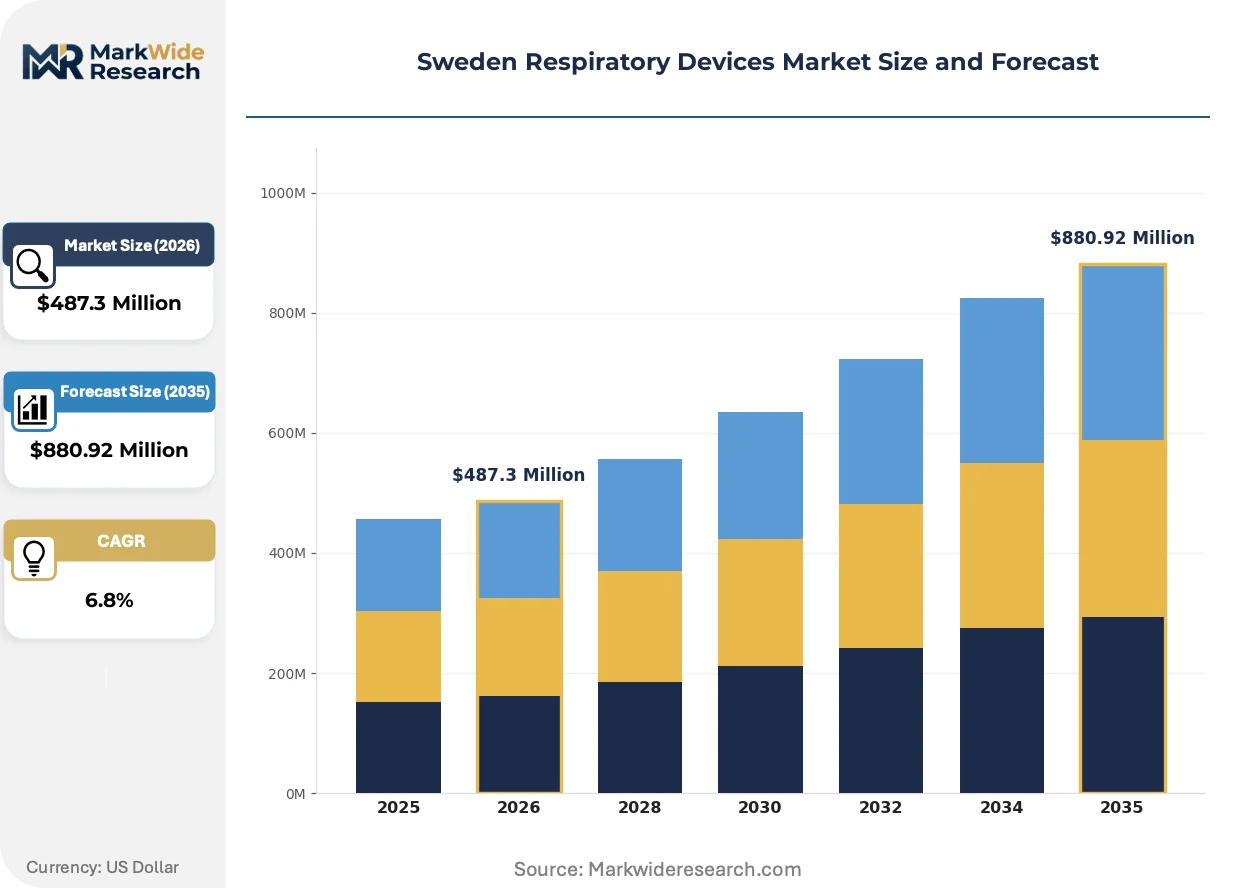
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Nebulizers, CPAP Devices, Oxygen Concentrators Application: Chronic Obstructive Pulmonary Disease, Asthma Management, Sleep Apnea Treatment, Invasive Mechanical Ventilation End User: Hospitals, Homecare Settings, Clinics, Rehabilitation Centers Technology: Digital Monitoring, Portable Devices, Continuous Positive Airway Pressure, Bi-level Positive Airway Pressure |
| Companies Covered | Dragerwerk AG, Fisher & Paykel Healthcare Ltd, Fosun Pharmaceutical (Breas Medical AB), GE Healthcare, Medtronic PLC, Koninklijke Philips NV, GlaxoSmithKline PLC, Invacare Corporation, Getinge AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Respiratory Devices Market Evolving Landscape
Swedish respiratory device development is pivoting toward connected care ecosystems and predictive analytics, displacing standalone hardware sales with integrated platform offerings. This shift reconfigures R&D priorities and partnership strategies across the value chain.
Adaptive ventilation algorithms is bifurcating the intensive care equipment landscape. These systems automatically adjust pressure support based on real-time respiratory mechanics. Sahlgrenska University Hospital and Karolinska University Hospital are piloting implementations with documented weaning protocol improvements. The technology is bifurcating purchasing criteria toward software capability rather than hardware specifications alone.
EU MDR Article 10 post-market surveillance requirements impose systematic clinical follow-up obligations on manufacturers of high-risk respiratory devices. Swedish manufacturers must now maintain active implantable-equivalent vigilance for ventilators and CPAP systems, doubling regulatory affairs headcount for mid-tier suppliers. Class III invasive ventilation equipment faces the steepest documentation burden, with Stockholm-based firms accelerating hiring of clinical data specialists.
Regional health authority procurement teams are unbundling device acquisition from proprietary service contracts, demanding open-architecture maintenance protocols. This purchasing pattern shift disrupts historical lock-in strategies of dominant ventilator suppliers. Västra Götaland and Skåne regional authorities now mandate interoperability certification as a bid prerequisite, compressing pricing power for integrated system vendors.
Sweden Respiratory Devices Market Segmentation
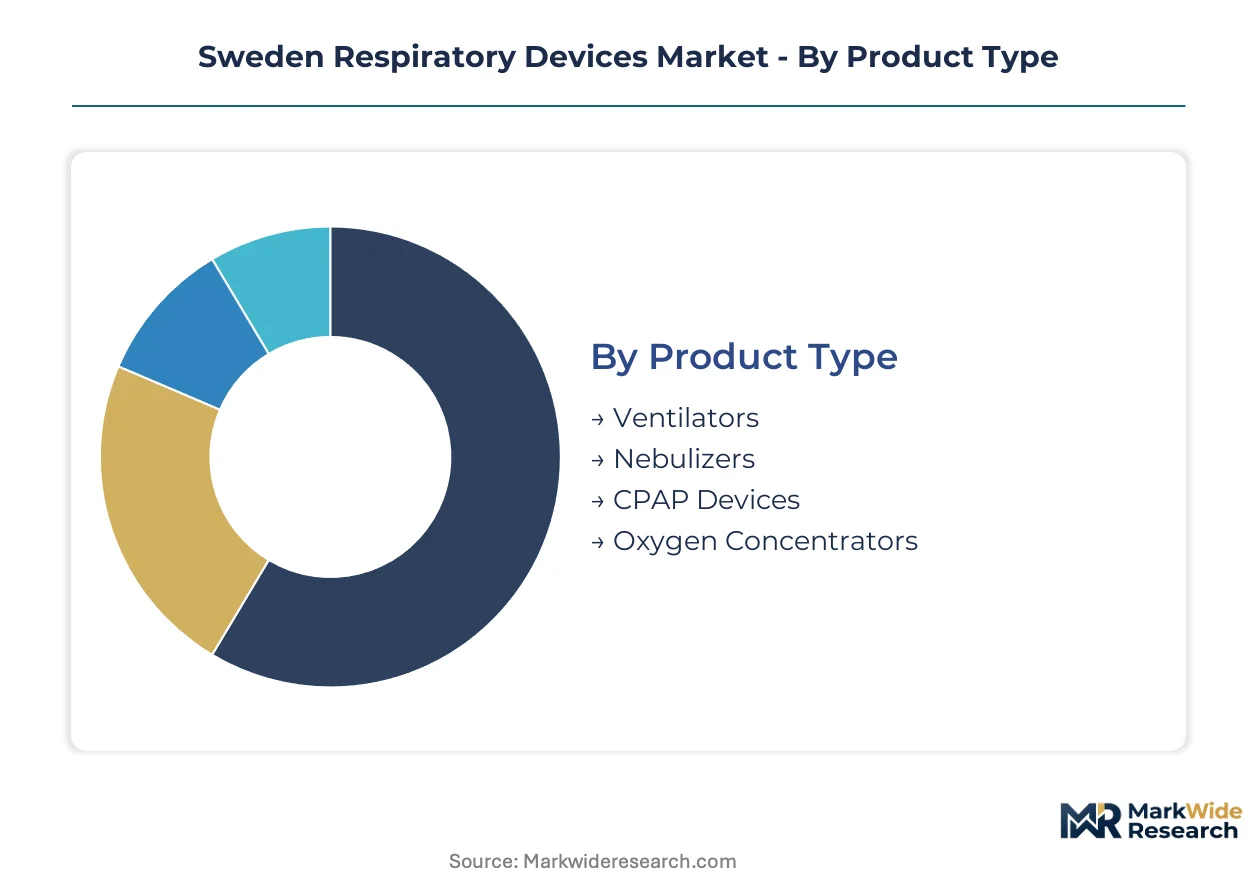
Respiratory device procurement in Sweden fragments across acute care infrastructure, domiciliary reimbursement pathways, and industrial occupational health mandates. Channel configuration determines margin structure and service obligation intensity for manufacturers serving Swedish regional health authorities.
Product Type:
Ventilators flow through hospital capital equipment tenders with bundled maintenance terms, while CPAP devices and oxygen concentrators reach patients via pharmacy retail and homecare distributor networks.
- Ventilators:Intensive care units and emergency departments specify pneumatic systems delivering pressure-controlled and volume-controlled ventilation modes. Demand concentrates in Stockholm's university hospital clusters where regional procurement consolidation favors multi-year service contracts over standalone hardware sales.
- CPAP Devices:Continuous positive airway pressure systems for obstructive sleep apnea incorporate humidification modules and mask interfaces. Homecare settings in Gothenburg's medical technology corridor drive replacement cycles for masks and tubing that generate recurring revenue streams.
- Nebulizers:Aerosol delivery systems for bronchodilator and corticosteroid administration serve pediatric asthma management in outpatient clinics.
- Oxygen Concentrators:Pressure swing adsorption units providing 90-95% oxygen purity support COPD patients in Norrland's dispersed rural populations where cylinder delivery logistics prove prohibitive.
Ventilators dominate installed base capital allocation. CPAP devices are where expansion concentrates.
Application:
Cost tier stratification separates acute intervention reimbursement from chronic disease management protocols, with invasive mechanical ventilation commanding premium pricing and sleep apnea treatment relying on volume-driven homecare economics.
- Invasive Mechanical Ventilation:Endotracheal and tracheostomy-based ventilation supports respiratory failure in ICUs. Swedish regional hospitals prioritize adaptive algorithms that automate weaning protocols, with Sahlgrenska University Hospital piloting implementations that reduce ventilation duration.
- Sleep Apnea Treatment:Diagnostic and therapeutic pathways for obstructive sleep apnea integrate home sleep testing with auto-titrating CPAP. ISO 80601-2-80 compliance determines reimbursement eligibility under the Swedish Medical Products Agency frameworks.
- Chronic Obstructive Pulmonary Disease:Long-term oxygen therapy and non-invasive ventilation address progressive airflow limitation. Pulmonary rehabilitation programs in Skåne regional authority bundle device provision with patient education.
- Asthma Management:Pediatric and adult asthma protocols emphasize metered-dose inhaler technique and nebulized bronchodilator rescue therapy in primary care settings.
Invasive mechanical ventilation absorbs the highest per-procedure reimbursement. Sleep apnea treatment is climbing the fastest as diagnostic penetration deepens.
End User:
Customer type determines regulatory classification and post-market surveillance intensity, with hospitals triggering Class IIb and III device obligations while homecare settings operate under lighter documentation requirements.
- Hospitals:Acute care facilities across Sweden's seven regional health authorities operate heterogeneous ventilator fleets accumulated over decades. The National Board of Health and Welfare's standardization directives now mandate interoperability certification as a bid prerequisite.
- Homecare Settings:Domiciliary oxygen and sleep therapy providers manage patient adherence through remote monitoring platforms. Digital Monitoring integration remains underpenetrated in Norrland's dispersed populations.
- Clinics:Outpatient pulmonary function testing and asthma specialist centers require portable diagnostic spirometry and peak flow monitoring equipment.
- Rehabilitation Centers:Post-acute weaning facilities and pulmonary rehabilitation programs utilize non-invasive ventilation for neuromuscular and chest wall disorder patients.
Hospitals anchor procurement volume concentration. Homecare settings are gaining share fastest as reimbursement shifts toward ambulatory care.
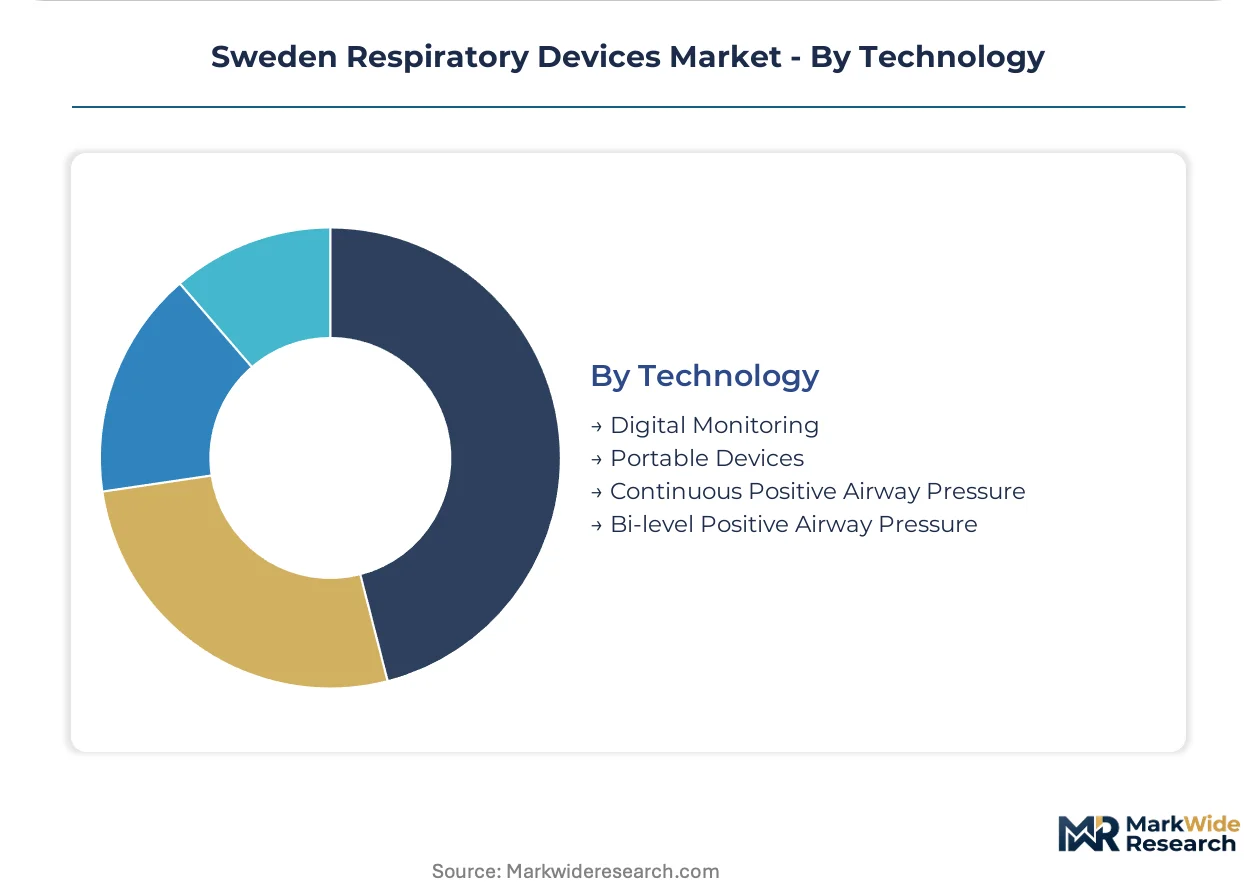
Technology:
Technology maturity separates established pneumatic platforms from emerging digital overlays, with portable device miniaturization enabling geographic expansion into underserved regions.
- Digital Monitoring:Cloud-connected respiratory devices transmit adherence data and physiological parameters to clinical decision support systems. Remote patient oversight platforms for COPD and sleep apnea cohorts create first-mover advantages for vendors integrating with Swedish electronic health record architectures.
- Portable Devices:Battery-operated oxygen concentrators and travel CPAP systems weigh under 2.5 kilograms for ambulatory patient mobility. Lightweight designs penetrate Norrland's remote municipalities where transportation infrastructure limits cylinder delivery frequency.
- Continuous Positive Airway Pressure:Fixed-pressure and auto-titrating CPAP systems deliver splinting pressure to prevent upper airway collapse during sleep.
- Bi-level Positive Airway Pressure:Spontaneous-timed and pressure-controlled modes support neuromuscular disease and obesity hypoventilation syndrome in hospital and homecare settings.
Continuous positive airway pressure dominates unit shipment volume. Digital Monitoring is where steepest expansion trajectory materializes as regional authorities integrate remote oversight into post-discharge protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish regional health authorities concentrate procurement power across seven administrative regions, with university hospital clusters driving ventilator demand and Gothenburg's medical technology corridor anchoring device innovation.
Stockholm
Karolinska University Hospital and Södersjukhuset anchor intensive care ventilator procurement for Region Stockholm, with adaptive ventilation algorithm pilots reducing mechanical ventilation duration. The Swedish Medical Products Agency enforces MDR compliance timelines for Class IIb and III devices entering this cluster. Digital Monitoring integration trials for post-discharge COPD oversight concentrate in Stockholm's electronic health record architectures.
Västra Götaland
Sahlgrenska University Hospital drives demand for humidification-integrated ventilator platforms and non-invasive ventilation systems for neuromuscular patients. Region Västra Götaland's procurement mandates interoperability certification as a bid prerequisite, unbundling device acquisition from proprietary service contracts. Gothenburg's medical technology corridor draws venture funding toward respiratory R&D facilities and clinical trial sites.
Skåne
Skåne University Hospital operates heterogeneous ventilator fleets accumulated over decades, complicating centralized data aggregation for remote monitoring deployment. The National Board of Health and Welfare's standardization directives bundle device acquisition with long-term service obligations across this region. Pulmonary rehabilitation programs in Lund and Malmö bundle oxygen concentrator provision with patient education protocols.
Norrland
Norrland's dispersed rural populations drive portable oxygen concentrator demand where cylinder delivery logistics prove prohibitive, with battery-operated units under 2.5 kilograms penetrating remote municipalities. Digital Monitoring technology remains underpenetrated in this geography, creating first-mover advantages for cloud-connected device vendors. Umeå University Hospital anchors specialist respiratory care for Sweden's northernmost counties.
Östergötland
Linköping University Hospital manages regional intensive care ventilation capacity for southeastern Sweden, with procurement falling under the National Board of Health and Welfare's standardization frameworks. The region's industrial base generates parallel demand for workplace respiratory protection equipment under Arbetsmiljöverket occupational exposure mandates. Post-acute weaning facilities in Norrköping utilize non-invasive ventilation for chest wall disorder patients.
Sweden Respiratory Devices Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with intensive care portfolios, with mid-tier specialists and regional distributors occupying secondary positions. Three archetypes dominate: German industrial conglomerates with critical care ventilation heritage, Asia-Pacific diversified healthcare groups with sleep therapy platforms, and Nordic regional champions with local service networks. Competitive moves concentrate on M&A consolidation of notified body certification capabilities and strategic partnerships for digital health platform integration.
Within the diversified medical technology tier, Dragerwerk AG and Medtronic PLC exemplify archetypes leveraging deep distribution relationships with Swedish regional health authorities. Fisher & Paykel Healthcare Ltd occupies a position representing humidification system specialists that integrate with existing ventilator platforms. These three entities anchor competitive dynamics across Stockholm's university hospital clusters and Gothenburg's procurement corridors.
| Leading Market Players |
|---|
| Dragerwerk AG |
| Fisher & Paykel Healthcare Ltd |
| Fosun Pharmaceutical (Breas Medical AB) |
| GE Healthcare |
| Medtronic PLC |
| Koninklijke Philips NV |
| GlaxoSmithKline PLC |
| Invacare Corporation |
| Getinge AB |
| Others |
Value Network & Pricing Analysis
EU Medical Devices Regulation certification gates both supplier qualification and price differentiation simultaneously in the Swedish respiratory devices market. The MDR transition collapses the supplier base for high-risk equipment while creating tiered pricing power for compliant manufacturers serving Stockholm's university hospital clusters.
Pricing Analysis
Multi-year cost-plus contracts with Swedish regional health authorities incorporate semiconductor and medical-grade elastomer indexation clauses. Three-tier pricing structure across premium adaptive-ventilation systems, standard ICU platforms, and economy homecare CPAP devices reflects ISO 80601-2-80 certification grade and bundled service obligation intensity. Pricing pressure stems from semiconductor allocation risk concentrated in East Asian foundries, compressing margins on ventilator control systems. Homecare settings exhibit highest price sensitivity due to pharmacy retail channel competition, while intensive care procurement teams prioritize algorithm capability over unit cost.
Supply Chain Analysis
Taiwan Strait transit exposure underwrites ventilator semiconductor supply security for Swedish manufacturers. Control system chip fabrication concentrates in Taiwan and South Korea, while medical-grade silicone for CPAP masks sources from Germany and Japan. Single-source vulnerability in specialized pneumatic valve components creates allocation risk during demand surges. Distribution runs through seven Swedish regional health authority procurement consortia, with Gothenburg's medical technology corridor anchoring aftermarket service logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in MDR regulatory documentation and adaptive algorithm development concentrates in Stockholm and Gothenburg, constraining scaling for manufacturers lacking these capabilities. The market rewards firms that consolidate certification resources before notified body capacity constraints freeze new entrants.
For Market Incumbents: Consolidate notified body certification capabilities through targeted hiring of clinical data specialists to defend against MDR documentation burden escalation. Deepen distribution relationships with Västra Götaland and Skåne regional authorities before interoperability mandates unbundle proprietary service contracts. Prioritize backward integration into humidification module production to capture margin from Fisher & Paykel Healthcare's integration strategy. For New Entrants and Emerging Players: Anchor in Norrland's dispersed rural populations where Digital Monitoring penetration remains underdeveloped and portable oxygen concentrator demand outstrips supply. Target Umeå University Hospital's specialist respiratory care network for pilot deployments of cloud-connected COPD oversight platforms. Pursue direct-to-homecare distributor relationships bypassing Stockholm procurement consolidation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across adaptive ventilation algorithm development as Sahlgrenska and Karolinska university hospitals demand predictive intervention capabilities. Long-term viability favors mid-tier specialists with existing ISO 80601-2-80 certification pathways rather than hardware-only manufacturers facing MDR recertification cliffs. Watch notified body approval velocity for Class III invasive ventilation equipment as the inflection signal for portfolio rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR transition timelines determine market access for Dragerwerk and Medtronic portfolios. |
| Hospital System Partnership | Karolinska and Sahlgrenska pilots establish reference sites for adaptive algorithm adoption. |
| Software Companion Development | Remote monitoring platforms differentiate vendors in Norrland's underpenetrated geographies. |
| Reimbursement Strategy Alignment | ISO 80601-2-80 compliance secures Swedish Medical Products Agency eligibility for CPAP providers. |
| Backward Integration into Humidification | In-house production of integration modules captures margin from ventilator platform sales. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the Swedish respiratory devices value chain. Primary interviews engaged hospital purchasing committee members, biomedical engineers at Stockholm and Gothenburg university hospitals, GPO contracts managers within regional health authorities, and regulatory affairs leads at notified body certification firms. Secondary validation drew from Swedish Medical Products Agency MDR guidance documents, National Board of Health and Welfare procurement directives, ISO 80601-2-80 standard publications, and Arbetsmiljöverket occupational exposure mandate records. Bottom-up segment sizing triangulated against top-down regional health authority capital expenditure patterns.
Across the analysis window, volume and value outputs reflect segmented modeling across product type, application, end user, and technology dimensions. CAGRs were derived from installed base replacement cycles, diagnostic penetration trajectories for sleep apnea, and remote monitoring adoption curves in COPD management. Forecast inputs incorporated regional procurement consolidation timelines under National Board of Health and Welfare standardization directives and semiconductor supply allocation scenarios from East Asian foundries.
Underlying assumptions cover MDR certification completion rates, notified body capacity expansion, and regional health authority interoperability mandate enforcement, with deviation risk concentrated in semiconductor supply disruptions and biomedical engineering talent migration patterns. Practitioners should keep alternative scenarios live as EU regulatory implementation timelines and East Asian foundry allocation policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Direct Energy Medical Devices Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Gastric Bands Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
High Flow Oxygen Therapy Devices Market