
 Urine Collection Devices Market | 2026-2036
Urine Collection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Urine Collection Devices Market Outlook
A shift from single-source to multi-source polymer procurement is hardening among tier-one manufacturers. Coloplast A/S leverages its captive silicone supply chain to sustain margin stability across European home care channels. B. Braun Melsungen AG anchors its position through in-house extrusion capabilities for catheter-connected collection systems. Medline Industries, LP competes on distribution density, controlling shelf space across integrated delivery networks in the United States.
Urine collection devices comprise closed and open drainage systems engineered from medical-grade PVC, silicone, or latex with graduated volume markings and anti-reflux valves, designed to capture, measure, and transport urine for drainage management or laboratory analysis. Collection bags dominate hospital procurement volumes due to standardized catheterization protocols, while home care demand for portable urinals is expanding fastest as discharge planning shifts toward ambulatory recovery. Plastic-based single-use devices command the largest production footprint, though silicone multi-use systems capture disproportionate margin pools in long-term catheterization where durability reduces replacement frequency.
The FDA enforces sterility and biocompatibility standards under 21 CFR Part 820 quality system regulations, while Europe's MDR requires clinical evidence updates for legacy collection devices previously cleared under the Medical Device Directive. Japan's PMDA maintains distinct packaging and labeling requirements that shape export-ready product configurations for Asian markets. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs diverge and determine whether regional SKU proliferation or harmonized platform designs offer superior capital efficiency.
Market Dynamics
The transition from open to closed-system urine collection is hardening catheterization protocols across acute care settings, with infection control committees now mandating anti-reflux valve configurations as standard equipment rather than premium upgrades.
Growth Catalysts
- MDR compliance deadlines:Europe's Medical Device Regulation is forcing hospital procurement departments to refresh legacy device inventories, creating replacement demand for certified closed-system bags.
- Home care discharge protocols:Post-acute care planners in Germany and Japan are expanding portable urinal prescriptions to reduce readmission rates among mobility-limited patients.
- Silicone material substitution:Long-term catheterization programs are migrating toward multi-use silicone systems to cut replacement labor and material waste.
Market Restraints
- Medical-grade PVC resin concentration:Three petrochemical suppliers control specialty polymer feedstocks for disposable collection bags, exposing converters to input cost volatility.
- Japan PMDA packaging mandates:Distinct sterilization barrier and labeling requirements force dedicated SKU configurations that fragment production runs.
- Catheter-free monitoring alternatives:Non-invasive bladder volume scanners are displacing indwelling collection systems in select post-operative recovery protocols.
Strategic Opportunities
- India's hospital infrastructure buildout:Greenfield medical cities in Gujarat and Tamil Nadu lack entrenched supplier relationships, creating first-mover access for closed-system bag manufacturers.
- Reimbursement code unbundling:US CMS separation of collection device costs from catheter procedure payments enables standalone pricing strategies for premium configurations.
- Antimicrobial coating convergence:Silver-ion and chlorhexidine surface treatments are merging with silicone extrusion processes to command infection-control premiums.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for novel polymer blends extend product launch schedules by 14-18 months.
- Cleanroom extrusion capacity:FDA 21 CFR Part 820 compliant manufacturing lines require capital commitments that strain mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urine Collection Devices Market |
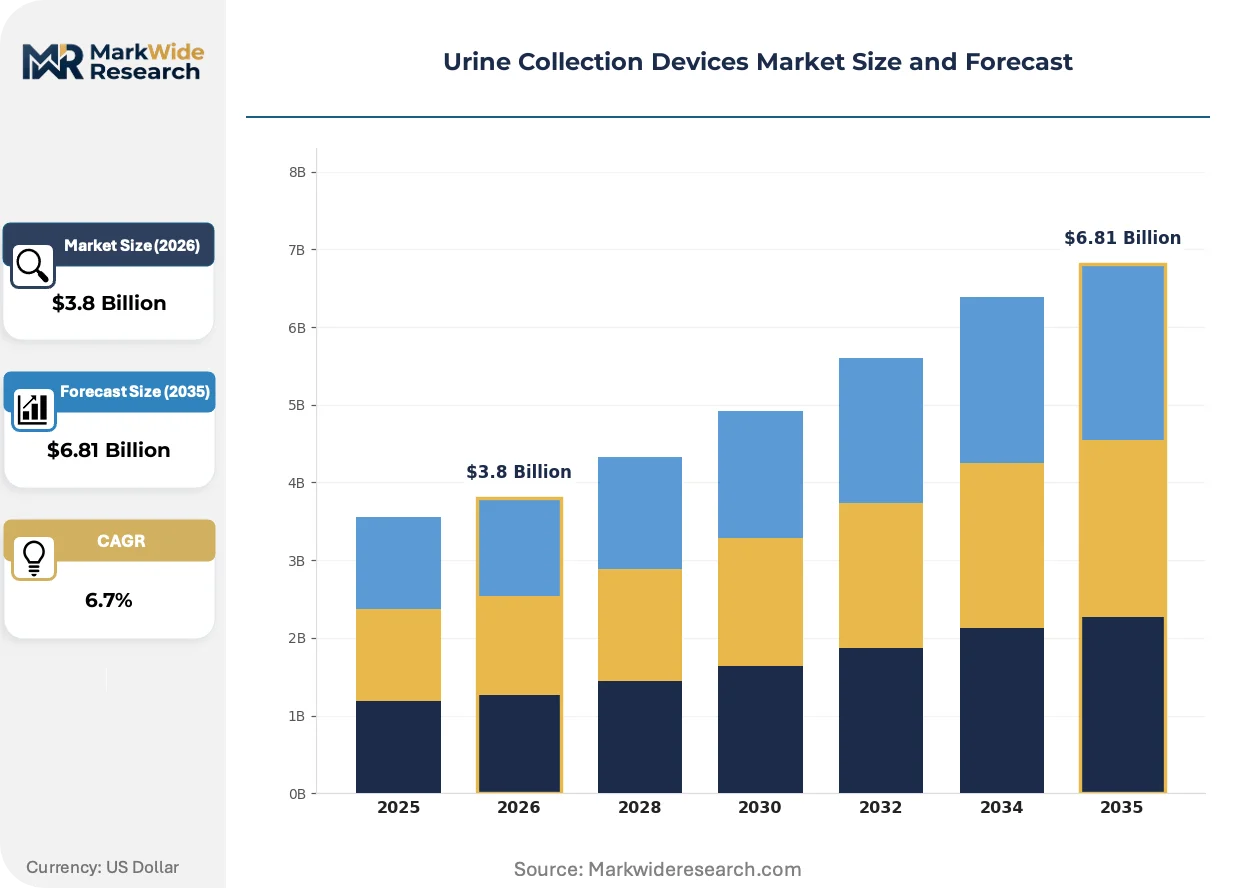
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
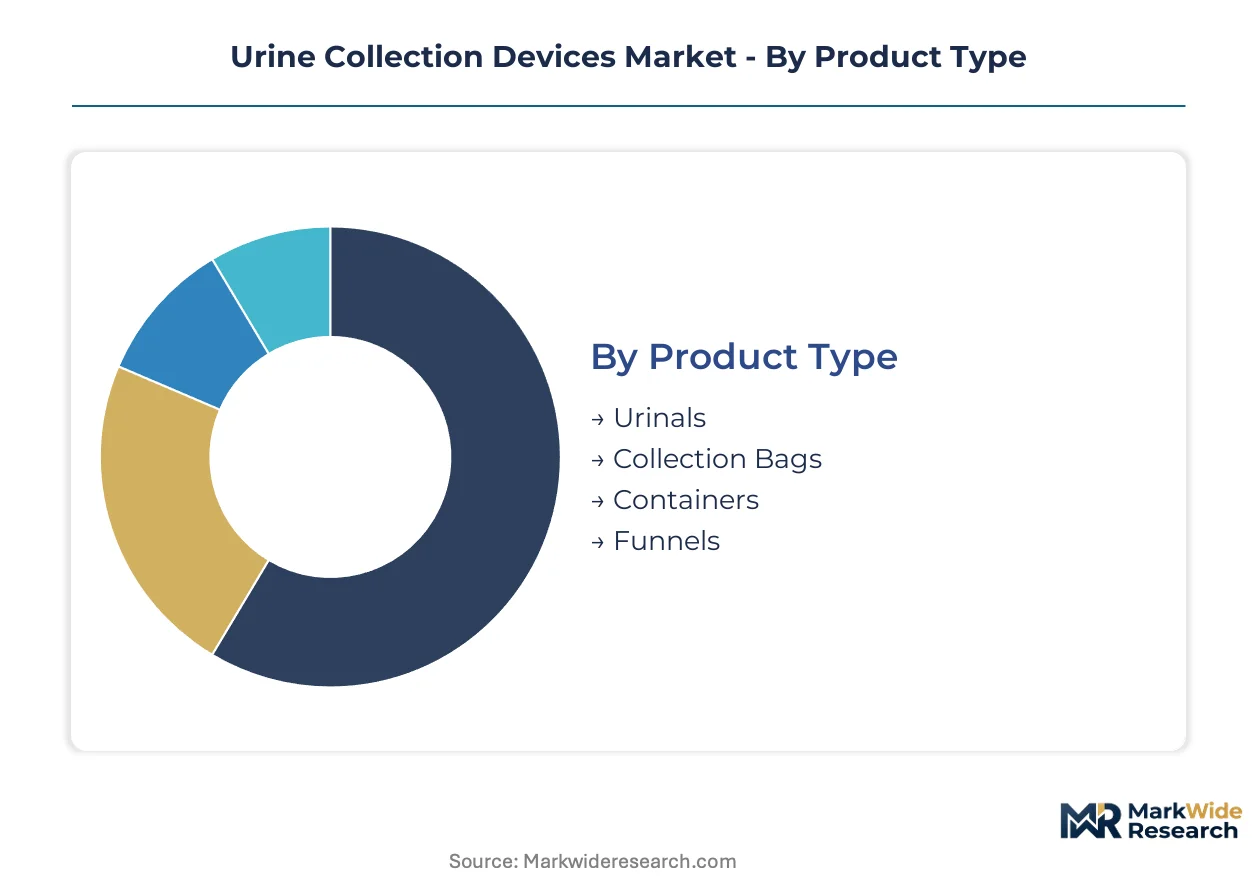
| Segmentation | Product Type: Urinals, Collection Bags, Containers, Funnels End User: Hospitals, Clinics, Home Care, Laboratories Material: Plastic, Glass, Metal, Disposable Usage Type: Single-use, Multi-use, Point-of-care, Diagnostic |
| Companies Covered | Becton, Dickinson and Company, Coloplast A/S, B. Braun Melsungen AG, Teleflex Incorporated, ConvaTec Group PLC, Hollister Incorporated, Medline Industries, LP, Cardinal Health, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urine Collection Devices Market Strategic Shifts
Digital volume monitoring and antimicrobial material science are converging to redefine performance benchmarks, while regulatory divergence between major jurisdictions is fragmenting product platform strategies.
Closed-system collection bags with integrated electronic flow sensors are automating real-time output tracking for ICU nursing staff. Academic medical centers in the United States are piloting these configurations to reduce manual charting burden and enable early sepsis detection through urine output trend analysis. This automation is compressing the interval between physiological change and clinical response, shifting competitive advantage toward device-data integration capabilities.
Europe's MDR transition is forcing clinical evidence updates for legacy collection devices previously cleared under the Medical Device Directive. Manufacturers must now submit post-market surveillance data and biological safety documentation that was not required under prior rules. Home care distributors in Germany and France are responding by consolidating supplier portfolios to favor vendors with dedicated regulatory affairs teams.
Integrated delivery networks in the United States are consolidating catheter and collection device procurement under single-source agreements that bundle infection rate guarantees. Hospital purchasing cooperatives are displacing individual facility negotiations, concentrating volume with distributors offering logistics integration and consignment inventory programs. This consolidation is most visible in the southeastern states where health system mergers have reduced independent acute care facilities by one-third over the past decade.
Urine Collection Devices Market Segmentation
Urine collection devices fragment across four structural dimensions that determine procurement patterns, margin pools, and regulatory exposure. Material chemistry and usage protocols create the deepest fault lines between commodity converters and specialized manufacturers.
Product Type:
Standardization dominates high-volume hospital procurement, while customization concentrates in ambulatory and home care channels where patient mobility constraints vary widely.
- Collection Bags:Medical-grade PVC or silicone reservoirs with graduated volume markings and anti-reflux valves, engineered for closed-system catheter connections. Demand concentrates in United States and German acute care facilities where infection control committees now mandate anti-reflux configurations as baseline equipment rather than premium upgrades.
- Urinals:Portable receptacles in polypropylene or stainless steel configurations, designed for bedridden or mobility-limited patients without catheterization. Home care discharge planners in Japan and Germany are expanding prescriptions to reduce readmission rates among elderly populations recovering outside institutional settings.
- Containers:Rigid specimen vessels with leak-resistant closures for laboratory transport and analysis.
- Funnels:Polypropylene or polyethylene transfer devices for clean-catch midstream sampling protocols.
Most installed capacity flows through Collection Bags. Expansion is steepest in Urinals.
End User:
Reimbursement structure and sterility requirements split manufacturing economics between institutional purchasers and dispersed retail channels.
- Hospitals:Integrated delivery networks and purchasing cooperatives dominate procurement, consolidating volume under single-source agreements that bundle infection rate guarantees with logistics integration. Southeastern United States health system mergers have reduced independent acute care facilities by one-third over the past decade, concentrating purchasing power with distributors offering consignment inventory programs.
- Home Care:Dispersed patient populations and prescription-based fulfillment create channel complexity. German and Japanese post-acute care planners are driving fastest volume expansion as discharge protocols shift toward ambulatory recovery and portable urinal prescriptions multiply.
- Clinics:Outpatient facilities with intermediate sterility requirements and lower per-procedure reimbursement ceilings.
- Laboratories:Specimen handling operations requiring traceable chain-of-custody packaging and transport configurations.
Hospital procurement absorbs the dominant share of production output. Home Care is climbing the fastest as population aging accelerates device utilization outside institutional walls.
Material:
Cost tier and durability expectations divide polymer converters from metal fabricators, with regulatory biocompatibility requirements filtering supplier participation.
- Plastic:Medical-grade PVC, polypropylene, and polyethylene formulations for single-use disposables. Three petrochemical suppliers control specialty polymer feedstocks for disposable collection bags, exposing converters to input cost volatility and supply concentration risk.
- Disposable:Synonymous with plastic-based single-use configurations in procurement taxonomy, capturing largest production footprint due to standardized catheterization protocols and elimination of reprocessing labor.
- Glass:Borosilicate specimen containers for laboratory analysis requiring chemical inertness and optical clarity.
- Metal:Stainless steel urinals and bedpans for long-term care facilities with central sterilization capabilities.
Plastic commands the installed base. The Disposable category is gaining share fastest as infection control protocols harden against reusable alternatives.
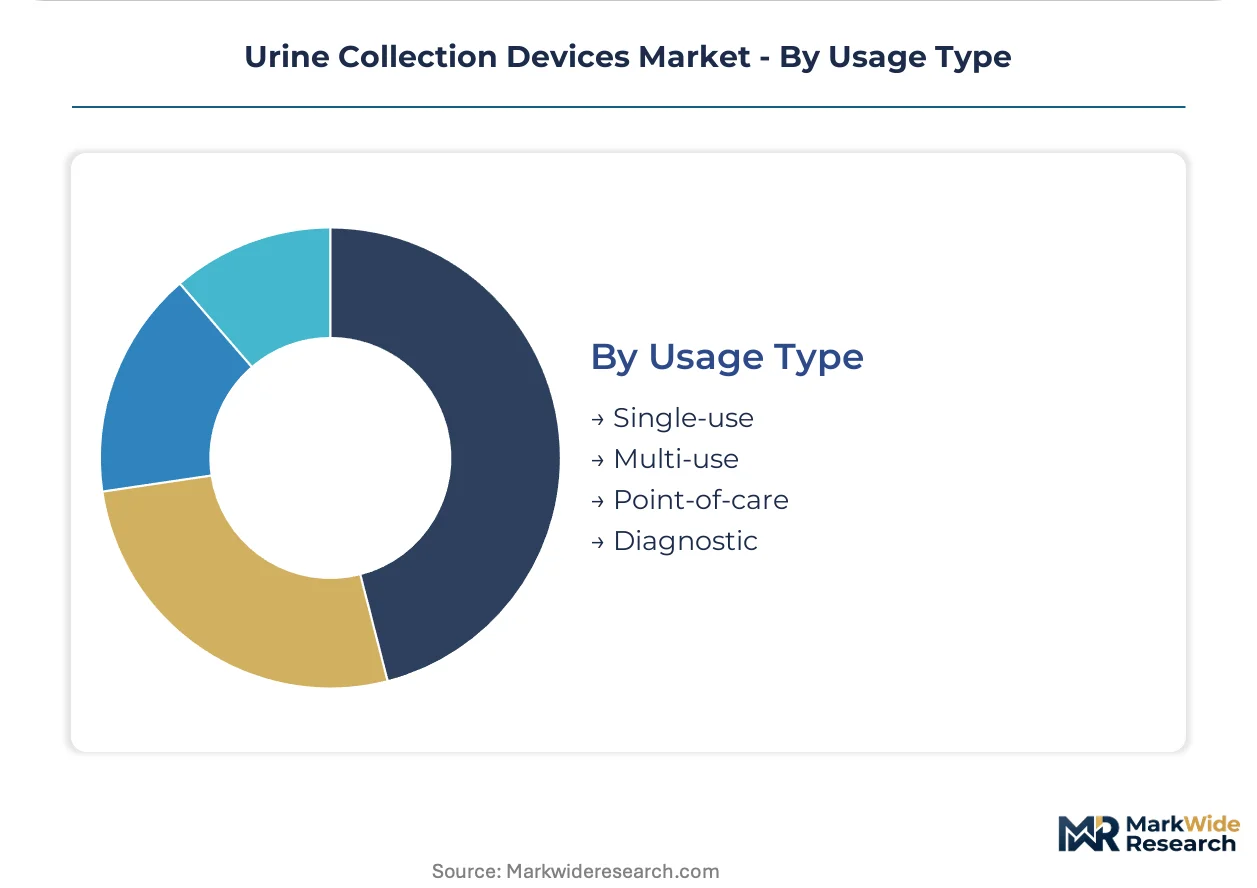
Usage Type:
Replacement frequency and capital intensity diverge sharply between single-use disposables and multi-use durable systems, reshaping manufacturer margin structures.
- Single-use:Polymer devices engineered for one-procedure utilization and regulated medical waste disposal. FDA 21 CFR Part 820 quality system regulations and Europe's MDR clinical evidence requirements extend launch timelines and compliance costs for novel polymer blends.
- Multi-use:Silicone collection systems designed for extended catheterization cycles, capturing disproportionate margin pools in long-term care where durability reduces replacement frequency and labor expenditure. Silicone material substitution is accelerating as facilities seek to cut waste streams.
- Point-of-care:Immediate diagnostic sampling configurations without laboratory transport.
- Diagnostic:Specimen collection optimized for laboratory analysis workflows and chain-of-custody documentation.
Single-use systems absorb most production throughput. Multi-use configurations are expanding most quickly as sustainability pressures and labor cost containment reshape long-term catheterization economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement networks anchor the highest concentration of closed-system urine collection device utilization, with acute care facilities mandating anti-reflux valve configurations as baseline equipment.
United States
Integrated delivery networks in the southeastern states drive hospital procurement consolidation, with health system mergers reducing independent acute care facilities by one-third over the past decade. The FDA enforces sterility and biocompatibility standards under 21 CFR Part 820 quality system regulations. Academic medical centers in Boston and the Research Triangle pilot digital volume monitoring configurations for ICU automation.
Germany
Post-acute care planners expand portable urinal prescriptions to reduce readmission rates among elderly populations recovering outside institutional settings. Europe's Medical Device Regulation forces hospital procurement departments to refresh legacy device inventories, creating replacement demand for certified closed-system bags. Industrial clusters in North Rhine-Westphalia concentrate converter capacity for medical-grade polymer extrusion.
Japan
Aging demographics accelerate home care device utilization outside institutional walls, with discharge protocols shifting toward ambulatory recovery. The Pharmaceuticals and Medical Devices Agency maintains distinct packaging and labeling requirements that shape export-ready product configurations. Manufacturing concentration in the Kanto region around Tokyo supplies domestic hospital networks with silicone-based multi-use systems.
India
Greenfield medical cities in Gujarat and Tamil Nadu lack entrenched supplier relationships, creating first-mover access for closed-system bag manufacturers. The Central Drugs Standard Control Organization regulates medical device imports and domestic production under evolving classification schemes. Hospital infrastructure buildouts in Hyderabad and Chennai attract distributor partnerships for standardized catheterization protocols.
United Kingdom
National Health Service procurement frameworks consolidate catheter and collection device purchasing under infection rate guarantee bundles. The Medicines and Healthcare products Regulatory Agency oversees MDR transition compliance for legacy devices previously cleared under the Medical Device Directive. Clinical commissioning groups in Greater Manchester and the West Midlands standardize anti-reflux valve specifications across secondary care trusts.
Urine Collection Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue antimicrobial coating convergence and digital monitoring integration. The vendor base stratifies across three maturity tiers: multinational conglomerates with captive polymer supply chains, mid-scale converters with regional distribution density, and specialized fabricators focused on silicone multi-use durability. Competitive positioning hardens around backward integration into medical-grade resin procurement, cleanroom extrusion capacity expansion, and strategic partnerships with integrated delivery networks for consignment inventory programs.
Among European-headquartered manufacturers, Coloplast A/S and B. Braun Melsungen AG exemplify distinct strategic archetypes. Coloplast A/S represents the captive supply chain model, leveraging in-house silicone sourcing to sustain margin stability across home care channels. B. Braun Melsungen AG occupies a position anchored by in-house extrusion capabilities for catheter-connected collection systems. Medline Industries, LP exemplifies the distribution-density archetype, competing through shelf space control across United States integrated delivery networks. These three entities illustrate how geographic origin and structural configuration shape competitive positioning without converging on identical capability investments.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Coloplast A/S |
| B. Braun Melsungen AG |
| Teleflex Incorporated |
| ConvaTec Group PLC |
| Hollister Incorporated |
| Medline Industries, LP |
| Cardinal Health |
| Boston Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
Silicone extrusion automation in closed-system bag manufacturing is compressing unit economics while concentrating production among converters with cleanroom capacity. This technological shift simultaneously reduces per-unit labor content and erects capital barriers that filter mid-tier competitors from premium tier participation.
Pricing Analysis
Medical-grade PVC resin pass-through from three dominant petrochemical suppliers anchors pricing volatility in the disposable tier. Three-tier pricing structure across premium silicone multi-use, standard anti-reflux PVC, and economy open-system configurations reflects certification grade and durability expectations. Pricing pressure stems from integrated delivery network procurement consolidation demanding infection-rate guarantees bundled with device costs. Home care distributors exhibit highest price sensitivity due to thin reimbursement margins, while ICU automation configurations command premium tolerance for digital monitoring integration.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty polymer converters controlling medical-grade silicone extrusion for long-term catheterization systems. Raw material flows draw from Saudi petrochemical feedstocks, Belgian specialty resin compounders, and domestic Japanese silicone manufacturers. Tariff exposure on Chinese-sourced polypropylene for portable urinals fragments production economics. Distribution runs through United States group purchasing organizations and European hospital procurement cooperatives with consignment inventory requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as infection control committees mandate anti-reflux valve configurations previously sold as premium upgrades. The demand shift toward closed-system standardization rewards manufacturers with regulatory affairs depth and cleanroom capacity.
For Market Incumbents: Anchor market position through backward integration into medical-grade resin procurement and captive silicone supply chains. Defend against catheter-free bladder monitoring substitutes by embedding digital volume sensors in ICU configurations. Prioritize MDR compliance certification as a competitive moat against mid-tier converters lacking clinical evidence capabilities.
For New Entrants and Emerging Players: Launch via direct hospital contracting in India's greenfield medical cities where supplier relationships remain unformed. Target Gujarat and Tamil Nadu infrastructure buildouts with closed-system bag configurations priced below European import equivalents. Pursue antimicrobial coating partnerships as differentiation against commodity PVC competitors.
For Investors and Strategic Acquirers: Roll-up economics work for regional converters with FDA 510(k) clearance and established GPO relationships because procurement consolidation favors vendors with logistics integration capabilities. Five-to-ten year viability hinges on MDR transition completion and silicone substitution momentum. Monitor India's CDSCO classification evolution as inflection signal for emerging market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Certification | Europe's MDR transition forces clinical evidence updates that filter non-compliant legacy manufacturers from hospital procurement. |
| Antimicrobial Coating Integration | Silver-ion surface treatments merge with silicone extrusion to command infection-control premiums in long-term catheterization. |
| Digital Volume Monitoring Development | Electronic flow sensors automate ICU urine output tracking for early sepsis detection and reduced nursing charting burden. |
| India Distribution Partnership | Greenfield medical cities in Gujarat and Tamil Nadu lack entrenched supplier relationships, creating first-mover access. |
| Silicone Supply Chain Captivity | In-house polymer sourcing sustains margin stability against PVC resin volatility and specialty feedstock concentration. |
Study Parameters
Multiple input streams — hospital procurement database analysis, GPO contract reviews, regulatory filing examination, and clinician workflow observation — were reconciled to construct demand estimates. Primary interviews with biomedical engineers, hospital purchasing committee members, infection control officers, and home care discharge planners were validated against secondary sources including FDA 510(k) clearances, EUDAMED registration data, CMS Medicare reimbursement schedules, and Japanese MHLW device listings. Bottom-up unit demand modeling and top-down market sizing were triangulated to constrain variance.
Data-stream reconciliation across product type, material chemistry, end-user channel, and usage frequency dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented volume trajectories weighted by price tier evolution and regional reimbursement dynamics. Forecast inputs incorporated MDR compliance deadline impacts, silicone substitution elasticity in long-term care, and India's hospital infrastructure buildout pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence acceleration or catheter-free monitoring technology breakthroughs. Projections reflect assumptions regarding infection control protocol standardization and polymer feedstock price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
UHD Surgical Display Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Soft Tissue Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Nasal Implant Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Pelvic Floor Stimulators Market