
 Spinal Thoracolumbar Implants Market | 2026-2036
Spinal Thoracolumbar Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Thoracolumbar Implants Market Outlook
Ambulatory surgical centers is pivoting toward complex thoracolumbar fusion procedures once confined to inpatient settings, shifting capital allocation and surgeon training priorities. Medtronic leverages its integrated navigation and implant ecosystems to capture these outpatient migrations. DePuy Synthes sustains broad hospital contracting power through scale manufacturing of posterior fixation systems. Stryker Corporation differentiates via its proprietary 3D-printed titanium interbody platforms that reduce subsidence rates.
Spinal thoracolumbar implants are load-bearing orthopedic devices, typically manufactured from titanium alloys, polyetheretherketone (PEEK), or bioactive glass composites, designed to restore vertebral column stability through pedicle screw-rod constructs or interbody fusion cages with defined yield strengths exceeding 900 MPa. Their primary commercial purpose is to enable spinal fusion while preserving sagittal balance and neural decompression in degenerative or traumatic pathologies. Titanium screw-rod systems dominate procedural volume due to proven osseointegration and modulus-matching with cortical bone, though PEEK interbody cages command premium positioning in deformity correction cases where radiolucency aids fusion assessment. Bioactive glass variants represent the fastest-expanding material niche, driven by osteostimulative properties that reduce pseudarthrosis risk in compromised bone.
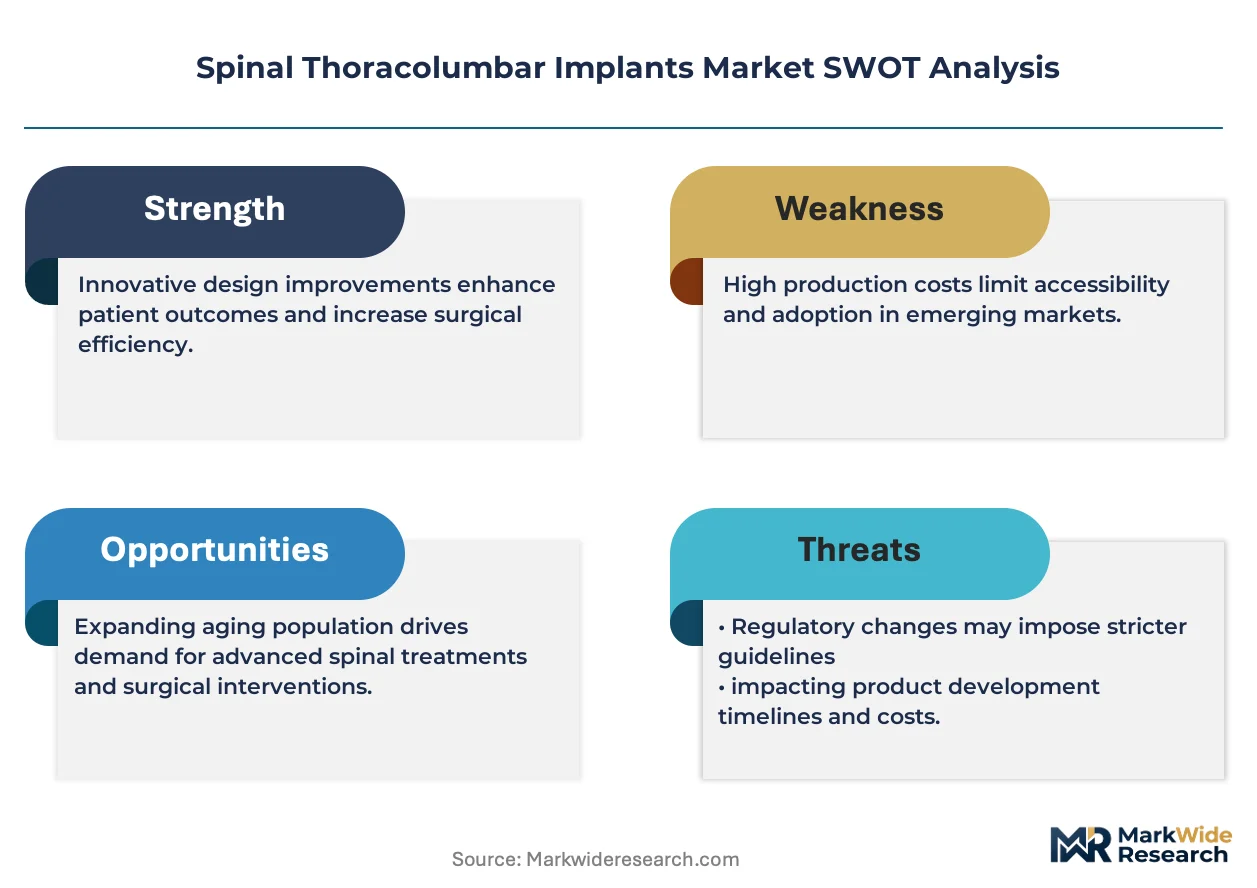
FDA 510(k) predicates and EU MDR technical documentation requirements are elevating clinical evidence thresholds for new thoracolumbar implant introductions, extending development timelines and favoring incumbents with established safety databases. Japan's PMDA and China's NMPA impose additional biocompatibility and mechanical testing protocols that filter smaller manufacturers from multi-regional commercialization. Stakeholders must monitor evolving reimbursement bundling for outpatient spinal fusion and anticipate how health technology assessment bodies in Germany and France will weight long-term implant survival data against initial procedural costs.
Market Dynamics
The migration of complex thoracolumbar fusion procedures into ambulatory surgical centers is compressing traditional hospital revenue streams while forcing manufacturers to reconfigure implant portfolios for same-day discharge protocols. This outpatient pivot demands smaller instrumentation sets, streamlined sterile processing compatibility, and surgeon training programs that accelerate procedural competency outside academic medical centers.
Growth Catalysts
- EU MDR Technical Documentation:Elevated clinical evidence requirements for predicate device comparisons are filtering smaller competitors and consolidating procurement decisions around established safety databases.
- 3D-Printed Titanium Interbody Platforms:Additive manufacturing enables patient-specific cage geometries with optimized porosity profiles that accelerate osseointegration timelines in deformity correction cases.
- Germany's Hospital Procurement Consortia:Centralized purchasing power across university hospitals and municipal clinic networks favors suppliers with comprehensive posterior fixation and interbody fusion portfolios.
Market Restraints
- Titanium Alloy Input Volatility:Sponge titanium prices fluctuate with aerospace sector demand cycles, compressing gross margins on screw-rod systems that constitute procedural volume anchors.
- FDA 510(k) Predicate Narrowing:Substantial equivalence pathways now require closer technological similarity to cleared devices, extending development timelines for novel surface modifications or material substitutions.
- PEEK Radiolucency Limitations:Polyetheretherketone cages generate imaging artifacts that complicate fusion assessment, prompting some payers to restrict reimbursement for standalone interbody procedures without supplemental fixation.
Strategic Opportunities
- Japan's Aging Surgical Population:PMDA accelerated review pathways for osteostimulative implants address elevated pseudarthrosis risk in osteoporotic vertebral bodies, creating premium positioning for bioactive glass composite cages.
- Navigation-Robotic Convergence:Integration of intraoperative imaging with autonomous screw placement is reducing fluoroscopy exposure and expanding eligible patient populations for minimally invasive approaches.
- France's HTA Weighting Shift:HAS evaluation frameworks are incorporating ten-year implant survival data into reimbursement decisions, rewarding manufacturers with prospective registry infrastructure.
Industry Challenges
- Biomechanical Testing Standardization:ISO 12189 vertebral body replacement test methods vary across notified body interpretations, creating compliance fragmentation for multi-regional submissions.
- Surgeon Training Pipeline Constraints:Fellowship programs produce insufficient complex deformity specialists to match ASC expansion timelines, forcing device companies to subsidize procedural education directly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Thoracolumbar Implants Market |
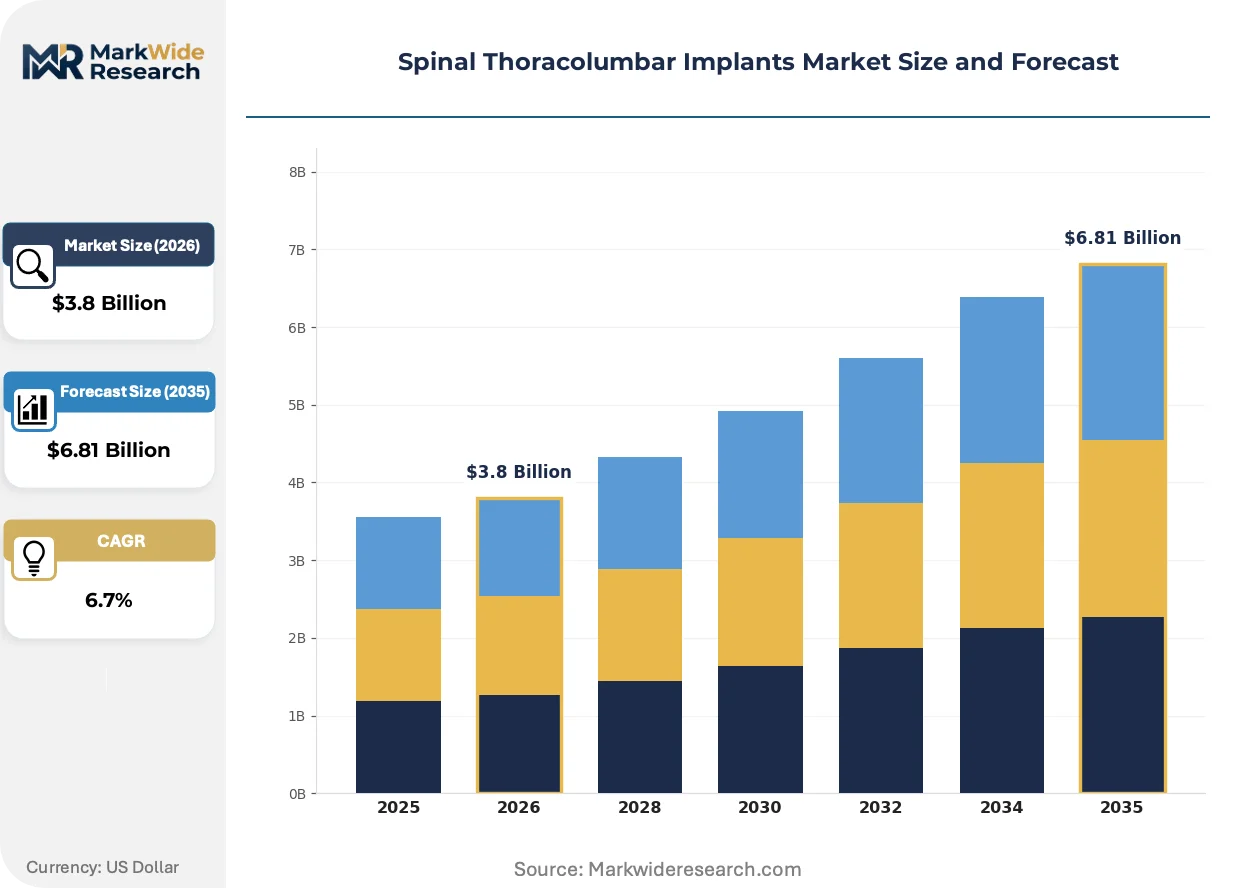
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screws, Rods, Plates, Interbody Cages Material: Titanium, Stainless Steel, PEEK, Bioactive Glass Application: Deformity Correction, Fracture Stabilization, Disc Degeneration, Tumor Treatment End User: Hospitals, Surgical Centers, Orthopedic Clinics, Rehabilitation Facilities |
| Companies Covered | Medtronic, DePuy Synthes, Stryker Corporation, Zimmer Biomet, Globus Medical, NuVasive, B. Braun Melsungen AG, Orthofix Medical, Alphatec Spine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Thoracolumbar Implants Market Strategic Shifts
Digital surgical planning and patient-specific instrumentation are compressing operative times while reducing revision rates through preoperative alignment optimization. These capabilities are redefing competitive differentiation beyond material science toward integrated procedural ecosystems.
Modular pedicle screw systems with interchangeable tulip heads and extension rods are modularizing inventory management for ambulatory surgical centers. Facilities in Texas and Florida are adopting these platforms to reduce sterile processing costs and case cart complexity. The technology is modularizing supplier relationships by enabling single-vendor consolidation across deformity, trauma, and degenerative indications.
EU MDR Article 10 technical documentation requirements now mandate post-market clinical follow-up protocols for all Class III spinal implants. Manufacturers must maintain active implant registries or participate in national arthroplasty databases to sustain CE marking. German notified bodies are enforcing these provisions most stringently, delaying market access for firms without established European surveillance infrastructure.
Hospital procurement committees are consolidating vendor contracts around comprehensive spine platforms that bundle implants with navigation, biologics, and capital equipment. This bundled purchasing is displacing discrete category sourcing and favoring suppliers with integrated portfolios. The shift is most pronounced in California and New York health systems where value-based care contracts penalize implant-related complications.
Spinal Thoracolumbar Implants Market Segmentation
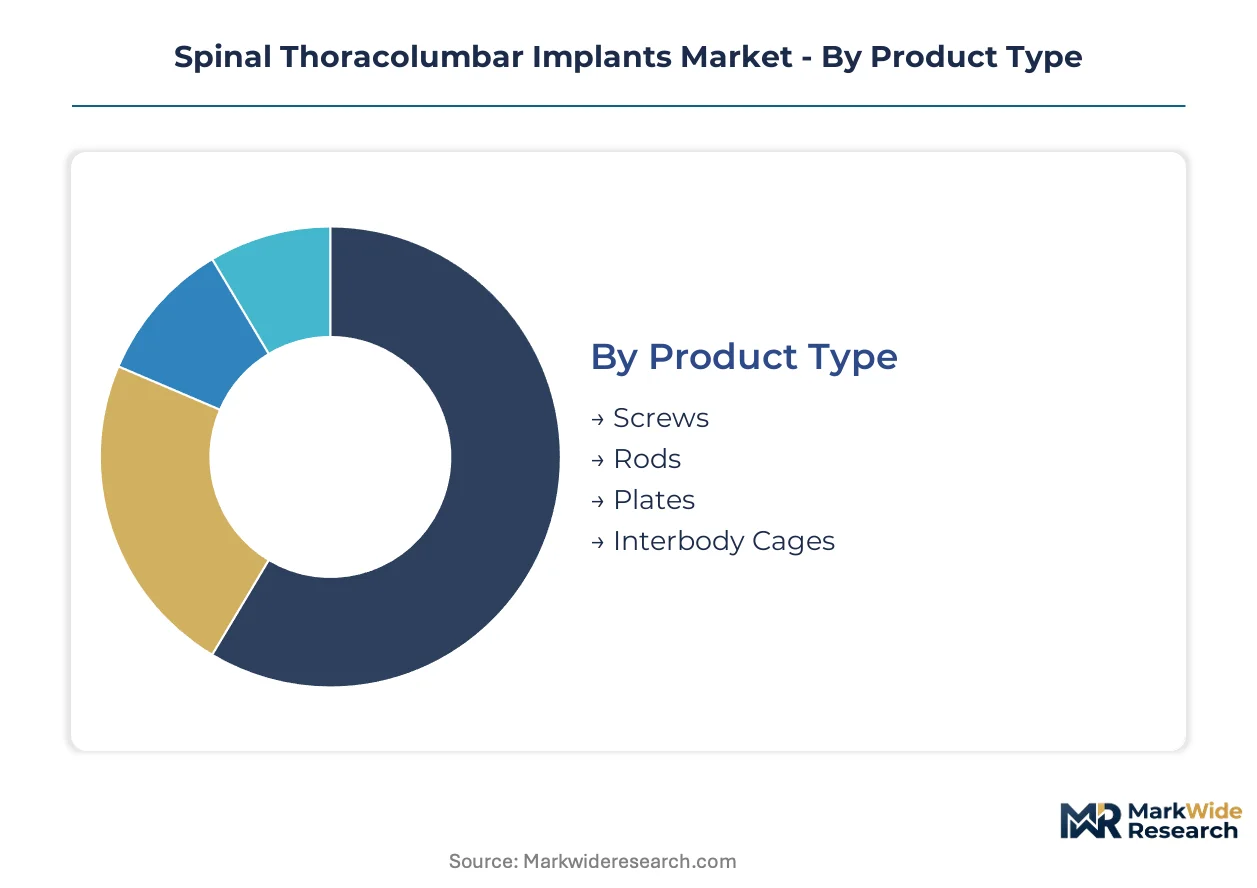
Procurement committees evaluate thoracolumbar implant portfolios across four intersecting dimensions: hardware configuration, biomaterial properties, clinical indication, and care setting economics. Each dimension carries distinct reimbursement implications and technical documentation requirements that shape supplier selection.
Product Type:
Pedicle screw-rod constructs anchor hospital contracting decisions due to their procedural volume dominance and inventory standardization benefits.
- Screws:Polyaxial and monoaxial pedicle screw designs with dual-lead thread patterns achieve cortical purchase in osteoporotic vertebral bodies. Demand concentrates in Germany's university hospital networks where procurement consortia prioritize titanium alloy systems with established CE marking under EU MDR.
- Interbody Cages:Lordotic and parallel cage geometries manufactured via additive printing or machining restore disc height and enable fusion. Growth tilts toward 3D-printed titanium platforms with optimized porosity profiles that accelerate osseointegration in deformity correction cases.
- Rods:Cobalt-chrome and titanium alloy rods with pre-bent anatomical contours maintain sagittal alignment across multi-level constructs. California health systems favor cobalt-chrome for its superior fatigue resistance in long-segment fusions.
- Plates:Anterior thoracolumbar plating systems provide rigid fixation for corpectomy defects and trauma stabilization. Japan's PMDA maintains distinct mechanical testing protocols that filter smaller manufacturers from anterior column device commercialization.
Volume sits with pedicle screws; growth tilts toward patient-specific interbody cages.
Material:
Biocompatibility certification tiers and modulus-matching characteristics drive material selection for specific bone quality and fusion assessment requirements.
- Titanium:Ti-6Al-4V ELI and commercially pure titanium grades dominate screw-rod manufacturing due to proven osseointegration and fatigue resistance exceeding 900 MPa yield strength. Germany's hospital procurement consortia mandate titanium-interbody systems with established reimbursement codes.
- PEEK:Radiolucent polyetheretherketone cages enable postoperative fusion assessment without metal artifact interference. France's HAS evaluation frameworks incorporate PEEK cage survival data into reimbursement decisions for standalone interbody procedures.
- Stainless Steel:316LVM austenitic stainless steel persists in cost-sensitive trauma applications and temporary external fixation. Indian orthopedic clinics leverage stainless steel for budget-constrained fracture stabilization cases.
- Bioactive Glass:Silicate-based composites with osteostimulative ion release kinetics represent the fastest-expanding material niche. Japan's aging surgical population and PMDA accelerated review pathways create premium positioning for bioactive glass cages in osteoporotic vertebral bodies.
Revenue concentrates in titanium alloys; steepest expansion trajectory belongs to bioactive glass composites.
Application:
Reimbursement bundling complexity and surgical invasiveness stratify demand across degenerative, traumatic, and oncologic indications.
- Disc Degeneration:Interbody fusion and motion-preserving stabilization address spondylosis and disc herniation in the aging population. Texas and Florida ambulatory surgical centers are expanding lumbar fusion capabilities for degenerative indications previously confined to inpatient settings.
- Deformity Correction:Pedicle subtraction osteotomy and multi-level constructs restore sagittal balance in adult spinal deformity. Academic medical centers in New York and California maintain concentrated deformity case volumes requiring specialized implant inventories.
- Fracture Stabilization:Short-segment fixation and percutaneous screw placement stabilize traumatic vertebral body fractures. Level I trauma centers prioritize expedited instrumentation sets for polytrauma protocols.
- Tumor Treatment:Corpectomy cages and anterior column reconstruction enable en bloc resection and metastatic disease stabilization. Comprehensive cancer centers require integrated navigation and implant ecosystems for complex oncologic spine surgery.
Procedure volume anchors in disc degeneration; deformity correction commands premium pricing tiers.
End User:
Capital equipment integration and sterile processing infrastructure differentiate procurement requirements across care settings.
- Hospitals:Academic medical centers and community hospitals maintain comprehensive spine programs with navigation, robotic, and biologics integration. Bundled purchasing in California and New York health systems penalizes implant-related complications through value-based care contracts.
- Surgical Centers:Ambulatory facilities in Texas and Florida are pivoting toward complex thoracolumbar fusion with streamlined instrumentation sets and same-day discharge protocols. Modular pedicle screw systems reduce sterile processing costs and case cart complexity.
- Orthopedic Clinics:Specialist practices concentrate on diagnostic workup and postoperative rehabilitation rather than implant-intensive surgery. Clinics in Germany's municipal networks refer complex fusion cases to university hospitals.
- Rehabilitation Facilities:Post-acute care centers manage non-operative spinal conditions and fusion recovery protocols. These facilities generate downstream demand for implant surveillance and pseudarthrosis screening.
Revenue concentration remains with hospitals; surgical centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of spinal thoracolumbar implants concentrates in Germany, Switzerland, and the United States, while demand absorption spreads across aging populations in Japan, Germany, and the United States with divergent reimbursement structures.
United States
Ambulatory surgical centers in Texas and Florida are expanding lumbar fusion capabilities, compressing traditional hospital revenue streams. FDA 510(k) clearance pathways are tightening predicate device comparisons for novel surface modifications. Greater Boston and the Pacific Northwest maintain concentrated academic medical center clusters for complex deformity surgery.
Germany
Hospital procurement consortia across university networks favor titanium-interbody systems with established reimbursement codes under Germany's DRG framework. EU MDR technical documentation requirements are elevating clinical evidence thresholds for new implant introductions. Bavaria's medical technology corridor anchors European manufacturing of posterior fixation systems.
Japan
PMDA accelerated review pathways for osteostimulative implants address elevated pseudarthrosis risk in the country's aging surgical population. The national health insurance system maintains distinct mechanical testing protocols that filter smaller manufacturers. Kanto region hospitals concentrate deformity correction case volumes requiring specialized implant inventories.
China
NMPA biocompatibility and mechanical testing protocols are filtering smaller manufacturers from multi-regional commercialization of thoracolumbar devices. Provincial procurement consortia are consolidating vendor contracts around domestic suppliers. Yangtze River Delta medical device clusters are expanding additive manufacturing capabilities for patient-specific interbody cages.
Switzerland
Swissmedic maintains stringent post-market surveillance requirements for Class III spinal implants that favor manufacturers with established European safety databases. The country's precision engineering ecosystem supports high-value additive manufacturing of titanium alloy constructs. Basel and Zurich anchor specialized biomechanical testing facilities serving multi-regional submissions.
Spinal Thoracolumbar Implants Market Competitive Environment
Top-tier vendors anchor hospital contracting through integrated navigation and implant ecosystems, while mid-tier specialists compete on material innovation and regional procurement relationships. The vendor base stratifies across three tiers: diversified orthopedic conglomerates with comprehensive spine portfolios, focused spine specialists with differentiated interbody platforms, and regional fabricators serving cost-sensitive trauma applications. Competitive positioning depends on M&A activity consolidating navigation-robotic capabilities and strategic partnerships bundling implants with biologics and capital equipment.
Within the diversified orthopedic tier, Medtronic and DePuy Synthes exemplify integrated platform strategies spanning navigation, robotic placement, and comprehensive implant portfolios. Stryker Corporation occupies a position emphasizing proprietary manufacturing approaches for patient-specific hardware. These three anchors represent distinct competitive archetypes: ecosystem integration at Medtronic, scale manufacturing leverage at DePuy Synthes, and additive manufacturing differentiation at Stryker.
| Leading Market Players |
|---|
| Medtronic |
| DePuy Synthes |
| Stryker Corporation |
| Zimmer Biomet |
| Globus Medical |
| NuVasive |
| B. Braun Melsungen AG |
| Orthofix Medical |
| Alphatec Spine |
| Others |
Value Chain & Pricing Dynamics
EU MDR Article 10 technical documentation mandates now gate qualified supply access and premium-tier pricing power, forcing manufacturers to maintain active implant registries or participate in national surveillance databases before commanding reimbursement premiums in German hospital procurement consortia.
Pricing Analysis
Margin tightening in standard-tier screw-rod systems reflects titanium alloy input volatility tracking aerospace demand cycles. Three-tier pricing structure across premium, standard, and economy levels differentiates by CE marking tier under EU MDR and volume scale through hospital procurement consortia. Cost-down pressure on economy-tier stainless steel trauma fixation accelerates as Indian orthopedic clinics prioritize budget-constrained fracture stabilization. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity due to same-day discharge protocol economics, while academic medical centers in New York and California absorb premium positioning for deformity correction platforms.
Supply Chain Analysis
Regional distribution centers in Bavaria's medical technology corridor, the Swiss precision engineering ecosystem around Basel and Zurich, and Yangtze River Delta medical device clusters anchor hub-and-spoke patterns for global implant fulfillment. Manufacturing draws from sponge titanium feedstock, PEEK polymer resin, and bioactive glass precursor materials. Single-source vulnerability concentrates in aerospace-qualified titanium alloy suppliers. Distribution runs through hospital procurement consortia in Germany, GPO contracts in California and New York health systems, and provincial procurement bodies in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over additive manufacturing capabilities and navigation-robotic ecosystems determines pricing power and procurement committee positioning.
For Market Incumbents: Deploy backward integration into titanium alloy feedstock and captive additive manufacturing capacity to defend against aerospace sector demand cycles compressing screw-rod margins. Consolidate navigation-robotic ecosystems through strategic partnerships bundling implants with intraoperative imaging and autonomous screw placement, neutralizing emerging entrants lacking FDA 510(k) predicate device databases.
For New Entrants and Emerging Players: PMDA accelerated review pathways in Japan open a window for bioactive glass composite cages targeting osteoporotic vertebral bodies in the country's aging surgical population. Target standalone interbody procedures in France where HAS evaluation frameworks weight ten-year implant survival data, enabling premium positioning through prospective registry infrastructure rather than scale manufacturing leverage.
For Investors and Strategic Acquirers: FDA 510(k) predicate narrowing is the leading indicator that development timeline extension will filter smaller competitors and consolidate procurement decisions around established safety databases. Focus acquisition screening on mid-tier spine specialists with differentiated 3D-printed titanium platforms and active European surveillance infrastructure, treating EU MDR technical documentation completion as the critical inflection signal for multi-regional commercialization viability.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | CE marking under EU MDR gates German hospital procurement consortia access and reimbursement code eligibility. |
| Navigation-Robotic Ecosystem Integration | Autonomous screw placement reduces fluoroscopy exposure and expands minimally invasive eligible populations. |
| Additive Manufacturing Capacity Buildout | Patient-specific cage geometries with optimized porosity accelerate osseointegration timelines in deformity correction. |
| Hospital System Partnership | Bundled purchasing in California and New York penalizes implant-related complications through value-based contracts. |
| Reimbursement Strategy | Outpatient spinal fusion bundling in Texas and Florida ASCs requires streamlined instrumentation sets. |
Study Parameters
FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement records formed the secondary backbone, cross-referenced with primary interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Bottom-up and top-down triangulation validated implant volume estimates against national arthroplasty registry data and DRG reimbursement claims.
Historical trendline analysis of procedural migration from inpatient to ambulatory settings informed segmentation modeling across product type, material composition, clinical indication, and care setting economics. CAGRs were derived from elasticity-adjusted demand projections incorporating EU MDR compliance timelines and PMDA accelerated review pathway uptake. Forecast inputs included titanium alloy price indices and ASC expansion rates in Texas and Florida.
Caveats apply where FDA predicate device narrowing, EU MDR notified body capacity constraints, or aerospace titanium demand spikes could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Deaver Retractor Market
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Asia Pacific Brachytherapy Devices Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
Hip Kits Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
High Intensity Focused Ultrasound (HIFU) Market
Medical Devices
Lyophilized Injectable Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Laryngoscopes Market
Medical Devices
Pen Injectors Market
Medical Devices
Sialendoscopes Market
Medical Devices
Medical Bionic Implant Market