
 Capsule Endoscope Systems Market | 2026-2036
Capsule Endoscope Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Capsule Endoscope Systems Market Analysis
Asset-light leasing models for capsule endoscopy hardware is rewriting competitive dynamics for mid-sized diagnostic chains. Medtronic leverages its installed base of GI platforms to bundle capsule services with legacy endoscopy contracts. Olympus Corporation anchors its position through in-house production of optical imaging components that reduce per-procedure supply costs. CapsoVision specializes in magnetically controlled capsule systems that differentiate its offering in hospital accounts seeking polyp detection capabilities.
Capsule endoscope systems are ingestible, disposable imaging devices typically measuring 11 mm by 26 mm, containing complementary metal-oxide semiconductor sensors, white-light emitting diodes, and wireless radio-frequency transmitters that relay 50,000 to 150,000 images to external receivers during an eight-hour gastrointestinal transit; their primary purpose is to visualize the small bowel mucosa without sedation, intubation, or radiation exposure. Wireless capsule endoscopes occupy the dominant revenue position due to established reimbursement codes and physician familiarity, while AI integration represents the fastest-expanding technology segment as machine-learning algorithms reduce interpretation burden and false-negative rates for obscure GI bleeding. Diagnostic capsules command premium pricing relative to monitoring capsules because regulatory pathways for malignancy detection claims require larger clinical validation datasets.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements shape product launch sequencing and clinical trial investment for manufacturers seeking dual-market access. Japan's PMDA and China's NMPA operate divergent standards for software-as-a-medical-device classification that complicate AI-integrated capsule submissions across Asia-Pacific jurisdictions. Stakeholders must monitor evolving cybersecurity guidance from these regulators as wireless transmission protocols become attack surfaces for healthcare ransomware campaigns.
Market Dynamics
EU MDR technical documentation requirements and FDA 510(k) clearance timelines are compressing product launch windows, forcing manufacturers to sequence clinical trials across jurisdictions while AI integration accelerates regulatory complexity for software-as-a-medical-device submissions.
Growth Catalysts
- Japan METI reimbursement policies:Favorable coverage for non-invasive diagnostic modalities accelerates hospital procurement of capsule systems in aging demographic regions.
- Wireless transmission bandwidth expansion:5G infrastructure deployment enables real-time image relay, reducing gastroenterologist read times and expanding outpatient clinic adoption.
- Small bowel visualization demand:Rising incidence of obscure GI bleeding in tertiary care centers creates procedural volume for capsule-based diagnosis.
Market Restraints
- Optical sensor supply concentration:Complementary metal-oxide semiconductor fabrication capacity clusters in East Asian foundries, exposing manufacturers to geographic supply disruption.
- EU MDR clinical evidence requirements:Expanded technical documentation for Class IIa devices extends certification timelines and inflates regulatory compliance costs.
- Conventional endoscopy substitution:Flexible endoscopy retains reimbursement advantages for upper and lower GI tract examination in insured populations.
Strategic Opportunities
- India diagnostic chain expansion:Asset-light leasing models for capsule hardware penetrate mid-tier hospital networks in tier-2 cities.
- AI-integrated polyp detection:Machine-learning algorithm convergence with magnetically controlled capsule systems enables therapeutic capability expansion beyond pure diagnosis.
- China NMPA software-as-medical-device pathway:Divergent classification standards for AI-integrated submissions create first-mover advantage for compliant manufacturers.
Industry Challenges
- GI radiologist workforce scarcity:Specialized training pipelines for capsule image interpretation lag procedural volume growth in hospital systems.
- Wireless protocol cybersecurity compliance:Evolving FDA and PMDA guidance on transmission encryption requires firmware revalidation mid-product lifecycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capsule Endoscope Systems Market |
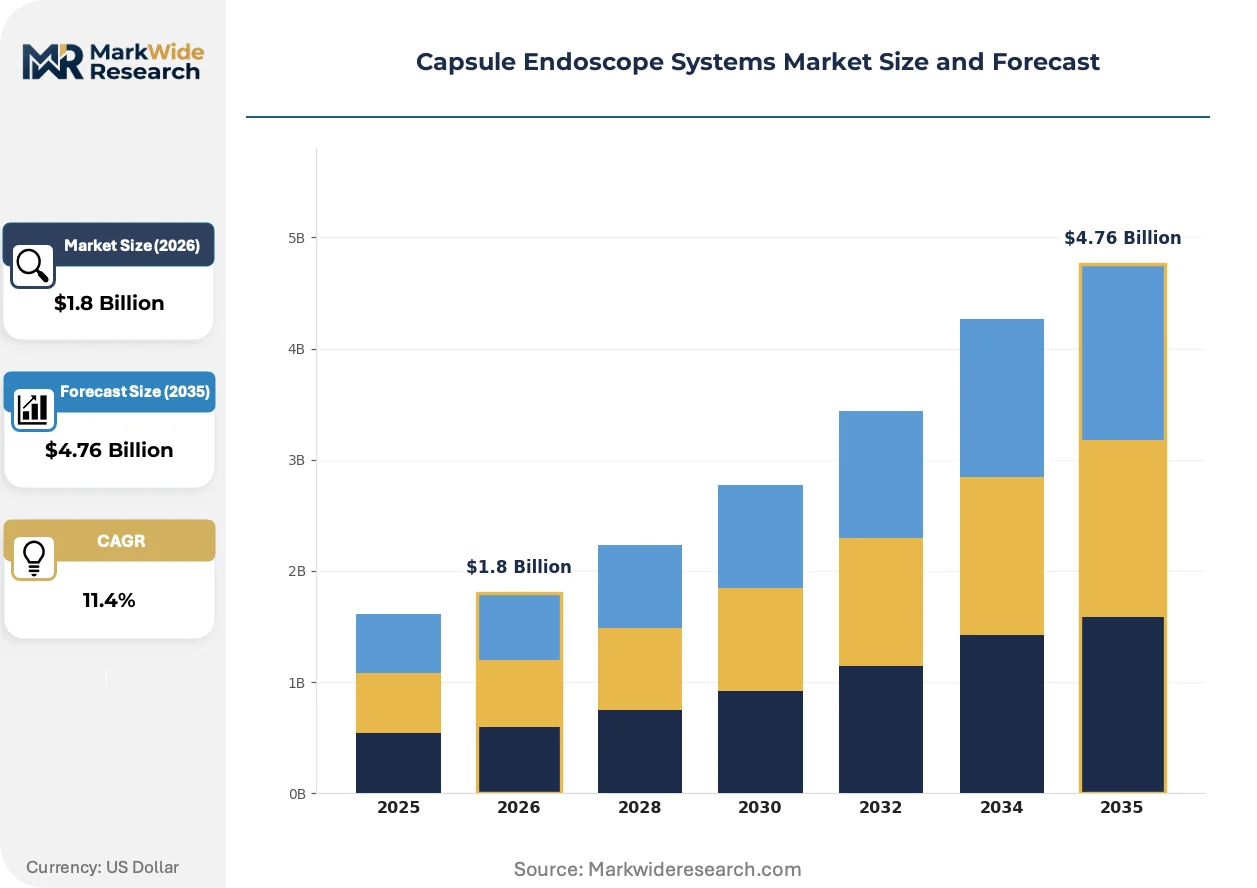
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Capsule Endoscope, Imaging Capsule, Diagnostic Capsule, Monitoring Capsule Technology: Optical Imaging, Video Capsule, Wireless Transmission, AI Integration End User: Hospitals, Clinics, Diagnostic Centers, Research Facilities Application: Gastrointestinal Examination, Capsule Polypectomy, Malignancy Detection, Obscure GI Bleeding |
| Companies Covered | Medtronic, Olympus Corporation, CapsoVision, IntroMedic, Chongqing Jinshan Science & Technology, RF System Lab, Boston Scientific Corporation, Fujifilm Holding Corporation, Check-Cap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capsule Endoscope Systems Market Emerging Trajectories
Machine-learning integration is compressing interpretation timelines while regulatory frameworks for software-enabled devices fragment across jurisdictions, and procurement models shift toward per-procedure economics.
Magnetically controlled capsule endoscopy is hybridizing diagnostic and therapeutic functions through robotic navigation systems that enable targeted biopsy and polyp detection. Tertiary hospitals in Germany and Japan are piloting these systems for small bowel examination. This convergence is hybridizing the traditional boundary between screening and interventional gastroenterology, forcing manufacturers to validate combined claims.
EU MDR Article 10 post-market surveillance requirements mandate systematic collection of clinical follow-up data for capsule devices with malignancy detection indications. Manufacturers must establish quality management systems for proactive safety monitoring. Diagnostic capsule categories face the steepest compliance burden, as these claims require larger validation datasets than monitoring-only indications.
Hospital procurement committees are unbundling capsule interpretation services from device supply, creating separate contracting for AI-assisted read platforms. Diagnostic chains in Japan and Germany now source image analysis software independently from capsule hardware. This fragmentation is most visible in metropolitan hospital systems where gastroenterology departments negotiate direct AI vendor relationships.
Capsule Endoscope Systems Market Segmentation
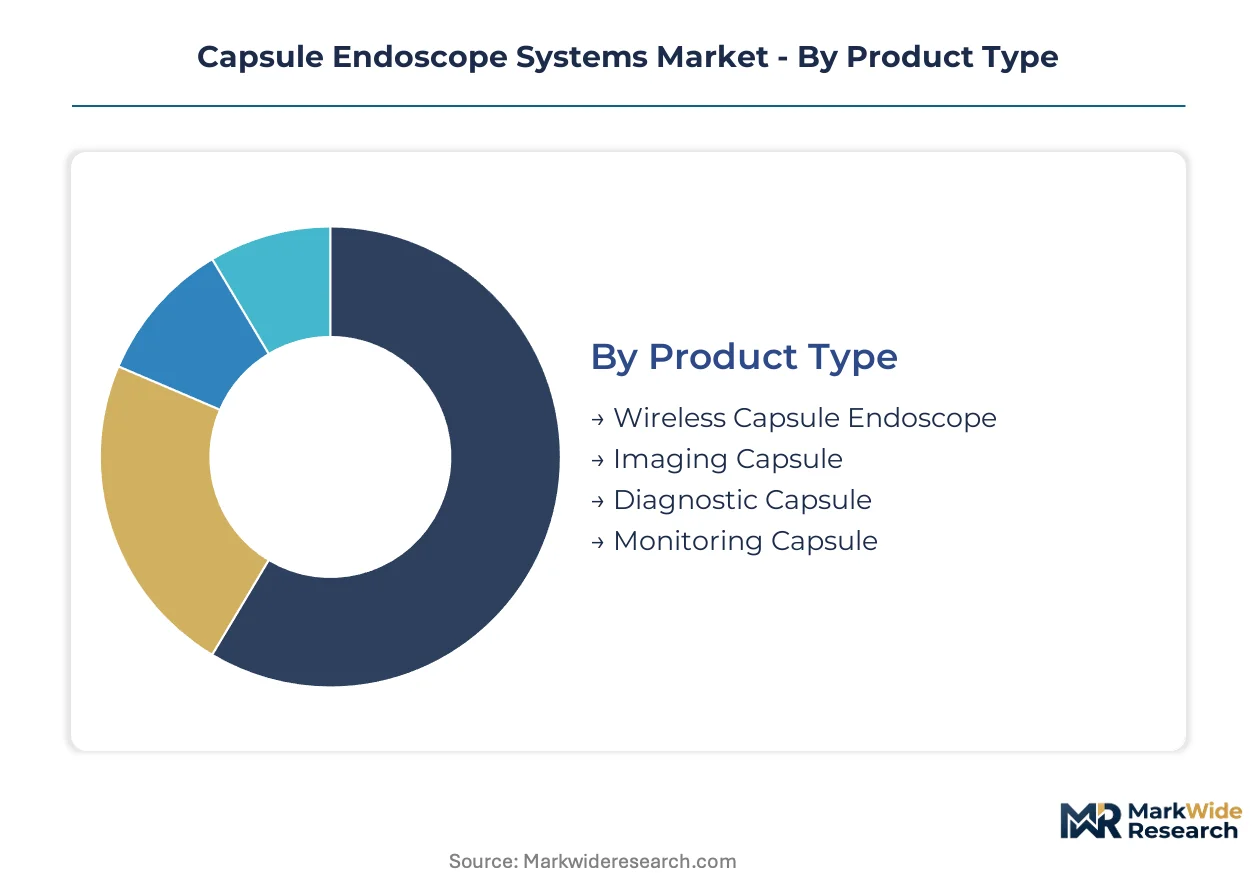
Segmentation in capsule endoscope systems reveals how technology maturity, reimbursement pathways, and clinical workflow integration determine purchasing patterns across healthcare delivery settings. Manufacturers must align product configurations with distinct regulatory requirements and end-user capabilities rather than pursuing uniform platform strategies.
Product Type:
Mature disposable hardware formats dominate hospital procurement budgets while emerging multifunction capsules reshape competitive positioning in tertiary care networks.
- Wireless Capsule Endoscope:These ingestible devices contain CMOS sensors, white-light LEDs, and RF transmitters relaying 50,000 to 150,000 images during eight-hour GI transit. German hospital systems under EU MDR compliance timelines are expanding wireless capsule programs for small bowel visualization without sedation requirements.
- Diagnostic Capsule:Purpose-built for malignancy detection claims with larger clinical validation datasets and premium pricing relative to monitoring variants. Japan's METI reimbursement policies favor these non-invasive diagnostic modalities in aging demographic regions where procedure volume concentrates.
- Imaging Capsule:Standardized optical platforms serving baseline visualization needs across outpatient clinic networks.
- Monitoring Capsule:Simplified hardware for longitudinal patient tracking with reduced regulatory burden and lower per-unit cost.
Wireless capsule endoscopes handle the majority of throughput; diagnostic capsules are the fastest mover on share.
Technology:
Cost tier separation between legacy optical platforms and premium AI-integrated systems is widening as software validation requirements fragment across FDA, PMDA, and NMPA jurisdictions.
- AI Integration:Machine-learning algorithms compress gastroenterologist read times while reducing false-negative rates for obscure GI bleeding. 5G infrastructure deployment in Japan and Germany enables real-time image relay, accelerating outpatient clinic adoption of AI-assisted interpretation platforms.
- Wireless Transmission:RF protocols and external receiver systems form the backbone of capsule-to-physician data flow. Evolving FDA and PMDA cybersecurity guidance on transmission encryption requires firmware revalidation mid-product lifecycle, complicating manufacturer maintenance commitments.
- Optical Imaging:CMOS-based capture systems with established component supply chains from East Asian foundries.
- Video Capsule:Frame-sequenced imaging formats compatible with legacy hospital PACS infrastructure.
Wireless transmission anchors current installed base; AI integration is expanding most quickly as software-as-medical-device pathways mature.
End User:
Customer type determines procurement sophistication, with hospital systems demanding bundled service contracts while diagnostic centers prioritize per-procedure economics.
- Hospitals:Tertiary care centers in Germany and Japan pilot magnetically controlled capsule systems for polyp detection and targeted biopsy capabilities. EU MDR Article 10 post-market surveillance requirements mandate systematic clinical follow-up data collection for malignancy detection indications, elevating compliance investment.
- Diagnostic Centers:Mid-sized chains in India adopt asset-light leasing models for capsule hardware, penetrating tier-2 city networks without capital-intensive procurement. These facilities increasingly unbundle capsule interpretation services from device supply, sourcing AI-assisted read platforms independently.
- Clinics:Outpatient settings with constrained specialist availability driving demand for simplified workflow integration.
- Research Facilities:Academic medical centers validating novel therapeutic applications and hybrid diagnostic-interventional protocols.
Hospitals command the highest per-procedure revenue; diagnostic centers are gaining share fastest through volume-based contracting models.
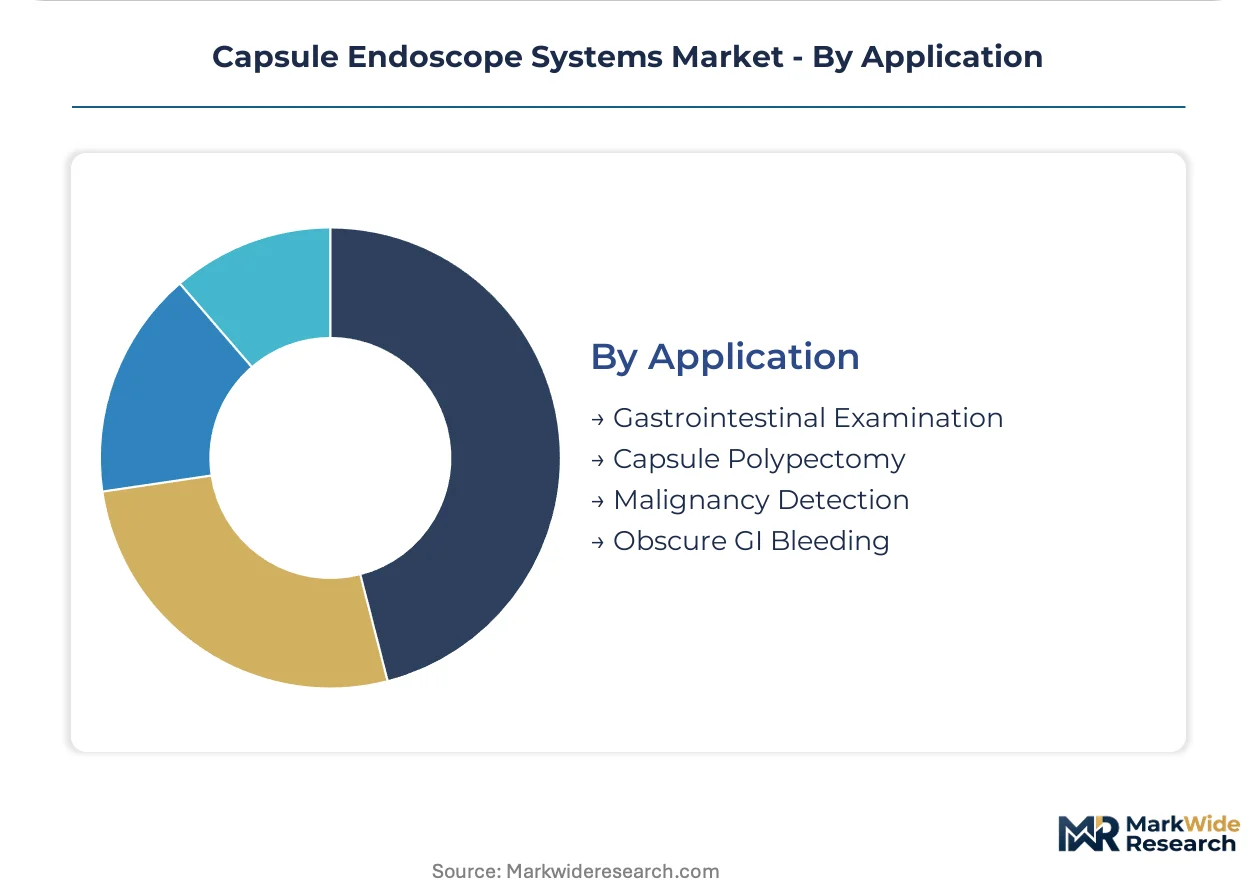
Application:
Volume concentrates in established screening categories while therapeutic boundaries blur as robotic navigation enables polyp intervention.
- Gastrointestinal Examination:Broad-category small bowel mucosa visualization without sedation, intubation, or radiation exposure. This foundational application maintains reimbursement code stability across US Medicare and Japan's universal coverage framework.
- Obscure GI Bleeding:Rising incidence in tertiary care centers creates procedural volume for capsule-based diagnosis where conventional endoscopy fails to identify sources. Specialized training pipelines for capsule image interpretation lag volume growth, constraining workforce scalability.
- Malignancy Detection:Regulatory pathways requiring extensive clinical validation datasets for diagnostic claims.
- Capsule Polypectomy:Emerging therapeutic frontier hybridizing screening and interventional gastroenterology through magnetic control systems.
Gastrointestinal examination generates the largest procedure base; obscure GI bleeding applications are climbing the fastest as referral patterns shift toward non-invasive first-line diagnosis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany, Japan, and the United States drive the majority of premium-tier capsule system purchases, while diagnostic chains in India and China expand volume through leased hardware models.
Germany
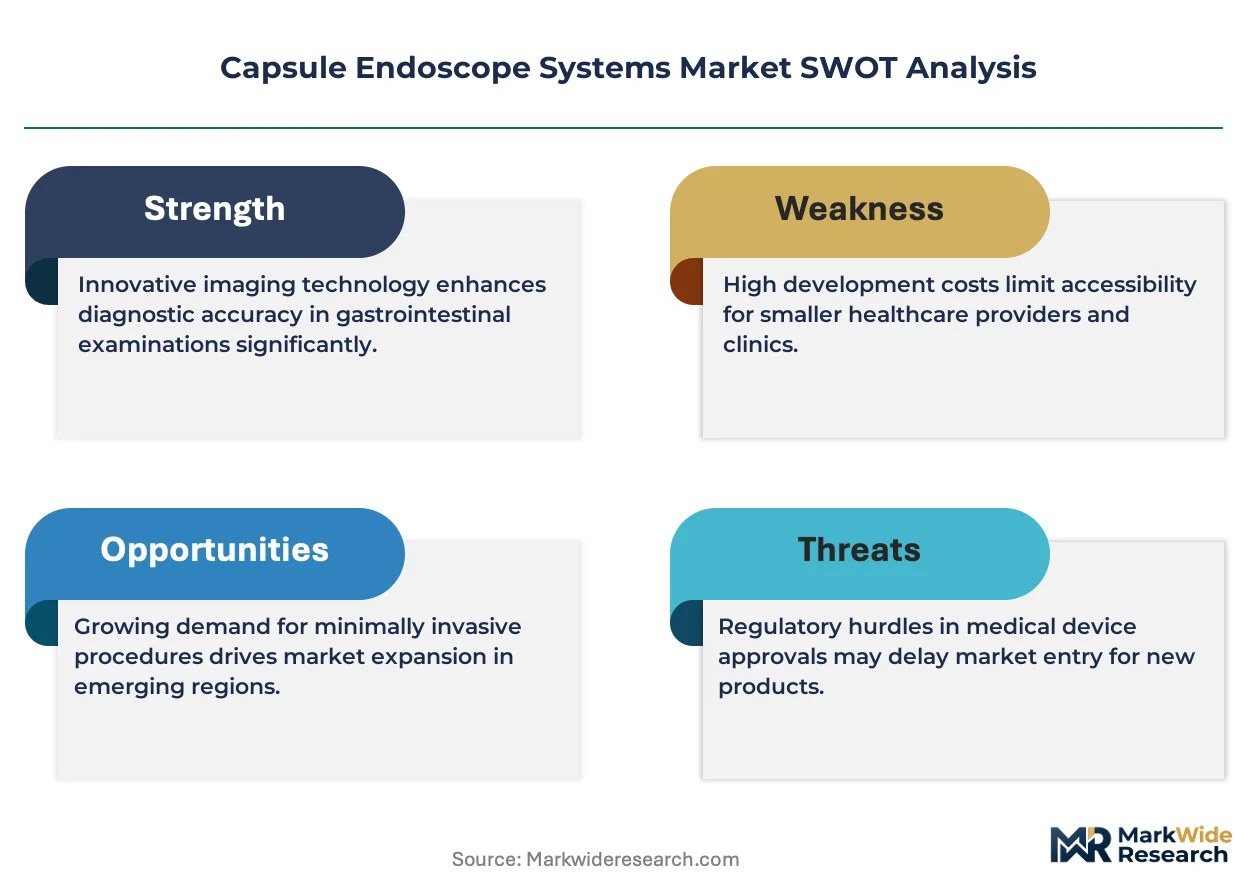
Tertiary hospitals in Bavaria and North Rhine-Westphalia are expanding magnetically controlled capsule programs for polyp detection capabilities. EU MDR Article 10 post-market surveillance requirements mandate systematic clinical follow-up data collection, extending certification timelines for malignancy detection claims. The Berlin-Brandenburg medical technology cluster hosts manufacturers navigating dual FDA and EU MDR submission sequencing.
Japan
Aging demographics in the Kanto region concentrate demand for non-invasive small bowel visualization procedures. METI reimbursement policies favor diagnostic capsules over conventional endoscopy in outpatient settings. Osaka-based hospital systems pilot AI-integrated interpretation platforms that compress gastroenterologist read times through 5G-enabled real-time image relay.
United States
Academic medical centers in Massachusetts and California validate therapeutic capsule applications including targeted biopsy capabilities. FDA 510(k) clearance timelines and evolving cybersecurity guidance on wireless transmission encryption require firmware revalidation mid-product lifecycle. The Greater Boston cluster leads clinical trials for software-as-a-medical-device classifications.
India
Mid-sized diagnostic chains in Maharashtra and Karnataka adopt asset-light leasing models to penetrate tier-2 city networks without capital-intensive procurement. The country's national pharmaceutical regulator maintains divergent standards for AI-integrated submissions compared to FDA pathways. Hyderabad-based hospital networks unbundle capsule interpretation services from device supply, sourcing AI-assisted read platforms independently.
China
Domestic manufacturers in the Yangtze River Delta region scale production of CMOS-based imaging capsules for hospital procurement committees. NMPA software-as-medical-device classification standards create first-mover advantage for compliant manufacturers submitting AI-integrated products. Shanghai medical centers pilot magnetically controlled systems that hybridize diagnostic and therapeutic gastroenterology functions.
Capsule Endoscope Systems Market Vendor Landscape
Channel-controlling players compete with product-specialist players across procurement tiers, producing a bifurcated structure where bundled service contracts dominate hospital accounts while per-procedure economics capture diagnostic chain volume. The vendor base clusters around three strategic archetypes: diversified medical technology conglomerates with installed base leverage, optical imaging specialists with captive component supply, and magnetic navigation innovators with therapeutic capability claims. Dominant competitive moves include backward integration into CMOS sensor fabrication and strategic partnerships with AI interpretation software vendors.
Among diversified medical technology conglomerates, Medtronic leverages its installed base of GI platforms to bundle capsule services, while Olympus Corporation anchors its position through in-house production of optical imaging components. CapsoVision occupies a specialist position within the magnetic navigation tier, exemplifying the product-architecture differentiation that targets hospital accounts seeking polyp detection capabilities beyond pure diagnostic visualization.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| CapsoVision |
| IntroMedic |
| Chongqing Jinshan Science & Technology |
| RF System Lab |
| Boston Scientific Corporation |
| Fujifilm Holding Corporation |
| Check-Cap |
| Others |
Supply Flow & Price Mechanics
Undercapacity in East Asian CMOS foundries is elevating component pricing leverage for optical sensor suppliers while compressing margins for capsule device assemblers negotiating long-term supply agreements with German and Japanese hospital procurement committees.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate component sourcing agreements between capsule manufacturers and East Asian foundries. Pricing stratifies across FDA-cleared diagnostic tiers, CE-marked standard systems, and economy monitoring capsules without malignancy claims. Cost compression in economy-tier hardware is intensifying because Indian diagnostic chains demand per-procedure leasing economics below depreciation recovery thresholds. Hospital systems in Japan exhibit lowest price sensitivity due to METI reimbursement guarantees, while tier-2 Indian clinics anchor the high-sensitivity segment.
Supply Chain Analysis
Upstream CMOS sensor fabrication draws from Taiwan, South Korea, and Japan, with white-light LED sourcing concentrated in Chinese component clusters. Capsule assembly rests on RF transmitter modules, optical-grade polymers, and disposable battery cells. Single-source vulnerability in advanced CMOS nodes exposes manufacturers to foundry allocation decisions during capacity crunches. Distribution runs through authorized medical device distributors serving hospital procurement committees and direct leasing arrangements with diagnostic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capsule endoscope systems are entering a cyclical recovery phase as deferred hospital capital programs restart under EU MDR compliance deadlines and Japan's aging demographics sustain procedure volume expansion.
For Market Incumbents: Entrench installed base relationships by bundling AI-assisted interpretation software with hardware service contracts, neutralizing unbundling pressure from hospital procurement committees. Deepen backward integration into optical component supply through strategic partnerships with Taiwanese foundries, securing allocation priority during semiconductor capacity crunches. Prioritize EU MDR Article 10 post-market surveillance infrastructure investment to defend diagnostic-tier pricing against emerging competitors with narrower compliance capabilities.
For New Entrants and Emerging Players: Mid-tier diagnostic chains in India's tier-2 cities represent the most penetrable entry point, where asset-light leasing models bypass capital-intensive procurement barriers that protect incumbent hospital accounts. China's NMPA software-as-medical-device pathway offers regulatory arbitrage for AI-integrated submissions ahead of FDA convergence. Pursue direct AI vendor partnerships with Japanese outpatient clinics seeking independent interpretation platforms unbundled from hardware supply.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-software interpretation layers as cloud deployment reduces on-premise infrastructure requirements, improving returns for platform-focused entrants versus hardware-heavy incumbents. Acquisition targets with magnetic navigation patents and therapeutic claim validation offer strongest five-to-ten-year positioning as diagnostic-interventional boundaries dissolve. Monitor FDA cybersecurity guidance evolution for wireless transmission protocols as an inflection signal for firmware revalidation cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Enables German hospital system contracting under Article 10 post-market surveillance mandates. |
| AI-Integrated Software Submission | Secures PMDA software-as-medical-device classification ahead of NMPA pathway divergence. |
| Magnetically Controlled System Pilot | Positions tertiary centers for polyp detection capabilities beyond pure diagnostic visualization. |
| Asset-Light Leasing Program Launch | Penetrates Indian tier-2 diagnostic chains without capital-intensive procurement requirements. |
| 5G-Enabled Real-Time Image Platform | Compresses gastroenterologist read times through Osaka-based hospital network adoption. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across gastroenterology departments, hospital procurement committees, biomedical engineering units, and diagnostic chain operations executives. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, Japan's PMDA approval records, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations across product tiers.
Calibration against historical regulatory approval timelines and reimbursement policy shifts anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology integration level, end-user procurement sophistication, and application clinical complexity. CAGRs were derived from fitted adoption curves weighted by jurisdictional reimbursement stability and workforce training pipeline capacity. Forecast inputs incorporated 5G infrastructure deployment schedules and AI algorithm validation study publication rates.
Practitioners should monitor EU MDR notified body capacity constraints and PMDA cybersecurity guidance revisions for early signals of certification timeline extension. Cross-checking against hospital procurement database trend lines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Directed Energy Based Surgical Systems Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Ultrasound Stimulator Market
Medical Devices
Vortex Mixer Market
Medical Devices
Global Therapeutic Respiratory Devices Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Americas Medical Suction Device Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Capsulotomy Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Global Wedge Pressure Catheter Market
Medical Devices
Global Abutment Implants Market