
 Global Portable Oxygen Concentrators Market | 2026-2036
Global Portable Oxygen Concentrators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Oxygen Concentrators Market Foresight
Membrane-based oxygen enrichment is reshaping concentrator miniaturization by enabling lighter units without sacrificing clinical-grade output. Inogen, Inc. leverages direct-to-consumer channels to sustain premium positioning in the home healthcare segment. Philips Respironics anchors hospital-transition partnerships across North American respiratory clinics. ResMed Inc. competes through integrated cloud connectivity that differentiates its ambulatory care offerings.
Portable oxygen concentrators are electromechanical devices that separate ambient air into concentrated oxygen streams, typically delivering 90-96% purity at flow rates from 0.5 to 3 liters per minute via pressure swing adsorption or membrane diffusion. Their primary purpose is to replace heavy compressed-gas cylinders for patients requiring supplemental oxygen during daily activities. Pulse dose technology dominates unit shipments due to battery efficiency advantages in mobile settings, while continuous flow configurations command higher price points in long-term care facilities where nocturnal oxygen delivery is non-negotiable. Home healthcare end users represent the deepest margin pool as reimbursement frameworks favor durable medical equipment provision in residential settings over institutional alternatives.
FDA 510(k) clearance pathways and EU MDR Class IIa device requirements impose clinical validation burdens that filter out undercapitalized entrants in the United States and European markets. ISO 13485 quality management standards and IEC 60601-1 electrical safety protocols further condition design engineering investments for manufacturers targeting regulated geographies. Stakeholders must monitor how CMS oxygen reimbursement rate adjustments and NICE technology appraisals in the United Kingdom reshape profitability thresholds for pulse-dose versus continuous-flow portfolio allocations.
Market Dynamics
Post-acute care decentralization is compressing institutional oxygen delivery timelines while membrane diffusion technology enables clinical-grade output at under-five-pound form factors, fundamentally altering patient mobility economics and reimbursement calculations.
Growth Catalysts
- Aging Demographics:Japan, Germany, and the United States sustain replacement cycles through elevated COPD prevalence among populations over sixty-five. Home healthcare providers expand portable oxygen programs to capture these recurring revenue streams.
- EU MDR Class IIa Harmonization:Streamlined conformity assessment pathways accelerate market access for validated pulse-dose and continuous-flow units across twenty-seven member states.
- Membrane-Based Enrichment:Polymer membrane diffusion systems reduce compressor mass by eliminating zeolite bed requirements, enabling wearable configurations previously unattainable with pressure swing adsorption architectures.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell sourcing depends on processing capacity concentrated in East Asian chemical refineries, exposing manufacturers to input volatility and export control disruptions.
- FDA 510(k) Clinical Validation Burden:Substantial equivalence demonstrations for novel flow delivery algorithms require controlled oxygen saturation studies that filter undercapitalized entrants from the United States market.
- Compressed Gas Cylinder Substitution:Refillable liquid oxygen reservoirs retain cost advantages for stationary nocturnal therapy, limiting portable concentrator penetration in long-term care facilities with existing bulk delivery contracts.
Strategic Opportunities
- India Respiratory Infrastructure:National health mission expansion into tier-two and tier-three cities creates first-mover positioning for pulse-dose units addressing undiagnosed COPD populations.
- Cloud-Connected Remote Monitoring:Integration of cellular telemetry with pulse oximetry enables predictive maintenance and adherence tracking, differentiating ambulatory care offerings from commodity hardware.
- Japan METI Carbon Neutrality Roadmap:Medical device efficiency standards incentivize low-power concentrator designs that qualify for green procurement preferences in prefectural hospital systems.
Industry Challenges
- ISO 13485 Quality Management Implementation:Small manufacturers struggle to maintain design control documentation and supplier qualification protocols required for CE marking under notified body scrutiny.
- IEC 60601-1 Third Edition Electrical Safety Certification:Electromagnetic compatibility testing for aircraft cabin use adds twelve to eighteen months to product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Oxygen Concentrators Market |
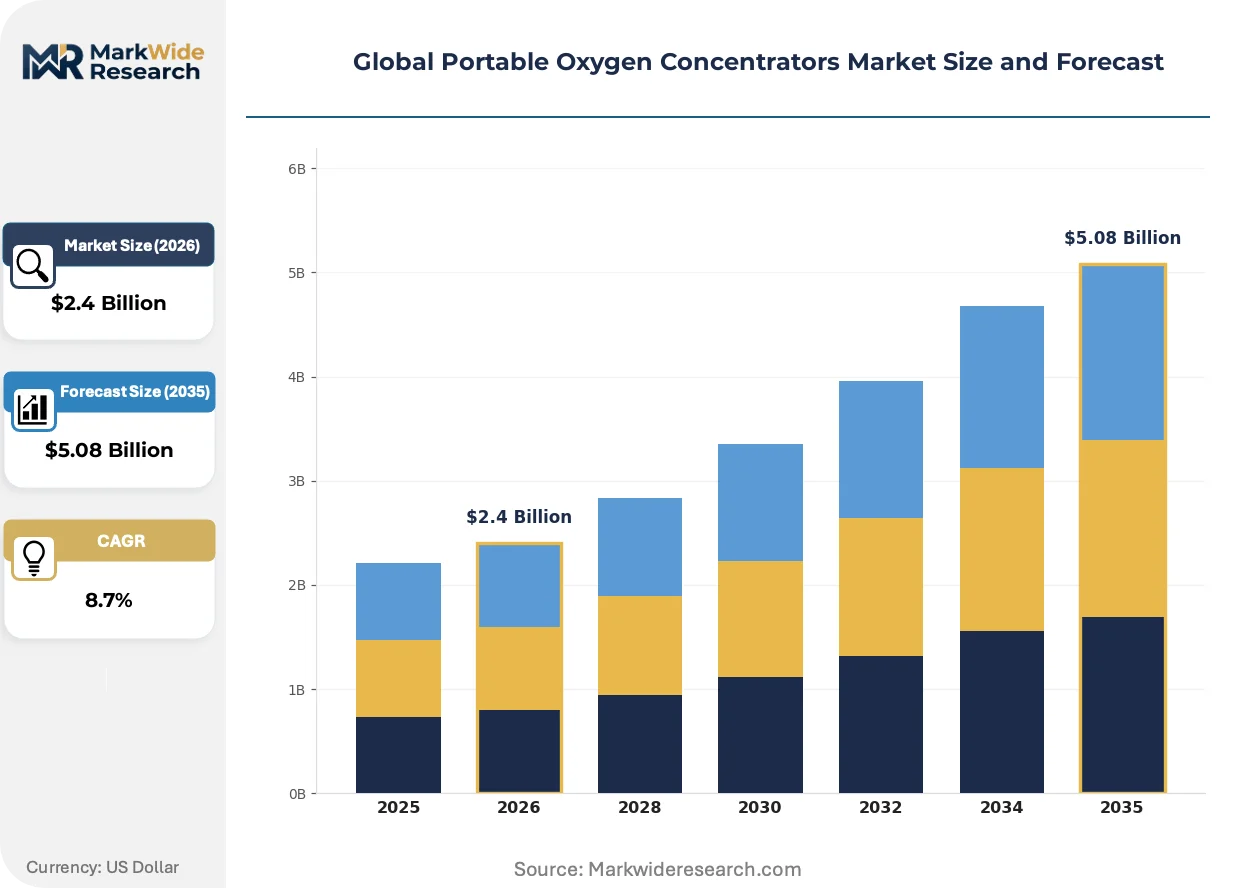
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Flow, Pulse Dose, Dual Mode, Disposable, Rechargeable Technology: Sieve Bed, Membrane, PSA, VPSA, Oxygen Enrichment Application: Chronic Obstructive Pulmonary Disorder, Pulmonary Fibrosis, Cystic Fibrosis, Neuromuscular Disorders, Post-Surgical Therapy, Sleep Apnea End User: Home Healthcare, Ambulatory Care, Long-Term Care Facilities, Respiratory Clinics, Hospice Care |
| Companies Covered | Inogen, Inc., Philips Respironics, ResMed Inc., Drive DeVilbiss Healthcare, CAIRE Inc., Invacare Corporation, Chart Industries, Inc., AirSep Corporation, Nidek Medical Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Oxygen Concentrators Market Shifts & Advancements
Portable oxygen concentrator development is pivoting toward software-defined flow modulation and predictive diagnostics, compressing the traditional hardware replacement cycle while opening recurring revenue streams through connected service layers.
Membrane-based oxygen enrichment is virtualizing the physical separation layer that historically demanded zeolite beds and pneumatic valving. Home healthcare providers in the United States and Germany are adopting these lighter configurations for active patient populations requiring eight to twelve hours of daily mobility. The technology is virtualizing component count and maintenance intervals, shifting competitive differentiation toward embedded analytics and patient adherence platforms.
The EU MDR Class IIa device classification framework is tightening clinical evidence requirements for pulse-dose delivery algorithms. Manufacturers must now submit prospective usability studies and post-market surveillance plans to notified bodies, extending regulatory timelines by six to nine months. Continuous-flow units intended for nocturnal use face heightened scrutiny of alarm reliability and power-fail oxygen backup systems.
Direct-to-consumer channel expansion is disintermediating durable medical equipment distributors that historically controlled patient onboarding and insurance documentation. In the United States, Medicare Advantage plans and commercial payers are experimenting with remote patient monitoring reimbursement codes that favor manufacturers capturing longitudinal usage data. This behavioral shift concentrates margin capture with original equipment manufacturers while compressing distributor inventory positions.
Global Portable Oxygen Concentrators Market Segmentation
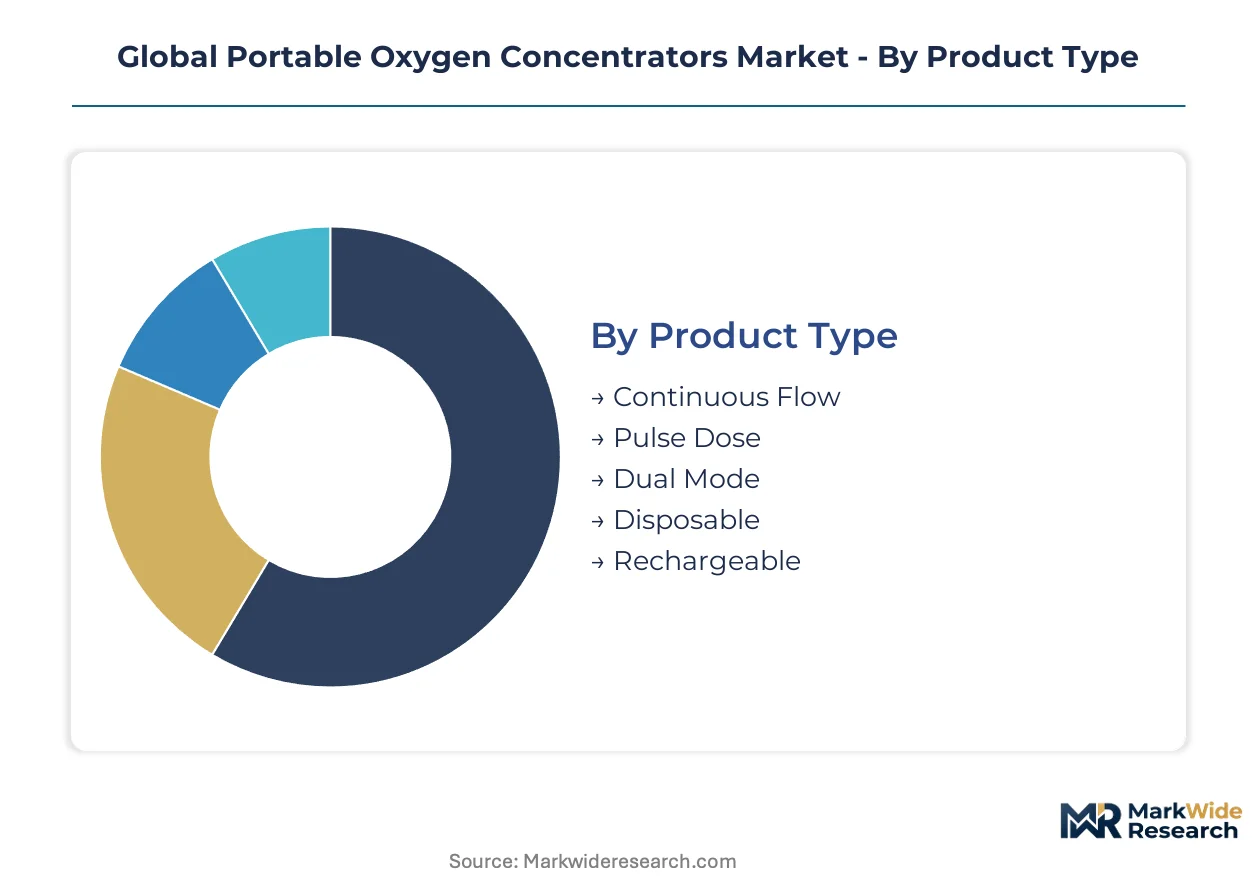
Portable oxygen concentrator manufacturers configure product portfolios across four intersecting dimensions to match reimbursement codes with clinical workflows. Technology selection determines weight and battery life. End-user channel strategy shapes margin capture and service attachment rates.
Product Type:
Cost tier stratification separates premium continuous-flow systems from lightweight pulse-dose alternatives targeting mobile patient populations.
- Pulse Dose:Delivers oxygen in bolus increments synchronized with patient inhalation, reducing battery drain by sixty to seventy percent versus continuous delivery. Medicare Advantage plans in the United States favor this configuration for ambulatory patients requiring daytime mobility outside residential settings.
- Continuous Flow:Maintains steady oxygen output independent of breathing pattern, essential for nocturnal therapy and patients with shallow respiration. Long-term care facilities in Germany specify these units for institutional contracts where power reliability trumps portability metrics.
- Dual Mode:Switches between pulse and continuous output based on activity detection algorithms.
- Disposable:Single-use concentrators for emergency deployment and disaster response stockpiles.
- Rechargeable:Swappable battery architectures extending field operation for active patient lifestyles.
Continuous Flow commands the established base. The steepest expansion runs through Pulse Dose.
Technology:
Application requirements dictate separation mechanism selection, with membrane diffusion displacing legacy pressure swing adsorption in sub-five-pound wearable configurations.
- Membrane:Polymer diffusion layers extract oxygen without zeolite beds or pneumatic valving, cutting compressor mass by forty percent. Japanese prefectural hospital systems prioritize these units under METI carbon neutrality procurement guidelines.
- PSA (Pressure Swing Adsorption):Zeolite molecular sieves alternate between pressurization and venting cycles to concentrate oxygen from ambient air. Indian national health mission tenders specify PSA architecture for reliability in tier-two city deployments with unstable power grids.
- Sieve Bed:Traditional two-bed zeolite systems dominating installed base maintenance cycles.
- VPSA (Vacuum Pressure Swing Adsorption):Lower-pressure operation reducing compressor energy consumption for stationary applications.
- Oxygen Enrichment:Generic classification covering non-cryogenic separation methods below medical-grade purity thresholds.
PSA retains the installed base. Membrane configurations are climbing the fastest as weight reduction drives replacement decisions.
Application:
Customer type segmentation aligns device specifications with disease progression patterns and reimbursement eligibility windows.
- Chronic Obstructive Pulmonary Disorder:Progressive airflow limitation requiring escalating oxygen prescriptions as FEV1 declines. Home healthcare providers in the United States structure rental programs around COPD patient life expectancy curves to maximize reimbursement capture.
- Sleep Apnea:Nocturnal oxygen desaturation often co-occurring with CPAP therapy non-compliance. German respiratory clinics prescribe portable concentrators as bridge therapy for patients failing mask adaptation protocols.
- Pulmonary Fibrosis:Interstitial lung disease with rapid oxygen dependence escalation.
- Cystic Fibrosis:Genetic mucus clearance impairment requiring high-flow oxygen during pulmonary exacerbations.
- Neuromuscular Disorders:Diaphragmatic weakness necessitating ventilator-oxygen integration.
- Post-Surgical Therapy:Temporary oxygen support following thoracic or cardiac procedures.
COPD anchors volume commitments. Sleep Apnea applications are expanding most quickly as diagnostic thresholds broaden.
End User:
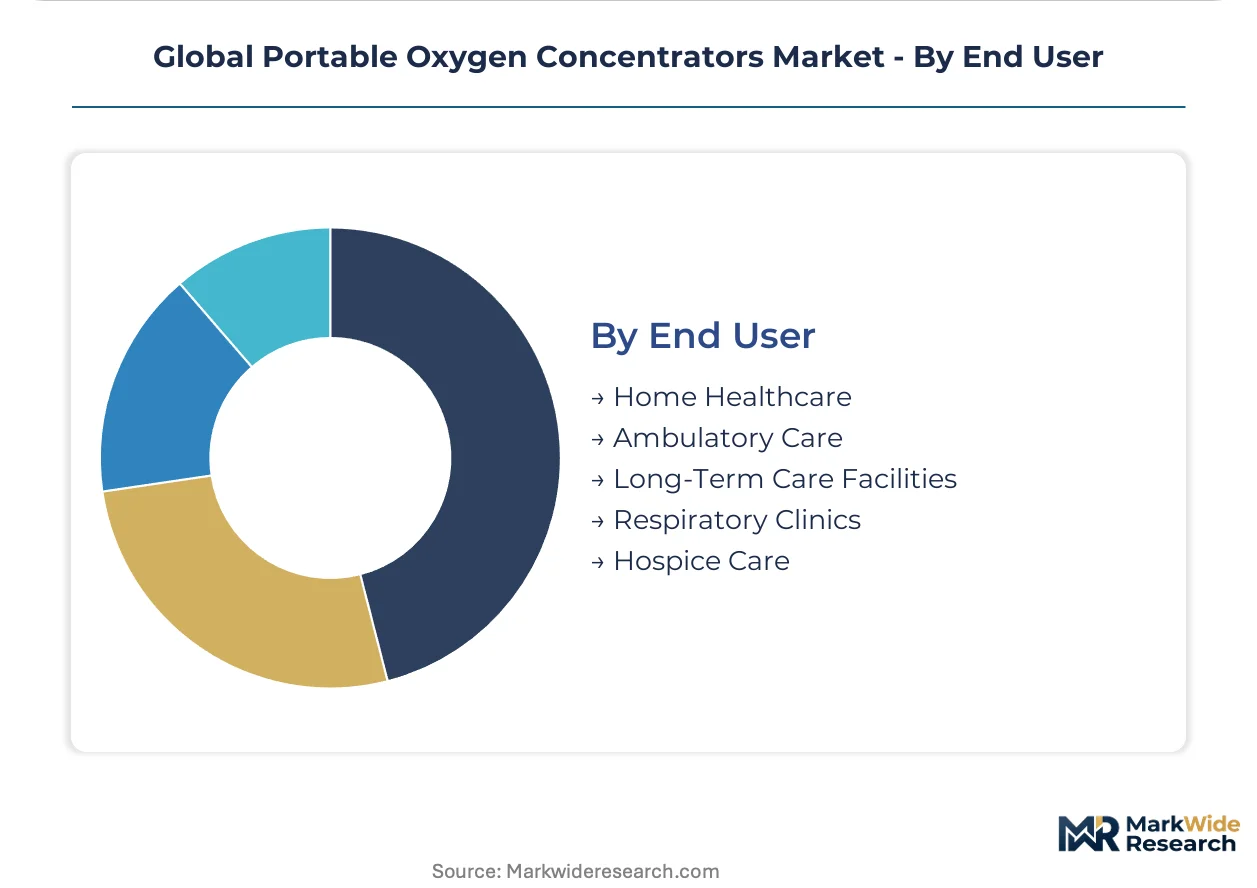
Volume concentration varies sharply by channel, with residential settings capturing recurring revenue streams unavailable to institutional purchasers.
- Home Healthcare:Durable medical equipment provision at patient residences with monthly rental billing and 24/7 clinical support hotlines. United States Medicare Part B reimbursement rates favor this channel over hospital-based oxygen delivery.
- Ambulatory Care:Outpatient respiratory clinics managing post-acute transitions with remote monitoring integration. Japanese home-visit nursing stations deploy lightweight concentrators for community-based COPD management.
- Long-Term Care Facilities:Nursing homes with bulk oxygen contracts limiting portable concentrator penetration.
- Respiratory Clinics:Specialist practices conducting six-minute walk tests and oxygen titration studies.
- Hospice Care:Palliative oxygen for terminal dyspnea with emphasis on silent operation and family caregiver simplicity.
Home Healthcare dominates margin capture. Ambulatory Care channels are gaining share fastest as post-acute decentralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export membrane-based concentrators to Japanese prefectural hospital systems under METI carbon neutrality procurement guidelines, establishing a high-value trade corridor between precision engineering clusters and green healthcare infrastructure.
United States
Medicare Part B reimbursement rates and Medicare Advantage plan expansion sustain replacement cycles for pulse-dose units among ambulatory COPD patients. FDA 510(k) clearance pathways filter undercapitalized entrants through substantial equivalence requirements for novel flow algorithms. Minneapolis and San Diego anchor respiratory device engineering clusters where home healthcare providers partner with manufacturers on direct-to-consumer distribution models.
Germany
Long-term care facilities specify continuous-flow configurations for institutional contracts where power reliability outweighs portability metrics. EU MDR Class IIa harmonization accelerates conformity assessment across twenty-seven member states for validated pulse-dose units. North Rhine-Westphalia hosts engineering centers developing low-power concentrator designs that align with EU Green Deal medical device efficiency standards.
Japan
Aging demographics above age sixty-five drive concentrated demand for lightweight wearable configurations enabling eight to twelve hours of daily mobility. METI carbon neutrality roadmaps incentivize low-power designs qualifying for green procurement preferences in prefectural hospital systems. Kanto region manufacturers integrate polymer membrane diffusion systems that eliminate zeolite bed mass for sub-five-pound form factors.
India
National health mission expansion into tier-two and tier-three cities creates first-mover positioning for pulse-dose units addressing undiagnosed COPD populations. CDSCO medical device regulations and BIS quality standards condition market access for imported and domestically manufactured concentrators. Gujarat and Maharashtra industrial corridors host assembly operations for PSA-architecture units specified in government tenders requiring reliability under unstable power grid conditions.
Global Portable Oxygen Concentrators Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where durable medical equipment distributors face disintermediation from direct-to-consumer models. Three archetypes dominate: integrated respiratory conglomerates with hospital-transition partnerships, pure-play portable oxygen specialists leveraging cloud connectivity differentiation, and diversified medical device manufacturers with captive home healthcare service networks. Competitive moves concentrate on M&A for patient monitoring platform integration and strategic partnerships with Medicare Advantage plans for preferred device placement.
Within the integrated respiratory tier, Philips Respironics and ResMed Inc. exemplify archetypes combining hardware manufacturing with digital health infrastructure. Inogen, Inc. occupies a distinct position as a pure-play specialist emphasizing direct-to-consumer channel control. These three companies represent contrasting strategic vectors: hospital-transition anchoring, connected care platform integration, and consumer-direct margin capture.
| Leading Market Players |
|---|
| Inogen, Inc. |
| Philips Respironics |
| ResMed Inc. |
| Drive DeVilbiss Healthcare |
| CAIRE Inc. |
| Invacare Corporation |
| Chart Industries, Inc. |
| AirSep Corporation |
| Nidek Medical Products, Inc. |
| Others |
Supply & Pricing Matrix
East Asian lithium-ion cell processing capacity concentrates battery sourcing for portable oxygen concentrator manufacturers, tethering margin pools to chemical refinery output stability and export control exposure while downstream home healthcare providers capture recurring rental revenue streams insulated from input volatility.
Pricing Analysis
Membrane-based next-generation units command forty to sixty percent premiums over legacy PSA architectures, while prior-generation continuous-flow systems face cost compression from Medicare reimbursement rate adjustments. Three-tier pricing structure across premium membrane wearables, standard pulse-dose configurations, and economy fixed-flow units stratifies by weight and battery autonomy. Pricing pressure stems from CMS oxygen reimbursement compression and direct-to-consumer channel disintermediation. Hospital purchasing committees exhibit lowest price sensitivity due to total-cost-of-ownership framing, while tier-two city distributors in emerging markets demonstrate acute elasticity.
Supply Chain Analysis
Contract manufacturing for portable oxygen concentrators concentrates with Foxconn Health Technology, Jabil Healthcare, and Flex Medical in Malaysia, Mexico, and Poland facilities. Component sourcing draws from Chinese rare-earth magnet suppliers for compressor motors, Japanese polymer membrane fabricators, and South Korean lithium-ion cell pack assemblers. Single-source vulnerability runs through zeolite molecular sieve suppliers in the United States and Germany. Distribution runs through durable medical equipment rental networks in the United States and specialized respiratory device distributors in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
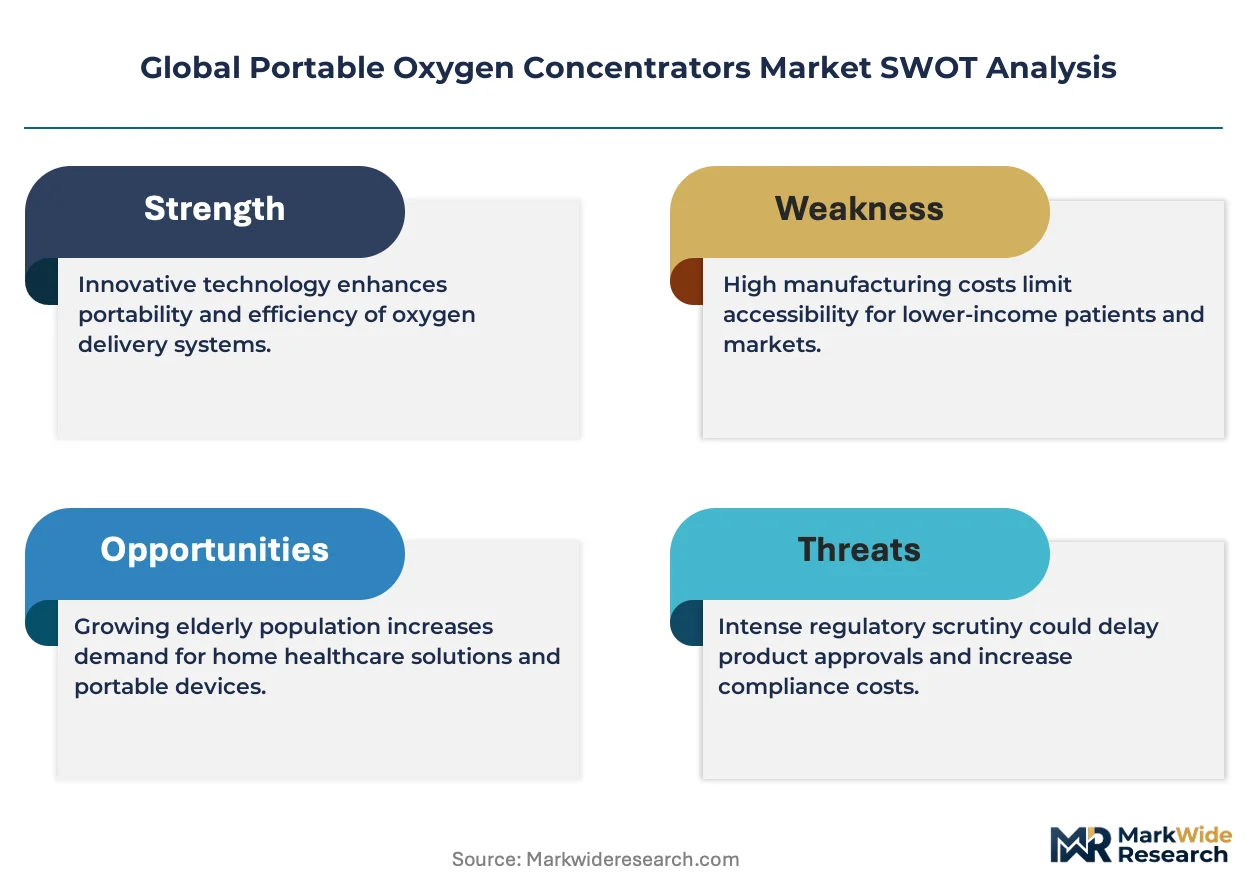
Portable oxygen concentrator manufacturing demands scarce competencies in medical-grade pneumatic engineering, FDA 510(k) clinical validation, and cloud-connected telemetry integration that few mid-cap industrials possess in combination.
For Market Incumbents: Build regulatory data moats through longitudinal post-market surveillance databases that emerging competitors cannot replicate without five-year clinical accumulation. Deepen backward integration into polymer membrane fabrication to secure weight-reduction roadmaps against Japanese materials suppliers. Counter direct-to-consumer disintermediation by capturing Medicare Advantage preferred device placement through outcomes-based contracting with payers. For New Entrants and Emerging Players: Establish a beachhead in Indian tier-two and tier-three city respiratory infrastructure where PSA-architecture reliability under unstable power grids creates first-mover positioning. Target undiagnosed COPD populations through national health mission tender participation rather than competing in saturated United States and German replacement cycles. Deploy government liaison capabilities as the primary go-to-market angle to navigate CDSCO and BIS compliance pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed durable medical equipment distributors facing margin compression from manufacturer direct-to-consumer pivots. Five-to-ten year viability hinges on cloud-connected remote monitoring platform integration rather than hardware commoditization. Watch for FDA breakthrough device designations for novel membrane diffusion architectures as inflection signals for technology-generation transitions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways filter undercapitalized entrants from United States reimbursement eligibility. |
| CE Marking Pathway | EU MDR Class IIa harmonization accelerates conformity assessment across twenty-seven member states. |
| Hospital System Partnership | Philips Respironics anchors post-acute transitions through North American respiratory clinic networks. |
| Software Companion Development | ResMed Inc. differentiates through integrated cloud connectivity and predictive maintenance analytics. |
| Reimbursement Strategy | Inogen, Inc. captures Medicare Advantage remote patient monitoring codes through direct-to-consumer channels. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and home healthcare provider operations directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up unit shipment modeling triangulated against top-down healthcare expenditure flows across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with pulse-dose versus continuous-flow technology splits, membrane versus PSA architecture migration curves, and home healthcare versus institutional channel mix constituting core segmentation dimensions. CAGRs derived from replacement cycle analysis in aging demographic clusters and reimbursement rate elasticity modeling. Forecast inputs incorporated METI carbon neutrality procurement guidelines and CDSCO medical device regulation implementation timelines.
Sensitivities concentrate around lithium-ion supply disruptions, CMS reimbursement rate adjustments, and EU MDR notified body capacity constraints. Quarterly review of FDA breakthrough device designations, Medicare Advantage plan expansion rates, and Japanese prefectural hospital green procurement awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Penile Implants Market
Medical Devices
Contraceptive Devices Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Injection Pen Market
Medical Devices
Gastric Bands Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
Neurostimulation Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
Patellar Implant Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
North America Smart Medical Devices Market