
 Global Breast Pumps Market | 2026-2036
Global Breast Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breast Pumps Market Foresight
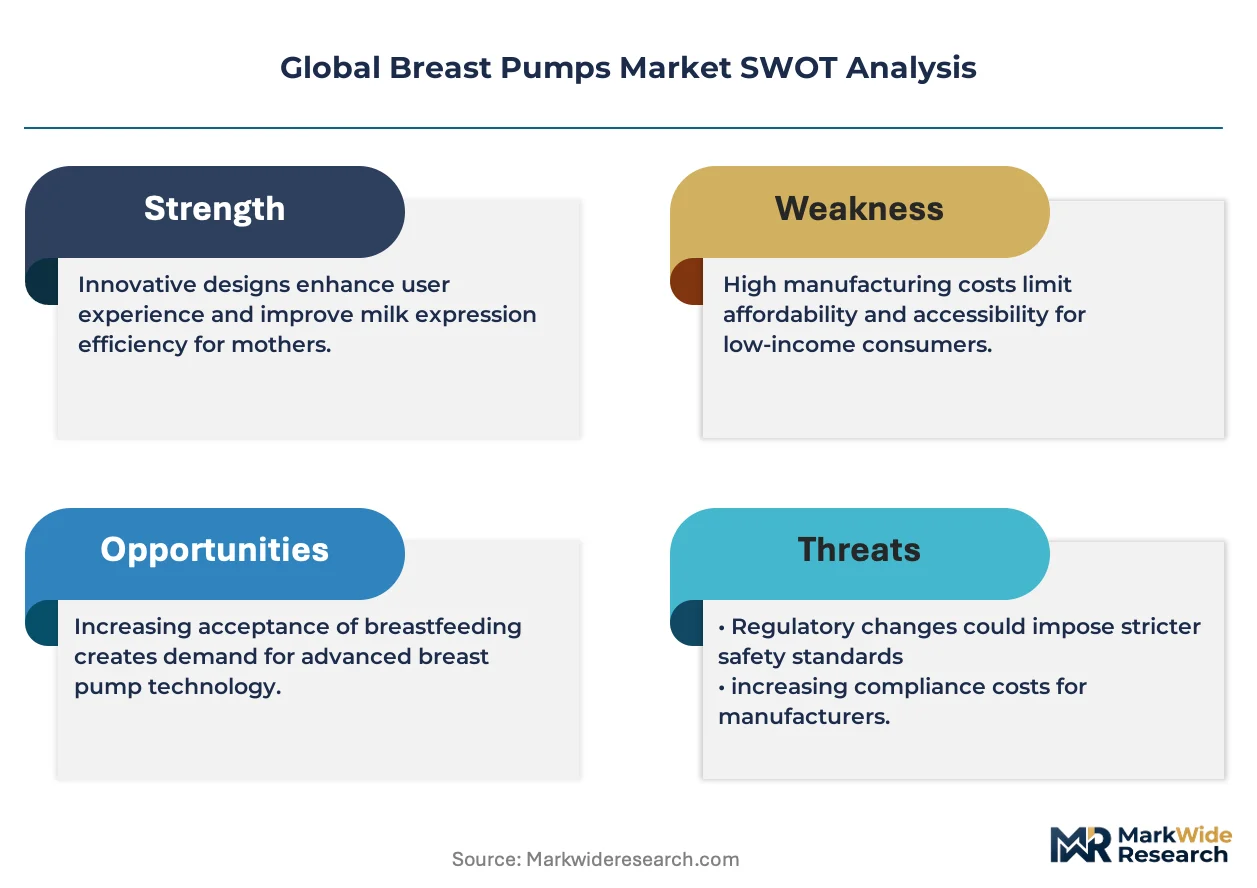
Hospital procurement channels is narrowing as group purchasing organizations consolidate supplier lists. Medela AG leverages its clinical certification to sustain premium placement in NICU contracts. Philips N.V. anchors its position through backward integration into motor and silicone component production. Elvie competes on wearable form factors that bypass traditional retail pharmacy distribution.
Breast pumps are suction-based mechanical devices that extract milk from lactating breasts, typically operating at vacuum pressures of 150-250 mmHg with cycle rates adjustable between 30-60 expressions per minute for physiological comfort and milk flow optimization. Electric pumps with closed-system technology dominate hospital procurement due to infection-control protocols, while battery-operated wearable units represent the fastest-growing margin pool as mothers prioritize mobility over stationary pumping sessions. Hospital-grade pumps retain the highest price positioning but face volume pressure from declining birth rates in several developed markets.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) Class I rules shape product design, biocompatibility testing, and post-market surveillance obligations for manufacturers seeking access to the United States and European markets. ISO 80369-7 small-bore connector standards and IEC 60601-1 electrical safety certifications further constrain component sourcing and design flexibility. Stakeholders must monitor whether emerging wearable pump formats trigger reclassification under stricter regulatory frameworks as software-controlled expression algorithms proliferate.
Market Dynamics
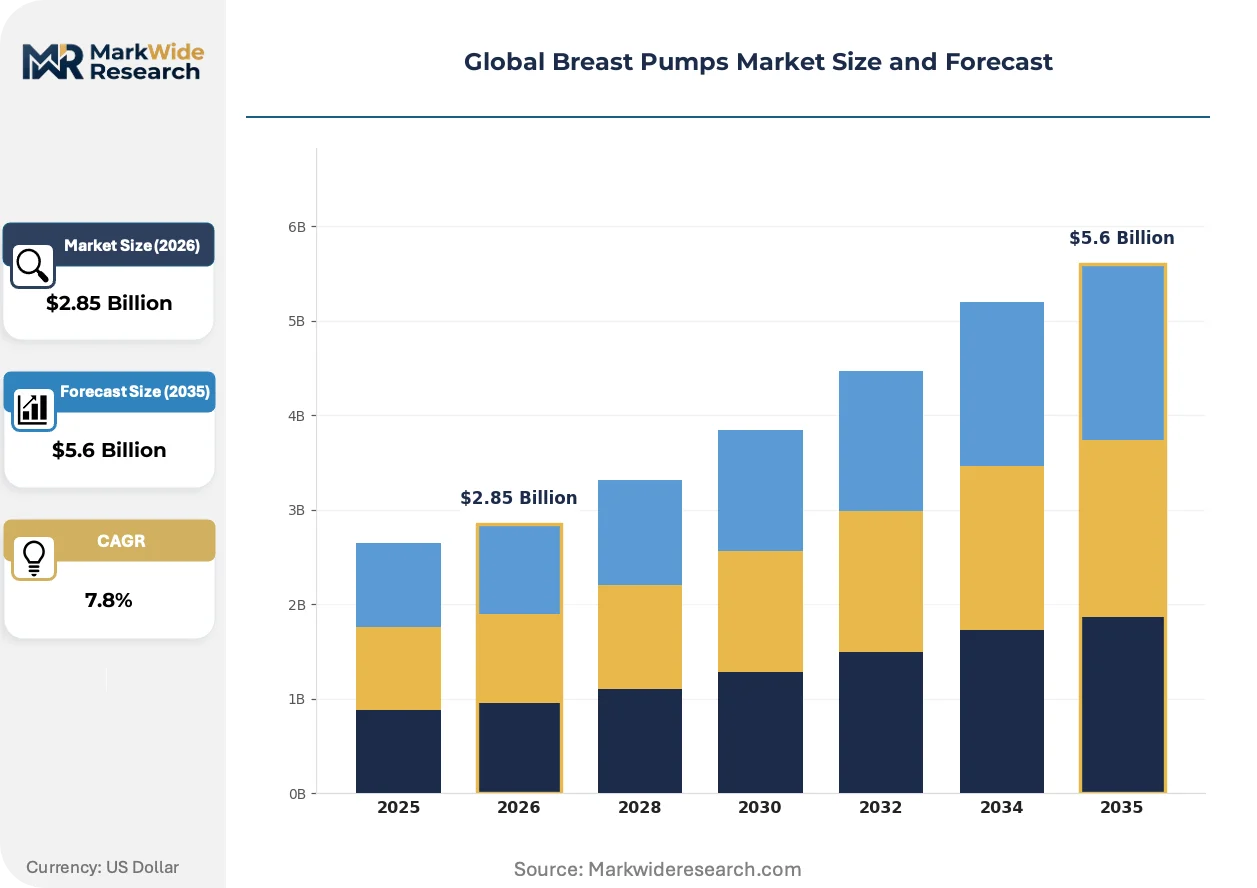
Corporate lactation benefit mandates and wearable pump miniaturization are restructuring demand composition, shifting volume from hospital procurement toward direct-to-consumer channels and employer-subsidized programs.
Growth Catalysts
- US Workplace Lactation Mandates:The Affordable Care Act pumping break requirements and state-level lactation accommodation laws compel employers to subsidize pump purchases, expanding the insured buyer pool beyond traditional retail.
- Wearable Motor Efficiency Gains:Brushless DC motor miniaturization and silicone diaphragm molding advances enable palm-sized pumps generating hospital-grade vacuum pressures without tethered power sources.
- China Three-Child Policy:Provincial birth incentive programs and extended maternity leave provisions in Jiangsu and Zhejiang provinces stimulate first-time pump adoption among urban professional mothers.
Market Restraints
- Silicone Raw Material Concentration:Medical-grade liquid silicone rubber supply concentrates among German and Japanese chemical suppliers, exposing pump manufacturers to input cost volatility and allocation constraints.
- FDA 510(k) Pathway Lengthening:The FDA Center for Devices and Radiological Health has tightened substantial equivalence determinations for powered breast pumps, extending clearance timelines for novel form factors.
- Manual Pump Substitution Resilience:Low-cost manual suction pumps retain share in price-sensitive segments and emerging markets where electricity access remains intermittent.
Strategic Opportunities
- Subscription Hardware Models:Employer benefit administrators and maternity insurance plans in Germany and the Netherlands are piloting pump-as-a-service arrangements with return-and-sanitize logistics.
- India PLI Scheme Alignment:The Indian government's production-linked incentive scheme for medical devices offers capital subsidy offsets for domestic pump assembly operations targeting ASEAN export markets.
- App-Integrated Expression Algorithms:Convergence of pressure sensor arrays with machine learning-based milk flow prediction creates differentiation in the premium wearable segment.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies for novel silicone formulations face laboratory capacity constraints, delaying product launch schedules.
- Legacy Hospital Contract Lock-In:NICU group purchasing organization agreements with multi-year exclusive terms create high switching costs for innovative pump entrants seeking clinical validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breast Pumps Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pumps, Electric Pumps, Battery-Operated Pumps, Hospital-Grade Pumps Technology: Single-Phase Expression, Double-Phase Expression, Closed System, Open System Application: Personal Use, Clinical Use, Lactation Support, Infant Feeding Assistance End User: Mothers, Neonatal Intensive Care Units, Maternity Clinics, Homecare Providers |
| Companies Covered | Newell Brands, Ardo, Medela AG, Lansinoh Laboratories, Hygeia Health, Philips N.V., Ameda, Elvie, Pigeon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breast Pumps Market Shifts & Advancements
Wearable form factors and algorithm-controlled expression patterns are compressing the traditional distinction between hospital-grade performance and consumer convenience, while regulatory frameworks scramble to classify software-augmented devices.
Closed-system wearable pumps with integrated milk collection chambers are collapsing the hardware boundary between stationary electric units and mobile battery-operated devices. Mothers in corporate lactation programs and gig-economy workers without dedicated pumping spaces are adopting these formats fastest. The technology is collapsing average selling price premiums previously commanded by hospital-grade certification alone.
The EU Medical Device Regulation Class I reclassification debate is forcing manufacturers to reassess software-controlled pumps with automated expression algorithms. Brussels-based notified bodies are demanding clinical evidence for pressure modulation features previously treated as mechanical functions. German and French regulators are scrutinizing app-connected pumps for cybersecurity compliance under parallel GDPR and MDR obligations.
Employer benefit administrators are consolidating pump procurement through specialized maternity platform vendors, bypassing traditional retail pharmacy and medical supply distribution. Large self-insured employers in the United States and United Kingdom are negotiating direct manufacturer relationships with volume guarantees and standardized device configurations. This concentration is most visible in technology sector headquarters clusters around Seattle, Austin, and London where lactation accommodation benchmarking has become talent retention infrastructure.
Global Breast Pumps Market Segmentation
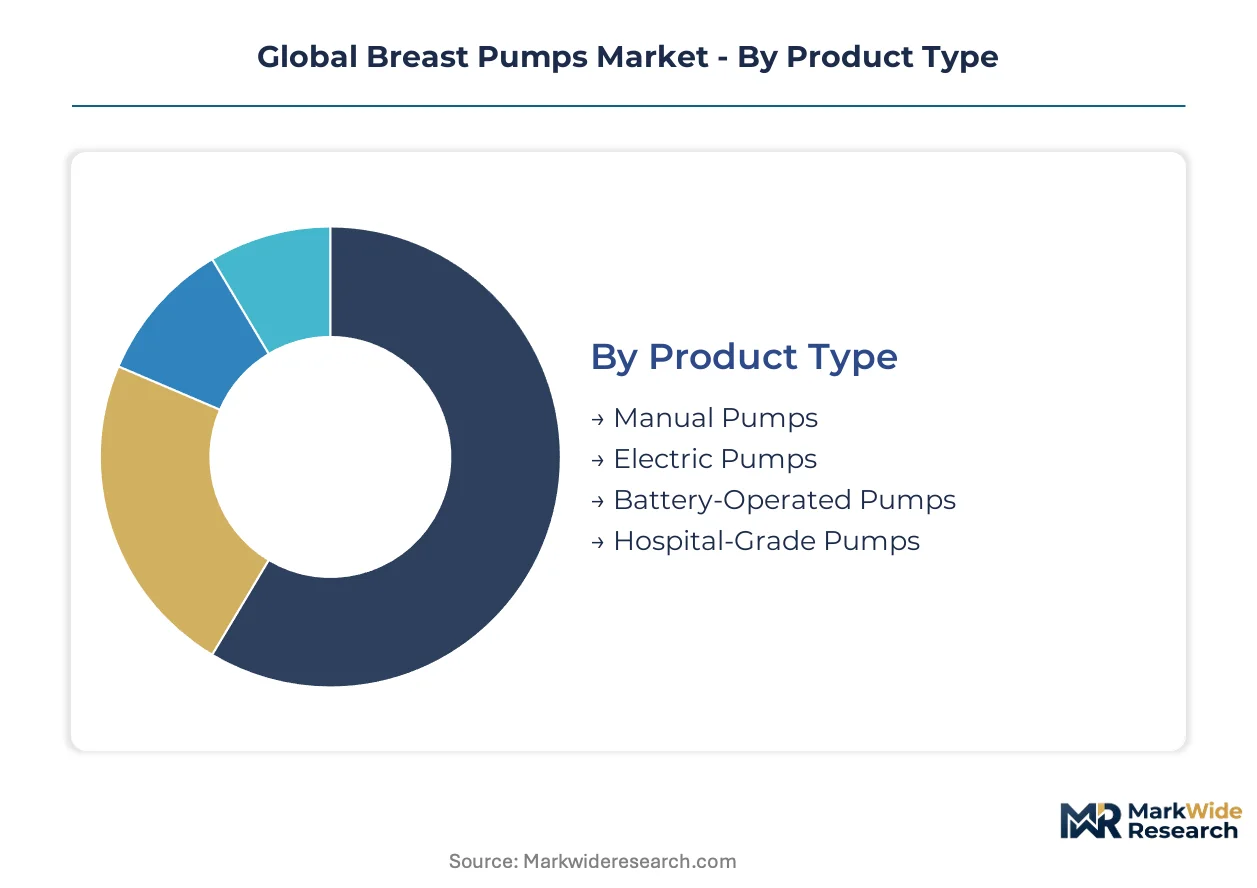
Segmentation in breast pumps tracks a fundamental tension between clinical certification requirements and consumer convenience priorities. Each dimension reveals how procurement channels, reimbursement pathways, and user mobility needs partition the addressable market.
Product Type:
Replacement cycles stretch from single-use manual disposables to five-year hospital-grade installations, compressing or extending revenue visibility for manufacturers depending on which tier captures volume.
- Manual Pumps:Hand-operated piston or lever mechanisms generating vacuum through mechanical suction without electrical components. Demand concentrates in rural India and sub-Saharan Africa where grid electricity remains unreliable, with UNICEF procurement programs sustaining volume despite minimal margin.
- Electric Pumps:AC-powered units with adjustable vacuum pressure and cycling frequency, typically deployed in dedicated lactation rooms. United States employer lactation benefit administrators favor these for corporate campus installations where stationary pumping infrastructure is feasible.
- Battery-Operated Pumps:Lithium-ion powered portable units bridging stationary and wearable formats. German maternity insurance plans are expanding reimbursement eligibility for rechargeable models as workplace mobility norms shift.
- Hospital-Grade Pumps:Multi-user capable devices with barrier-protected closed systems and FDA 510(k) clearance for clinical settings. NICU group purchasing organization contracts in the United States and National Health Service framework agreements in the United Kingdom lock in premium placement despite high unit costs.
Hospital-grade pumps dominate installed base. Battery-operated pumps are where expansion concentrates.
Technology:
Cost tiers separate legacy open-system designs from closed-system premiums, with software-enabled expression algorithms commanding additional reimbursement justification in European markets.
- Single-Phase Expression:Continuous suction patterns mimicking infant nursing at single pressure levels. Entry-level electric pumps in Southeast Asian retail pharmacies and Latin American public health programs rely on this simplified architecture.
- Double-Phase Expression:Alternating stimulation and expression phases replicating natural let-down reflex sequencing. United States and Netherlands private insurance reimbursement schedules recognize this feature as clinically differentiated, expanding addressable premium volume.
- Closed System:Diaphragm-barrier designs preventing milk pathway contamination of motor components. Mandatory for hospital procurement in France, Germany, and the United Kingdom under infection control protocols; EU MDR Class I reclassification debates are tightening biocompatibility documentation requirements.
- Open System:Direct milk-to-motor contact requiring thorough cleaning between uses. Price-sensitive segments in Mexico, Brazil, and Indonesia retain share due to lower manufacturing cost, though regulatory pressure is narrowing permissible applications.
Closed systems dominate installed base. Double-phase expression is where expansion concentrates.
Application:
Customer type stratification runs from self-directed consumer purchases to institutionally prescribed clinical interventions, with reimbursement complexity increasing across that spectrum.
- Personal Use:Individual mother-directed pumping without clinical supervision. Direct-to-consumer e-commerce channels in China and the United States are capturing volume fastest as wearable formats reduce pharmacy intermediary dependence.
- Clinical Use:Physician or lactation consultant-prescribed pumping protocols for medical indications. French and Italian national health service reimbursement pathways require prescription documentation, slowing volume but securing price premiums.
- Lactation Support:Professional consultation-integrated pumping programs addressing supply challenges or premature infant feeding. Employer-sponsored programs at technology sector headquarters in Seattle, Austin, and London are expanding this category through on-site lactation consultant staffing.
- Infant Feeding Assistance:Pumping for neonates unable to nurse directly, including premature or medically fragile infants. NICU contracts in the United States, Germany, and Japan concentrate demand for hospital-grade multi-user systems with rigorous sterilization protocols.
Personal use dominates installed base. Lactation support is where expansion concentrates.
End User:
Volume concentration varies sharply between fragmented individual purchasers and consolidated institutional procurement, with margin structure inverting that pattern.
- Mothers:Individual lactating women purchasing through retail, insurance, or employer benefit channels. China's urban professional mothers in Jiangsu and Zhejiang provinces are expanding fastest under extended maternity leave policies and provincial birth incentive programs.
- Neonatal Intensive Care Units:Hospital departments caring for premature or critically ill newborns requiring expressed milk feeding. Group purchasing organization consolidation in the United States and NHS Supply Chain centralization in the United Kingdom are narrowing supplier lists to clinically certified incumbents.
- Maternity Clinics:Outpatient facilities providing prenatal and postnatal lactation services. France's network of PMI maternal and child health centers and Germany's midwife-led birth centers are expanding rental pump programs as budget constraints limit capital purchases.
- Homecare Providers:Durable medical equipment suppliers delivering pumps to postpartum mothers under insurance authorization. United States Medicare and Medicaid managed care plans are tightening prior authorization requirements, compressing distributor margins.
Mothers dominate installed base. Neonatal intensive care units are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the dominant geography, while EU MDR Class I reclassification debates and China's three-child policy incentives reshape procurement patterns across developed and emerging markets.
United States
Employer lactation benefit mandates under the Affordable Care Act and state-level accommodation laws expand the insured buyer pool beyond retail channels. FDA Center for Devices and Radiological Health has tightened substantial equivalence determinations for powered pumps, extending clearance timelines for novel form factors. Technology sector headquarters clusters around Seattle, Austin, and London—where lactation accommodation benchmarking has become talent retention infrastructure—are consolidating procurement through specialized maternity platform vendors.
Germany
Provincial birth incentive programs and extended maternity leave provisions stimulate first-time pump adoption among urban professional mothers. EU Medical Device Regulation Class I rules and ISO 10993 cytotoxicity testing requirements shape product design and biocompatibility documentation for market access. German maternity insurance plans are expanding reimbursement eligibility for rechargeable battery-operated models as workplace mobility norms shift, while Berlin-Brandenburg and Bavaria host notified bodies scrutinizing software-controlled pumps for cybersecurity compliance under parallel GDPR and MDR obligations.
China
Jiangsu and Zhejiang provinces are expanding fastest under extended maternity leave policies and provincial birth incentive programs tied to the three-child policy. NMPA regulatory pathways and GB standards constrain component sourcing and design flexibility for manufacturers seeking market access. Yangtze River Delta manufacturing clusters are capturing direct-to-consumer e-commerce volume as wearable formats reduce pharmacy intermediary dependence among urban professional mothers.
United Kingdom
NHS Supply Chain centralization and framework agreements are narrowing supplier lists to clinically certified incumbents for hospital-grade multi-user systems. National Health Service reimbursement pathways require prescription documentation for clinical-use pumps, slowing volume but securing price premiums. London technology sector employers are negotiating direct manufacturer relationships with volume guarantees and standardized device configurations, bypassing traditional retail pharmacy distribution.
India
UNICEF procurement programs sustain manual pump volume in rural areas where grid electricity remains unreliable, despite minimal margin. The government's production-linked incentive scheme for medical devices offers capital subsidy offsets for domestic pump assembly operations targeting ASEAN export markets. Maharashtra and Gujarat manufacturing hubs are piloting pump-as-a-service arrangements with return-and-sanitize logistics for employer benefit administrators and maternity insurance plans.
Global Breast Pumps Market Competitive Landscape
Clinically certified incumbents and wearable technology specialists split the market into distinct capability tiers. Hospital procurement consolidation through group purchasing organizations and NHS Supply Chain centralization favors established players with multi-year exclusive NICU contracts. Three archetypes dominate: heritage medical device manufacturers with backward integration into motor and silicone component production, direct-to-consumer wearable specialists bypassing traditional retail pharmacy distribution, and regional fabricators serving price-sensitive emerging markets through manual pump offerings. Competitive moves concentrate on strategic partnerships with employer benefit administrators and geographic expansion through production-linked incentive alignment in India.
Within the clinically certified tier, Medela AG and Philips N.V. occupy positions sustained by hospital-grade certification and component production control. Among direct-to-consumer specialists, Elvie exemplifies the wearable form factor approach that collapses average selling price premiums previously commanded by stationary electric units. Newell Brands and Pigeon Corporation represent diversified consumer goods conglomerates and Asia-Pacific-focused specialists respectively, each anchoring distinct geographic and channel strategies. The competitive terrain rewards regulatory navigation capability and employer relationship depth over pure manufacturing scale.
| Leading Market Players |
|---|
| Newell Brands |
| Ardo |
| Medela AG |
| Lansinoh Laboratories |
| Hygeia Health |
| Philips N.V. |
| Ameda |
| Elvie |
| Pigeon Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in German and Japanese medical-grade silicone rubber production is tightening input allocation and amplifying cost pass-through leverage among chemical suppliers. Pump manufacturers face compressed margins as liquid silicone rubber spot availability constrains production scheduling and forces premium pricing for secured volumes.
Pricing Analysis
Geographic price spreads separate United States employer-subsidized channels from Indian manual pump retail, with reimbursement depth explaining the divergence. Three-tier pricing structure across hospital-grade certification, wearable premium, and manual economy levels dominates transaction architecture. Price differentiation rests on FDA 510(k) clearance tier and motor performance specifications. Cost compression in the wearable segment is intensifying because brushless DC motor commoditization erodes hardware premiums. Employer benefit administrators demonstrate lowest price sensitivity; rural Indian mothers exhibit highest.
Supply Chain Analysis
Medical-grade liquid silicone rubber feedstock concentrates among German and Japanese chemical suppliers, with Yangtze River Delta molding operations dependent on imported material. Component sourcing draws from Taiwan for precision motors, China for lithium-ion cells, and Germany for diaphragm formulations. Single-source vulnerability in silicone rubber allocation exposes pump assemblers to force majeure disruption. Distribution runs through employer benefit administrators and GPO contracts in developed markets, direct-to-consumer e-commerce in China, and UNICEF procurement in South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The breast pumps market is recovering from birth-rate cyclicality as workplace lactation mandates and wearable innovation restructure demand composition. Extended maternity leave provisions across Jiangsu, Zhejiang, and several German provinces provide the cyclical lift.
For Market Incumbents: Harden NICU contract renewal terms through multi-year exclusive agreements with group purchasing organizations before wearable entrants secure clinical validation. Deepen backward integration into silicone diaphragm production to offset German and Japanese chemical supplier pricing power. FDA 510(k) pathway lengthening creates defensive moats for cleared portfolios against software-augmented challengers. For New Entrants and Emerging Players: Establish a beachhead in employer-subsidized wearable pumps through direct relationships with technology sector benefit administrators in Seattle, Austin, and London. Target India's production-linked incentive scheme for capital-efficient assembly serving ASEAN export markets. Go-to-market leverage rests on app-integrated expression algorithms that command premium positioning despite hardware commoditization. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pump-as-a-service operators with return-and-sanitize logistics. Long-term viability favors clinically certified incumbents with GPO contract depth over pure-play wearable hardware. Acquisition screening should prioritize notified body relationships for EU MDR Class I reclassification navigation. Watch FDA substantial equivalence determination timelines as inflection signal for novel form factor clearance velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Clearance velocity determines competitive access to employer-subsidized channels and NICU contracts. |
| Employer Benefit Partnership | Direct relationships with technology sector headquarters clusters bypass retail pharmacy margin extraction. |
| Silicone Component Backward Integration | Captive supply of medical-grade liquid silicone rubber insulates against German and Japanese allocation constraints. |
| Wearable Algorithm Development | Machine learning-based milk flow prediction differentiates premium positioning as hardware commoditizes. |
| India PLI Scheme Alignment | Capital subsidy offsets enable ASEAN export competitiveness from Maharashtra and Gujarat assembly hubs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with lactation consultants, hospital biomedical engineers, GPO contracts managers, and employer benefit administrators. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement schedules, and UNICEF procurement records. Bottom-up volume estimates from country-level birth rate and pump penetration assumptions were triangulated against top-down manufacturer revenue aggregation.
Calibration against historical FDA clearance timelines and GPO contract renewal cycles anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, technology tier, application setting, and end-user procurement channel, with regional regulatory cluster as an overlay. CAGRs were derived from fitted adoption curves incorporating workplace lactation mandate expansion and wearable motor efficiency gains as primary demand drivers.
Macroeconomic conditions sit as an overlay; deviation in birth rate trajectories, employer healthcare benefit generosity, or silicone rubber commodity pricing would shift the trajectory. Cross-checking against hospital procurement database trends and maternity insurance reimbursement schedule revisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
ADA Substitute Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Medical Device Coating Market
Medical Devices
Organ Preservation Market
Medical Devices
Cervical Spacer Systems Market
Medical Devices
Rapid Infuser Market
Medical Devices
Air Compressor Nebulizer Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Aortic Cannula Systems Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
Intermittent Catheters Market