
 Global Cardiac Holter Monitor Market | 2026-2036
Global Cardiac Holter Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Holter Monitor Market Foresight
Hospital procurement is decoupling from standalone Holter hardware as health systems prioritize integrated telemetry platforms. GE HealthCare Technologies leverages its imaging ecosystem to bundle ambulatory ECG with enterprise cardiac workflows. Nihon Kohden Corporation anchors its position through deep channel control in Japanese cardiology clinics. iRhythm Technologies Inc. differentiates via AI-enabled patch analytics that reduce clinician interpretation burden.
A cardiac Holter monitor records continuous electrocardiographic signals over 24–48 hours via 3–12 lead configurations, storing data on solid-state memory for offline arrhythmia analysis. The device serves primarily as a diagnostic tool for intermittent cardiac rhythm disturbances that escape standard 12-lead ECG capture. Patch monitors now lead growth among product types due to patient compliance advantages and water-resistant adhesive designs that enable multi-day wear. Remote patient monitoring services represent the fastest-expanding end-user channel as reimbursement shifts toward value-based cardiac care models. Home healthcare deployment remains comparatively mature with slower upgrade cycles tied to capital equipment amortization schedules.
FDA 510(k) pathways and EU MDR conformity assessments govern device safety and software validation requirements for algorithm-based diagnostic outputs. Japan's PMDA enforces distinct clinical evidence standards for extended-wear ECG systems that delay market entry relative to Western regulators. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under EUDAMED as connected Holter systems proliferate outside controlled clinical environments.
Market Dynamics
Hospital procurement is decoupling from standalone Holter hardware as health systems prioritize integrated telemetry platforms that bundle ambulatory ECG with enterprise cardiac workflows. This structural shift is compressing margins for device-only vendors while rewarding platform ecosystems.
Growth Catalysts
- Remote patient monitoring reimbursement:CMS and private payers in the United States are expanding coverage for ambulatory ECG services performed outside hospital settings.
- EU MDR extended-wear pathways:CE marking frameworks for 14-day patch monitors are accelerating clinical validation timelines across European cardiology networks.
- Wearable adhesive technology:Water-resistant hydrogel interfaces enable multi-day continuous monitoring without skin irritation, improving patient compliance in home healthcare deployment.
Market Restraints
- Semiconductor supply concentration:Solid-state memory and low-power microcontrollers for Holter devices depend heavily on East Asian foundry capacity.
- PMDA clinical evidence requirements:Japan's pharmaceutical and medical device agency demands extended domestic trials for algorithm-based diagnostic outputs, delaying market entry.
- Implantable loop recorders:Subcutaneous devices with 2-3 year battery life are capturing high-value arrhythmia cases that escape patch detection.
Strategic Opportunities
- Brazilian outpatient cardiology:ANVISA regulatory harmonization with FDA 510(k) standards is opening private clinic channels in São Paulo and Rio de Janeiro.
- AI-ECG convergence:Machine learning interpretation layered on patch data streams enables automated preliminary reads before cardiologist review.
- Direct-to-employer contracting:Occupational health programs in Germany are purchasing ambulatory monitoring services for workforce cardiovascular screening.
Industry Challenges
- Algorithm validation timelines:FDA software as a medical device guidance requires prospective clinical studies for each diagnostic claim, extending development cycles.
- Legacy EHR integration:Hospital information systems in Japan use proprietary data formats that complicate seamless Holter report ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Holter Monitor Market |
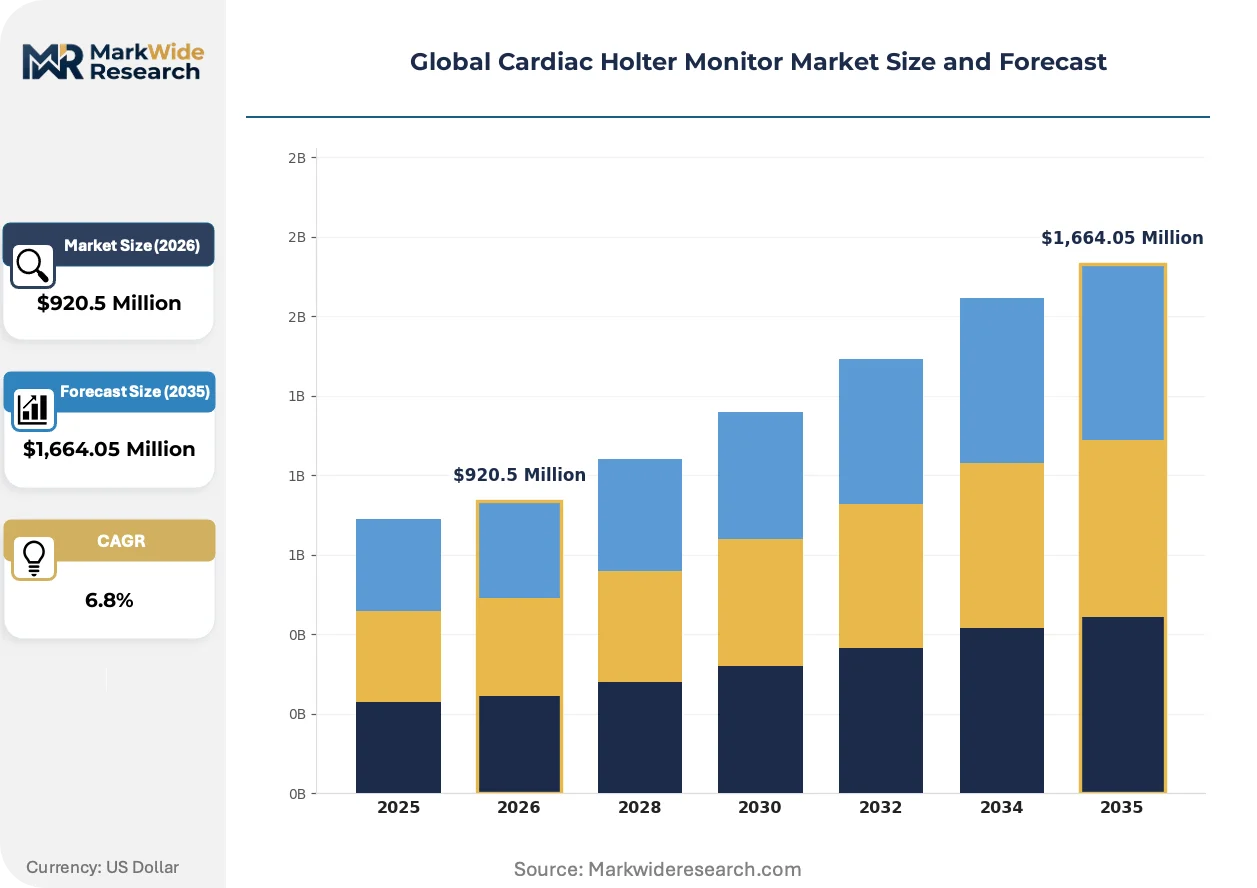
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,664.05 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Holter Monitor, Wearable Device, Patch Monitor, Ambulatory ECG Recorder, Event Monitor Application: Arrhythmia Detection, Myocardial Ischemia, Atrial Fibrillation Monitoring, Heart Rate Variability, Syncope Evaluation End User: Cardiology Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers, Specialized Cardiac Hospitals, Remote Patient Monitoring Services Deployment: Hospital-based, Outpatient Facilities, Home Healthcare, Telemedicine Platforms, Mobile Health Units |
| Companies Covered | Fukuda Denshi Co. Ltd, Nihon Kohden Corporation, GE HealthCare Technologies, Edan Instruments Inc., iRhythm Technologies Inc., Koninklijke Philips N.V., Medtronic, BPL Medical Technologies, Schiller AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Holter Monitor Market Shifts & Advancements
Wearable patch form factors are compressing the traditional 24-48 hour Holter window into multi-week continuous monitoring, fundamentally altering how clinicians capture intermittent arrhythmias.
Deep learning arrhythmia classification is unifying signal processing and diagnostic interpretation into single-chip architectures. Cardiology clinics in the United States are adopting these systems at accelerating rates. The technology is unifying hardware and software margins that previously sat with separate vendors.
EU MDR post-market surveillance obligations under EUDAMED are mandating real-world performance tracking for connected Holter systems. Manufacturers must submit periodic safety reports and cybersecurity updates. Extended-wear patch devices face the steepest compliance burden as they operate outside controlled clinical environments.
Hospital procurement committees are consolidating ambulatory ECG purchasing under value-based cardiac care contracts. Integrated delivery networks in Germany are replacing capital equipment leases with per-test service agreements. This pattern is most visible in United States health systems where CMS bundled payment pilots reward diagnostic yield over device ownership.
Global Cardiac Holter Monitor Market Segmentation
Segmentation in cardiac Holter monitors reveals how hardware specifications, clinical use cases, and care delivery settings fragment purchasing authority. Product form factors determine reimbursement eligibility, while end-user channels dictate software integration requirements and service revenue models.
Product Type:
Patch form factors and wearable designs are compressing traditional Holter windows from 24-48 hours into multi-week continuous monitoring, altering how intermittent arrhythmias escape detection.
- Patch Monitor:Water-resistant hydrogel adhesives enable 14-day wear without skin irritation, capturing arrhythmias that elude shorter monitoring windows. Demand concentrates in United States remote patient monitoring services where CMS reimbursement favors extended-wear diagnostic yield over device ownership. FDA 510(k) pathways for algorithm-based patch outputs are accelerating clinical validation timelines.
- Wearable Device:These integrate ECG sensors into consumer-accessible form factors with patient-facing mobile applications. German occupational health programs are purchasing wearable monitoring services for workforce cardiovascular screening, driven by value-based contracting models that reward early detection.
- Portable Holter Monitor:Traditional 3-12 lead configurations with solid-state memory storage remain standard in Japanese cardiology clinics where PMDA clinical evidence requirements favor established hardware platforms.
- Ambulatory ECG Recorder:Compact devices designed for outpatient mobility with offline arrhythmia analysis capabilities serve diagnostic laboratories in São Paulo and Rio de Janeiro where ANVISA harmonization with FDA standards is opening private clinic channels.
- Event Monitor:Patient-activated or auto-triggered systems capture symptomatic episodes outside continuous monitoring protocols, serving syncope evaluation workflows in specialized cardiac hospitals.
Patch monitors lead on scale; wearable devices lead on momentum.
Application:
Diagnostic specificity determines hardware selection and reimbursement coding, with algorithm-interpretable conditions commanding premium service pricing.
- Atrial Fibrillation Monitoring:Machine learning classification of irregularly irregular rhythms now enables automated preliminary reads before cardiologist review. United States integrated delivery networks are replacing capital equipment leases with per-test service agreements for AF burden quantification.
- Arrhythmia Detection:Broad-catch diagnostic protocols for ventricular ectopy, bradyarrhythmias, and conduction disturbances remain the foundational use case across all product types and geographies.
- Myocardial Ischemia:ST-segment analysis capabilities require higher-fidelity signal processing and 12-lead configurations, concentrating demand in hospital-based deployment settings.
- Heart Rate Variability:Autonomic function assessment applications are gaining traction in German direct-to-employer occupational health contracts for stress-related cardiovascular risk stratification.
- Syncope Evaluation:Correlation of symptomatic episodes with cardiac rhythm data drives event monitor selection in ambulatory surgical centers performing pre-operative clearance.
Atrial fibrillation monitoring leads on scale; heart rate variability leads on momentum.
End User:
Procurement authority is fragmenting across clinical settings as reimbursement shifts from device ownership to diagnostic service delivery.
- Remote Patient Monitoring Services:Platform-based providers bundle patch logistics, AI interpretation, and cardiologist oversight into per-test contracts. CMS and private payers in the United States are expanding coverage for ambulatory ECG services performed outside hospital settings, accelerating channel growth.
- Cardiology Clinics:Japanese specialty practices anchor demand through deep channel relationships with established device vendors, though legacy EHR integration complicates seamless report ingestion.
- Specialized Cardiac Hospitals:These institutions prioritize integrated telemetry platforms that bundle ambulatory ECG with enterprise cardiac workflows, compressing margins for device-only vendors.
- Diagnostic Laboratories:Centralized interpretation services are adopting AI-ECG convergence for automated preliminary reads, unifying hardware and software margins.
- Ambulatory Surgical Centers:Pre-operative clearance requirements drive event monitor utilization for syncope evaluation in outpatient procedural settings.
Cardiology clinics lead on scale; remote patient monitoring services lead on momentum.
Deployment:
Care setting determines regulatory exposure, with connected systems outside controlled clinical environments facing heightened cybersecurity and post-market surveillance obligations.
- Telemedicine Platforms:Virtual-first cardiology practices in the United States are adopting patch-based remote monitoring as core service infrastructure, with FDA cybersecurity guidance mandating real-world performance tracking for connected systems.
- Home Healthcare:Capital equipment amortization schedules slow upgrade cycles compared to service-based deployment models, though water-resistant adhesive designs are improving patient compliance.
- Hospital-based:Procurement committees are consolidating ambulatory ECG purchasing under value-based cardiac care contracts that reward diagnostic yield.
- Outpatient Facilities:German integrated delivery networks are replacing capital equipment leases with per-test service agreements in this channel.
- Mobile Health Units:Screening programs in Brazilian urban centers leverage portable Holter configurations for community-based arrhythmia detection.
Hospital-based deployment leads on scale; telemedicine platforms lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as extended-wear patch producers migrate validation activities toward jurisdictions with streamlined FDA 510(k) equivalence pathways rather than confronting EU MDR's extended clinical evidence timelines.
United States
CMS reimbursement expansion for remote patient monitoring services drives outpatient channel growth. FDA cybersecurity guidance mandates real-world performance tracking for connected Holter systems operating outside clinical environments. Silicon Valley and Boston medical device clusters concentrate AI-ECG convergence development.
Germany
Occupational health programs purchase ambulatory monitoring services for workforce cardiovascular screening under value-based contracting models. EU MDR conformity assessments govern extended-wear device safety requirements. The Rhine-Ruhr industrial corridor anchors integrated delivery network procurement consolidation.
Japan
PMDA clinical evidence standards for algorithm-based diagnostic outputs delay market entry relative to Western regulators. Deep channel relationships in specialty cardiology clinics sustain demand for established hardware platforms. Tokyo and Osaka metropolitan areas concentrate reimbursement decision-making authority.
Brazil
ANVISA regulatory harmonization with FDA 510(k) standards opens private clinic channels in São Paulo and Rio de Janeiro. Outpatient cardiology networks adopt portable Holter configurations for community-based arrhythmia detection. Southeastern urban centers drive diagnostic laboratory centralization.
United Kingdom
NHS long-term plan targets shift ambulatory ECG delivery toward community-based settings. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR safety benchmarks. London and Manchester health innovation districts pilot AI-enabled patch analytics integration.
Global Cardiac Holter Monitor Market Competitive Landscape
Platform ecosystem bundling dominates the current landscape as health systems consolidate procurement under integrated telemetry contracts. The vendor base separates into three distinct tiers: imaging conglomerates with enterprise cardiac workflows, pure-play patch specialists with AI interpretation layers, and regional device manufacturers with deep channel control. Strategic archetypes include platform integrators seeking workflow lock-in, algorithm developers monetizing software margins, and hardware incumbents defending installed base relationships. M&A activity concentrates on AI-ECG convergence capabilities, while geographic expansion targets Brazilian and German outpatient channels.
Among Japanese medical device incumbents, Nihon Kohden Corporation and Fukuda Denshi Co. Ltd exemplify regional channel control archetypes. GE HealthCare Technologies occupies a position representing imaging ecosystem bundling, while iRhythm Technologies Inc. anchors the AI-enabled patch specialist tier. These three companies collectively illustrate the competitive tension between hardware legacy and software-driven service models reshaping procurement authority.
| Leading Market Players |
|---|
| Fukuda Denshi Co. Ltd |
| Nihon Kohden Corporation |
| GE HealthCare Technologies |
| Edan Instruments Inc. |
| iRhythm Technologies Inc. |
| Koninklijke Philips N.V. |
| Medtronic |
| BPL Medical Technologies |
| Schiller AG |
| Others |
Supply & Pricing Matrix
Captive silicon sourcing from Taiwanese foundries anchors both component security and margin structure for patch monitor manufacturers serving United States remote patient monitoring channels. This integration choice insulates vendors from spot-market volatility while enabling service-based pricing that decouples revenue from hardware depreciation cycles.
Pricing Analysis
Distributor margin compression in European cardiology networks is accelerating direct contracting between patch manufacturers and integrated delivery networks. Three-tier pricing structure across premium AI-enabled, standard algorithm-assisted, and economy hardware-only levels stratifies by diagnostic yield guarantee and cardiologist oversight depth. Pricing pressure stems from CMS reimbursement rate compression for ambulatory ECG services, squeezing per-test margins. Hospital procurement committees exhibit lowest price sensitivity due to bundled payment incentives, while independent diagnostic laboratories face acute cost pressure from capital equipment amortization.
Supply Chain Analysis
Japan's PMDA domestic clinical trial mandates are reshaping sourcing footprints toward United States and German validation partners with established algorithm equivalence pathways. Solid-state memory and low-power microcontrollers draw from Taiwanese and South Korean semiconductor fabrication, while water-resistant hydrogel adhesives feed from German chemical specialty suppliers. Single-source vulnerability concentrates in advanced ECG sensor MEMS fabrication. Distribution runs through cardiology-focused medical device distributors with GPO contracting authority in United States health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA 510(k) streamlined pathways and EU MDR extended clinical evidence timelines creates cost-differential opportunities for algorithm developers validating in United States jurisdiction first.
For Market Incumbents: Deepen AI-ECG convergence capabilities through in-house development of arrhythmia classification algorithms, defending against pure-play patch specialists capturing cardiologist interpretation margins. Fortify channel control in Japanese specialty clinics where PMDA evidence requirements delay entrant disruption. Prioritize cybersecurity certification investment as FDA guidance hardens post-market surveillance for connected systems operating outside hospital environments. For New Entrants and Emerging Players: Enter via Brazilian outpatient cardiology networks where ANVISA harmonization with FDA standards lowers regulatory entry costs relative to European markets. Target diagnostic laboratories in São Paulo and Rio de Janeiro with portable Holter configurations priced for private clinic capital budgets. Pursue white-label AI interpretation partnerships with established device manufacturers lacking algorithm development capacity. For Investors and Strategic Acquirers: Roll-up economics work for AI-enabled patch specialists because cardiologist interpretation bottlenecks create scarcity value for automated diagnostic platforms with proven clinical validation. Long-term viability hinges on software margin capture displacing hardware commoditization across the care delivery window. Monitor FDA software as a medical device enforcement patterns as inflection signal for algorithm-based diagnostic claim valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerated market entry for algorithm-based patch diagnostics in United States remote monitoring channels. |
| CE Marking Under EU MDR | Extended clinical evidence requirements reshape validation timelines for European cardiology network deployment. |
| Hospital System Partnership | Integrated telemetry platform bundling secures enterprise cardiac workflow lock-in against device-only vendors. |
| Software Companion Development | AI-ECG convergence unifies hardware and interpretation margins previously captured by separate stakeholders. |
| Reimbursement Strategy | CMS coverage expansion for ambulatory ECG services outside hospital settings accelerates service-based revenue models. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, cardiologist workflow observations, regulatory filing analysis, and GPO contract database review — were reconciled to construct demand-side segmentation. Primary engagement with biomedical engineers, cardiology practice administrators, and remote patient monitoring platform executives informed operational constraints. Secondary validation drew from FDA 510(k) databases, EUDAMED vigilance reports, CMS Medicare claims data, and Japanese PMDA approval records. Bottom-up unit economics and top-down reimbursement trend analysis were triangulated to anchor volume projections.
Data-stream reconciliation across product form factor, diagnostic application specificity, end-user procurement authority, and deployment setting generated the segmentation framework. CAGRs were derived from reimbursement rate trajectory modeling and technology substitution elasticity estimates. Algorithm validation timeline assumptions and semiconductor supply availability patterns served as industry-specific forecast inputs across the projection horizon.
The model holds under stable regulatory equivalence pathways between FDA and ANVISA; deviation in EU MDR clinical evidence interpretation or PMDA algorithm validation requirements would shift geographic deployment sequencing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Midline Catheters Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Orthodontic Retainers Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Stool Management Systems Market
Medical Devices
Morcellators Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Single-Use Assemblies Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Bone Allografts Market