
 Education Microscope Market | 2026-2036
Education Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Education Microscope Market Analytics
Modular microscope systems with detachable digital cameras and tablet-compatible imaging modules is pivoting how K-12 districts and community colleges evaluate purchases. Nikon Corporation leverages its optical heritage to sustain premium positioning in university research clusters. Motic Microscopes competes aggressively on price-performance ratios for bulk institutional tenders in emerging markets. Olympus Corporation anchors its education presence through service networks that reduce total cost of ownership for multi-year district contracts.
An education microscope is an optical or electronic magnification instrument engineered for instructional environments, typically featuring achromatic objectives with magnifications from 4x to 100x, mechanical stages with 1mm Vernier resolution, and LED or halogen illumination systems designed for repeated student handling. Its primary commercial purpose is enabling visual observation of cellular structures, crystalline formations, or particulate samples in structured learning settings. Compound microscopes still dominate volume shipments to high school biology programs where durability and low maintenance outweigh advanced features. Digital microscopes represent the fastest-expanding product type as remote and hybrid learning protocols normalize screen-based specimen sharing. Software-integrated technology platforms capture disproportionate margin pools by bundling measurement tools, annotation layers, and cloud storage into recurring license structures.
FDA oversight of medical-device adjacent microscopy used in clinical training programs shapes product liability standards that manufacturers voluntarily extend to education SKUs. EPA energy-efficiency guidelines for laboratory equipment influence LED illumination adoption and power-supply design choices across supplier portfolios. ISO 10901 and IEC 61010-1 compliance requirements filter market access for imports into European and North American institutional procurement channels. Stakeholders must weigh captive software ecosystems against open-platform interoperability as districts consolidate vendor relationships and demand multi-decade curriculum alignment.
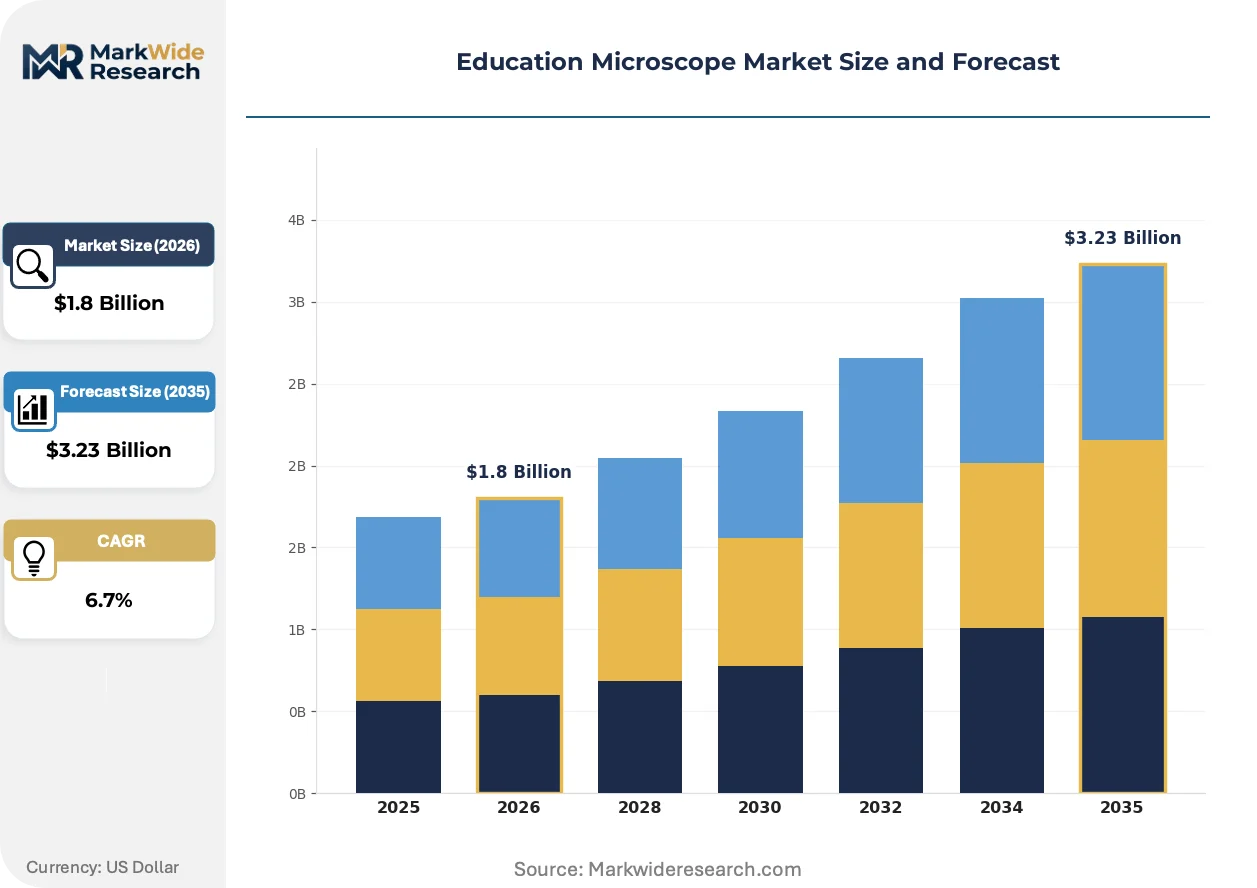
Market Dynamics
Digital microscopy platforms with integrated software suites are compressing replacement cycles for conventional optical units as K-12 districts and universities consolidate vendor relationships around multi-decade curriculum alignment.
Growth Catalysts
- STEM curriculum mandates:National education boards in India and China prioritize laboratory infrastructure spending in public secondary schools, accelerating institutional procurement timelines for compound microscope systems.
- REACH compliance harmonization:European Union chemical safety standards for educational laboratory equipment streamline cross-border tender processes for microscope suppliers serving multiple member states.
- Cloud-enabled specimen sharing:Hybrid learning protocols normalize screen-based microscopy in remote instruction, expanding addressable demand beyond physical classroom constraints.
Market Restraints
- Optical glass supply concentration:German and Japanese specialty glass manufacturers control premium objective lens substrates, exposing procurement budgets to input cost volatility and extended lead times.
- FDA liability extension:Medical-device adjacent microscopy standards voluntarily applied to education SKUs elevate product liability insurance burdens and documentation requirements for manufacturers.
- Tablet substitution pressure:Consumer-grade digital magnification attachments for mobile devices capture price-sensitive home-learning segments, constraining entry-level microscope pricing power.
Strategic Opportunities
- Vocational training expansion:India's National Education Policy prioritizes technical skills development in tier-2 and tier-3 cities, creating underpenetrated demand pockets for mid-range digital microscope systems.
- AI-powered image analysis convergence:Machine learning classification algorithms integrated with camera modules enable automated cell counting and anomaly detection, differentiating premium education platforms.
- CE-MDR regulatory tailwind:European medical device regulation harmonization creates certification pathways for clinical training microscopes that manufacturers can leverage for adjacent education market access.
Industry Challenges
- Electronics-Optics integration complexity:Legacy microscope architectures require substantial re-engineering to accommodate CMOS sensor modules and wireless connectivity stacks without compromising optical path stability.
- ISO 10901 certification timelines:Extended validation periods for educational equipment safety standards delay product launches and compress effective sales windows within academic procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Education Microscope Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compound Microscope, Stereo Microscope, Digital Microscope, Portable Microscope End User: Schools, Colleges, Universities, Research Institutes Application: Biological Studies, Material Science, Forensics, Educational Demonstrations Technology: Optical, Electronic, Software-Integrated, High-Definition |
| Companies Covered | Thermo Fisher Scientific, ZEISS Group, Nikon Corporation, Olympus Corporation, Leica Microsystems, JEOL Ltd, Bruker Corporation, Meiji Techno, Motic Microscopes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Education Microscope Market Evolving Landscape
Software-integrated imaging platforms are redefining how institutions evaluate total cost of ownership, bundling measurement tools and cloud storage into recurring license structures that extend vendor relationships beyond hardware replacement cycles.
Wireless digital microscope systems with tablet-native interfaces are electrifying how biology departments equip teaching laboratories. Secondary schools in North American districts adopt these units at accelerated pace as STEM grant funding prioritizes technology-enabled instruction. The shift compresses capital allocation previously split between optical hardware and separate imaging accessories into consolidated platform purchases.
EPA energy-efficiency guidelines for laboratory equipment are mandating LED illumination retrofits and low-power supply designs across supplier portfolios. Manufacturers serving US institutional markets reconfigure product lines to meet standby power thresholds. Education SKUs now carry efficiency certifications previously reserved for research-grade instrumentation, affecting component sourcing and thermal management engineering.
Bundled service contracts with multi-year calibration and software update commitments are displacing transactional hardware sales in university procurement. Purchasing departments in European research clusters negotiate all-inclusive agreements that lock in vendor relationships. This pattern concentrates supplier selection authority at central administrative levels rather than individual department discretion.
Education Microscope Market Segmentation
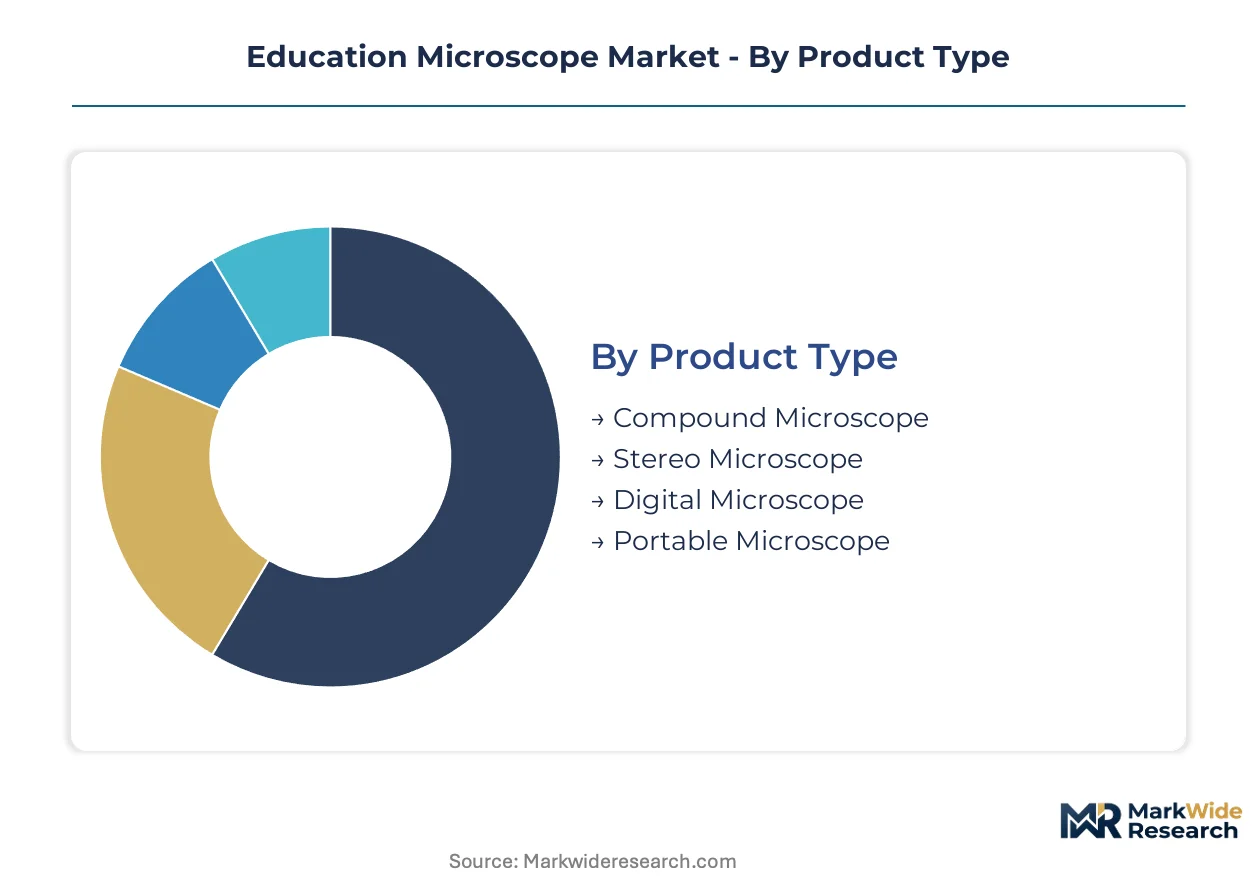
Education microscope procurement patterns diverge sharply across institutional tiers, with K-12 districts prioritizing durability and service networks while research universities demand software-integrated imaging platforms. Segmentation reveals how vendor portfolios must straddle these conflicting requirements without fragmenting manufacturing scale.
Product Type:
Standalone optical systems dominate basic biology instruction, while embedded digital modules are penetrating advanced research training environments where data capture and sharing are mandatory.
- Compound Microscope:Achromatic objective configurations with 4x to 100x magnification ranges and mechanical stages remain the workhorse for high school biology programs. Demand concentrates in Indian and Chinese public secondary schools where national curriculum mandates prioritize affordable laboratory infrastructure.
- Digital Microscope:CMOS sensor-integrated units with tablet-native interfaces and wireless specimen sharing capabilities are displacing conventional optical units in North American university teaching laboratories. Hybrid learning protocols in US community colleges accelerate procurement of screen-based microscopy platforms.
- Stereo Microscope:Low-magnification dissecting instruments with dual optical paths serve veterinary and agricultural training programs requiring three-dimensional specimen manipulation.
- Portable Microscope:Battery-powered field units with LED illumination target environmental science curricula and outdoor education programs in remote district locations.
Compound microscopes lead volumes today; digital microscopes are gaining share fastest.
End User:
Cost tier stratification separates price-sensitive bulk tenders from premium research-grade procurement, with service contract bundling becoming decisive at the university level.
- Schools:K-12 districts prioritize total cost of ownership metrics, favoring mechanical durability and multi-year service agreements over optical sophistication. Indian state education boards drive volume through centralized tender processes for public secondary institutions.
- Universities:Research-intensive institutions demand software-integrated platforms with cloud storage, annotation tools, and measurement algorithms. European university clusters negotiate all-inclusive vendor relationships spanning hardware, calibration, and curriculum-aligned updates.
- Colleges:Two-year and technical institutions occupy a mid-market position, balancing digital imaging requirements against constrained capital budgets.
- Research Institutes:Specialized facilities require fluorescence and confocal extensions beyond standard education SKUs, though clinical training programs overlap with medical-device adjacent standards.
Schools anchor volume shipments; universities command premium pricing tiers.
Application:
Maturity gradients separate established biological instruction from emerging forensic and materials science curricula that demand specialized illumination and specimen preparation accessories.
- Biological Studies:Cellular and tissue observation remains the foundational application, with staining protocols and wet mount preparation defining standard equipment configurations. Chinese provincial education budgets prioritize biology laboratory expansion under STEM curriculum reforms.
- Forensics:Hair, fiber, and ballistic analysis training requires polarized light and comparison microscope capabilities. US criminal justice programs at community colleges expand specialized procurement as vocational credentials gain enrollment share.
- Material Science:Metallurgical and crystallography instruction demands reflected light and hot stage accessories, penetrating engineering and geology departments.
- Educational Demonstrations:Museum and science center outreach programs drive demand for projection-capable units with large-format display integration.
Biological studies dominate installed base; forensics exhibits steepest expansion trajectory.
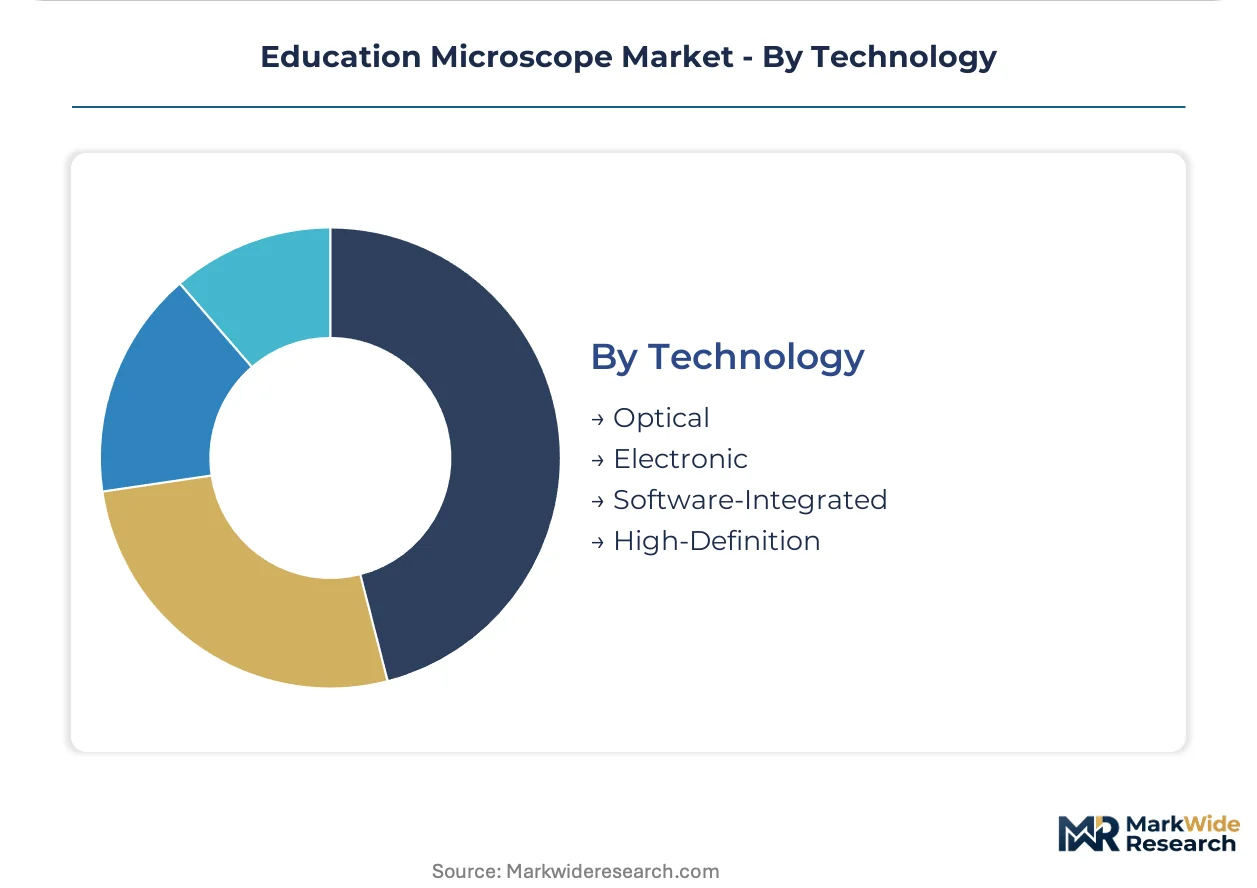
Technology:
Supply concentration in German and Japanese optical glass manufacturing shapes which technology tiers can achieve cost competitiveness at institutional scale.
- Optical:Conventional refractive systems with achromatic and plan-apochromatic objective grades still constitute the majority of shipments to price-sensitive markets. Japanese specialty glass manufacturers control premium objective substrates, constraining margin flexibility.
- Software-Integrated:Bundled platforms combining hardware with measurement algorithms, annotation layers, and cloud storage are capturing disproportionate margin pools through recurring license structures. US university procurement offices favor these consolidated vendor relationships.
- Electronic:CMOS and CCD sensor-based digital imaging modules require substantial re-engineering of legacy optical architectures to maintain path stability.
- High-Definition:4K and higher resolution imaging targets clinical training programs where diagnostic-grade visualization standards apply.
Optical technology leads unit volumes; software-integrated platforms expand most quickly in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical engineering traditions established modern microscopy manufacturing in the late 19th century, with Carl Zeiss AG and Ernst Leitz (now Leica Microsystems) pioneering precision lens grinding for scientific instruments. This heritage concentrated specialized glassmaking expertise in the Wetzlar-Jena corridor, creating supply chain dependencies that persist across institutional procurement channels worldwide.
United States
STEM grant funding from the National Science Foundation accelerates digital microscope adoption in K-12 districts and community colleges. EPA energy-efficiency guidelines for laboratory equipment mandate LED illumination retrofits and standby power thresholds below 1 watt. The Greater Boston research cluster concentrates demand from Harvard and MIT teaching laboratories, where software-integrated platforms with cloud specimen sharing dominate procurement specifications.
Germany
REACH compliance harmonization streamlines cross-border tender processes for microscope suppliers serving multiple EU member states. The Wetzlar-Jena optical corridor anchors premium objective lens manufacturing, with Schott AG controlling specialty glass substrates for achromatic and plan-apochromatic configurations. Bavarian technical universities drive demand for fluorescence-equipped research training microscopes aligned with clinical credentialing programs.
China
National curriculum reforms under the Ministry of Education prioritize laboratory infrastructure in public secondary schools across 31 provincial jurisdictions. MIIT standards for educational equipment safety filter market access for imported microscopy systems. The Yangtze River Delta manufacturing belt around Shanghai concentrates domestic production of entry-level compound microscopes for bulk institutional tenders in tier-2 and tier-3 cities.
India
The National Education Policy directs technical skills development funding toward vocational training institutes in tier-2 and tier-3 cities, expanding addressable demand for mid-range digital systems. BIS certification requirements for laboratory equipment create compliance barriers for unverified imports. State education boards in Maharashtra and Karnataka execute centralized procurement for public secondary school biology laboratories under STEM curriculum mandates.
Japan
METI industrial policy supports precision optics manufacturing through JIS standardization and research consortia linking Olympus and Nikon with university engineering departments. PMDA medical device standards for clinical training microscopes elevate product liability documentation that manufacturers voluntarily extend to education SKUs. The Kansai manufacturing corridor around Osaka maintains captive supply chains for CMOS sensor modules integrated into wireless digital microscopy platforms.
Education Microscope Market Competitive Landscape
The competitive structure tilts toward heritage optical manufacturers with century-scale brand equity in university research clusters. Three tiers separate premium instrument makers commanding 40-60% gross margins on software-integrated platforms from price-competitive assemblers serving emerging market bulk tenders. Strategic archetypes include: (1) vertically integrated specialists controlling glass-to-finished-product pipelines; (2) electronics-first entrants re-engineering legacy optical architectures around CMOS sensors; and (3) regional fabricators leveraging labor cost advantages for mechanical stage and illumination assembly. Dominant competitive moves encompass multi-year service contract bundling that locks institutional purchasing departments into recurring revenue relationships, and backward integration into LED illumination module production to capture energy-efficiency compliance premiums.
Within the heritage optical tier, ZEISS Group and Nikon Corporation exemplify manufacturers whose brand equity in research-grade instrumentation extends into education procurement channels. Motic Microscopes occupies a position among price-performance competitors targeting volume institutional tenders in emerging markets. Olympus Corporation anchors the service-network archetype, with multi-year calibration and software update commitments displacing transactional hardware sales in European university clusters. These three company types collectively represent the strategic positioning spectrum visible across the supplier base.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| ZEISS Group |
| Nikon Corporation |
| Olympus Corporation |
| Leica Microsystems |
| JEOL Ltd |
| Bruker Corporation |
| Meiji Techno |
| Motic Microscopes |
| Others |
Value Network & Pricing Analysis
Multi-year service contract bundling in European university procurement is forcing manufacturers to restructure cost allocation across hardware and recurring software licenses, compressing upfront margins while extending revenue recognition timelines. This shift rewards suppliers with captive LED illumination module production and in-house calibration infrastructure, penalizing pure-play assemblers dependent on third-party component sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates software-integrated platforms with cloud subscriptions from standalone optical units and entry-level compound systems. Price differentiation hinges on ISO 10901 certification grade and after-sales service bundling depth. Cost compression in the economy tier is intensifying because Indian state education boards consolidate bulk tenders around total cost of ownership metrics. K-12 districts in emerging markets exhibit highest price sensitivity; research universities in the US and Germany show lowest sensitivity to unit pricing when multi-year curriculum alignment is guaranteed.
Supply Chain Analysis
Freight cost volatility from German and Japanese optical glass manufacturers to assembly hubs in China and Vietnam is elevating landed cost uncertainty for premium objective lens substrates. Manufacturing concentration in Germany, Japan, and China draws from specialty glassmaking in the Wetzlar-Jena corridor, CMOS sensor fabrication in the Kansai belt, and mechanical stage assembly in the Yangtze River Delta. Single-source vulnerability in achromatic objective substrates from Schott AG and Ohara Corporation exposes procurement budgets to extended lead time risk. Distribution runs through institutional purchasing departments and centralized state education board tenders rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where German optical heritage commands premium positioning in North American and European research clusters, while Chinese and Indian manufacturing cost structures capture volume in emerging market bulk tenders.
For Market Incumbents: Extend service-network density in tier-2 and tier-3 Indian cities to preempt Motic Microscopes' price-performance positioning. Deepen backward integration into LED illumination module production to capture EPA energy-efficiency compliance premiums and defend margin structure against electronics-first entrants re-engineering around CMOS sensors.
For New Entrants and Emerging Players: Vocational training institutes in Maharashtra and Karnataka state education board jurisdictions represent the most penetrable buyer archetype, with under-served demand for mid-range digital systems between K-12 durability and university software complexity. Target forensic science programs at US community colleges through specialized polarized light configurations as a curriculum-differentiated entry wedge.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated specialists controlling glass-to-finished-product pipelines and captive calibration service networks. Long-term viability favors acquisition targets with ISO 10901 certification infrastructure and established relationships with Indian state procurement boards. The signal to watch is consolidation in European university purchasing departments toward single-vendor multi-decade contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Illumination | Captures EPA energy-efficiency compliance premiums and reduces component cost volatility. |
| Software-Integrated Platform Launch | Locks university procurement into recurring license structures beyond hardware replacement cycles. |
| Multi-Year Service Contract Expansion | Concentrates supplier selection authority at central administrative levels in European research clusters. |
| Geographic Manufacturing Footprint Shift | Positions assembly capacity near Indian state education board tender jurisdictions to reduce logistics exposure. |
| AI-Powered Image Analysis Development | Differentiates premium education platforms through automated cell counting and anomaly detection capabilities. |
Research Methodology
Bottom-up institutional procurement modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with biology department heads, state education board procurement officers, university purchasing committee administrators, and microscope distributor technical sales teams were validated against secondary sources including MIIT educational equipment safety filings, EPA laboratory equipment efficiency certifications, BIS laboratory equipment standards documentation, and ISO 10901 compliance registries. This triangulation ensures volume estimates align with documented tender awards and import records.
Historical trendline analysis of replacement cycle compression and digital platform displacement patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, end-user tier, application discipline, and technology architecture. CAGRs were derived from weighted average of institutional budget growth trajectories and supplier pricing trajectory assumptions. Forecast inputs incorporated STEM curriculum mandate implementation timelines in India and China, and REACH compliance harmonization progression across EU member states.
Inputs from state education board tender databases and university procurement office contract disclosures were available through the study window; gaps in real-time inventory positioning at distributor level introduce uncertainty bands around quarterly volume estimates. Forecasts reflect documented assumptions regarding digital platform adoption curves and regulatory compliance timeline adherence. Stakeholders should weight assumptions against their own operating context and institutional customer concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Intraoral Scanners Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
Pancreatic and Biliary Stents Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
Dermal Allograft Market