
 Robotics-Assisted Telesurgery Market | 2026-2036
Robotics-Assisted Telesurgery Market Size, Share, and Industry Trends Forecast 2026-2036
Robotics-Assisted Telesurgery Market Analytics
Hospital procurement channels for capital surgical equipment is tilting toward bundled telerobotic service contracts rather than standalone system sales. Intuitive Surgical leverages its installed base of da Vinci systems to extend into telepresence-enabled surgical workflows. Stryker anchors its position through orthopedic-focused robotic platforms with modular teleoperation capabilities. Siemens Healthcare competes by integrating imaging systems with real-time data transmission protocols for remote surgical guidance.
Robotics-assisted telesurgery denotes surgical procedures performed by a surgeon at a physical distance from the patient, using robotic manipulators with sub-millimeter precision, haptic feedback latency under 200 milliseconds, and encrypted broadband connectivity to translate hand motions across geographic separation. The primary purpose is to deliver specialist surgical expertise to underserved locations without physical relocation of personnel or patients. Robotic Systems command the dominant share of product type revenue due to high capital intensity and multi-year depreciation cycles, while Imaging Systems represent the fastest-growing segment as 4K-8K visualization standards become mandatory for remote tissue differentiation. Among applications, General Surgery occupies the broadest addressable case volume, though Urology sustains premium pricing through prostate and kidney procedure complexity.
FDA premarket notification pathways and EU MDR Class III certification requirements shape product development timelines and market access costs for telesurgical platforms. The national pharmaceutical regulator in Japan and Health Canada impose additional clinical evidence standards for remote-control surgical devices that delay cross-border rollout. Stakeholders must monitor evolving 5G network reliability standards and spectrum allocation policies, as telecommunications infrastructure quality directly determines where telesurgical services become commercially viable.
Market Dynamics
Hospital procurement of telerobotic suites is tilting toward bundled service contracts that wrap capital equipment, connectivity infrastructure, and per-procedure licensing into multi-year agreements. This shift compresses vendor cash conversion cycles while locking in long-term customer relationships across distributed surgical networks.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for cross-border surgical platforms accelerate commercialization timelines and reduce premarket notification uncertainty for developers seeking US market entry.
- 5G Network Deployment:Telecommunications carriers are prioritizing ultra-reliable low-latency communication slices for healthcare applications, enabling haptic feedback transmission under 200 milliseconds in rural coverage zones.
- Rural Health System Access Gaps:Geographic concentration of specialist surgeons in academic medical centers creates pull demand for hub-and-spoke telesurgical models that extend procedural capacity to underserved communities.
Market Restraints
- EU MDR Class III Certification Burden:Conformity assessment requirements for active implantable surgical devices impose substantial clinical evidence costs and extended notified body queue times that delay EU market entry.
- Capital Equipment Depreciation Cycles:Multi-year amortization schedules for robotic surgical systems constrain hospital capital budgets and extend replacement intervals beyond typical technology refresh rates.
- Broadband Infrastructure Inequality:Fiber-optic backbone gaps in mountainous and remote regions limit addressable market expansion regardless of regulatory clearance status.
Strategic Opportunities
- Orthopedic Procedure Expansion:Modular teleoperation capabilities on joint replacement platforms open addressable case volumes beyond soft-tissue specialties into spine and trauma applications.
- Japan PMDA Streamlined Pathways:Sakigake designation system for regenerative medicine and innovative medical devices offers accelerated approval timelines for first-in-class telesurgical systems.
- 4K-8K Visualization Convergence:Integration of high-resolution imaging standards with real-time data transmission protocols enables remote tissue differentiation capabilities that match on-site surgical precision.
Industry Challenges
- Haptic Feedback Engineering Talent Scarcity:Specialized expertise in force-feedback algorithm development and tactile sensor calibration concentrates in limited geographic clusters, constraining R&D scaling.
- Cross-Border Malpractice Liability Framing:Unclear jurisdictional allocation of surgical responsibility between remote operator, local assistant, and platform manufacturer complicates insurance underwriting and risk transfer mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotics-Assisted Telesurgery Market |
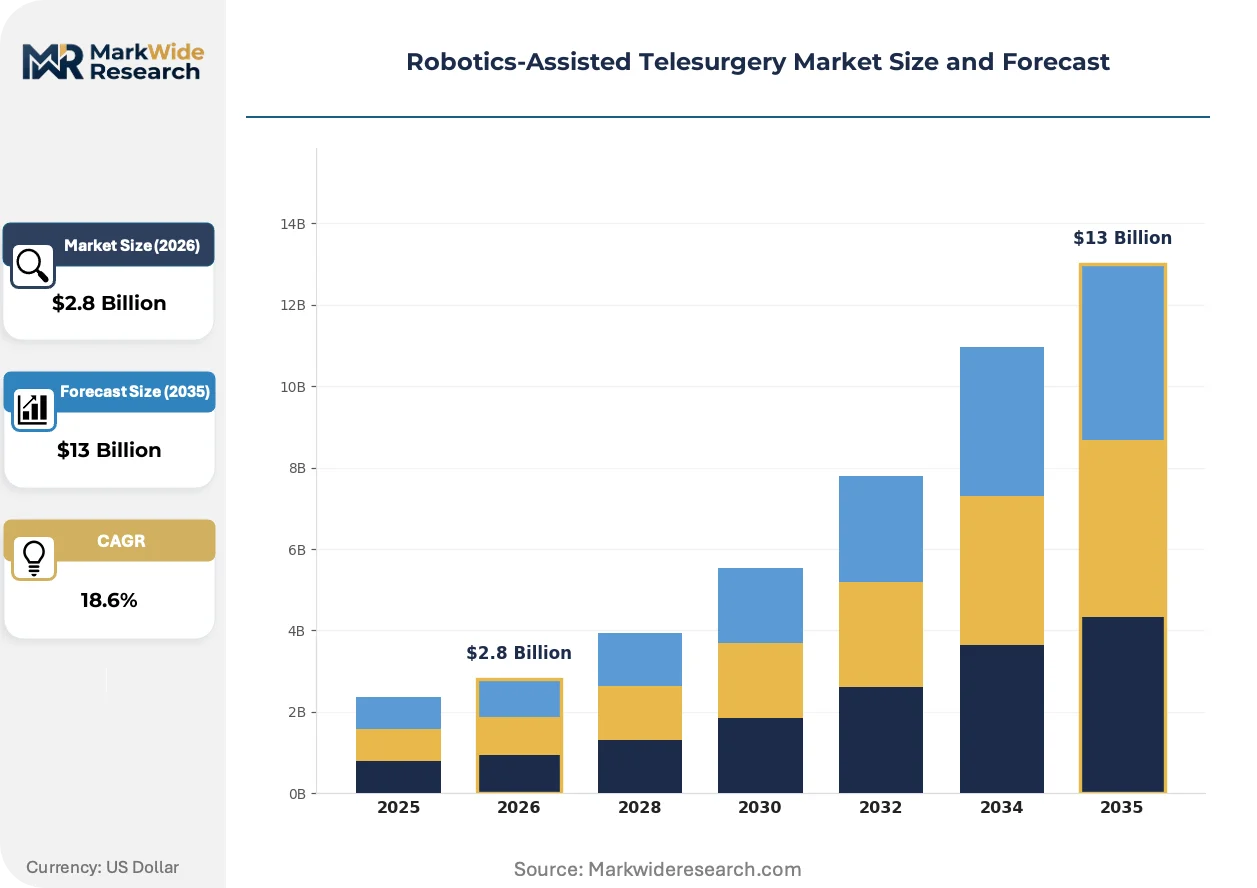
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Surgical Instruments, Imaging Systems, Ancillary Devices End User: Hospitals, Ambulatory Surgical Centers, Research Institutions, Clinics Technology: Telecommunication Technology, Visualization Technology, Control Systems, Feedback Mechanisms Application: General Surgery, Orthopedics, Urology, Gynecology |
| Companies Covered | Intuitive Surgical, Asensus Surgical US, CMR Surgical Ltd, Sina Robotics & Medical Innovators Co, SS Innovations International, RIVERFIELD Inc, MicroPort, Siemens Healthcare, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotics-Assisted Telesurgery Market Evolving Landscape
Telepresence-enabled surgical workflows are compressing the physical distance between specialist expertise and patient need. Three converging developments are restructuring how robotic platforms deliver remote procedural capability.
Edge computing architectures are virtualizing surgical control systems by distributing processing loads between hospital-site robotic manipulators and cloud-based analytics engines. Academic medical centers in the United States are piloting these distributed architectures to reduce on-premise server requirements while maintaining sub-100 millisecond command latency. This virtualization is enabling smaller rural facilities to host telesurgical procedures without dedicated IT infrastructure investments.
EU MDR conformity assessment requirements for active implantable surgical devices are tightening clinical evidence standards for telesurgical platforms seeking European market access. Notified bodies are demanding extended follow-up data on remote procedure outcomes that extend premarket submission timelines by 18-24 months. Surgical robotics manufacturers are responding by front-loading clinical trials in Germany and France to build EU-specific evidence dossiers ahead of formal applications.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, negotiating standalone technical support agreements with third-party clinical engineering firms. This disintermediation is most visible in the United States, where health system consolidation has concentrated buying power and enabled direct sourcing of maintenance services independent of original equipment manufacturers.
Robotics-Assisted Telesurgery Market Segmentation
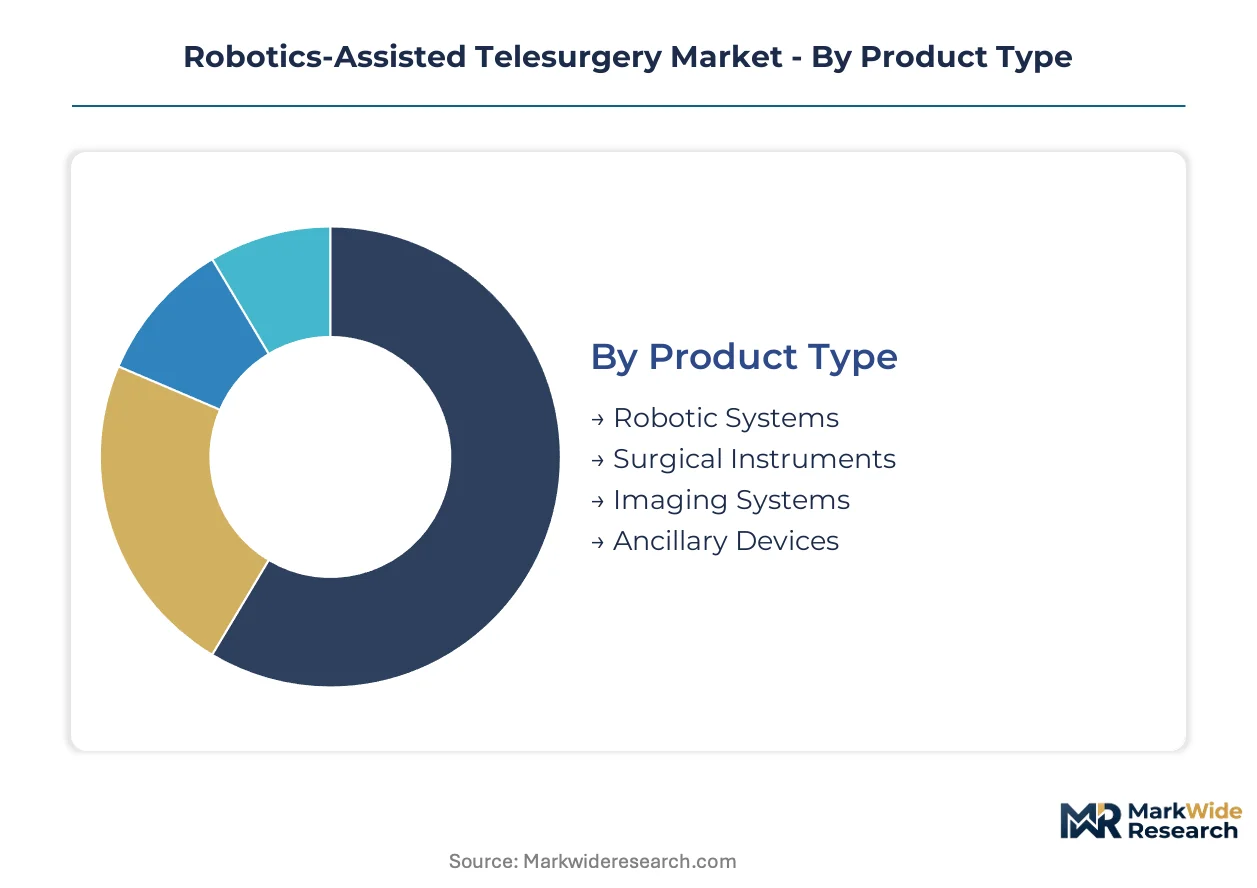
Segmentation in robotics-assisted telesurgery reveals distinct capital intensity profiles across equipment categories and sharply divergent procurement cycles between hospital networks and outpatient facilities. Understanding these structural differences enables vendors to align product roadmaps with replacement timelines and service contract structures.
Product Type:
Depreciation cycles range from multi-year capital equipment amortization for robotic platforms to rapid refresh rates for disposable instruments and visualization hardware.
- Robotic Systems:Capital-intensive manipulator arms with sub-millimeter precision motors and haptic feedback arrays command extended procurement timelines. Hospital networks in the United States negotiate bundled service contracts spanning 7-10 years, with replacement decisions tied to FDA clearance status for next-generation platforms.
- Imaging Systems:4K-8K visualization standards are accelerating replacement of legacy camera stacks as remote tissue differentiation becomes clinically mandatory. Academic medical centers in Germany and France are front-loading procurement of high-resolution transmission protocols to meet EU MDR evidence requirements for cross-border surgical guidance.
- Surgical Instruments:Disposable and limited-use end effectors with integrated sterilization tracking.
- Ancillary Devices:Patient-side carts, insufflation units, and energy platforms with modular teleoperation interfaces.
Robotic Systems dominates installed base. Imaging Systems is where expansion concentrates.
End User:
Procurement authority concentrates in consolidated health systems with centralized capital committees, while smaller facilities rely on group purchasing organizations.
- Hospitals:Integrated delivery networks with hub-and-spoke surgical models anchor procurement volume. Rural hospital affiliates in the United States are deploying telerobotic suites through shared service agreements with academic medical center hubs, bypassing standalone capital acquisition.
- Ambulatory Surgical Centers:Outpatient joint replacement and hernia repair facilities are adopting leased telepresence configurations to access specialist expertise without full-time robotic capital deployment. Medicare reimbursement parity for remote-assisted procedures is accelerating ASC adoption in Texas and Florida markets.
- Research Institutions:Clinical trial sites and surgical training centers with simulation infrastructure.
- Clinics:Specialty urology and gynecology practices with limited procedure volume.
Hospitals command procurement volume leadership. Ambulatory Surgical Centers are climbing the fastest.
Technology:
Development investment clusters around latency reduction and tactile fidelity, with telecommunications infrastructure quality determining commercial viability geography by geography.
- Telecommunication Technology:5G network slices with ultra-reliable low-latency communication enable haptic feedback transmission under 200 milliseconds. Telecommunications carriers in Japan and South Korea are prioritizing healthcare-grade spectrum allocation ahead of commercial telesurgical rollout.
- Control Systems:Distributed edge computing architectures virtualize surgical command processing between hospital-site manipulators and cloud analytics engines. Academic medical centers in the United States are piloting these configurations to reduce rural facility IT infrastructure requirements.
- Visualization Technology:Real-time 4K-8K video compression with artifact-free transmission.
- Feedback Mechanisms:Force-sensing algorithms and tactile sensor calibration for remote tissue manipulation.
Telecommunication Technology determines addressable market geography. Control Systems is where R&D investment concentrates.
Application:
Procedure complexity and reimbursement levels create divergent margin profiles across surgical specialties, with soft-tissue applications leading deployment scale.
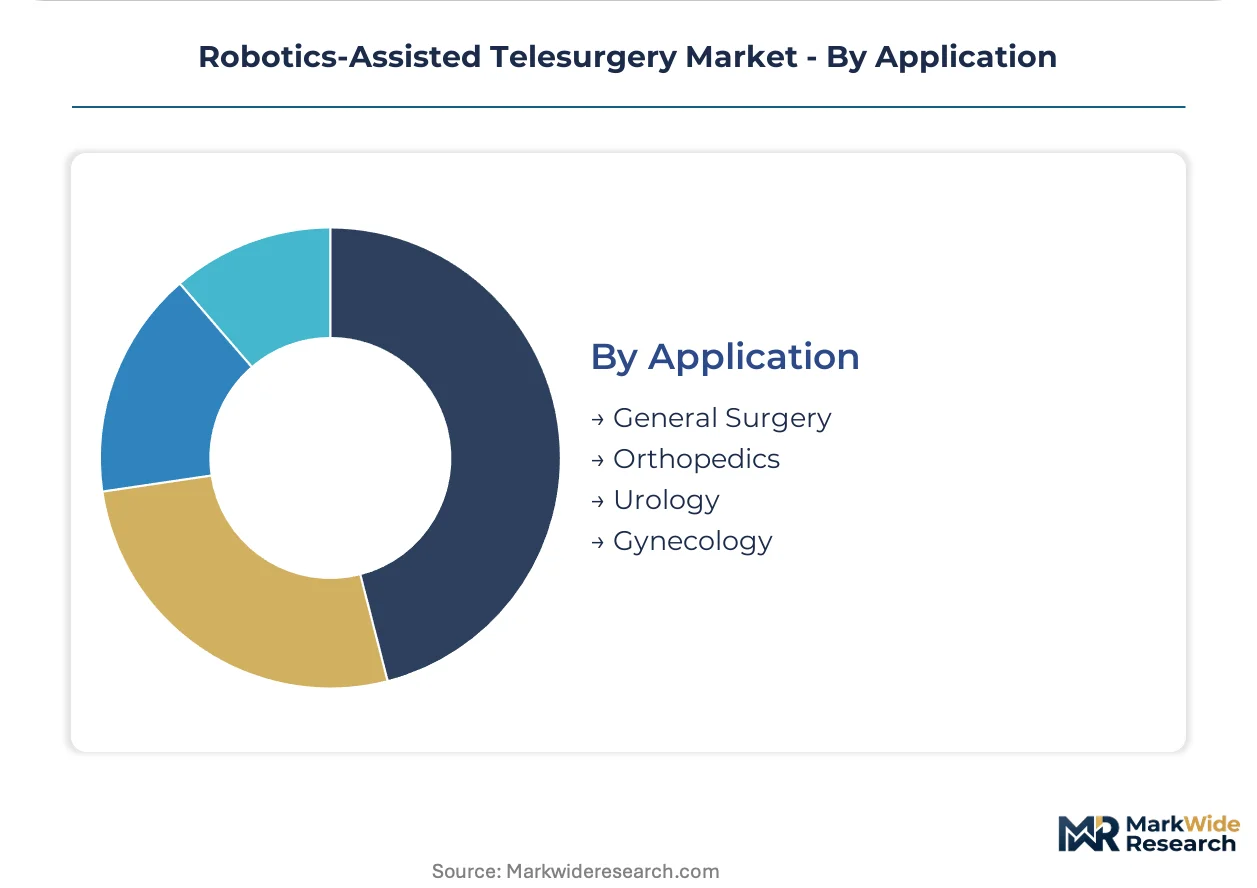
- General Surgery:Hernia repair, cholecystectomy, and colorectal procedures constitute the broadest addressable case volume. Hospital networks are standardizing telerobotic protocols for routine abdominal surgeries to extend specialist capacity across distributed sites.
- Urology:Prostatectomy and partial nephrectomy complexity sustains premium pricing for remote surgical platforms. Tertiary referral centers in France and Germany are concentrating telesurgical expertise for oncologic urology procedures.
- Orthopedics:Joint replacement and spine procedures with modular teleoperation capabilities.
- Gynecology:Hysterectomy and myomectomy with established robotic surgical workflows.
General Surgery leads procedure volume. Urology sustains premium pricing concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where bundled telerobotic service contracts command premium terms, while European markets absorb compliance cost premiums from MDR certification burdens that compress vendor margins.
United States
Rural health system access gaps and academic medical center hub-and-spoke models drive concentrated procurement of telerobotic suites. FDA breakthrough device designations accelerate commercialization timelines for cross-border surgical platforms. Hospital networks in Texas and Florida deploy shared service agreements that bypass standalone capital acquisition for rural affiliates.
Germany
Tertiary referral centers concentrate telesurgical expertise for oncologic procedures while front-loading clinical trials to build EU-specific evidence dossiers. EU MDR Class III certification requirements impose extended notified body queue times that delay market entry. The Baden-Württemberg industrial cluster anchors precision manufacturing of haptic feedback arrays for robotic manipulators.
Japan
Telecommunications carriers prioritize healthcare-grade spectrum allocation for ultra-reliable low-latency communication slices. PMDA Sakigake designation offers accelerated approval timelines for first-in-class telesurgical systems. Tokyo-based academic medical centers pilot distributed edge computing architectures to reduce rural facility IT infrastructure requirements.
France
Academic medical centers concentrate telesurgical expertise for complex urology procedures while negotiating bundled service contracts spanning 7-10 years. ANSM clinical evidence standards for remote-control surgical devices shape premarket submission timelines. The Paris-Saclay cluster advances 4K-8K visualization standards for remote tissue differentiation capabilities.
South Korea
5G network deployment prioritizes ultra-reliable low-latency communication infrastructure for healthcare applications. MFDS imposes additional clinical evidence standards that delay cross-border rollout of remote surgical platforms. Seoul-based health systems deploy telerobotic suites through multi-year agreements that wrap capital equipment and connectivity infrastructure.
Robotics-Assisted Telesurgery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision motors, haptic sensors, and visualization hardware. The vendor base organizes around three archetypes: diversified medical technology conglomerates with installed base leverage, pure-play surgical robotics developers with modular teleoperation capabilities, and imaging-system integrators with real-time data transmission protocols. Consolidation pressure intensifies as hospital procurement tilts toward bundled service contracts requiring end-to-end platform ownership. Competitive moves center on M&A to acquire haptic feedback engineering talent and strategic partnerships with telecommunications carriers to secure dedicated network slices.
Within the diversified conglomerate tier, Intuitive Surgical and Stryker occupy positions shaped by installed base leverage and orthopedic-focused platform development respectively. Siemens Healthcare represents the imaging-system integrator archetype, anchoring competitive positioning through convergence of visualization standards with transmission protocols. CMR Surgical Ltd exemplifies the pure-play developer model with modular teleoperation capabilities. These three companies collectively illustrate how vendor strategy diverges between capital equipment amortization cycles and per-procedure licensing revenue streams.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Asensus Surgical US |
| CMR Surgical Ltd |
| Sina Robotics & Medical Innovators Co |
| SS Innovations International |
| RIVERFIELD Inc |
| MicroPort |
| Siemens Healthcare |
| Stryker |
| Others |
Value Network & Pricing Analysis
Undercapacity in precision haptic sensor fabrication across the Baden-Württemberg cluster is compressing supplier margins while amplifying pricing leverage for integrated platform vendors. Hospital procurement committees exploit this asymmetry by demanding bundled service contracts that internalize connectivity infrastructure costs.
Pricing Analysis
Configured-to-order pricing for telerobotic suites commands a 40-60% premium over standard configurations with fixed instrument sets. Subscription-based licensing with per-procedure fees dominates hospital network procurement, though ambulatory surgical centers favor capital leases with maintenance wrap. Price differentiation hinges on FDA breakthrough designation status and 5G network slice guarantees. Cost compression in imaging system tiers is intensifying because 4K-8K camera stack commoditization erodes hardware margins. Academic medical centers exhibit lowest price sensitivity due to grant-funded acquisition channels; rural hospital affiliates face acute budget constraints that drive shared-service negotiations.
Supply Chain Analysis
Export controls on precision servo motors and force-feedback algorithms under US EAR Category 9 restrictions limit technology flows to Chinese and Russian end-users. Component manufacturing concentrates in Germany, Japan, and the United States for haptic arrays; Taiwan and South Korea supply high-resolution image sensors. Supply chains draw from rare earth magnets for motor assemblies, gallium nitride semiconductors for power electronics, and medical-grade stainless steel for instrument shafts. Single-source vulnerability in haptic feedback engineering talent clusters constrains R&D scaling. Distribution runs through hospital group purchasing organizations and direct OEM contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-assisted autonomous surgical systems that reduce reliance on real-time remote operator expertise. Defense requires pre-emptive platform evolution rather than reactive pricing adjustments.
For Market Incumbents: Pre-empt autonomous surgical system substitution by embedding predictive analytics modules into existing telepresence workflows. Backward integration into haptic sensor manufacturing mitigates supply concentration risk in Baden-Württemberg. Lock rural hospital affiliates into 10-year exclusive service contracts before reimbursement parity expands to ASC competitors. For New Entrants and Emerging Players: Southeast Asian hospital networks with nascent robotic surgery programs represent the most penetrable white-space opportunity. Target modular teleoperation retrofit kits for legacy laparoscopic towers rather than competing head-to-head with integrated platforms. Pursue Japan PMDA Sakigake designation as a regulatory fast-track to anchor credibility before US FDA submission. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across imaging system sub-segments as 4K-8K camera commoditization accelerates. Long-term viability favors platform integrators with installed base leverage over pure-play component suppliers. Monitor 5G network reliability standards in rural coverage zones as the critical inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review compresses commercialization timelines for cross-border surgical platforms. |
| Hospital System Partnership | Hub-and-spoke agreements lock in multi-year revenue streams across distributed surgical networks. |
| 5G Network Slice Reservation | Telecommunications carrier partnerships secure ultra-reliable low-latency communication infrastructure. |
| Haptic Feedback Talent Acquisition | Specialized engineering expertise concentrates in limited geographic clusters requiring targeted recruitment. |
| EU MDR Clinical Evidence Build | Front-loaded trials in Germany and France accelerate notified body queue navigation. |
Research Methodology
The analysis maps robotic systems, imaging systems, surgical instruments, and ancillary devices, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at surgical robotics manufacturers. Primary interview insights triangulate against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and telecommunications carrier 5G deployment disclosures. Bottom-up installed base counts reconcile with top-down capital expenditure estimates across academic medical center networks.
Assumptions held fixed include 5G network reliability standards, FDA premarket notification pathway timelines, and EU MDR notified body capacity; variables tested include rural health system reimbursement parity and haptic feedback algorithm licensing costs. Segmentation dimensions span product type, end user, technology, and application with geographic regulatory cluster overlays. CAGRs derive from logistic diffusion curves fitted to historical robotic surgery adoption patterns, with inputs including hospital capital budget cycles and specialist surgeon geographic distribution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by autonomous surgical system developers would shift outcomes beyond modeled ranges. Material shifts in 5G spectrum allocation policy or EU MDR conformity assessment timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
Global Hi-Tech Medical Devices Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Pleural Cavity Drainage Market
Medical Devices
Implantable Port Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Pressure Ulcer Devices Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
South Korea ECG Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market