
 Pulse Electromagnetic Field (PEMF) Therapy Devices Market | 2026-2036
Pulse Electromagnetic Field (PEMF) Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pulse Electromagnetic Field (PEMF) Therapy Devices Market Analytics
Multi-source component procurement is restructuring supply economics for PEMF device manufacturers. Medithera GmbH anchors its German production base with in-house coil winding capabilities. Swiss Bionic Solutions leverages a distributed European supplier network for control module assembly. Orthofix Medical Inc. competes through specialized clinical sales channels tied to orthopedic practices.
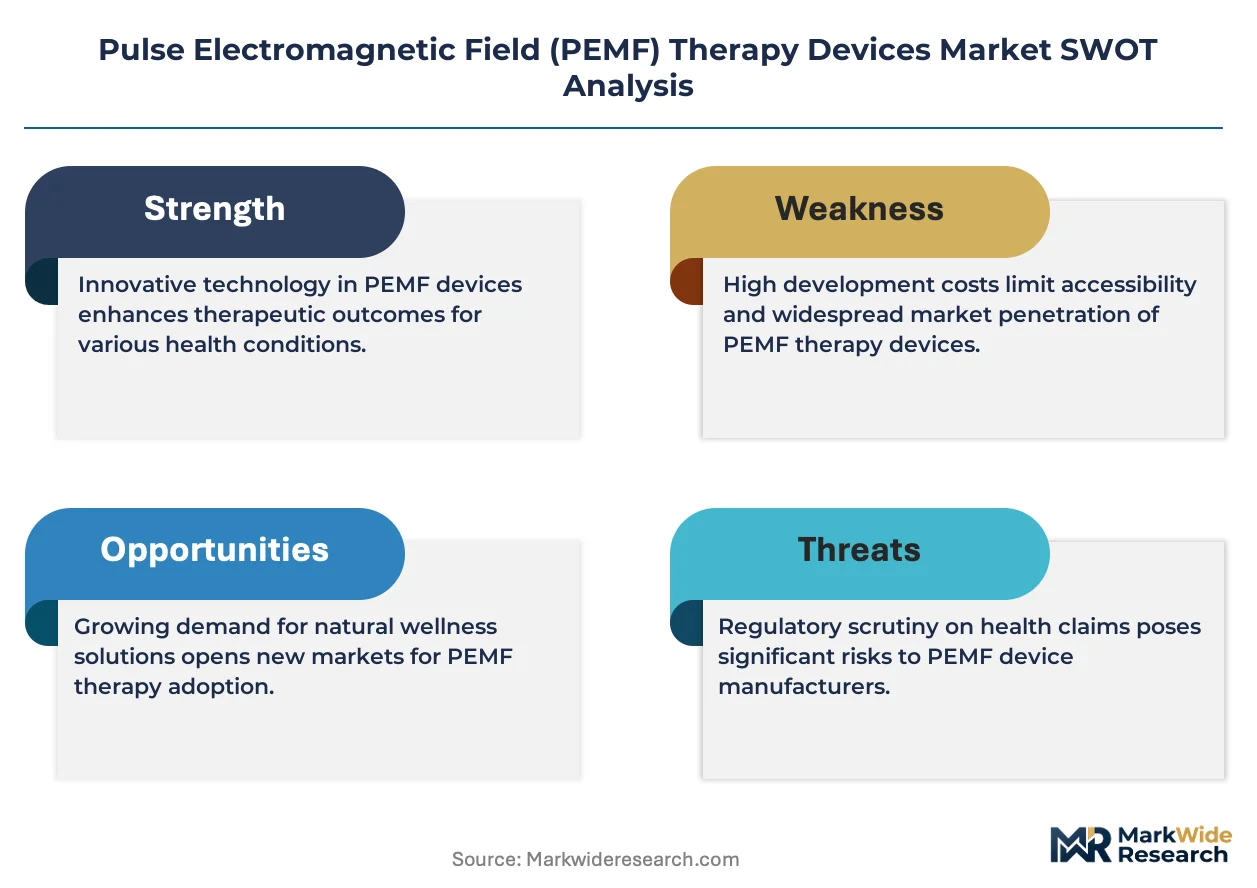
Pulse electromagnetic field therapy devices generate time-varying magnetic fields at frequencies typically between 1 Hz and 100 Hz to induce microcurrents in biological tissues. These systems employ copper or ferrite-core applicators driven by solid-state pulse generators to modulate cellular membrane potential and calcium ion flux. Portable devices and home systems capture expanding margin pools as direct-to-consumer channels reduce clinical dependency. Pain management applications dominate volume, while bone healing commands premium pricing through orthopedic reimbursement codes. Low-frequency and biphasic square wave technologies lead installed base, though high-frequency platforms gain traction in sports medicine settings.
The FDA oversees Class II medical device clearances under 510(k) pathways, while the EMA's Medical Device Regulation imposes clinical evidence requirements for European market access. ISO 13485 quality management standards govern manufacturing audits across both jurisdictions. Germany's BSI and TÜV Süd serve as notified bodies for CE marking conformity assessments. Stakeholders must monitor evolving software-as-medical-device classifications for app-integrated PEMF controllers.
Market Dynamics
FDA Class II clearance pathways for neuromuscular stimulators compress product development timelines while German university hospitals integrate PEMF protocols into post-surgical rehabilitation workflows, reshaping clinical adoption curves.
Growth Catalysts
- Orthopedic reimbursement codes:Bone healing applications command premium pricing through specialized reimbursement frameworks in Germany and the United States, accelerating hospital procurement cycles.
- Sports medicine integration:University hospital rehabilitation programs now embed PEMF protocols into athlete recovery workflows, creating institutional demand anchors.
- Portable device technology:Solid-state pulse generators enable home-use systems that reduce clinical dependency while capturing expanding margin pools through direct-to-consumer channels.
Market Restraints
- Copper and ferrite-core supply concentration:Coil winding capabilities concentrate among specialized German and East Asian suppliers, creating input bottlenecks for applicator manufacturing.
- EMA Medical Device Regulation clinical evidence requirements:European market access demands extensive clinical documentation that extends regulatory timelines and elevates compliance costs.
- Pharmacological pain management substitutes:NSAID and opioid protocols retain physician familiarity and established reimbursement pathways in acute care settings.
Strategic Opportunities
- Home-use system penetration:Direct-to-consumer channels for portable PEMF devices remain underdeveloped in France and Spain relative to German market maturity.
- App-integrated controller convergence:Software-as-medical-device classifications create openings for smartphone-connected pulse generators that blend hardware with digital therapeutics.
- Veterinary orthopedic applications:Equine and companion animal rehabilitation protocols represent adjacent demand verticals with lighter regulatory burdens than human medical devices.
Industry Challenges
- ISO 13485 quality management certification timelines:Manufacturing audits across FDA and EMA jurisdictions require 12-18 month preparation cycles that delay market entry.
- Multi-frequency platform integration complexity:Engineering teams must reconcile low-frequency installed bases with high-frequency sports medicine specifications within unified product architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulse Electromagnetic Field (PEMF) Therapy Devices Market |
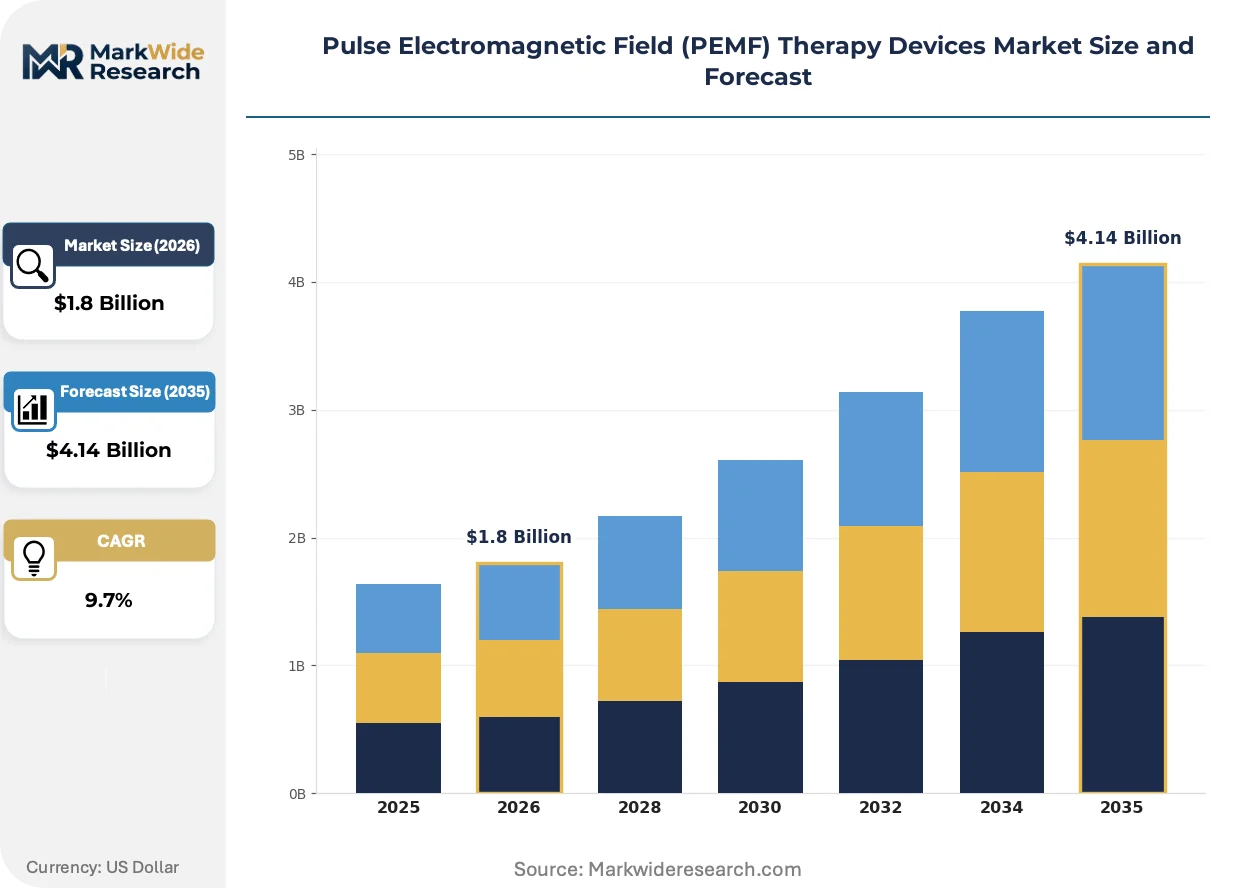
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Home Systems, Clinical Units, Commercial Solutions Application: Pain Management, Muscle Recovery, Bone Healing, Stress Reduction End User: Hospitals, Rehabilitation Centers, Sports Clinics, Home Users Technology: Low Frequency, High Frequency, Biphasic Square Wave, Pulsed Direct Current |
| Companies Covered | Medithera GmbH, Swiss Bionic Solutions, Orthofix Medical Inc., HealthyLine, OMI, BEMER Group, Oska Wellness, I-Tech Medical Division, Curatronic Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulse Electromagnetic Field (PEMF) Therapy Devices Market Evolving Landscape
PEMF device architecture is converging around digital control layers that modulate cellular membrane potential through software-defined pulse parameters rather than fixed hardware configurations.
Biphasic square wave generators are unifying pain management and bone healing applications within single hardware platforms. Orthopedic practices in Germany's Tübingen corridor adopt these dual-purpose systems to consolidate capital equipment budgets. The technology is unifying previously separate clinical workflows into integrated rehabilitation protocols.
The FDA's evolving 510(k) clearance pathways for software-as-medical-device classifications compress review timelines for app-integrated controllers. Manufacturers now embed Bluetooth-enabled pulse modulation algorithms that qualify for abbreviated premarket notification. Portable device segments respond fastest, leveraging predicate device strategies to accelerate market entry.
Clinical sales channel consolidation is compressing the traditional distributor hierarchy. Orthopedic practices increasingly source PEMF systems through specialized device representatives rather than broad-line medical distributors. Germany and Switzerland exhibit the most pronounced channel disintermediation, with manufacturer-direct contracting capturing share from regional distributors.
Pulse Electromagnetic Field (PEMF) Therapy Devices Market Segmentation
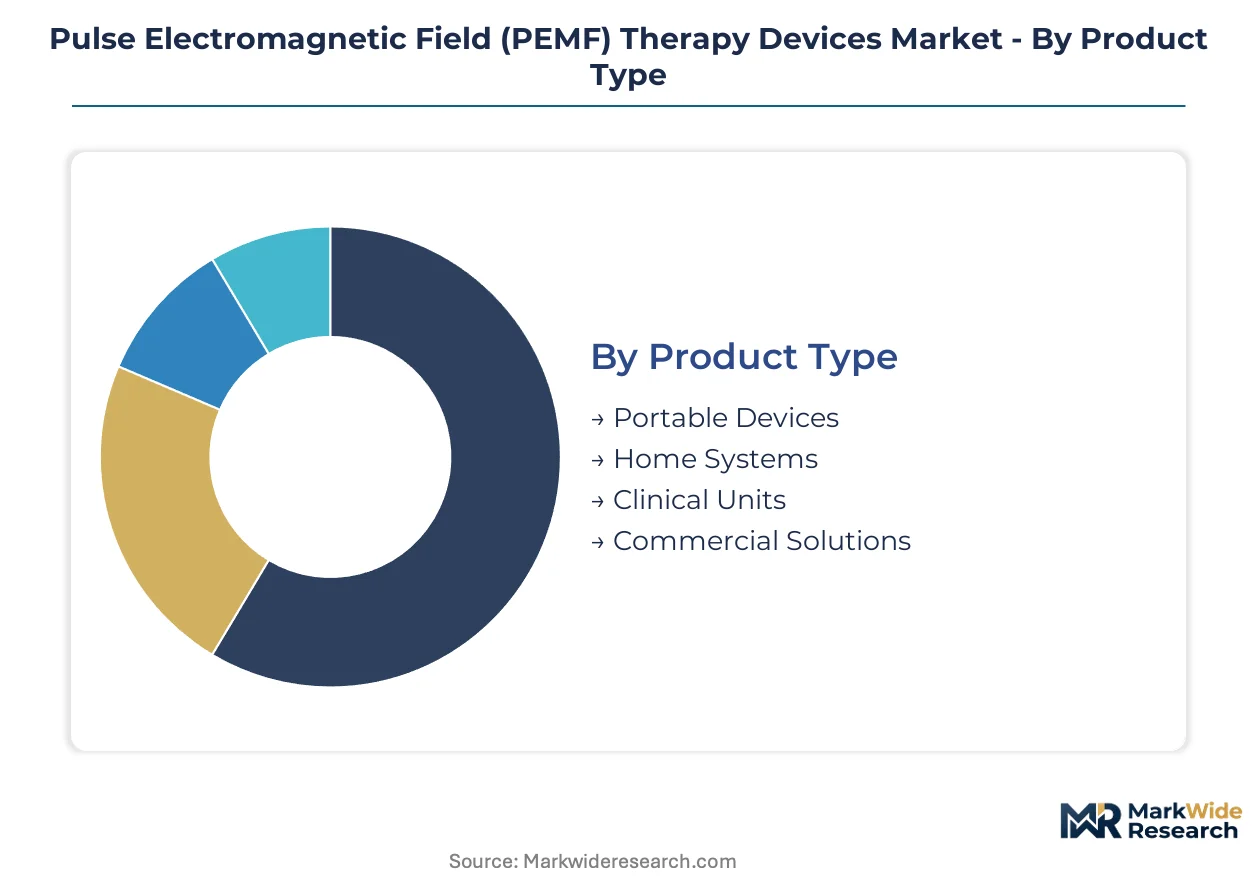
PEMF device segmentation reveals how hardware configurations, clinical settings, and waveform technologies partition purchasing authority and reimbursement pathways. Each dimension carries distinct margin profiles and regulatory obligations that shape manufacturer portfolio strategy.
Product Type:
Replacement cycles accelerate as solid-state electronics displace analog pulse generators, shortening hardware refresh timelines from seven years toward four-year intervals.
- Portable Devices:Battery-powered units with solid-state pulse generators deliver 1-100 Hz modulation through flexible applicator coils. Demand clusters in German sports medicine practices and US direct-to-consumer channels where mobility commands price premiums over stationary alternatives.
- Home Systems:Tabletop configurations with programmable treatment protocols target chronic pain patients seeking clinical independence. Reimbursement code limitations in France and Spain suppress penetration relative to German market maturity where private health supplements cover acquisition costs.
- Clinical Units:Multi-channel hospital installations serving orthopedic wards.
- Commercial Solutions:Wellness center and spa deployments with aesthetic positioning.
Volume placements concentrate in Portable Devices; the faster expansion belongs to Home Systems.
Application:
Cost tier separation widens as bone healing applications secure premium reimbursement while pain management competes against pharmacological substitutes.
- Pain Management:Post-operative and chronic neuropathic indications drive the largest addressable population. German rehabilitation centers embed these protocols into standard workflows, though NSAID familiarity among US physicians constrains prescription rates.
- Bone Healing:Non-union fracture and spinal fusion applications command the highest per-treatment pricing through dedicated orthopedic reimbursement codes. FDA 510(k) clearances for fracture healing indications require controlled clinical trials that extend development timelines.
- Muscle Recovery:Athletic performance and post-exertion protocols.
- Stress Reduction:Wellness-oriented applications with lighter clinical evidence requirements.
Revenue concentration sits with Bone Healing; Pain Management delivers the widest installed base expansion.
End User:
Customer type determines procurement channel structure, with institutional buyers demanding ISO 13485 certification and home users prioritizing app connectivity.
- Hospitals:Integrated into post-surgical rehabilitation workflows at German university hospitals. Capital equipment committees require health technology assessment documentation that favors established suppliers with clinical evidence portfolios.
- Rehabilitation Centers:Outpatient facilities with recurring patient throughput.
- Sports Clinics:Performance-focused installations with athlete-specific protocols.
- Home Users:Direct-to-consumer purchasers bypassing clinical gatekeepers.
Procurement authority concentrates in Hospitals; Sports Clinics are climbing the fastest as athletic program budgets expand.
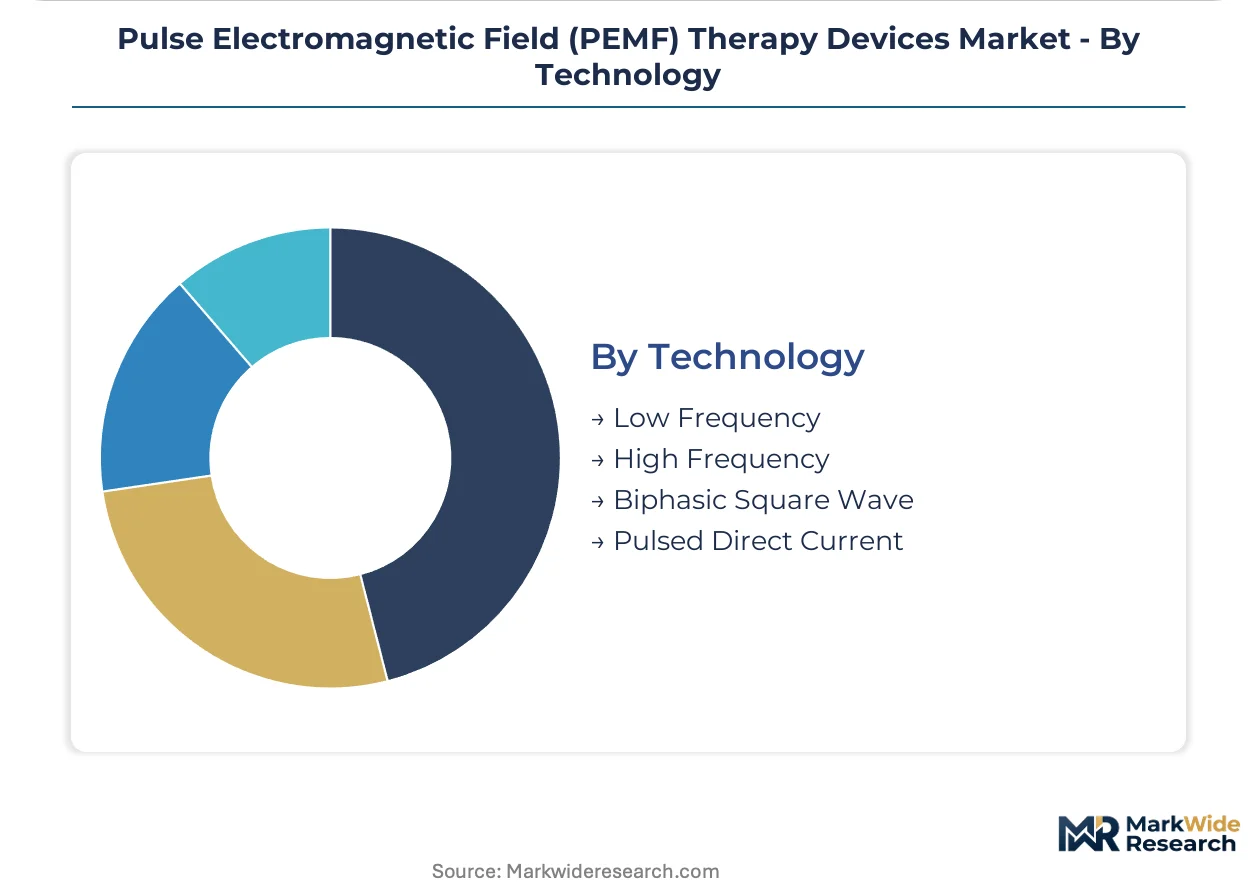
Technology:
Technology maturity separates installed base stability from next-generation platform development, with waveform architecture determining applicator design and software control requirements.
- Low Frequency:1-30 Hz sinusoidal and rectangular waveforms dominate existing installed bases through established clinical familiarity. Coil winding specifications concentrate among German and East Asian suppliers, creating input bottlenecks for manufacturers lacking captive winding capabilities.
- Biphasic Square Wave:Unified platforms serving pain and bone healing applications within single hardware configurations. Orthopedic practices in Germany's Tübingen corridor adopt these dual-purpose systems to consolidate capital budgets and reduce equipment redundancy.
- High Frequency:Sports medicine settings drive adoption above 30 Hz.
- Pulsed Direct Current:Specialized applications with distinct regulatory pathways.
Installed base dominance belongs to Low Frequency; Biphasic Square Wave platforms are gaining share fastest through dual-application consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and ferrite-core supply corridors in Germany's Baden-Württemberg region anchor European PEMF manufacturing capacity. Tübingen's medical technology cluster hosts specialized coil winding operations that feed applicator assembly across the continent. These input dependencies shape where device finalization occurs and which markets receive priority allocation.
United States
FDA 510(k) clearance pathways for neuromuscular stimulators attract orthopedic device manufacturers seeking abbreviated premarket review. The agency's evolving software-as-medical-device classifications compress timelines for app-integrated pulse generators. Post-surgical rehabilitation programs at university hospitals in Boston and Philadelphia embed PEMF protocols into athlete recovery workflows.
Germany
BSI and TÜV Süd serve as notified bodies for CE marking under the EMA's Medical Device Regulation, creating regulatory expertise concentration in Munich and Stuttgart. Private health supplements cover home system acquisition costs, accelerating penetration relative to neighboring markets. The Tübingen corridor anchors dual-purpose biphasic square wave adoption among orthopedic practices consolidating capital equipment budgets.
Switzerland
Swissmedic oversees medical device conformity assessments with streamlined pathways for Class II therapeutic equipment. Distributed European supplier networks enable control module assembly without captive manufacturing investments. Zurich and Basel host clinical sales operations that bypass traditional distributor hierarchies through manufacturer-direct contracting.
United Kingdom
Post-Brexit regulatory divergence from EU MDR frameworks creates dual compliance burdens for market entrants. NHS technology assessment documentation requirements favor established suppliers with clinical evidence portfolios. London rehabilitation centers drive outpatient demand for portable devices serving chronic pain populations.
Japan
PMDA marketing authorization pathways for therapeutic devices emphasize clinical trial data from domestic patient populations. METI industrial policy supports medical technology exports through standardized certification mutual recognition agreements. Osaka-based distributors serve as gatekeepers for Asian market expansion beyond domestic consumption.
Pulse Electromagnetic Field (PEMF) Therapy Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory certification and clinical sales channel access. The vendor base separates into three tiers: diversified orthopedic conglomerates with FDA clearance portfolios, European specialists with captive coil winding capabilities, and direct-to-consumer entrants leveraging abbreviated 510(k) pathways for portable systems. Dominant competitive moves include backward integration into applicator manufacturing and geographic expansion through specialized clinical representatives rather than broad-line distributors.
Within the European specialist tier, Medithera GmbH and Swiss Bionic Solutions exemplify contrasting supply chain strategies—captive German production versus distributed assembly networks. Orthofix Medical Inc. occupies a position among diversified orthopedic device manufacturers with established hospital contracting relationships. These three anchors illustrate how regulatory jurisdiction and manufacturing configuration determine competitive positioning across reimbursement-driven and direct-to-consumer segments.
| Leading Market Players |
|---|
| Medithera GmbH |
| Swiss Bionic Solutions |
| Orthofix Medical Inc. |
| HealthyLine |
| OMI |
| BEMER Group |
| Oska Wellness |
| I-Tech Medical Division |
| Curatronic Ltd. |
| Others |
Value Network & Pricing Analysis
Captive coil winding capabilities among German manufacturers anchor both supply security and pricing power for applicator assembly. Medithera GmbH's in-house production insulates against copper and ferrite-core volatility while supporting premium positioning for clinical-grade systems.
Pricing Analysis
Warranty and calibration service bundling separates clinical-grade PEMF systems from unbundled direct-to-consumer alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and applicator coil specifications. Pricing pressure stems from portable device commoditization in US direct-to-consumer channels where brand premiums erode against functional parity claims. Home users exhibit highest price sensitivity; orthopedic hospitals purchasing multi-channel installations prioritize clinical evidence portfolios over acquisition cost.
Supply Chain Analysis
Freight cost escalation from East Asian ferrite-core suppliers is compressing margins for European assemblers lacking captive winding operations. Coil winding capabilities concentrate in Germany and South Korea, with copper feedstock drawing from Chilean and Indonesian mining operations. Single-source vulnerability runs through specialized ferrite-core suppliers serving high-frequency sports medicine platforms. Distribution runs through specialized clinical representatives in Germany and Switzerland, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coil winding capacity scarcity props pricing for clinical-grade applicators, creating durable margin pools for manufacturers with captive production.
For Market Incumbents: Acquire specialized coil winding operations in Germany's Baden-Württemberg region to secure ferrite-core supply continuity. Backward integration into applicator manufacturing defends against East Asian supplier concentration while supporting ISO 13485 audit readiness for FDA and EMA submissions. For New Entrants and Emerging Players: Veterinary rehabilitation clinics represent an underserved buyer archetype with lighter regulatory burdens than human medical devices. France and Spain home-use markets show penetrable white space where reimbursement code limitations suppress incumbent presence. Direct-to-consumer channels with app-integrated controllers offer the fastest go-to-market pathway. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified orthopedic device manufacturers seeking FDA 510(k) clearance portfolios. Long-term viability hinges on software-as-medical-device convergence capabilities across the analysis window. Watch FDA software classification guidance updates as the critical inflection signal for platform valuation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR clinical evidence requirements extend timelines for European market access. |
| Hospital System Partnership | German university hospitals embed PEMF protocols into post-surgical rehabilitation workflows. |
| Software Companion Development | Bluetooth-enabled pulse modulation algorithms qualify for abbreviated FDA 510(k) review. |
| Reimbursement Strategy | Orthopedic reimbursement codes command premium pricing for bone healing applications. |
| Backward Integration | Captive coil winding insulates against copper and ferrite-core supply concentration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at orthopedic device manufacturers combined with FDA 510(k) databases, EMA MDR submission records, and hospital procurement databases. Bottom-up installed base estimates triangulated against top-down reimbursement code analysis.
Data-stream reconciliation across product type, application, end user, and technology segmentation dimensions shaped the analytical framework. CAGRs derived from weighted average of historical trajectory and adoption curve modeling across the projection horizon. Forecast inputs incorporated ISO 13485 certification timelines and software-as-medical-device classification evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software classification shifts and EMA MDR enforcement intensity. Forecasts reflect assumptions about reimbursement code stability and coil winding capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Lactation Massager Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Urine Collection Devices Market
Medical Devices
Fixed and Mobile C-Arms Market
Medical Devices
Global Pulmonary Drug Delivery Systems Market
Medical Devices
Organ Preservation Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Global Medical Loupes Market
Medical Devices
Cryoablation System Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market
Medical Devices
Breathing Circuits Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Cervical Disc Prosthesis Market
Medical Devices
Image-Based Cytometer Market