
 Drug and Gene Delivery Devices Market | 2026-2036
Drug and Gene Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Drug and Gene Delivery Devices Market Intelligence
The capability gap between integrated biopharma-device developers and standalone device suppliers is reorganizing competitive hierarchies in this market. Merck & Co. Inc. leverages its manufacturing scale across injectable systems for vaccine distribution. Medtronic plc anchors its position through implantable pump technology leadership in chronic therapy administration. Sarepta Therapeutics Inc. specializes in gene therapy delivery platforms for neuromuscular indications.
Drug and gene delivery devices are engineered systems designed to transport therapeutic agents—ranging from small molecules to nucleic acid constructs—across biological barriers at controlled release rates, typically achieving bioavailability targets through precision-engineered apertures, polymer matrices, or electro-mechanical actuation. These systems serve the primary commercial purpose of converting lab-validated drug candidates into clinically viable administration protocols that meet pharmacokinetic thresholds. Injectable systems dominate current revenue pools given their established reimbursement codes and manufacturing infrastructure, while microneedles represent the fastest-expanding segment as transdermal biologics delivery gains clinical validation. Cancer treatments command the largest therapy area allocation due to the volume of immuno-oncology agents requiring specialized administration.
The FDA's Center for Devices and Radiological Health and the European Medicines Agency's Medical Device Coordination Group jointly determine market access pathways through combination product designations and quality system inspections. The International Organization for Standardization's ISO 13485 framework governs manufacturing consistency, while the EU Medical Device Regulation imposes post-market surveillance obligations that extend device lifecycle accountability. Stakeholders must monitor evolving premarket review convergence between drug and device regulators to anticipate compliance cost structures.
Market Dynamics
The convergence of biologics pipelines with precision dosing requirements is compressing device development cycles and forcing contract manufacturers to absorb more regulatory risk on behalf of pharmaceutical sponsors.
Growth Catalysts
- EMA Adaptive Licensing:The European Medicines Agency's adaptive pathways framework accelerates gene therapy approvals, creating parallel demand for companion delivery systems validated under compressed timelines.
- Oncology Biologics Volume:Immuno-oncology agents requiring cold-chain injectable administration are expanding procurement budgets for pre-filled syringe and autoinjector platforms across hospital networks.
- Silicon Microneedle Fabrication:Advances in microelectromechanical systems manufacturing are enabling scalable production of dissolvable microneedle arrays for transdermal nucleic acid delivery.
Market Restraints
- Polymer Feedstock Concentration:Cyclic olefin polymer supply for primary packaging concentrates among Japanese and German chemical suppliers, exposing device makers to input cost volatility.
- ISO 13485 Audit Backlogs:Notified body capacity constraints under the EU Medical Device Regulation extend quality system certification timelines by twelve to eighteen months for new market entrants.
- Glass Syringe Substitution:Polymer-based primary containers are displacing borosilicate glass in high-value biologics, threatening specialized glass-forming equipment investments.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in India are building device assembly capabilities to capture gene therapy work migrating from high-cost geographies.
- Wearable Pump Convergence:Integration of continuous glucose monitoring algorithms with insulin delivery hardware creates adjacent positioning for multi-drug ambulatory infusion systems.
- Japan PMDA Sakigake:Japan's priority review designation for regenerative medicines accelerates reimbursement decisions, pulling early-stage device validation into Japanese clinical sites.
Industry Challenges
- Combination Product Expertise Gap:Cross-functional talent fluent in both pharmaceutical cGMP and device design controls commands premium compensation, constraining program staffing.
- Legacy ERP Integration:Device manufacturers acquiring pharmaceutical clients face system harmonization costs when merging batch record workflows with serialized device traceability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug and Gene Delivery Devices Market |
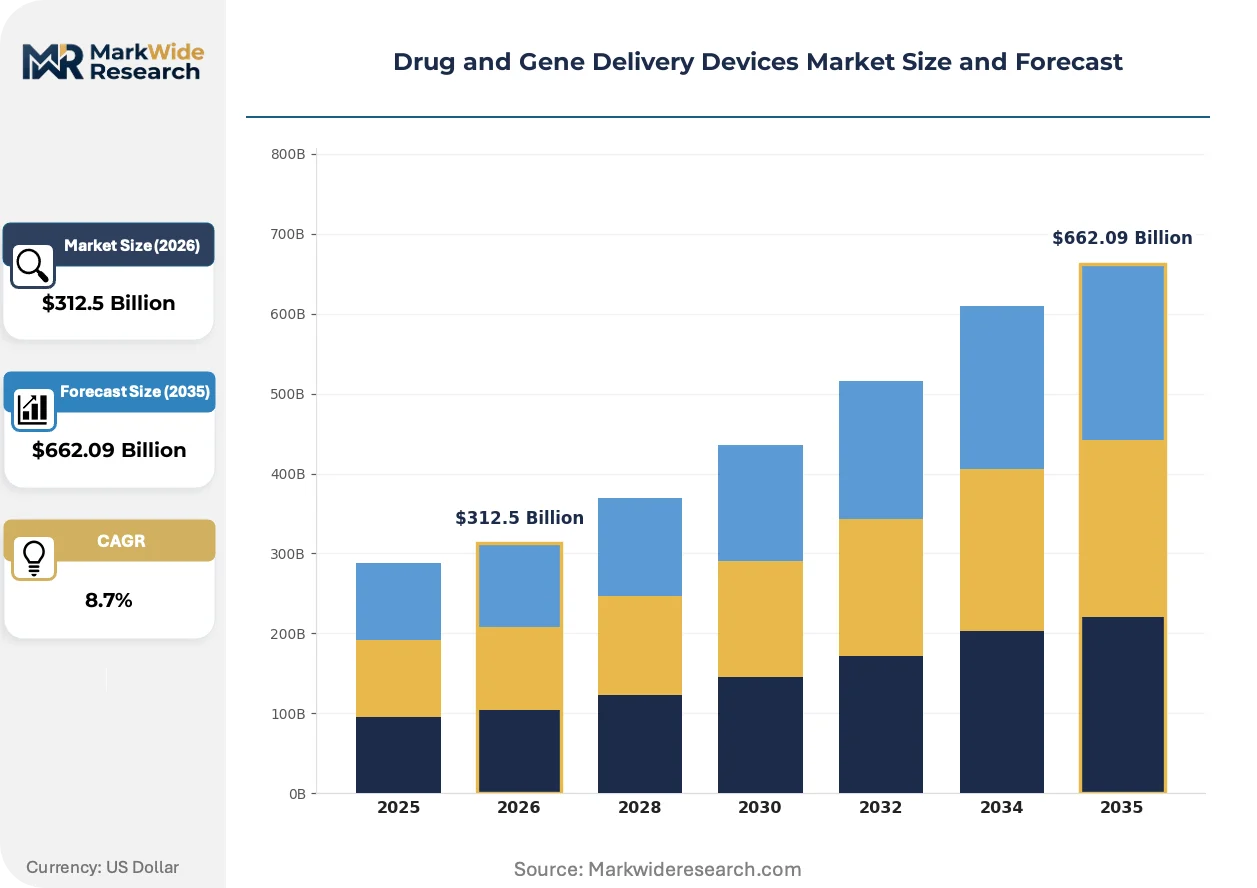
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $662.09 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Injectable Systems, Inhalation Devices, Implantable Pumps, Microneedles Therapy Area: Cancer Treatments, Genetic Disorders, Cardiovascular Conditions, Infectious Diseases End User: Hospitals, Research Laboratories, Homecare Settings, Pharmaceutical Companies Delivery Method: IV Administration, Oral Delivery, Subcutaneous Injection, Topical Application |
| Companies Covered | Merck & Co. Inc., AbbVie Inc., Bayer AG, AstraZeneca plc, Medtronic plc, Amgen Inc., Moderna Inc., Sarepta Therapeutics Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug and Gene Delivery Devices Market Strategic Shifts & Innovations
Digital connectivity and miniaturization are redefining device value propositions, shifting competitive advantage from mechanical precision to data-enabled therapy management and patient adherence verification.
Microneedle technology is decomposing the traditional boundary between transdermal and parenteral delivery routes. Gene therapy developers at academic medical centers are piloting dissolvable arrays for intradermal nucleic acid administration, bypassing cold-chain requirements for viral vector transport. This modality is decomposing the infrastructure barrier that has confined biologics to hospital-based infusion suites.
MDR Article 117 technical documentation requirements are forcing pharmaceutical sponsors to assume direct liability for device components within combination products. The European Medicines Agency's Medical Device Coordination Group has clarified that drug-led submissions must include full device design dossiers, compelling sponsors to either acquire device capabilities or impose stricter supplier audits. High-risk implantable delivery systems for chronic therapies face the steepest compliance cost escalation.
Hospital procurement committees are consolidating supplier relationships to reduce qualification overhead, favoring device vendors with dual drug-device regulatory track records. Integrated biopharma-device developers capture preferred vendor status by offering single-source accountability for combination product failures. This concentration is most pronounced in United States academic medical centers managing CAR-T cell therapy programs.
Drug and Gene Delivery Devices Market Segmentation
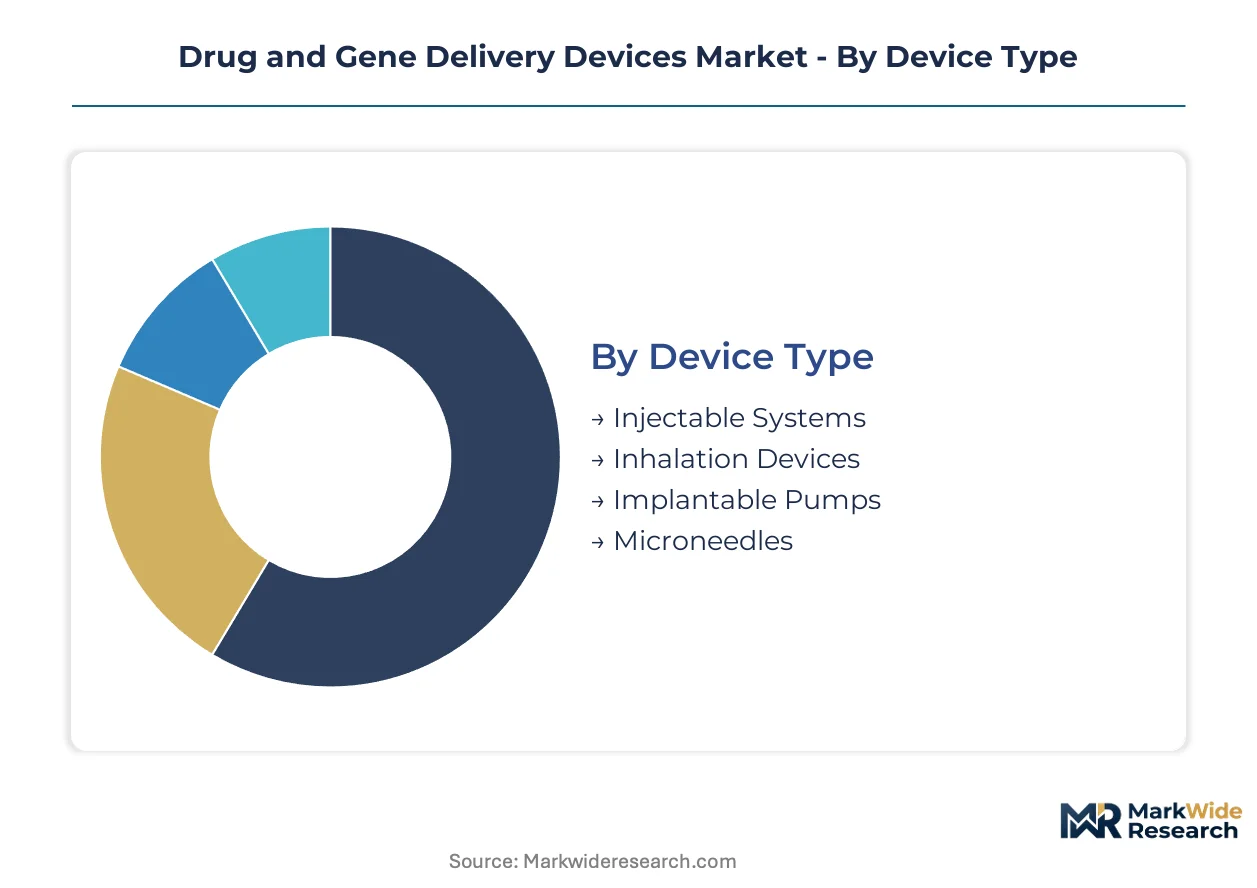
Device categorization in this market tracks reimbursement pathways and manufacturing infrastructure rather than pure technology performance. Segmentation reveals where capital deployment concentrates and which delivery modalities command premium pricing.
Device Type:
Injectable Systems capture the deepest margin pools due to established cold-chain infrastructure and biologics compatibility.
- Injectable Systems:Pre-filled syringes and autoinjectors engineered for biologics administration with precision dosing mechanisms. Demand concentrates in United States hospital networks managing immuno-oncology infusion protocols, driven by Medicare reimbursement codes for outpatient administration.
- Microneedles:Dissolvable or hollow arrays fabricated through microelectromechanical systems processes for transdermal nucleic acid delivery. Adoption accelerates in German academic medical centers piloting intradermal gene therapy bypassing viral vector cold-chain requirements.
- Inhalation Devices:Metered-dose and dry-powder systems for pulmonary biologics deposition.
- Implantable Pumps:Programmable reservoirs for chronic therapy administration in ambulatory patients.
Injectable Systems hold installed capacity. Microneedles is rotating up the share rankings.
Therapy Area:
Volume distribution follows pipeline investment intensity across pharmaceutical portfolios.
- Cancer Treatments:Delivery systems for checkpoint inhibitors, CAR-T cell therapies, and oncolytic viruses requiring specialized handling protocols. United States academic medical centers drive procurement for combination product qualification under FDA accelerated approval pathways.
- Genetic Disorders:Platforms for adeno-associated virus vectors and lipid nanoparticle formulations in neuromuscular and ophthalmic indications. Japanese sites under PMDA Sakigake designation pull early validation work for reimbursement priority review.
- Cardiovascular Conditions:Implantable and catheter-based systems for sustained-release anticoagulants and regenerative agents.
- Infectious Diseases:Vaccine delivery infrastructure including multi-dose vial adapters and needle-free injectors.
Cancer Treatments anchor current procurement budgets. Genetic Disorders is climbing the fastest as gene therapy pipelines mature.
End User:
Customer concentration reflects regulatory liability allocation and qualification overhead tolerance.
- Hospitals:Integrated health systems with in-house pharmacy compounding and infusion center operations. Procurement committees in United States academic medical centers consolidate supplier relationships to reduce combination product qualification burden.
- Pharmaceutical Companies:Sponsors assuming direct device liability under MDR Article 117 for drug-led combination submissions. European manufacturers face steepest compliance cost escalation for high-risk implantable systems.
- Homecare Settings:Self-administration platforms for chronic disease management with connected adherence monitoring.
- Research Laboratories:Investigational device exemptions and preclinical validation systems for academic medical centers.
Hospitals hold established procurement frameworks. Pharmaceutical Companies is gaining share fastest as sponsor liability expands.
Delivery Method:
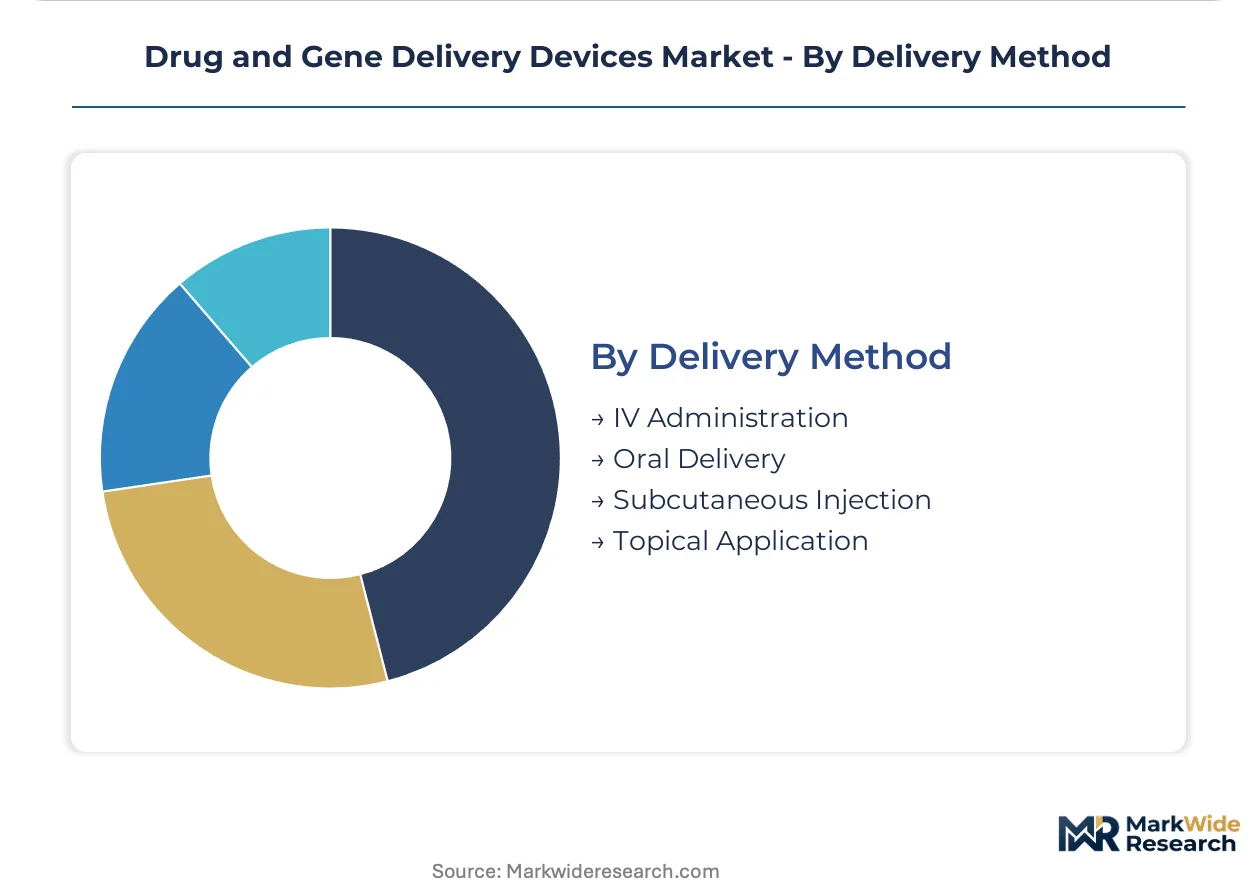
Route selection determines bioavailability targets and manufacturing complexity tiers.
- IV Administration:Infusion pumps, catheters, and closed-system transfer devices for hospital-based biologics delivery. German hospital networks prioritize polymer-based primary containers displacing borosilicate glass for high-value oncology agents.
- Subcutaneous Injection:Autoinjectors and pre-filled syringes enabling ambulatory administration of monoclonal antibodies. Japanese reimbursement infrastructure for advanced therapies accelerates patient transition from infusion suites to home settings.
- Oral Delivery:Enteric coatings and targeted release formulations for small molecules and nucleic acid constructs.
- Topical Application:Transdermal patches and microneedle arrays for localized or systemic absorption.
IV Administration holds clinical infrastructure investment. Subcutaneous Injection is expanding most quickly as self-administration protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in United States academic medical centers demonstrate the lowest price elasticity, absorbing premium device costs under Medicare reimbursement codes, while procurement committees in Indian contract manufacturing organizations operate with acute cost sensitivity as gene therapy work migrates from high-cost geographies.
United States
Hospital networks managing CAR-T cell therapy programs drive demand for combination product qualification under FDA accelerated approval pathways. The FDA's Center for Devices and Radiological Health determines market access through combination product designations. Boston and San Francisco academic medical centers consolidate supplier relationships to reduce qualification overhead for immuno-oncology infusion protocols.
Germany
German hospital networks prioritize polymer-based primary containers displacing borosilicate glass for high-value oncology agents. The EU Medical Device Regulation imposes post-market surveillance obligations through EMA's Medical Device Coordination Group. Heidelberg and Munich academic medical centers pilot intradermal gene therapy using dissolvable microneedle arrays bypassing viral vector cold-chain requirements.
Japan
Japanese reimbursement infrastructure for advanced therapies accelerates patient transition from infusion suites to home-based subcutaneous administration. The PMDA Sakigake designation for regenerative medicines pulls early-stage device validation into Tokyo and Osaka clinical sites. Kansai region manufacturers build assembly capabilities for lipid nanoparticle formulation delivery systems.
India
Contract development and manufacturing organizations in India absorb regulatory risk on behalf of pharmaceutical sponsors seeking cost reduction. The Central Drugs Standard Control Organization governs import licensing for investigational device exemptions. Hyderabad and Bengaluru clusters expand device assembly capabilities to capture gene therapy work migrating from Western geographies.
Switzerland
Swiss biopharmaceutical manufacturers anchor European procurement for high-risk implantable delivery systems facing steepest MDR Article 117 compliance cost escalation. Swissmedic coordinates with EMA on combination product submissions for chronic therapy administration. Basel region specialists concentrate on programmable reservoir technology for ambulatory patients.
Drug and Gene Delivery Devices Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated biopharma-device developers command premium positioning while standalone device suppliers compete on manufacturing scale. The market consolidates around three strategic archetypes: pharmaceutical conglomerates with captive device capabilities, pure-play device technology specialists, and contract manufacturers absorbing regulatory risk for sponsors. Dominant competitive moves include backward integration into polymer feedstock supply and strategic partnerships to bridge combination product expertise gaps.
Within the integrated biopharma tier, Merck & Co. Inc., Medtronic plc, and Sarepta Therapeutics Inc. occupy positions that exemplify contrasting strategic approaches to device-drug convergence. Merck represents pharmaceutical conglomerate scale applied to injectable distribution infrastructure. Medtronic anchors the implantable systems specialization vector through chronic therapy administration platforms. Sarepta exemplifies gene therapy pure-play positioning with concentrated neuromuscular indication focus. These three entities collectively illustrate how competitive advantage in this market derives from regulatory track record depth rather than manufacturing efficiency alone.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| AbbVie Inc. |
| Bayer AG |
| AstraZeneca plc |
| Medtronic plc |
| Amgen Inc. |
| Moderna Inc. |
| Sarepta Therapeutics Inc. |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
Twelve-to-eighteen-month ISO 13485 audit backlogs concentrate pricing power among established device suppliers with pre-certified quality systems, while contract manufacturers absorb regulatory risk to defend margin positions in gene therapy procurement. This lead-time asymmetry separates premium-tier integrated biopharma-device developers from standalone suppliers competing on manufacturing scale.
Pricing Analysis
After-sales service contracts and extended validation support drive lifetime value differentiation in high-risk implantable delivery systems. Device vendors bundle regulatory consulting with hardware sales to pharmaceutical sponsors facing MDR Article 117 compliance escalation. Pricing stratifies across premium, standard, and economy tiers based on combination product track record depth and geographic regulatory coverage. Cost compression in polymer-based primary containers intensifies as German and Japanese chemical suppliers exercise feedstock pricing power. Indian contract manufacturing organizations demonstrate acute price sensitivity as gene therapy assembly work migrates from Western geographies.
Supply Chain Analysis
Japan and Germany anchor cyclic olefin polymer supply for primary packaging, while India and Switzerland build assembly capabilities for high-value biologics delivery systems. Device manufacturing draws from silicon wafer fabrication for microneedle arrays, borosilicate glass for legacy syringe formats, and specialized polymers for cold-chain compatibility. Single-source vulnerability concentrates in Japanese chemical suppliers controlling cyclic olefin copolymer feedstock. Distribution runs through hospital procurement committees consolidating supplier relationships to reduce qualification overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from digital therapeutics and software-based adherence monitoring platforms that bypass hardware delivery entirely. This threat compresses the addressable market for traditional mechanical devices.
For Market Incumbents: Shield installed base relationships by acquiring polymer feedstock supply chain control and embedding predictive maintenance algorithms into implantable pump platforms. The combination product expertise gap constrains staffing for new program launches, making backward integration into regulatory consulting capabilities essential for margin defense.
For New Entrants and Emerging Players: Anchor in microneedle technology for transdermal nucleic acid delivery, where clinical validation requirements remain lower than implantable systems. German academic medical centers piloting intradermal gene therapy bypassing cold-chain requirements represent the most penetrable entry point. Partner with lipid nanoparticle formulation specialists to offer integrated device-drug positioning.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because reimbursement infrastructure maturation in Japan and the United States creates durable competitive moats around approved delivery systems. Target acquisition profiles emphasize device technology specialists with FDA breakthrough device designation track records. The signal to watch is EMA adaptive pathway approval velocity for gene therapies requiring companion delivery platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Article 117 Compliance Investment | Pharmaceutical sponsors assume direct device liability under EMA Medical Device Coordination Group clarifications. |
| Sakigake Designation Alignment | Japanese PMDA priority review pulls early-stage device validation into Tokyo and Osaka clinical sites. |
| Microneedle Fabrication Scale-Up | Microelectromechanical systems manufacturing enables dissolvable arrays for transdermal nucleic acid delivery. |
| Polymer Feedstock Backward Integration | Cyclic olefin polymer supply concentration among Japanese and German suppliers drives input cost volatility. |
| Hospital System Partnership Consolidation | United States academic medical centers reduce qualification burden through single-source supplier relationships. |
Research Approach
A spread of perspectives from regulatory affairs leads, hospital procurement managers, biomedical engineers, and GPO contracts managers converged on the working assumptions driving this analysis. Primary interviews with device manufacturers and pharmaceutical sponsors combined with secondary validation against FDA 510(k) filings, EMA combination product submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include device type, therapy area, end user, delivery method, and regional regulatory cluster. CAGRs were derived from volume and value trajectory analysis across the projection horizon. Forecast inputs incorporated pipeline maturity assessments for gene therapy candidates, reimbursement code expansion timelines for advanced therapies, and notified body capacity constraints under EU Medical Device Regulation.
Underlying assumptions cover sustained FDA accelerated approval pathway utilization and EMA adaptive licensing framework stability, with deviation risk concentrated in polymer feedstock supply disruptions and ISO 13485 audit timeline extensions. Recalibration cycles align with material shifts in combination product regulatory convergence and gene therapy reimbursement decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Meniscal Rasps Market
Medical Devices
Global Endotracheal Tubes Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Heat Therapy Units Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Global Microcatheter Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
US Clear Aligners Market